
 Shock Absorber Market | 2026-2036
Shock Absorber Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Absorber Market Intelligence
Fleet operator procurement concentration is hardening across North American and European commercial vehicle segments. ZF Friedrichshafen leverages its integrated chassis systems portfolio to capture long-term supply agreements with heavy-duty truck manufacturers. KYB Corporation anchors its position through dominant share in Asian OEM supply chains, while Tenneco Inc. competes aggressively in the North American aftermarket channel through extensive distribution partnerships.
A shock absorber is a mechanical or hydraulic device designed to absorb and damp shock impulses by converting kinetic energy into thermal energy, typically operating within a pressure range of 10-30 bar and utilizing hydraulic fluid viscosity between 5-15 cSt at operating temperature. Its primary industrial purpose is to control unwanted spring oscillation in vehicles and machinery, ensuring tire contact stability, occupant comfort, and structural load management. Mono-tube designs lead in premium automotive applications due to superior heat dissipation and fade resistance, while twin-tube configurations dominate mass-market OEM supply because of lower manufacturing complexity and cost base. Electric and magnetic technologies represent the fastest-expanding technology segment as adaptive damping systems penetrate mid-range vehicle platforms.
NHTSA Federal Motor Vehicle Safety Standards, EPA fuel economy regulations, and ECE R14 braking and stability directives collectively shape shock absorber performance requirements and testing protocols across major automotive markets. Compliance with these frameworks drives R&D investment toward lightweight materials, integrated sensor architectures, and predictive damping algorithms. Stakeholders must monitor how electrification shifts unsprung mass calculations and whether adaptive suspension becomes mandatory for autonomous vehicle safety certification.
Market Dynamics
Electrification is fundamentally recalibrating shock absorber engineering specifications as battery-electric platforms alter unsprung mass distributions and ride control algorithms. Commercial vehicle operators now demand adaptive damping systems capable of real-time load compensation across variable terrain conditions.
Growth Catalysts
- Euro 7 Emissions Standards:Stringent efficiency mandates are accelerating lightweight hydraulic fluid formulations and reduced-friction seal technologies across European OEM supply chains.
- Adaptive Damping Algorithms:Machine learning-enabled suspension control is penetrating mid-range passenger vehicle platforms, expanding addressable market for sensor-integrated shock absorber modules.
- Stuttgart Engineering Corridor:Concentrated R&D investment by German automotive OEMs and tier-one suppliers is establishing technical benchmarks for predictive ride control systems.
Market Restraints
- Specialized Steel Alloy Costs:High-grade chromium-molybdenum tubing for mono-tube designs faces price volatility tied to mining supply concentration in South Africa and Kazakhstan.
- Technical Limitation of Thermal Management:Twin-tube configurations exhibit fade susceptibility under sustained high-frequency oscillation, constraining deployment in heavy-duty off-highway machinery.
- Substitution Threat from Air Suspension:Pneumatic damping systems are capturing share in premium commercial vehicle segments where ride height adjustability commands procurement priority.
Strategic Opportunities
- Autonomous Vehicle Safety Certification:NHTSA is evaluating mandatory stability control requirements that would elevate adaptive suspension from premium option to baseline specification.
- India Commercial Vehicle Modernization:Bharat Stage VI Phase II implementation is creating demand for advanced damping systems capable of maintaining tire contact stability across deteriorated road infrastructure.
- Remanufacturing Channel Development:Circular economy frameworks under EU Green Deal are incentivizing shock absorber refurbishment programs for fleet operators seeking total cost reduction.
Industry Challenges
- Electrohydraulic Integration Complexity:Combining sensor architectures with legacy mechanical damping cores requires cross-functional engineering teams fluent in both disciplines.
- Homologation Timeline Compression:Accelerated vehicle platform development cycles are compressing durability testing protocols from 18 months to 12 months without compromising ECE R14 compliance validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Absorber Market |
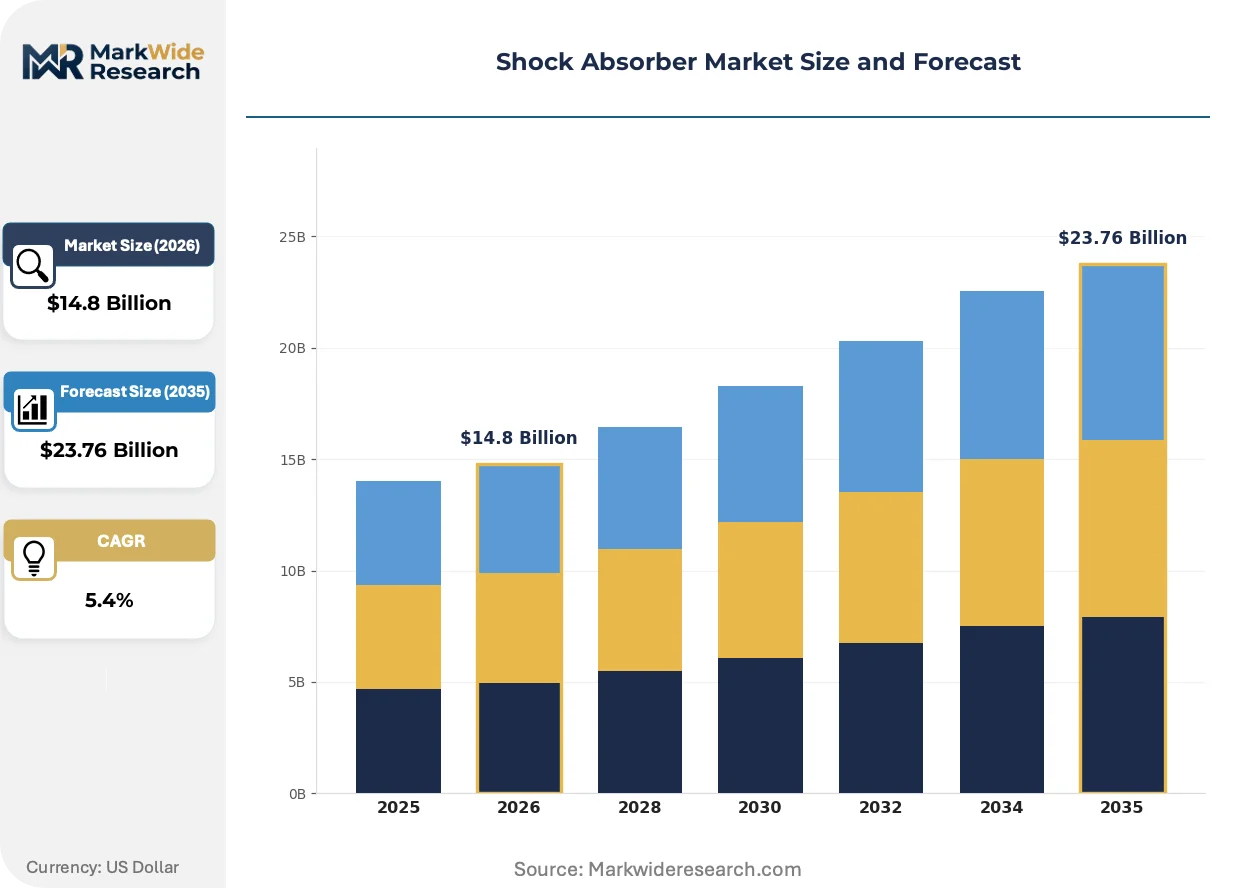
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twin-Tube, Mono-Tube, Air Shock, Gas Shock Application: Automotive, Industrial Equipment, Motorcycles, Bicycles End User: OEMs, Aftermarket, Fleet Operators, Casual Users Technology: Hydraulic, Pneumatic, Electric, Magnetic |
| Companies Covered | Hitachi Astemo Ltd., Showa Corporation, KYB Corporation, Gabriel India Ltd., Thyssenkrupp Bilstein, ZF Friedrichshafen, Mando Corporation, Bilstein Group, Tenneco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Absorber Market Strategic Shifts & Innovations
Active suspension architectures are displacing passive systems across vehicle categories, with sensor fusion and real-time damping adjustment becoming baseline expectations rather than premium differentiators.
Magnetorheological fluid technology is consolidating control authority within single damper units by enabling millisecond-scale viscosity modulation through electromagnetic field manipulation. Heavy-duty truck manufacturers in North America are adopting these systems for cab suspension isolation, reducing driver fatigue claims and warranty exposure. The technology is consolidating supplier value chains by integrating sensor, actuator, and control module functions that previously required separate sourcing relationships.
EPA Tier 3 fuel economy regulations are mandating weight reduction across powertrain and chassis components, directly influencing hollow piston rod designs and aluminum body construction in next-generation shock absorbers. Manufacturers must now validate corrosion resistance under extended salt spray protocols while maintaining structural integrity at reduced material thickness. Commercial vehicle platforms serving California ports face additional CARB compliance layers that accelerate adoption of these lightweight specifications.
Fleet operators are consolidating maintenance spend through integrated chassis service contracts that bundle shock absorber replacement with brake and steering system overhaul. This procurement compression is displacing independent aftermarket distributors who historically captured individual component replacement cycles. The pattern is most pronounced among North American Class 8 truck operators managing assets across dedicated route networks where uptime guarantees override unit-level sourcing flexibility.
Shock Absorber Market Segmentation
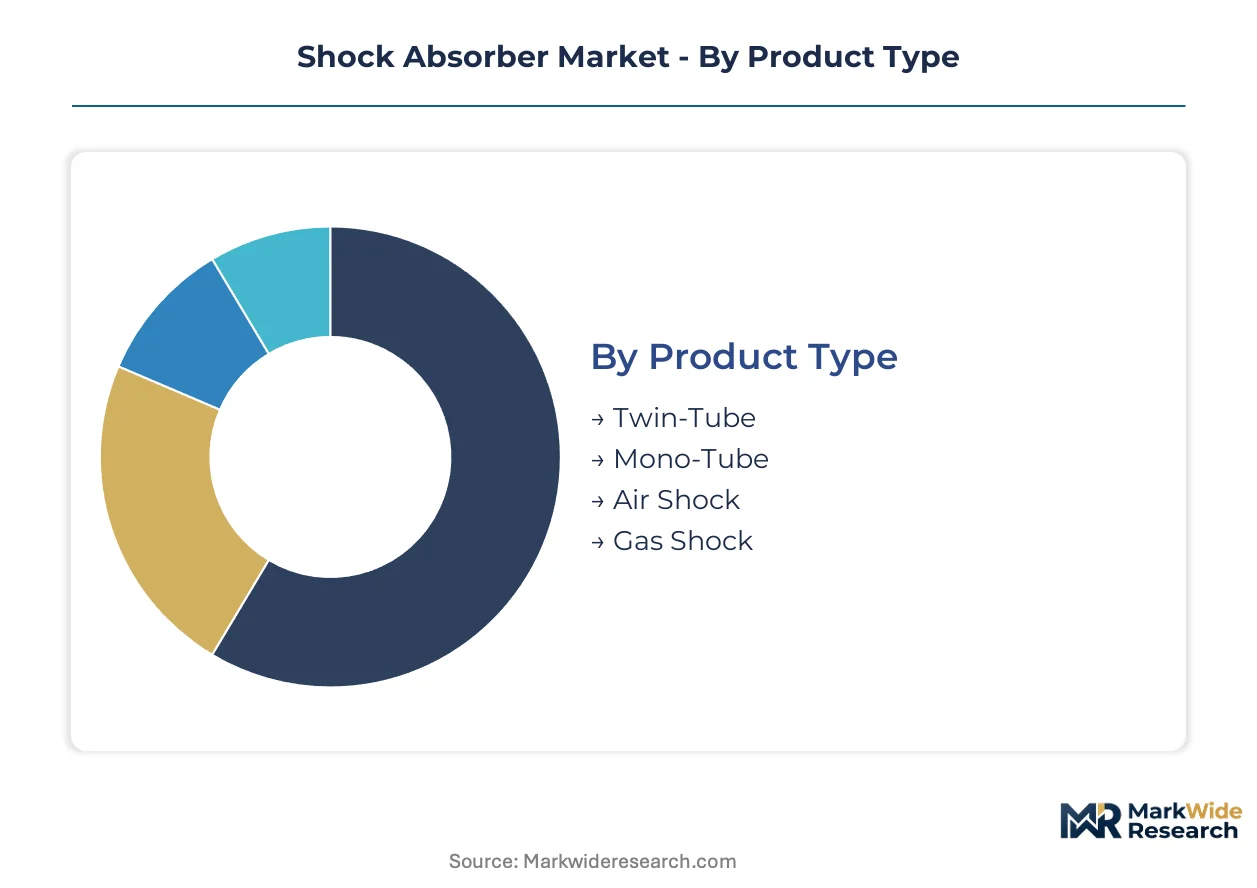
Shock absorber market segmentation reveals how engineering specifications, procurement channels, and technology platforms fragment commercial opportunity. Each axis carries distinct margin profiles and competitive dynamics that suppliers must navigate.
Product Type:
Structural design choices determine thermal performance, manufacturing cost, and platform compatibility across vehicle categories.
- Twin-Tube:Concentric cylinder architecture with inner working tube and outer reserve tube separates compression and rebound valving. Mass-market automotive OEMs in Germany favor this configuration for its 15-20% cost advantage over mono-tube alternatives in high-volume production.
- Mono-Tube:Single high-pressure cylinder with floating piston separating gas and oil chambers delivers superior fade resistance through enhanced heat dissipation. Premium passenger vehicle platforms and motorsport applications specify this design despite chromium-molybdenum tubing cost exposure.
- Air Shock:Pneumatic spring-damper integration enables ride height adjustability for commercial vehicle cab suspension and luxury SUV applications.
- Gas Shock:Nitrogen-charged single or twin-tube designs reduce cavitation and improve response consistency in heavy-duty off-highway machinery.
Twin-tube leads on scale; mono-tube leads on momentum.
Application:
End-use diversification creates divergent durability requirements and replacement cycle economics.
- Automotive:Passenger cars, light trucks, and commercial vehicles generate the largest procurement volumes, with electrified platforms demanding recalibrated damping algorithms for altered unsprung mass distributions.
- Industrial Equipment:Construction machinery, agricultural implements, and material handling equipment specify high-displacement dampers with reinforced seals for contaminated operating environments.
- Motorcycles:Inverted cartridge forks and rear mono-shocks prioritize weight reduction and adjustability for performance and touring segments.
- Bicycles:Mountain bike suspension forks and rear shocks represent a specialized niche with rapid technology turnover and direct-to-consumer distribution.
Automotive commands volume concentration; industrial equipment offers the steepest expansion trajectory as infrastructure investment accelerates.
End User:
Procurement authority and total cost calculation methods vary sharply across customer types.
- OEMs:Vehicle manufacturers negotiate multi-year supply agreements with tier-one suppliers, integrating shock absorbers into complete chassis system modules. ZF Friedrichshafen and KYB Corporation anchor this channel through engineering co-development contracts.
- Aftermarket:Independent distributors and service chains capture replacement demand from aging vehicle populations, with Tenneco Inc. leveraging broad retail partnerships across North America.
- Fleet Operators:Commercial vehicle asset managers consolidate maintenance spend through integrated service contracts bundling suspension, brake, and steering system overhaul.
- Casual Users:Individual consumers purchasing for personal motorcycles, bicycles, or light vehicle upgrades drive fragmented retail demand with high price sensitivity.
OEMs dominate value capture; fleet operators are concentrating procurement fastest through contract consolidation.
Technology:
Actuation mechanisms define the boundary between passive damping and adaptive ride control.
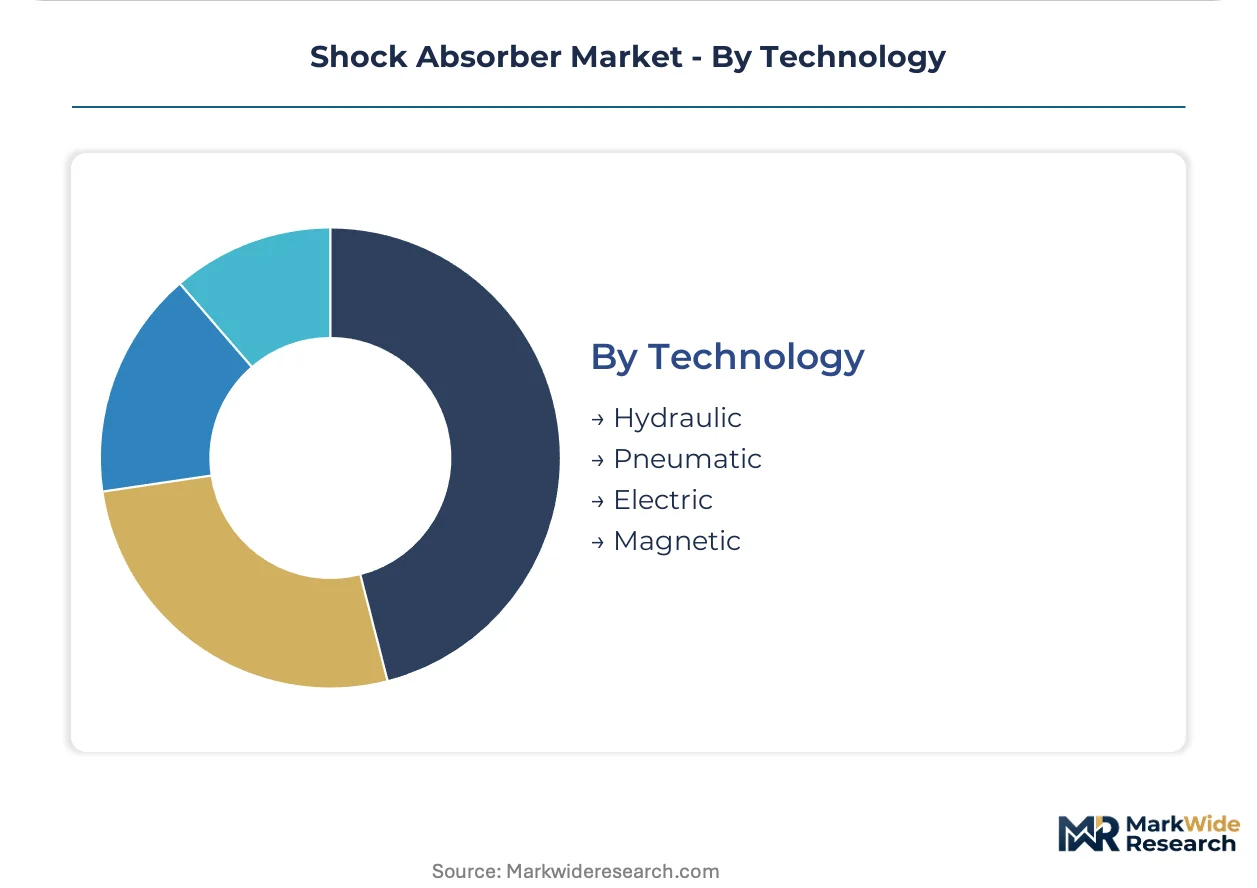
- Hydraulic:Conventional oil-based damping with fixed or manually adjustable valving remains the cost baseline for mass-market applications.
- Pneumatic:Air suspension systems integrate damping and spring functions, gaining share in premium commercial vehicles where ride height flexibility commands procurement priority.
- Electric:Motor-driven variable valves enable real-time damping adjustment based on sensor inputs, penetrating mid-range passenger platforms as sensor costs decline.
- Magnetic:Magnetorheological fluid systems modulate viscosity through electromagnetic fields in milliseconds, consolidating sensor, actuator, and control functions within single damper units for heavy-duty truck cab isolation.
Hydraulic retains volume dominance; magnetic systems are climbing the fastest as adaptive suspension becomes baseline expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands engineering-intensive supply relationships, while China scales manufacturing throughput for cost-sensitive platforms. India and the United States concentrate fleet procurement modernization, with Japan anchoring precision component exports.
Germany
Commercial vehicle OEMs in Stuttgart and Munich corridors specify predictive damping algorithms for electrified platforms. KBA enforces stringent durability validation under ECE R14 braking stability directives. Baden-Württemberg's tier-one supplier cluster advances integrated chassis module development for adaptive suspension systems.
China
Domestic EV manufacturers demand recalibrated shock absorbers for battery-heavy unsprung mass distributions. MIIT mandates lightweight chassis components under dual carbon reduction targets. The Yangtze River Delta manufacturing belt concentrates hollow piston rod fabrication for export-bound automotive supply chains.
United States
Class 8 truck fleet operators consolidate maintenance spend through integrated chassis service contracts. NHTSA evaluates mandatory stability control requirements that would elevate adaptive suspension specifications. Michigan's automotive engineering corridor hosts durability testing facilities compressing homologation timelines.
India
Bharat Stage VI Phase II implementation drives commercial vehicle damping system upgrades for degraded road infrastructure. BIS certification protocols align shock absorber testing with international durability standards. Tamil Nadu's automotive component belt attracts foreign supplier joint ventures serving domestic OEM assembly plants.
Japan
Precision mono-tube designs dominate motorsport and premium passenger vehicle exports. METI coordinates domestic supplier R&D consortia for magnetorheological fluid commercialization. Kanto region engineering clusters integrate sensor architectures with legacy mechanical damping cores.
Shock Absorber Market Key Industry Players
German producers anchor the premium chassis systems tier; Japanese specialists hold precision component supply relationships. The market structures around three strategic archetypes: integrated chassis module suppliers, precision damping component specialists, and aftermarket distribution consolidators. Capacity expansion and sensor-technology licensing represent the dominant competitive moves as electrification recalibrates engineering specifications.
Within the integrated chassis module tier, ZF Friedrichshafen and Tenneco Inc. exemplify divergent geographic positioning strategies. KYB Corporation occupies a distinct position among precision component specialists serving Asian OEM supply chains. These three anchors demonstrate how supplier archetypes map to distinct procurement channel concentrations without overlapping strategic territory.
| Leading Market Players |
|---|
| Hitachi Astemo Ltd. |
| Showa Corporation |
| KYB Corporation |
| Gabriel India Ltd. |
| Thyssenkrupp Bilstein |
| ZF Friedrichshafen |
| Mando Corporation |
| Bilstein Group |
| Tenneco Inc. |
| Others |
Cost & Logistics Intelligence
Euro 7 emissions compliance gates qualified supply for premium-tier shock absorber procurement, as lightweight hydraulic fluid formulations and reduced-friction seal technologies require certified manufacturing lines that OEMs will pay 15-20% premiums to access. Fleet operators consolidating maintenance spend through integrated chassis contracts further compress aftermarket price floors, forcing tier-two suppliers toward economy-tier positioning or exit.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard twin-tube configurations, pressuring legacy European suppliers to defend premium positioning through mono-tube thermal performance guarantees. Three-tier pricing structure across premium adaptive systems, standard OEM-specified dampers, and economy aftermarket replacements stratifies by certification grade and sensor integration depth. Cost compression in the economy tier is intensifying because hollow piston rod fabrication scales in the Yangtze River Delta manufacturing belt. Fleet operators exhibit lowest price sensitivity due to uptime guarantee requirements, while independent aftermarket distributors face margin collapse from procurement consolidation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Japanese automotive manufacturers, while aftermarket distribution runs through consolidated service chains capturing fleet maintenance contracts. Manufacturing concentrates in Germany, China, and Japan, with precision mono-tube fabrication anchored in Baden-Württemberg and Kanto region engineering clusters. Raw material supply draws from chromium-molybdenum tubing mills in South Africa and Kazakhstan, hydraulic fluid specialty chemical producers in Belgium and the United States, and nitrogen charging gas suppliers. Single-source vulnerability in high-grade alloy tubing exposes mono-tube producers to mining concentration risk. Distribution downstream centers on tier-one supplier integration with OEM platform engineering teams and fleet operator direct contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shock absorber market functions as a stable compounder, with electrification-driven recalibration of unsprung mass algorithms ensuring sustained R&D investment across replacement cycles.
For Market Incumbents: Hedge against air suspension substitution in premium commercial vehicle segments by deepening backward integration into sensor architecture development and securing long-term chromium-molybdenum supply agreements with South African mining consortiums. ZF Friedrichshafen and KYB Corporation demonstrate how engineering co-development contracts with OEM platform teams lock out adaptive damping competitors. Certification investment under ECE R14 braking stability directives remains the critical defensive moat. For New Entrants and Emerging Players: The 25-30% price-point gap between magnetorheological premium systems and standard hydraulic dampers creates white-space opportunity for electric variable-valve technologies penetrating mid-range passenger platforms. India commercial vehicle modernization under Bharat Stage VI Phase II offers the most penetrable geography, with Tamil Nadu's component belt providing manufacturing infrastructure for foreign joint ventures. Target fleet operator direct contracting with predictive maintenance software bundling as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for precision damping component specialists because OEM platform standardization is consolidating supplier relationships toward single-source adaptive system integrators. Five-to-ten-year viability favors manufacturers with captive sensor technology and hollow piston rod fabrication capabilities. The signal to watch is NHTSA mandatory stability control rulemaking, which would elevate adaptive suspension from premium option to baseline specification and trigger replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Architecture Integration | Combines damping cores with predictive algorithms for OEM platform co-development contracts. |
| Lightweight Material Transition | Hollow piston rod and aluminum body designs satisfy EPA Tier 3 weight reduction mandates. |
| Remanufacturing Channel Buildout | EU Green Deal circular economy frameworks incentivize shock absorber refurbishment programs. |
| Magnetorheological Fluid Commercialization | Millisecond-scale viscosity modulation consolidates sensor, actuator, and control functions. |
| Fleet Service Contract Consolidation | Integrated chassis maintenance bundling captures Class 8 truck operator procurement concentration. |
Research Approach
Bottom-up vehicle production modeling reconciled against top-down tier-one supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-one procurement directors, fleet maintenance managers, aftermarket distribution heads, and suspension system R&D leads informed demand-side validation. Secondary sources include vehicle registration databases, IHS Markit production forecasts, SEC 10-K filings from listed automotive suppliers, ECE R14 compliance documentation, and trade flow data from customs authorities. Cross-referencing bottom-up segment builds with top-down supplier revenue allocations ensures triangulation integrity.
Input-output matrices map shock absorber content per vehicle across propulsion architecture, vehicle class, OEM tier positioning, and regional production cluster dimensions. CAGRs derive from regression analysis of historical production volumes against technology penetration curves for adaptive damping systems. Industry-specific forecast inputs include electrification-driven unsprung mass recalibration coefficients and fleet operator contract consolidation velocity indices across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for solid-state electromechanical damping would alter the outlook if magnetic fluid systems face thermal management constraints under sustained high-frequency oscillation. Forecasts reflect base-case assumptions regarding regulatory timeline adherence and OEM platform development cycle compression. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Filter Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
South America Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Hub Motor Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Motorcycle Cooling Helmets Market
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
Cargo Bicycles Market
Bikes and Motorcycles
Motorcycle Headlight Bracket Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
US Fuel Cell Bikes Market