
 Ride on Bikes Market | 2026-2036
Ride on Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Ride on Bikes Market Analytics
Mid-drive motor integration with torque-sensing pedal assist is tilting production priorities toward precision-engineered powertrains over hub-motor architectures. Trek leverages its vertically integrated Project One custom manufacturing platform to sustain premium positioning in road and mountain categories. Rad Power Bikes anchors the direct-to-consumer channel with simplified assembly and price-accessible electric utility frames. Specialized dominates performance road segments through proprietary Future Shock suspension and aerodynamic tube shaping.
Ride on bikes encompass human-powered and electric-assisted two-wheel vehicles designed for recreational, competitive, and utilitarian transport, typically featuring aluminum alloy or carbon fiber frames with wheel diameters ranging from 20 to 29 inches and power outputs up to 750 watts for electric variants. Their primary commercial purpose spans personal mobility, physical fitness, and last-mile logistics integration. Electric bikes command the fastest-expanding margin pool as lithium-ion cell costs decline and urban congestion intensifies, while mountain bikes retain durable aftermarket service revenue through suspension rebuild cycles and tire replacement. The commuter customer segment is concentrating demand around integrated lighting, fender compatibility, and rack-ready frame geometries that support daily utility use.
US CPSC safety standards and FDA oversight of fitness-tracking accessories shape product liability exposure and data handling requirements for connected electric models. EU REACH substance restrictions and CE marking obligations govern frame coatings, battery enclosures, and electrical component sourcing across member state import channels. China's GB standards and MIIT manufacturing directives influence OEM supplier qualification for brands with Asian assembly footprints. Stakeholders must monitor evolving battery recycling mandates and emerging e-bike classification thresholds that determine motor power limits, path access rights, and insurance liability across municipal jurisdictions.
Market Dynamics
Mid-drive motor torque-sensing systems are compressing hub-motor architectures as precision powertrains capture premium commuter and mountain bike segments. This technological pivot is redistributing manufacturing investment toward compact, high-torque drivetrain engineering.
Growth Catalysts
- EU F-Gas Regulation:Battery thermal management requirements are accelerating adoption of advanced lithium-ion cell chemistries with improved thermal stability profiles.
- Urban congestion pricing:Municipal congestion zones in London, Milan, and Singapore are channeling last-mile commuters toward electric bike alternatives.
- Carbon fiber layup automation:Robotic fiber placement is reducing frame production cycle times and enabling complex aerodynamic tube geometries at scale.
Market Restraints
- Lithium carbonate volatility:Cell raw material cost swings compress margin predictability for electric bike assemblers dependent on Chinese cathode supply.
- REACH substance restrictions:Frame coating reformulation timelines extend product certification cycles for EU-bound shipments.
- Mechanical derailleur durability:Traditional chain-drive systems face substitution pressure from belt-drive and hub-gear alternatives in high-mileage fleet applications.
Strategic Opportunities
- Indian urban corridors:Metro rail integration gaps in Bangalore, Pune, and Hyderabad create white space for dockless electric bike sharing.
- EU Green Deal subsidies:National purchase incentive programs in France, Italy, and Spain are expanding addressable demand for mid-tier electric commuters.
- Battery-as-a-service models:Subscription-based cell leasing separates hardware ownership from energy access, lowering upfront purchase barriers.
Industry Challenges
- Power electronics integration:Motor controller firmware development requires scarce embedded systems talent competing with automotive and robotics sectors.
- CE marking documentation:Technical file assembly for mechanical safety and electromagnetic compatibility extends time-to-market for new frame platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ride on Bikes Market |
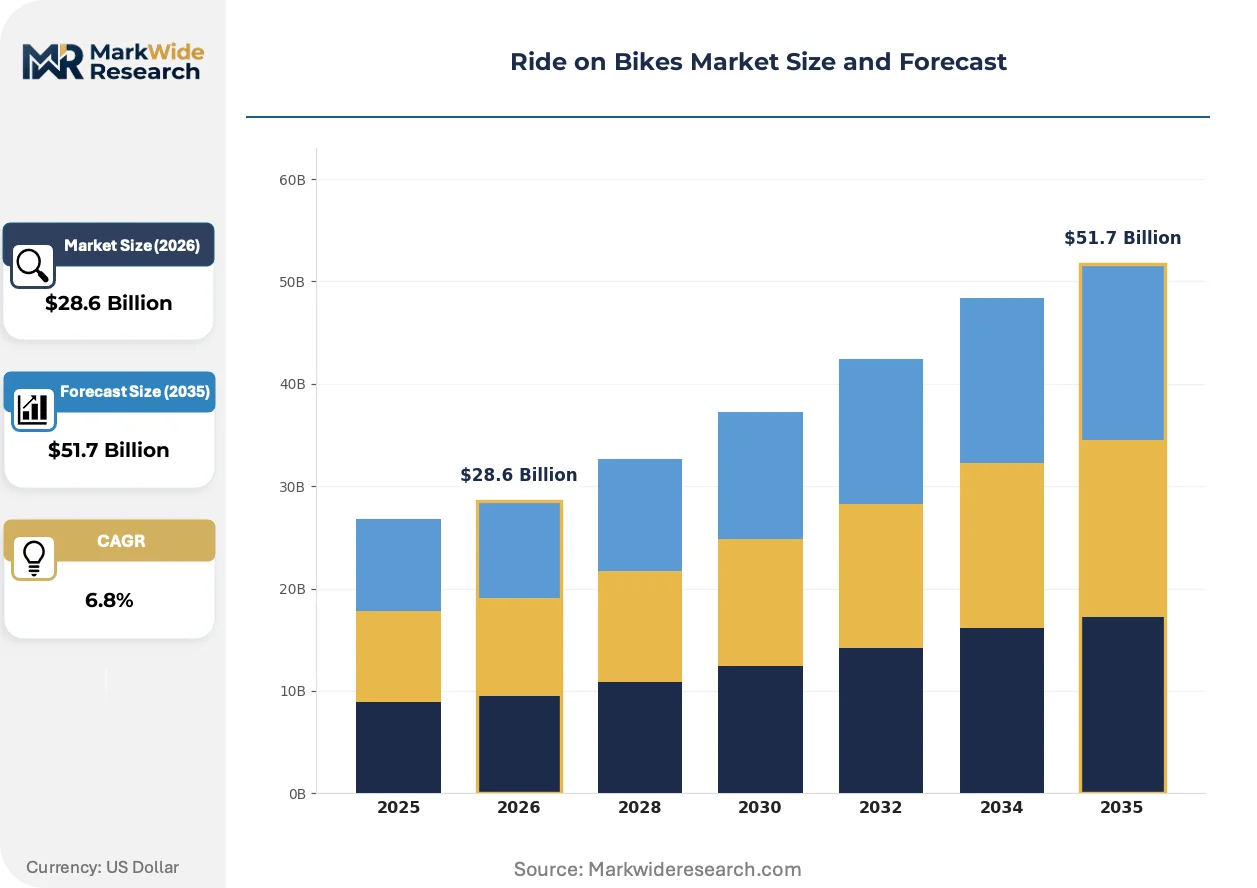
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Bikes, Mountain Bikes, Road Bikes, Hybrid Bikes Customer Type: Children, Adults, Fitness Enthusiasts, Commuters Usage Purpose: Recreational, Competitive, Commuting, Fitness Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Trek, Himiway, Rad Power Bikes, Velotric, Surron, Aventon, Specialized, Hovsco, Giant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ride on Bikes Market Evolving Landscape
Torque-sensing pedal assist algorithms, battery thermal management advances, and direct-to-consumer assembly simplification are restructuring competitive advantage in ride on bikes. These forces are compressing traditional channel hierarchies and elevating software-defined performance differentiation.
Mid-drive motor systems with integrated torque and cadence sensing are collapsing the performance gap between hub-motor economy models and premium human-bike interfaces. Urban commuters in German and Dutch cities are adopting these systems at accelerated replacement cycles. The technology is collapsing price-band segmentation as single-platform motor architectures span entry through performance tiers.
EU REACH substance restrictions on frame coatings and battery enclosure materials are forcing reformulation of supply chains serving member state markets. Manufacturers must document substance volumes and secure SCIP database entries for complex products. Electric cargo bikes with extended battery capacities face the most intensive compliance burden and are responding with modular, separable cell architectures.
Fleet procurement for last-mile logistics is consolidating demand around standardized service intervals and interchangeable component ecosystems. Delivery operators in Paris and Berlin are displacing traditional dealer networks with direct maintenance contracts and mobile service units. This pattern is most visible in commercial electric bike deployments where uptime guarantees override brand loyalty in vendor selection.
Ride on Bikes Market Segmentation
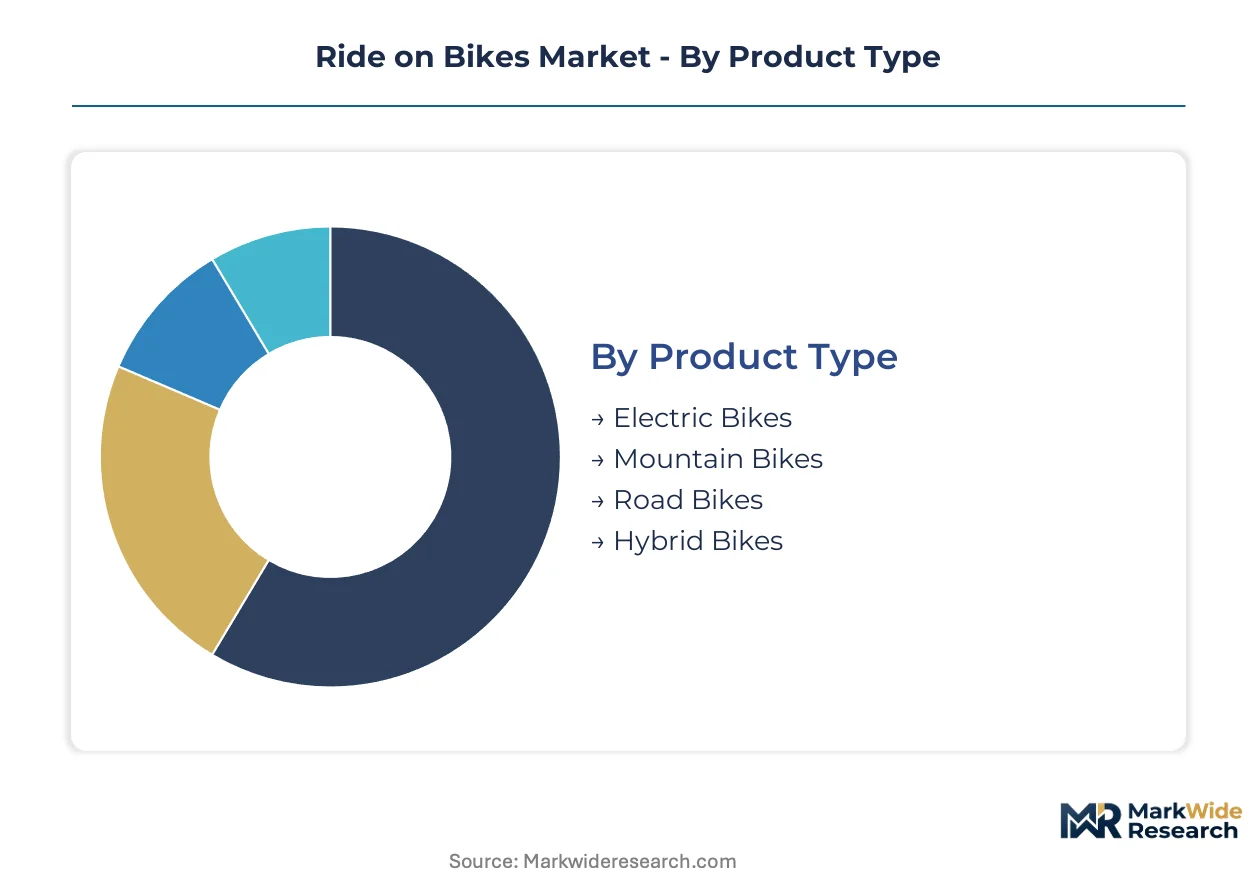
Ride on bikes serve divergent mobility needs across recreation, sport, and urban logistics. Segment boundaries blur as electric powertrains penetrate traditional categories and fleet procurement reshapes channel economics.
Product Type:
Use cases span last-mile cargo hauling, trail recreation, aerodynamic racing, and multi-terrain versatility.
- Electric Bikes:Lithium-ion powered frames with 250-750 watt motors and torque-sensing pedal assist dominate urban corridors in Germany and the Netherlands. Battery thermal management requirements under EU F-Gas Regulation are elevating cell chemistry standards for premium commuter models.
- Mountain Bikes:Full-suspension and hardtail configurations with 27.5 or 29-inch wheels target trail systems in Colorado, British Columbia, and the Alps. Aftermarket service revenue from suspension rebuilds and tire replacement sustains dealer profitability.
- Road Bikes:Carbon fiber or aluminum frames with drop handlebars emphasize aerodynamic tube shaping and low overall weight for competitive and fitness applications.
- Hybrid Bikes:Flat-bar geometries with moderate tire width balance paved-path efficiency with light off-road capability for casual recreational riders.
The dominant share belongs to Electric Bikes, while Mountain Bikes is closing the gap fastest through premium suspension technology upgrades.
Customer Type:
Demographic targeting reflects divergent price sensitivity, performance demands, and replacement cycle patterns.
- Adults:The core revenue base spans utility commuters seeking rack-ready frame geometries and integrated lighting through performance enthusiasts demanding carbon fiber layup precision. German purchase subsidy programs and Dutch cycling infrastructure investments concentrate demand in these geographies.
- Commuters:Daily urban riders prioritize fender compatibility, chaincase protection, and upright riding positions for high-mileage reliability in congestion-priced zones like London and Milan.
- Fitness Enthusiasts:Training-focused cyclists invest in power meter integration, aerodynamic positioning, and connected health data synchronization.
- Children:Sized-down frames with coaster or hand brakes address safety-conscious parental procurement through specialty retail channels.
Adults commands volume leadership, though Commuters is expanding most quickly as municipal congestion pricing spreads across European capitals.
Usage Purpose:
Activity-based segmentation determines component specification, durability requirements, and service attachment rates.
- Commuting:Daily transport applications demand puncture-resistant tires, enclosed drivetrains, and theft-resistant locking systems for unsupervised urban parking. Fleet operators in Paris and Berlin are displacing individual ownership with subscription-based electric bike deployments.
- Recreational:Weekend and leisure riding emphasizes comfort saddles, suspension forks, and step-through frame access for casual user demographics.
- Competitive:Racing disciplines require UCI-compliant frame geometries, electronic shifting, and power-to-weight optimization for sanctioned events.
- Fitness:Health-motivated cycling integrates heart rate monitoring, structured training platforms, and ergonomic fit optimization through professional bike fitting services.
Commuting generates the highest unit economics through fleet procurement, while Recreational maintains the broadest geographic penetration.
Distribution Channel:
Channel selection shapes margin capture, assembly complexity, and ongoing service relationships.
- Specialty Stores:Independent dealers provide professional fitting, maintenance contracts, and warranty administration for mid-to-premium segments. German KBA safety inspections and CE marking documentation requirements reinforce dealer technical competence.
- Online Retail:Direct-to-consumer platforms reduce price points through simplified final assembly by end users. Rad Power Bikes anchors this channel with modular packaging and video-guided setup protocols.
- Direct Sales:Manufacturer-owned showrooms and mobile service units capture full margin for vertically integrated brands with captive assembly capacity.
- Supermarkets:Mass retail placement targets price-sensitive entry segments with limited service attachment and seasonal inventory cycles.
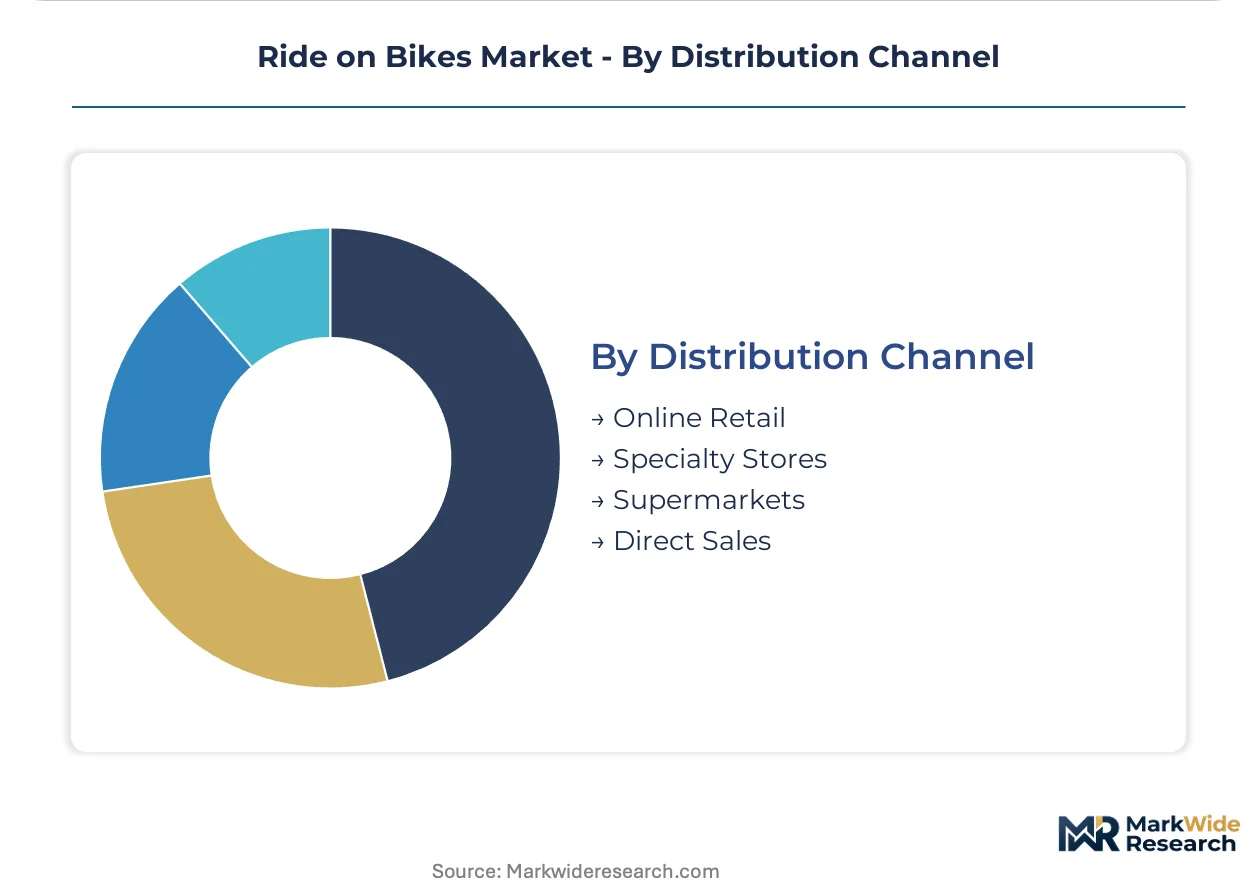
Specialty Stores retains the service-intensive premium tier, yet Online Retail is gaining share fastest through direct-to-consumer electric bike specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban commuters in congestion-priced European capitals and Asian logistics hubs drive regional demand concentration. Fleet operators and individual buyers cluster where cycling infrastructure investment intersects with subsidy availability and last-mile delivery density.
Germany
KBA safety inspections and federal purchase subsidies accelerate electric bike replacement cycles in Berlin and Munich. The EU F-Gas Regulation shapes battery thermal management standards for premium commuter models. Manufacturing clusters in Baden-Württemberg concentrate precision powertrain engineering for mid-drive motor systems.
Netherlands
Dedicated cycling infrastructure in Amsterdam and Rotterdam sustains the highest per-capita bike ownership rates globally. National subsidy programs and employer lease schemes compress payback periods for electric cargo bikes. The Randstad metropolitan ring generates concentrated fleet procurement from logistics operators replacing van-based deliveries.
United States
CPSC safety standards and municipal congestion pricing in New York and San Francisco channel commuters toward electric alternatives. Direct-to-consumer platforms reduce price points through simplified assembly protocols. The Pacific Northwest and Colorado mountain clusters sustain aftermarket service revenue from suspension rebuild cycles.
China
MIIT manufacturing directives and GB standards govern OEM supplier qualification for export-oriented assembly. Urban rail integration gaps in Shenzhen and Chengdu create white space for dockless electric bike sharing. The Yangtze River Delta concentrates frame fabrication and lithium-ion cell integration capacity.
India
Metro rail last-mile gaps in Bangalore, Pune, and Hyderabad drive dockless electric bike sharing pilots. BIS certification requirements and state-level EV policies shape product specification for domestic market entry. The Delhi-NCR corridor generates fleet demand from e-commerce logistics operators seeking congestion avoidance.
Ride on Bikes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Premium positioning through proprietary technology and mass-market penetration through simplified assembly coexist as viable strategies. Three archetypes dominate: vertically integrated custom manufacturers, direct-to-consumer platform operators, and performance-specialist engineering houses. Competitive moves concentrate on geographic expansion through localized assembly partnerships and portfolio diversification into electric cargo variants.
Within the premium engineering tier, Trek and Specialized occupy positions defined by proprietary suspension and aerodynamic technologies. Rad Power Bikes anchors the direct-to-consumer channel with simplified assembly protocols. Giant represents scale-driven manufacturing integration across multiple price bands and regional markets.
| Leading Market Players |
|---|
| Trek |
| Himiway |
| Rad Power Bikes |
| Velotric |
| Surron |
| Aventon |
| Specialized |
| Hovsco |
| Giant |
| Others |
Value Network & Pricing Analysis
Lithium carbonate volatility originating from Chinese cathode supply chains compresses margin predictability for electric bike assemblers while simultaneously forcing tiered pricing spreads between premium thermal-managed battery packs and entry-level cell configurations. This input cost uncertainty shapes procurement strategies across German KBA-certified manufacturers and direct-to-consumer platforms alike.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange lithium carbonate benchmarks dominate procurement between frame assemblers and cell suppliers. Three-tier pricing structure across premium, standard, and economy levels separates torque-sensing mid-drive systems from hub-motor alternatives from unassisted mechanical frames. Pricing pressure stems from raw material cost swings in battery chemistry inputs, compressing assembler margins most acutely in the mid-tier electric commuter segment. Fleet operators in Paris and Berlin exhibit highest price sensitivity through volume procurement tenders, while premium road bike enthusiasts in the Alps demonstrate lowest elasticity for proprietary suspension integration.
Supply Chain Analysis
Export control regimes restricting advanced power electronics and semiconductor-grade thermal management components limit controller firmware flows from automotive and robotics sectors into bike motor manufacturing. Frame fabrication concentrates in China's Yangtze River Delta, lithium-ion cell integration in South Korea and Japan, and precision powertrain engineering in Germany's Baden-Württemberg cluster. Raw material dependencies span carbon fiber precursors from Japan, rare earth magnets for mid-drive motors from China, and aluminum alloy extrusions from domestic European mills. Single-source vulnerability in torque-sensing chipset supply creates chokepoint exposure. Distribution runs through direct-to-consumer platforms for mass-market electric utility frames and specialty dealer networks for premium mountain and road categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
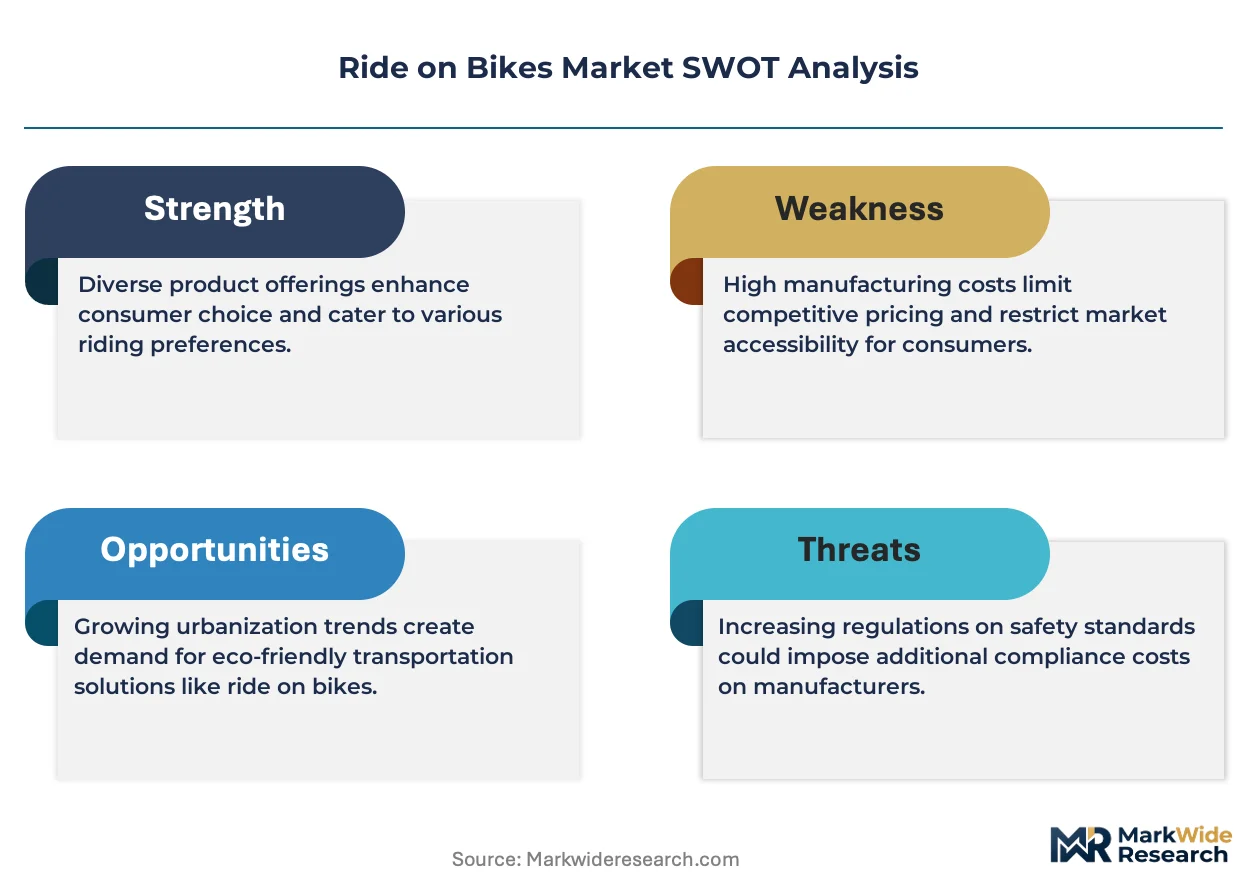
This market rewards incumbents with regulatory entrenchment advantages as EU F-Gas and REACH compliance documentation creates multi-year certification barriers that emerging competitors cannot rapidly replicate.
For Market Incumbents: Pre-empt margin erosion by securing captive lithium supply through backward integration into cell assembly partnerships in South Korea or Japan, and harden defensive positions by accelerating proprietary torque-sensing algorithm development before automotive semiconductor suppliers pivot into bike motor controllers. The threat of automotive-tier power electronics firms entering the precision powertrain space demands immediate R&D lock-in. For New Entrants and Emerging Players: Establish a beachhead in Indian dockless electric bike sharing corridors where metro rail integration gaps in Bangalore and Pune create unserved demand with minimal incumbent saturation. Target fleet procurement contracts with e-commerce logistics operators in the Delhi-NCR corridor, leveraging battery-as-a-service subscription models to circumvent upfront capital barriers that constrain individual ownership penetration. For Investors and Strategic Acquirers: EU battery recycling mandates reshaping the acquisition landscape favor targets with modular cell architectures and documented SCIP database compliance infrastructure. Long-term viability over the next decade hinges on thermal management IP and regulatory documentation depth rather than brand equity alone. The signal to watch is consolidation velocity among mid-tier frame assemblers unable to absorb REACH reformulation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Mid-Drive Motor Platform Standardization | Torque-sensing architectures from Bosch and Shimano reduce R&D duplication across German and Dutch OEM portfolios. |
| Battery Thermal Management Partnership | Collaboration with South Korean cell suppliers secures F-Gas-compliant chemistry access for premium commuter tiers. |
| Direct-to-Consumer Assembly Simplification | Rad Power Bikes' modular packaging protocols compress final-mile delivery costs and expand geographic reach. |
| CE Marking Technical File Investment | Pre-assembled electromagnetic compatibility documentation accelerates time-to-market for new frame platforms. |
| Fleet Maintenance Contract Expansion | Paris and Berlin logistics operators displace dealer networks with uptime-guaranteed mobile service units. |
Research Methodology
A spread of perspectives from frame engineering directors at German OEMs, procurement leads at South Korean battery suppliers, fleet operators in Paris and Berlin, specialty dealer principals in Amsterdam, and regulatory affairs specialists at ECHA converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU F-Gas implementation guidance, REACH SCIP database filings, KBA safety inspection protocols, and MIIT manufacturing directives. Customs data from Chinese frame export flows and Dutch cycling infrastructure investment disclosures provided volume anchors. Bottom-up assembly cost modeling and top-down category spend analysis were cross-referenced for triangulation.
Demand-supply balance framing anchored the projection framework across the analysis window. Segmentation dimensions modeled included product type, customer archetype, usage purpose, and distribution channel, with electric powertrain penetration rate treated as a cross-cutting variable. CAGRs were derived from segment-level volume buildups reconciled against aggregate category spend estimates. Industry-specific forecast inputs incorporated lithium carbonate price trajectory assumptions and municipal congestion pricing expansion schedules across European capitals.
Stress conditions across lithium raw material cost bands, EU regulatory enforcement intensity, and fleet procurement contract renewal cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure investment continuity and subsidy program stability. Material shifts in battery chemistry substitution timelines or REACH substance restriction scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
UAE Motorcycle ADAS Market
Bikes and Motorcycles
Adventure Motorcycle Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Motorcycle Headlight Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Netherlands E-Bike Market
Bikes and Motorcycles
UAE Electric Bike Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market