
 Motorcycle Drive Chain Market | 2026-2036
Motorcycle Drive Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Drive Chain Market Foresight
Modular chain-and-sprocket bundling is realigning how aftermarket buyers evaluate replacement options, shifting preference toward pre-matched kits over standalone component sales. Daido Kogyo Co., Ltd. leverages its integrated steel-making and chain-finishing operations to control alloy specifications from melt to final hardening. Tsubakimoto Chain Co. anchors its position through precision manufacturing scale serving both Japanese OEMs and global distributors. RK Japan differentiates via racing-derived technology transfer into premium street and sport bike segments.
A motorcycle drive chain is a roller chain transmitting mechanical power from the engine sprocket to the rear wheel, typically constructed from hardened carbon or alloy steel with pitch specifications ranging from 420 to 630 series and tensile ratings exceeding kilonewton thresholds for high-displacement applications. Its primary purpose is to deliver reliable torque transfer under variable load, contamination, and tension conditions across diverse operating environments. O-ring and X-ring sealed chains command margin concentration due to extended service intervals and lubrication retention advantages over standard unsealed designs. Street bikes represent the volume foundation while sport bikes drive premium specification adoption with tighter tolerance requirements.
Japan's METI enforces JIS standards for motorcycle component durability, directly influencing export certification requirements for chains manufactured in Asian supply bases. EPA noise and emissions regulations in the United States indirectly shape chain demand through OEM powertrain efficiency targets that stress driveline component optimization. India's BIS mandates component-level testing that filters non-compliant suppliers from aftermarket distribution channels serving its massive two-wheeler parc. Stakeholders must monitor how evolving electric motorcycle platform architectures alter torque delivery characteristics and chain load profiles.
Market Dynamics
Aftermarket chain-and-sprocket bundling is compressing standalone component margins while elevating kit-based suppliers who control matched-set quality and installation simplicity.
Growth Catalysts
- India's BIS component mandates:Mandatory testing protocols for two-wheeler chains are filtering substandard suppliers from distribution channels serving the country's massive vehicle parc.
- Southeast Asian OEM sourcing clusters:Thailand, Vietnam, and Indonesia manufacturing hubs are scaling production for street and commuter bike exports to Europe and Latin America.
- X-ring sealed chain technology:Extended service intervals and superior lubrication retention are displacing unsealed designs in premium displacement categories.
Market Restraints
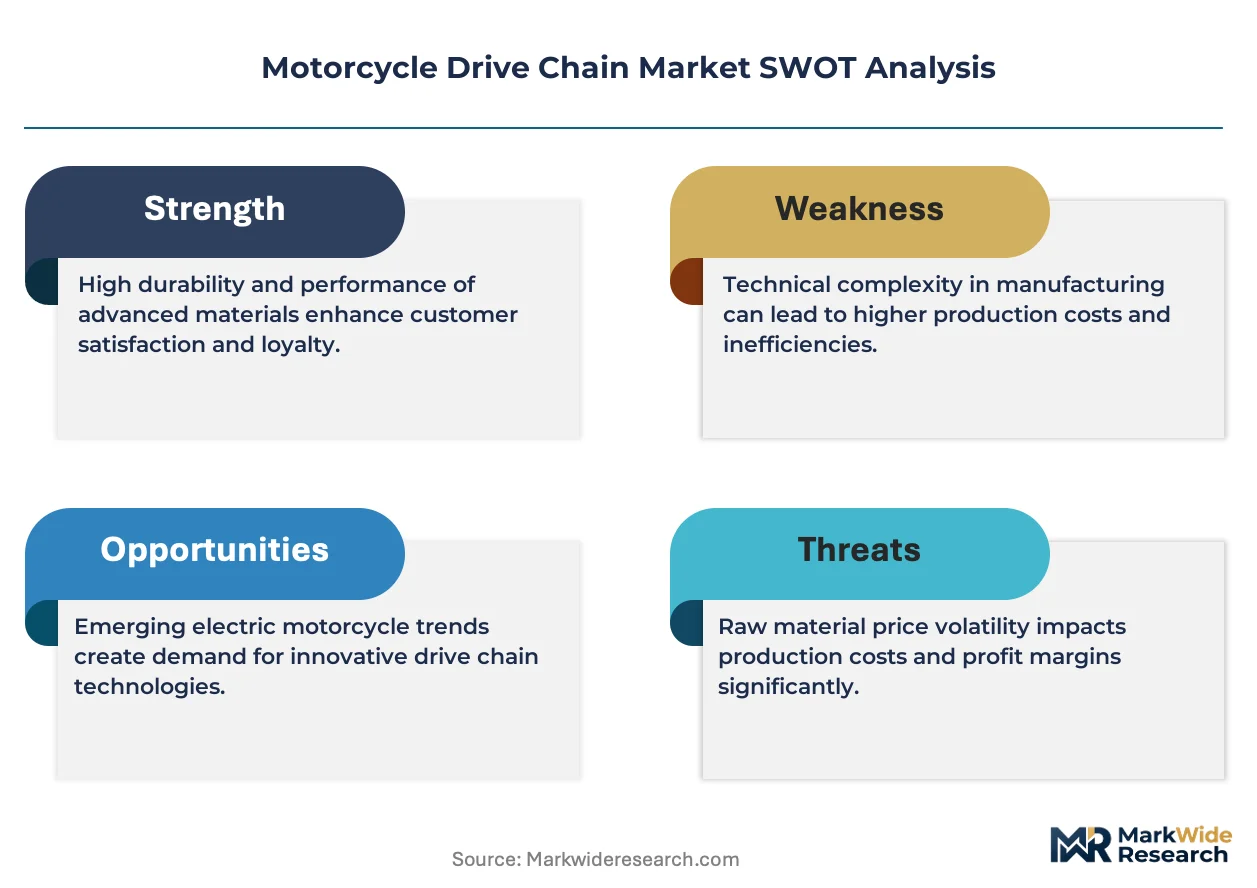
- Alloy steel input volatility:Nickel and chromium price swings directly compress hardening-stage margins for carbon-to-alloy specification transitions.
- Japanese supplier concentration:Daido Kogyo and Tsubakimoto Chain control melt-to-finish integrated capacity, limiting second-tier access to specification-grade steel.
- Belt drive substitution:Shaft and toothed-belt systems are capturing share in high-displacement touring and cruiser segments where maintenance minimization commands premium pricing.
Strategic Opportunities
- Brazilian aftermarket expansion:Underpenetrated kit distribution in São Paulo and Rio de Janeiro rider communities offers first-mover positioning for pre-matched chain-sprocket bundles.
- Electric motorcycle torque profiles:Instantaneous torque delivery characteristics require redesigned load-bearing specifications and fatigue-testing protocols.
- Japan's METI durability standards:JIS certification alignment opens export pathways for Asian supply bases seeking OEM qualification in developed markets.
Industry Challenges
- Heat-treatment skill scarcity:Specialized hardening technicians capable of maintaining JIS-compliant case-depth tolerances are concentrated in aging Japanese and German workforces.
- Multi-standard certification timelines:Simultaneous BIS, JIS, and EPA durability testing extends product launch cycles by 14-18 months for export-focused manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Drive Chain Market |
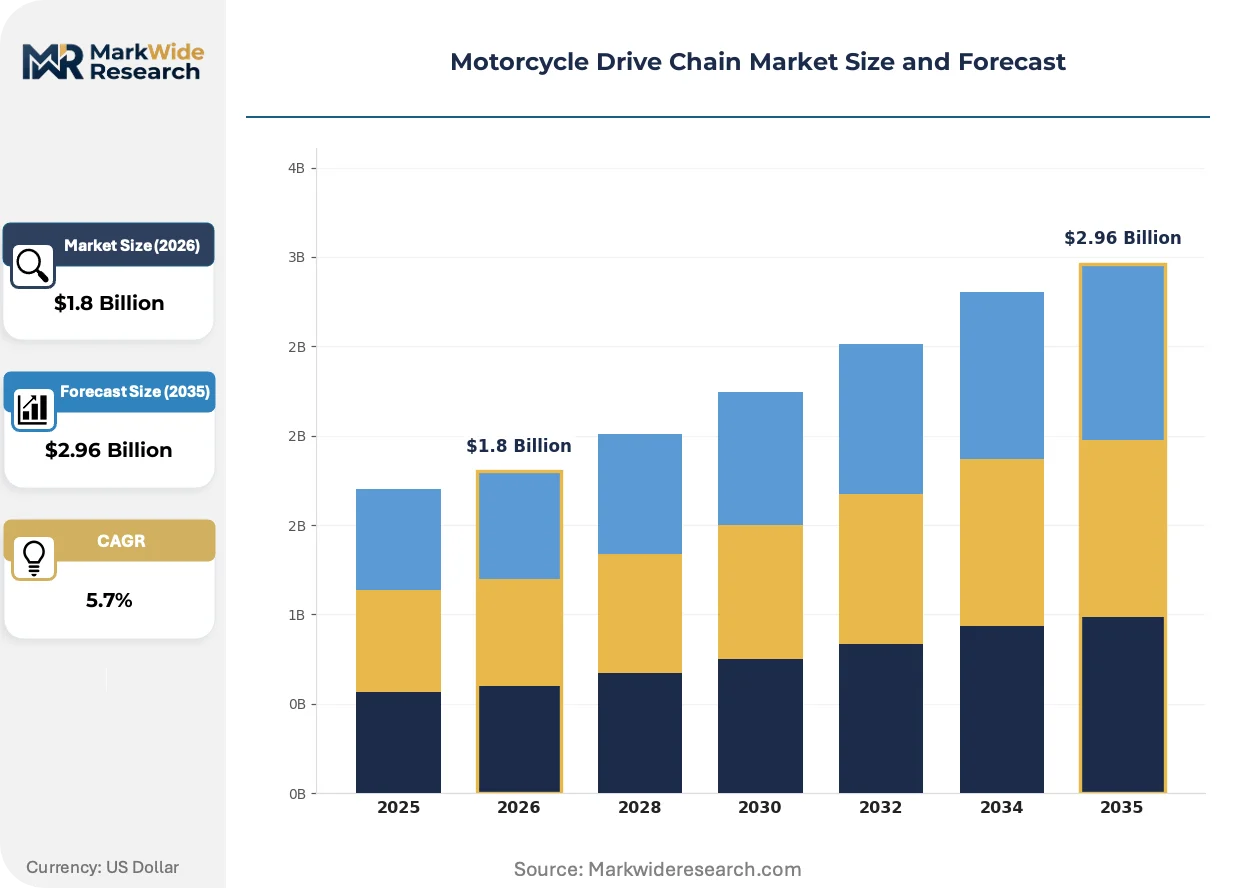
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chains, O-ring Chains, X-ring Chains, Heavy-Duty Chains Material: Steel, Alloy, Carbon, Stainless Steel End User: OEMs, Aftermarket Providers, Commercial Users, Individual Riders Application: Street Bikes, Dirt Bikes, Sport Bikes, Cruiser Bikes |
| Companies Covered | Daido Kogyo Co., Ltd., Tsubakimoto Chain Co., RK Japan, Regina Catene S.p.A., Sunstar Engineering, ENUMA Chain Mfg. Co., Ltd., Renthal Ltd, KMC International Inc., Qingdao Choho Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Drive Chain Market Shifts & Advancements
Pre-matched component ecosystems, regulatory durability mandates, and electric powertrain torque requirements are reconfiguring how chains are specified, sold, and stress-tested across displacement categories.
Sealed ring chain architecture is modularizing around standardized pitch-and-width platforms that accommodate multiple displacement classes through interchangeable pin and plate configurations. Japanese OEMs are adopting these platforms across 400cc to 1000cc model ranges to consolidate supplier relationships. The approach compresses SKU proliferation while allowing rapid specification adjustments for regional emission and noise regulations.
EPA noise regulations are forcing driveline efficiency optimization that stresses chain tensioning precision and friction minimization. OEM powertrain engineers are specifying tighter initial elongation tolerances to maintain sprocket engagement across variable load conditions. Sport bike manufacturers in Italy and Germany are responding with factory-installed X-ring chains and automated tensioning systems.
Kit-based procurement is displacing standalone component replacement among Southeast Asian commuter bike owners. Urban service centers in Bangkok and Jakarta are bundling chain, sprocket, and installation labor into fixed-price offerings that reduce customer decision complexity. This pattern is compressing margins for pure-play chain distributors while rewarding integrated aftermarket suppliers with direct workshop relationships.
Motorcycle Drive Chain Market Segmentation
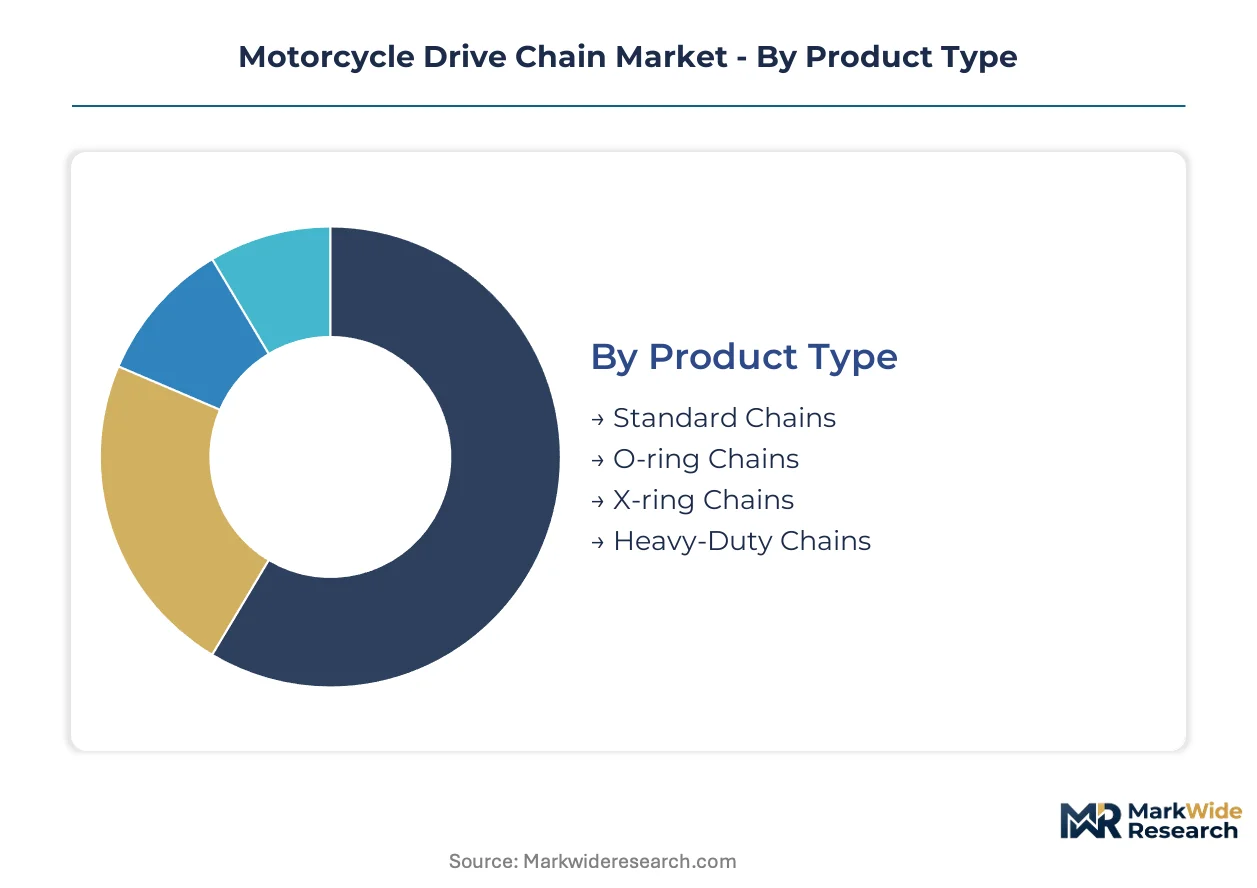
Chain specification varies sharply across displacement classes and duty cycles, requiring manufacturers to maintain parallel production lines with distinct hardening protocols. Segmentation clarity enables suppliers to align alloy selection and sealing technology with precise torque and contamination exposure profiles.
Product Type:
Capital intensity escalates dramatically with sealing complexity, as O-ring and X-ring configurations demand precision molding equipment and multi-stage assembly lines absent from standard chain production.
- X-ring Chains:Four-contact-point sealing geometry reduces friction by approximately 50% compared to O-ring designs while retaining lubrication across extended service intervals. Japanese OEMs specify these for 600cc-plus sport bikes where tension maintenance precision affects powertrain efficiency metrics under EPA noise regulations. India's BIS durability testing is accelerating adoption among export-oriented suppliers seeking premium positioning.
- O-ring Chains:Twin-lip elastomer seals deliver intermediate protection between unsealed and X-ring architectures, dominating mid-displacement street bike factory fitments. Thai and Vietnamese assembly plants source these for 150cc-400cc commuter exports to Latin American markets where service infrastructure favors 10,000-kilometer replacement cycles.
- Standard Chains:Unsealed roller designs serve cost-sensitive replacement demand in emerging markets with abundant low-cost labor for frequent maintenance.
- Heavy-Duty Chains:Reinforced plate thickness and oversized pins address high-torque cruiser and touring applications where belt-drive substitution has not yet displaced chain architectures.
Most installed capacity flows through O-ring configurations. Expansion is steepest in X-ring specifications.
Material:
Raw material selection determines case-hardening depth consistency and fatigue resistance under cyclic loading, with alloy formulations commanding premium positioning in OEM qualification programs.
- Alloy:Nickel-chromium formulations enable JIS-compliant surface hardness gradients essential for Japanese OEM sourcing contracts. Daido Kogyo's captive steelmaking secures specification control from melt through final heat treatment, creating supply scarcity for second-tier manufacturers lacking backward integration into ferrous metallurgy.
- Steel:Carbon-manganese grades dominate high-volume street bike production where cost optimization outweighs extended durability requirements. Indonesian and Thai assembly hubs specify these for domestic-market commuter bikes with 3-5 year replacement horizons.
- Carbon:Lower-grade formulations serve developing-market aftermarket replacement with minimal hardening investment.
- Stainless Steel:Corrosion resistance commands niche adoption in coastal riding environments and premium custom builds where aesthetic retention justifies material cost premiums.
Alloy grades absorb the majority of OEM specification investment. Stainless configurations are climbing fastest from minimal base penetration.
End User:
Procurement patterns diverge sharply between factory-installed specification authority and replacement-cycle purchasing behavior.
- OEMs:Factory fitment contracts demand JIS or BIS certification alignment, multi-year durability warranties, and direct engineering collaboration on tensioning system integration. Japanese and Indian motorcycle manufacturers consolidate supplier relationships around chains validated through 100,000-kilometer accelerated wear protocols.
- Aftermarket Providers:Pre-matched chain-sprocket kits are displacing standalone component sales in Southeast Asian urban service centers, compressing margins for pure-play distributors while rewarding integrated suppliers with direct workshop relationships.
- Commercial Users:Fleet operators in delivery and rental segments prioritize total cost of ownership calculations favoring extended-service sealed designs.
- Individual Riders:Enthusiast segments in Brazil and Argentina drive premium kit adoption through online channels and specialized retail.
OEM contracts anchor manufacturing scale. Aftermarket kit bundling is gaining share fastest.
Application:
Operating environment severity and performance expectations dictate tolerance specifications across displacement categories.
- Sport Bikes:Tighter pitch tolerances and reduced initial elongation specifications maintain sprocket engagement under rapid throttle modulation. Italian and German manufacturers specify factory-installed X-ring chains with automated tensioning systems to satisfy EPA noise regulations through driveline efficiency optimization.
- Street Bikes:Volume foundation of the market spans 125cc-400cc commuter and urban mobility segments where cost-efficient O-ring designs balance durability against price sensitivity. Indian and Southeast Asian manufacturing clusters scale production for domestic consumption and export to African and Latin American markets.
- Dirt Bikes:Contamination exposure and frequent cleaning cycles favor replaceable unsealed designs or specialized sealed variants with enhanced external sealing geometry.
- Cruiser Bikes:High-displacement touring applications face belt-drive substitution pressure where maintenance minimization commands premium pricing, though shaft-drive conversion remains capital-intensive for manufacturers.
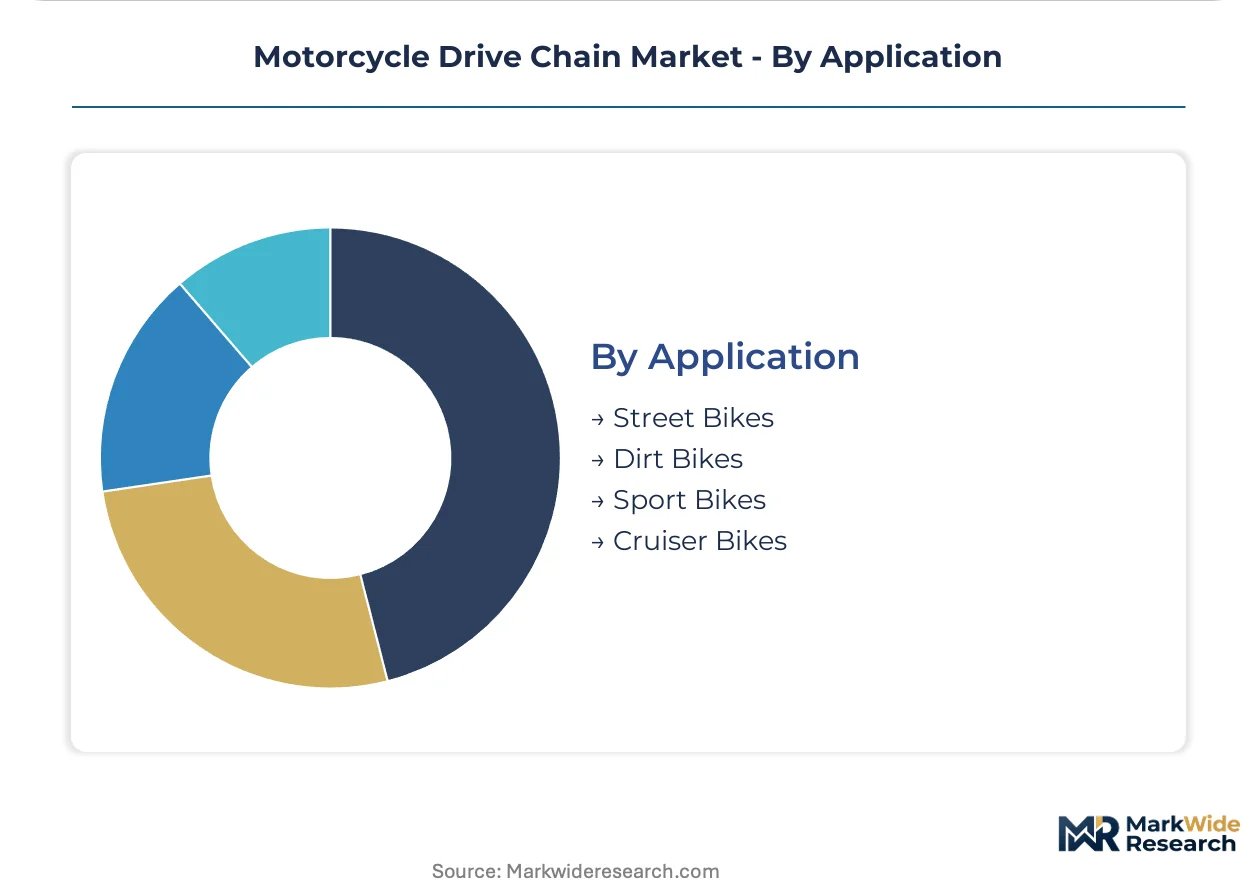
Street bike specifications absorb the greatest production volume. Sport bike requirements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered precision roller chain manufacturing in the post-war era, establishing metallurgical and heat-treatment standards that subsequently diffused across Asian supply bases. This technical lineage now shapes production geography from Kanto industrial corridors to emerging Southeast Asian assembly hubs.
Japan
Domestic OEM sourcing contracts and JIS durability certification anchor demand from Kawasaki, Honda, and Yamaha manufacturing networks. METI enforces component-level testing protocols that filter export suppliers from developed-market qualification pathways. The Kanto region surrounding Tokyo hosts integrated steel-to-chain operations serving both domestic motorcycle assembly and precision industrial applications.
India
BIS-mandated component testing for two-wheeler chains is restructuring aftermarket distribution channels serving the country's 200-million-plus vehicle parc. The PLI scheme for automotive components incentivizes domestic manufacturing scale for export-oriented suppliers. Maharashtra and Tamil Nadu industrial corridors concentrate forging and hardening capacity for Hero MotoCorp and Bajaj Auto sourcing requirements.
Thailand
OEM export manufacturing for Japanese and European motorcycle brands drives specification-grade chain demand at Rayong and Chonburi industrial estates. Board of Investment incentives attract tier-one suppliers seeking ASEAN market access with reduced tariff exposure. Bangkok metropolitan service centers are pioneering kit-based aftermarket bundling that compresses standalone component margins.
Vietnam
Honda and Yamaha assembly expansion in Vinh Phuc and Ha Nam provinces is scaling precision component demand for 150cc-400cc commuter exports. The Ministry of Industry and Trade's localization requirements pressure suppliers to establish domestic forging and surface-hardening operations. Ho Chi Minh City aftermarket distributors are consolidating workshop relationships through pre-matched chain-sprocket procurement contracts.
Indonesia
Domestic consumption of 125cc-250cc commuter bikes sustains high-volume O-ring chain specifications for Astra Honda Motor and Yamaha Indonesia production. National industrial standards for two-wheeler components are tightening quality benchmarks for import substitution programs. The Cikarang manufacturing zone east of Jakarta concentrates stamping and assembly operations serving both domestic fitment and regional export.
Motorcycle Drive Chain Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and metallurgical-control dimensions. Japanese suppliers with captive steelmaking operations command specification authority in OEM qualification programs, while second-tier manufacturers compete on cost efficiency for aftermarket replacement cycles. Three archetypes define competitive positioning: integrated metallurgists controlling alloy formulations from melt to finish, precision specialists serving racing-derived performance segments, and scale-oriented fabricators optimizing high-volume street bike supply. Capacity expansion and strategic kit bundling represent the dominant competitive vectors reshaping distributor relationships.
Among Japanese integrated manufacturers, Daido Kogyo Co., Ltd. and Tsubakimoto Chain Co. occupy positions defined by backward control over ferrous metallurgy and heat-treatment protocols. RK Japan represents the racing-technology transfer archetype, translating competition-derived specifications into premium street and sport bike applications. These three entities exemplify how technical lineage and manufacturing integration create tiered access to OEM sourcing contracts and export certification pathways.
| Leading Market Players |
|---|
| Daido Kogyo Co., Ltd. |
| Tsubakimoto Chain Co. |
| RK Japan |
| Regina Catene S.p.A. |
| Sunstar Engineering |
| ENUMA Chain Mfg. Co., Ltd. |
| Renthal Ltd |
| KMC International Inc. |
| Qingdao Choho Industrial Co., Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between JIS-qualified alloy chains and carbon-steel commodity alternatives creates parallel pricing architectures that track metallurgical control depth from melt to final hardening. Japanese integrated manufacturers command specification premiums through captive steelmaking, while second-tier suppliers compete on cost efficiency for aftermarket replacement cycles with minimal hardening investment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified alloy specifications from BIS-aligned mid-grade O-ring configurations and unsealed carbon-steel replacements. Price differentiation rests on certification tier and backward integration depth, with nickel-chromium formulations absorbing OEM specification investment. Cost compression in standard-grade segments is intensifying because Indonesian and Thai assembly hubs prioritize carbon-manganese cost optimization. Fleet operators and commercial users show least price sensitivity for extended-service sealed designs, while individual riders in emerging markets drive economy-tier volume.
Supply Chain Analysis
Certification gating through JIS and BIS protocols concentrates specification-grade supply in Japan and India, with secondary forging capacity scaling in Thailand and Vietnam for ASEAN market access. Raw material dependencies draw from nickel and chromium alloying elements, high-grade carbon steel billets, and precision elastomer sealing compounds. Single-source vulnerability runs through Japanese integrated steel-to-chain operations controlling alloy formulation from melt through final heat treatment. Distribution runs through OEM direct contracts anchoring manufacturing scale, supplemented by pre-matched kit bundling displacing standalone component sales in Southeast Asian urban service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where BIS certification investment in India unlocks access to a 200-million-plus vehicle parc at lower regulatory compliance cost than JIS qualification pathways serving developed-market OEMs.
For Market Incumbents: Hedge against belt-drive substitution in high-displacement touring segments by deepening captive steelmaking control and accelerating X-ring platform standardization across 400cc-1000cc model ranges. Prioritize certification maintenance through METI durability protocol alignment to defend OEM contract access against emerging Asian suppliers.
For New Entrants and Emerging Players: Begin with Brazilian aftermarket kit distribution in São Paulo and Rio de Janeiro rider communities, where pre-matched chain-sprocket bundling remains underpenetrated relative to Southeast Asian service center penetration. Target direct workshop relationships through fixed-price installation offerings that reduce customer decision complexity.
For Investors and Strategic Acquirers: Consolidation pressure builds where heat-treatment skill scarcity concentrates in aging Japanese and German workforces. Long-term viability favors targets with demonstrated JIS certification alignment and established OEM engineering collaboration on tensioning system integration. Watch electric motorcycle platform torque specification shifts as inflection indicator for redesigned load-bearing requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steelmaking | Captive alloy formulation from melt through hardening secures JIS-compliant case-depth tolerances for OEM qualification. |
| X-Ring Platform Standardization | Modular pitch-and-width architectures consolidate supplier relationships across 400cc-1000cc Japanese OEM model ranges. |
| Pre-Matched Kit Bundling | Fixed-price chain-sprocket-installation offerings compress standalone component margins while capturing workshop relationships. |
| BIS Certification Alignment | Component-level testing protocol compliance filters non-compliant suppliers from India's massive aftermarket distribution channels. |
| Electric Powertrain Specification Development | Instantaneous torque delivery characteristics demand redesigned fatigue-testing protocols and load-bearing geometries. |
Research Methodology
Multiple input streams — executive interviews with OEM procurement teams and aftermarket distribution heads, technical consultations with heat-treatment specialists and metallurgical engineers, and regulatory validation with BIS and METI compliance officers — were reconciled against customs records, JIS certification databases, motorcycle production registries, and SEC filings from listed component suppliers. Bottom-up volume builds across displacement categories and sealing technologies were cross-checked against top-down market sizing from trade flow analysis and OEM sourcing contract aggregation.
Historical shipment trajectories were cross-referenced against panel input from tier-one supplier strategy teams to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, material grade, end-user procurement pattern, and application duty cycle, with CAGRs derived from elasticity-adjusted volume projections and value-per-unit trends. Electric motorcycle platform development timelines and torque specification evolution served as category-specific forecast modifiers.
Caveats apply where alloy steel input volatility, multi-standard certification timeline extensions, or electric powertrain architecture shifts could materially shift the outlook. Forecasts reflect assumptions regarding continued JIS and BIS protocol stability and OEM consolidation around modular platform sourcing. A model refresh is warranted upon material change in nickel-chromium price trajectories or electric motorcycle torque delivery standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycle Fuel Hoses Market
Bikes and Motorcycles
Bicycle Saddles Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Motorcycle Airbag Market
Bikes and Motorcycles
North America Bicycle Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Motorcycle Horns Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
Motorcycle Drivetrain Market
Bikes and Motorcycles
Africa Two-Wheeler Market