
 Electric Vehicle Edrive Test Equipment Market | 2026-2036
Electric Vehicle Edrive Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Edrive Test Equipment Market Insights
Commercial vehicle electrification is restructuring how automotive OEMs and Tier-1 suppliers allocate capital toward validation infrastructure. AVL List GmbH dominates powertrain test bench integration for European truck electrification programs. Chroma ATE leverages its Taiwan manufacturing base to compete on cost for battery cycle test systems shipped to mainland China. HORIBA sustains technical leadership in motor dynamometer applications through sustained R&D spending on high-speed e-axle validation.
Electric Vehicle Edrive Test Equipment encompasses dynamometers, power analyzers, battery cyclers, and environmental chambers engineered to validate torque ripple below 0.5 percent, efficiency maps across 10-150 kW ranges, and thermal runaway containment under abuse conditions. Powertrain Test Systems anchor the largest margin pool due to the complexity of integrating inverter, motor, and gearbox subsystems under single-test protocols. Battery Test Systems represent the fastest-expanding category as cell-to-pack architectures demand verification of volumetric energy density and fast-charge degradation curves. Simulation Technology is displacing physical prototyping for early-stage inverter control algorithm validation, compressing development timelines for automotive OEMs.
China's MIIT enforces GB/T standards for NEV powertrain efficiency and battery safety testing that mandate specific equipment capabilities for homologation. EPA and NHTSA in the United States shape demand through Corporate Average Fuel Economy enforcement and pending heavy-duty vehicle electrification rules that expand compliance testing scope. ECE R100 and the EU Green Deal's CO2 fleet targets push European OEMs toward dual-motor powertrain validation. Stakeholders must monitor how battery chemistry shifts toward solid-state and sodium-ion architectures redefine the specification boundaries for thermal and electrical abuse test equipment.
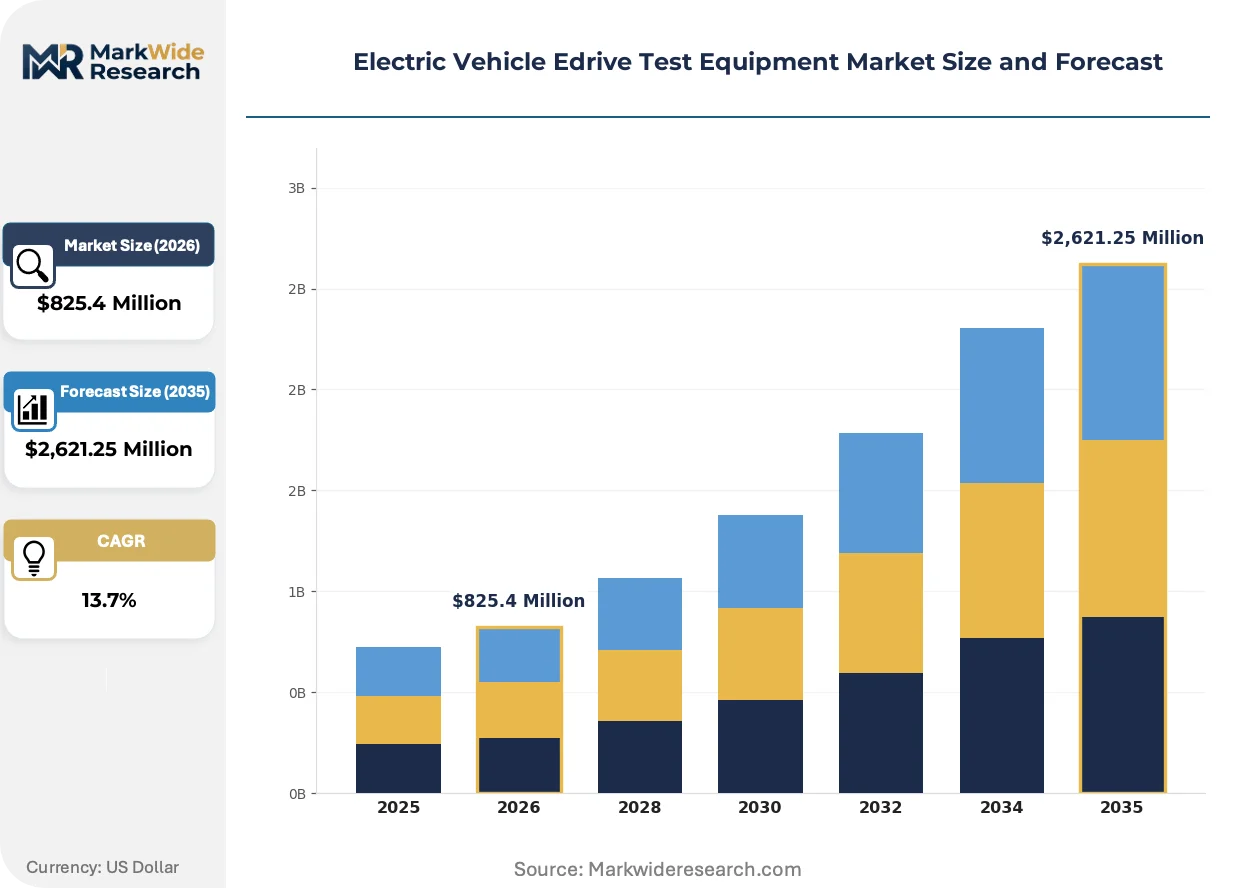
Market Dynamics
Commercial vehicle electrification is compressing development cycles for powertrain validation, forcing OEMs to consolidate physical testing with real-time simulation environments. This structural pressure is redistributing capital from prototype fleets toward integrated test bench infrastructure capable of validating 800V architectures and silicon carbide inverters under unified protocols.
Growth Catalysts
- GB/T 18488 Powertrain Efficiency Mandates:China's MIIT enforces stringent efficiency testing protocols for NEV homologation, requiring dynamometer systems capable of mapping torque ripple below 0.5 percent across full operating envelopes.
- Cell-to-Pack Architecture Verification:Battery manufacturers demand cyclers that validate volumetric energy density and fast-charge degradation curves for integrated pack designs, expanding equipment specification boundaries.
- Silicon Carbide Inverter Adoption:Wide-bandgap semiconductor integration into e-axles necessitates power analyzers with bandwidth exceeding 10 MHz to capture switching losses at frequencies above 100 kHz.
Market Restraints
- Copper and Rare Earth Price Volatility:Permanent magnet motor test equipment faces input cost pressure from neodymium and dysprosium supply concentration in Chinese refining operations.
- High-Voltage Safety Certification Burden:ECE R100 compliance for equipment operating above 60V DC imposes extended validation timelines and specialized personnel requirements on test bench manufacturers.
- Simulation Software Substitution:Hardware-in-the-loop platforms from dSPACE and National Instruments displace physical dynamometer hours for early-stage inverter algorithm development.
Strategic Opportunities
- Solid-State Battery Thermal Abuse Testing:Next-generation cell chemistries require redesigned environmental chambers capable of containing lithium-metal dendrite propagation under nail penetration and overcharge scenarios.
- Heavy-Duty Truck Electrification in Germany:MAN and Daimler Truck validation programs create demand for 500+ kW dynamometer systems with integrated cooling loop simulation for e-axle endurance testing.
- Subscription-Based Equipment Access:Tier-2 suppliers in India and Southeast Asia adopt leased test capacity through regional validation service providers, bypassing capital-intensive equipment ownership.
Industry Challenges
- High-Speed E-Axle Calibration Expertise Gap:Test engineers with proficiency in 20,000+ RPM motor validation and NVH measurement are concentrated among European and Japanese equipment specialists.
- Legacy 400V/800V Architecture Coexistence:Test facilities must maintain dual infrastructure capabilities during the extended transition period, straining floor space and capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Edrive Test Equipment Market |
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $2,621.25 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Test Systems, Powertrain Test Systems, Charging Infrastructure, Motor Test Equipment End User: Automotive OEMs, Tier-1 Suppliers, Research Institutions, Aftermarket Providers Technology: Load Testing, Measurement Systems, Simulation Technology, Data Acquisition Systems Application: Performance Testing, Safety Testing, Compliance Testing, Reliability Testing |
| Companies Covered | AVL List GmbH, Chroma ATE, HORIBA, TUV Rheinland, Keysight Technologies, National Instruments, Durr Group, Rohde & Schwarz, Ametek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Edrive Test Equipment Market Trends and Innovations
Power electronics integration and software-defined validation protocols are converging to compress development timelines. Equipment vendors are repositioning around data throughput and simulation fidelity rather than raw mechanical capacity.
Hardware-in-the-loop test benches are modularizing around standardized inverter control interfaces, enabling automotive OEMs to swap power modules without reconfiguring entire dynamometer cells. Tier-1 suppliers in Germany and Japan are adopting these platforms for parallel validation tracks. This architecture is modularizing supplier relationships, allowing buyers to source power stages from semiconductor vendors independently of mechanical subsystem integrators.
The EU Green Deal's CO2 fleet targets are accelerating dual-motor powertrain homologation requirements, compelling European OEMs to invest in synchronized multi-axis dynamometer systems. ECE R100 revisions are tightening electrical isolation test protocols for 800V architectures. Battery cyclers with integrated thermal runaway containment are capturing preference share in German and French validation facilities.
Validation service outsourcing is displacing captive test infrastructure among mid-volume EV startups in the United States and China. Contract test houses in Michigan and Shanghai are expanding capacity for complete powertrain endurance programs. This model concentrates demand among equipment vendors capable of remote monitoring and predictive maintenance integration.
Electric Vehicle Edrive Test Equipment Market Segmentation
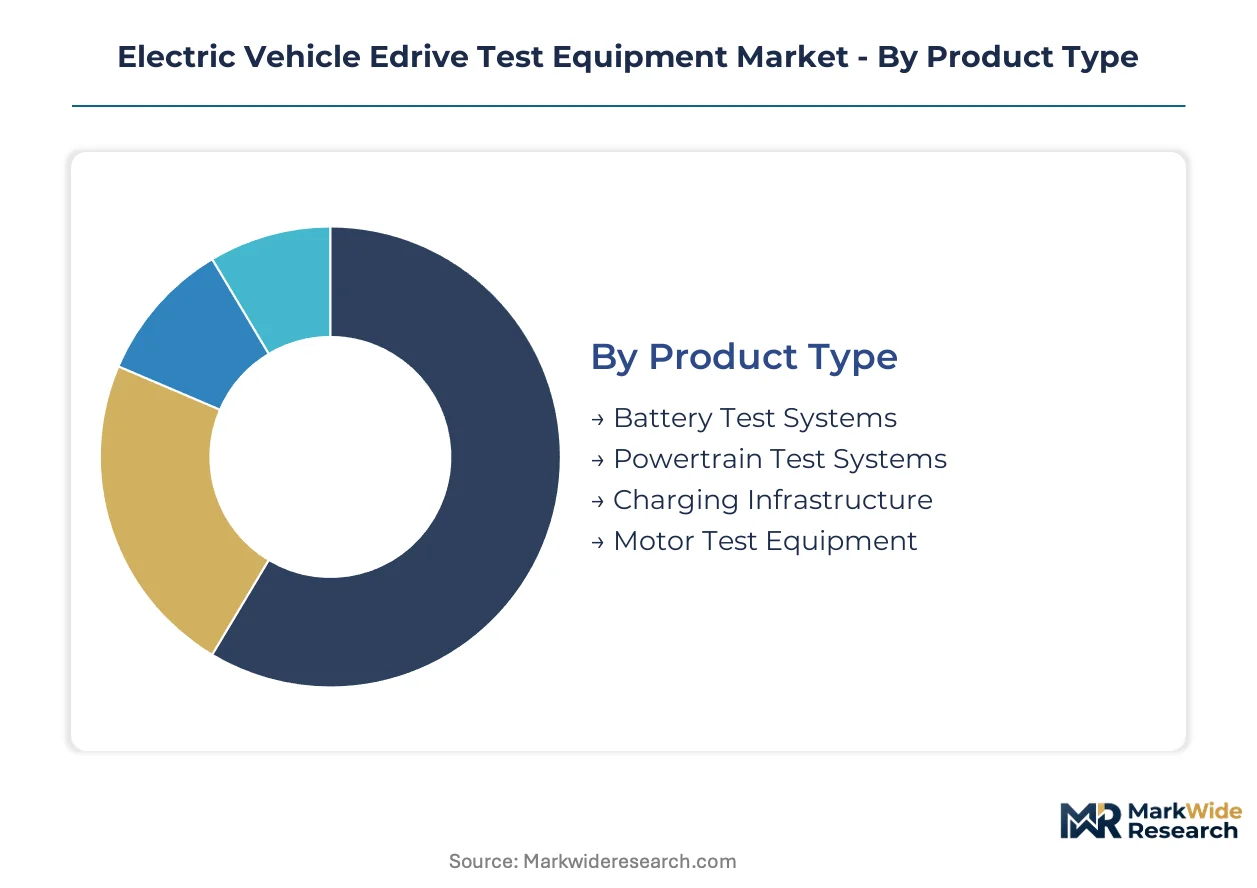
Test equipment vendors configure product portfolios around the integration depth of customer validation workflows. Standalone systems serve discrete testing phases, while embedded platforms synchronize multiple measurement domains under unified control architectures.
Product Type:
Standalone battery cyclers operate independently of powertrain benches, whereas integrated power analyzer modules embed directly within dynamometer control loops.
- Battery Test Systems:Cyclers and environmental chambers validate cell-to-pack thermal behavior and fast-charge degradation. Demand concentrates in Chinese NEV homologation labs where MIIT enforces GB/T abuse testing protocols for lithium-ion architectures. Solid-state chemistry transitions are expanding specification requirements for dendrite containment and lithium-metal anode validation.
- Powertrain Test Systems:Integrated dynamometer cells synchronize motor, inverter, and gearbox validation under single-test protocols. German truck electrification programs at MAN and Daimler Truck drive 500+ kW capacity demand with integrated cooling loop simulation. These systems anchor the largest margin pool due to multi-subsystem complexity.
- Charging Infrastructure:Test benches for DC fast-charger interoperability and grid integration.
- Motor Test Equipment:High-speed dynamometers and NVH analyzers for e-axle validation.
Powertrain Test Systems lead volumes today; Battery Test Systems are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive captive facilities from outsourced validation service models.
- Automotive OEMs:Captive test infrastructure for pre-homologation powertrain development and competitive benchmarking. Volkswagen and BYD maintain internal dynamometer networks spanning 400V and 800V architecture validation. OEMs consolidate spending toward integrated simulation-physical hybrid platforms.
- Tier-1 Suppliers:Equipment purchases track program-specific contract awards from automotive OEMs. Bosch and Continental operate validation centers in Germany, China, and the United States with synchronized multi-axis dynamometer capacity for dual-motor e-axle programs.
- Research Institutions:University and national laboratory procurement for fundamental power electronics and materials research.
- Aftermarket Providers:Diagnostic and refurbishment equipment for battery second-life and remanufacturing applications.
Automotive OEMs dominate current procurement; Tier-1 Suppliers are expanding capacity most aggressively.
Technology:
Application context determines whether measurement fidelity or simulation speed takes priority in technology selection.
- Load Testing:Mechanical and electrical load application for durability and thermal stress validation. Chassis dynamometer installations in Michigan and Shanghai contract test houses absorb demand from EV startups bypassing captive infrastructure ownership.
- Measurement Systems:Power analyzers, torque transducers, and temperature mapping for efficiency mapping and NVH characterization. Wide-bandgap silicon carbide inverter adoption necessitates bandwidth exceeding 10 MHz to capture switching losses above 100 kHz.
- Simulation Technology:Hardware-in-the-loop platforms for inverter control algorithm development.
- Data Acquisition Systems:Multi-channel sensor integration for synchronized mechanical and electrical parameter logging.
Measurement Systems anchor current spending; Simulation Technology is climbing the fastest.
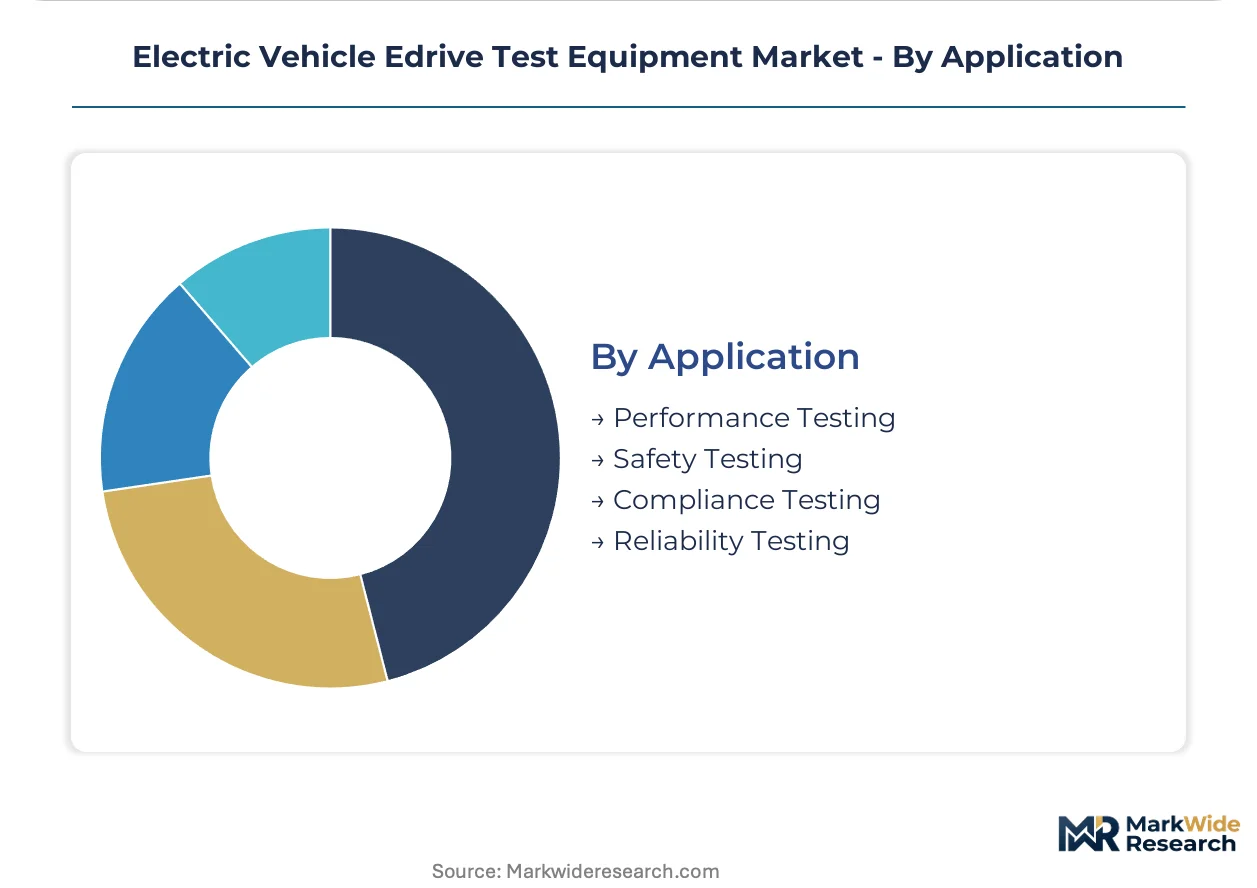
Application:
Regulatory mandate intensity varies across application types, with compliance testing carrying non-negotiable equipment specifications.
- Performance Testing:Efficiency mapping, torque ripple measurement, and thermal envelope characterization across operating envelopes. EPA and NHTSA Corporate Average Fuel Economy enforcement in the United States shapes dynamometer specification for heavy-duty vehicle electrification.
- Safety Testing:Thermal runaway containment, electrical isolation verification, and abuse scenario validation. ECE R100 revisions tighten protocols for 800V architectures, mandating specific environmental chamber capabilities for European homologation.
- Compliance Testing:Formal homologation against GB/T, ECE, and EPA regulations.
- Reliability Testing:Accelerated life testing and warranty validation for powertrain durability claims.
Performance Testing leads current equipment utilization; Safety Testing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive engineering corridor around Stuttgart and Munich concentrates the highest density of powertrain validation facilities serving European truck electrification programs. Chinese NEV mandates and American heavy-duty vehicle rules are redistributing equipment procurement across three distinct regulatory zones. Japanese precision instrumentation expertise sustains competitive positioning in high-speed motor measurement applications.
China
MIIT's GB/T 18488 efficiency mandates and GB/T battery safety protocols drive cyclers and dynamometer demand for NEV homologation. The MIIT enforces volumetric energy density verification for cell-to-pack architectures entering commercial production. Shanghai and Shenzhen validation clusters absorb capacity from domestic OEMs and contract test houses expanding for export certification.
Germany
MAN and Daimler Truck electrification programs require 500+ kW dynamometer systems with integrated cooling loop simulation for e-axle endurance testing. ECE R100 revisions tighten electrical isolation protocols for 800V architectures, mandating specific environmental chamber capabilities. Bavarian and Baden-Württemberg engineering centers anchor European powertrain validation infrastructure investment.
United States
EPA Corporate Average Fuel Economy enforcement and pending NHTSA heavy-duty vehicle electrification rules expand compliance testing scope for domestic OEMs. Michigan contract test houses absorb demand from EV startups bypassing captive infrastructure ownership. Detroit-area validation facilities concentrate on 400V/800V dual-architecture endurance programs.
Japan
METI funding for solid-state battery commercialization redirects thermal abuse testing specifications toward lithium-metal containment protocols. Nagoya and Tokyo precision engineering clusters sustain expertise in 20,000+ RPM motor validation and NVH measurement. Domestic equipment specialists capture regional share through high-speed e-axle calibration capabilities.
South Korea
Seoul Capital Area battery manufacturers demand cyclers validating fast-charge degradation curves for integrated pack designs entering European and North American supply chains. MFDS-aligned safety protocols shape environmental chamber specifications for export-bound cell production. Busan-Ulsan industrial complexes concentrate motor test equipment procurement for integrated e-axle programs.
Electric Vehicle Edrive Test Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as test bench manufacturers scale regional service networks to capture validation outsourcing demand from EV startups. The vendor base stratifies around three archetypes: integrated powertrain system integrators, standalone battery cycler specialists, and measurement instrument pure-plays. Geographic anchoring in German automotive corridors, Taiwanese electronics manufacturing, and Japanese precision engineering clusters shapes competitive positioning. M&A activity and strategic technology licensing are redistributing capability across silicon carbide inverter test bandwidth and solid-state battery thermal containment domains.
Among European integrated system providers, AVL List GmbH and HORIBA occupy positions exemplifying powertrain test bench consolidation around multi-subsystem validation protocols. Chroma ATE represents the Taiwan-based manufacturing archetype competing on cost for battery cycle test systems shipped to mainland China. These three anchors illustrate how regional industrial specialization—German automotive engineering depth, Japanese precision instrumentation heritage, and Taiwanese electronics manufacturing scale—maps onto distinct competitive vectors in dynamometer integration, high-speed motor measurement, and battery cycler production.
| Leading Market Players |
|---|
| AVL List GmbH |
| Chroma ATE |
| HORIBA |
| TUV Rheinland |
| Keysight Technologies |
| National Instruments |
| Durr Group |
| Rohde & Schwarz |
| Ametek |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between MIIT-homologated systems for Chinese NEV mandates and general-purpose equipment for aftermarket service creates divergent margin structures and sourcing strategies across the Electric Vehicle Edrive Test Equipment market. Premium-tier dynamometer cells command pricing premiums through integrated silicon carbide inverter test bandwidth and GB/T 18488 compliance documentation, while economy-tier battery cyclers compete on unit cost through Taiwanese electronics manufacturing scale.
Pricing Analysis
Input-cost pass-through from neodymium and dysprosium price volatility in Chinese rare earth refining operations compresses margins for permanent magnet motor test equipment manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and software integration intensity. Pricing pressure stems from hardware-in-the-loop simulation platforms displacing physical dynamometer hours for early-stage inverter algorithm development. Tier-2 suppliers in India and Southeast Asia exhibit highest price sensitivity, driving subscription-based equipment access models through regional validation service providers.
Supply Chain Analysis
China's domestic-content requirements for NEV homologation equipment reshape sourcing patterns toward local dynamometer integrators and battery cycler manufacturers. Manufacturing concentration centers on Germany for precision powertrain test benches, Taiwan for electronics-intensive battery cyclers, and Japan for high-speed motor measurement instrumentation. Copper winding materials, silicon carbide semiconductors, and rare earth permanent magnets constitute critical input dependencies. Single-source vulnerability persists in wide-bandgap semiconductor supply from limited wafer fabrication facilities. Distribution runs through direct OEM and Tier-1 procurement channels with extended validation service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle Edrive Test Equipment market functions as a stable compounder anchored by regulatory mandate intensity across Chinese NEV efficiency standards, EPA heavy-duty electrification rules, and ECE R100 revisions.
For Market Incumbents: Deepen backward integration into silicon carbide power analyzer modules to defend margin position against semiconductor vendor direct sales. Expand predictive maintenance service networks in Michigan and Shanghai contract test house clusters to capture validation outsourcing demand from EV startups. Prioritize GB/T 18488 certification documentation capabilities as Chinese MIIT tightens homologation requirements. For New Entrants and Emerging Players: The premium-to-economy price gap in battery cycler equipment for Indian and Southeast Asian Tier-2 suppliers offers white-space entry through leased test capacity models. Target safety testing environmental chambers for solid-state battery thermal abuse protocols as lithium-metal chemistry transitions accelerate. Pursue partnership-based go-to-market structures with regional validation service providers rather than direct equipment sales. For Investors and Strategic Acquirers: Consolidation pressure builds where hardware-in-the-loop simulation capabilities overlap with physical test bench infrastructure, creating redundant capacity among mid-cap specialists. Long-term viability favors integrated platform vendors spanning measurement systems, simulation technology, and data acquisition under unified control architectures. Monitor silicon carbide inverter adoption rates as inflection signal for power analyzer bandwidth demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Modular hardware-in-the-loop architectures enable automotive OEMs to swap power stages without reconfiguring entire dynamometer cells. |
| Battery Supply Agreement | Long-term cycler procurement contracts with Chinese cell-to-pack manufacturers secure volume through MIIT homologation cycles. |
| Software-Defined Vehicle Investment | Remote monitoring and predictive maintenance integration concentrates demand among equipment vendors serving outsourced validation. |
| Geographic Manufacturing Footprint | Regional service networks in Bavaria and Baden-Württemberg capture MAN and Daimler Truck e-axle endurance programs. |
| Charging Infrastructure Partnership | DC fast-charger interoperability test benches align with grid integration requirements under EPA heavy-duty electrification rules. |
Research Methodology
Bottom-up automotive OEM and Tier-1 supplier procurement tracking reconciled against top-down test bench manufacturer capacity and shipment monitoring forms the analytical core of this study. Primary interviews with validation engineering directors, equipment procurement managers at Bosch and Continental, contract test house operators in Michigan and Shanghai, and MIIT homologation lab administrators combined with secondary validation from SEC filings, MIIT GB/T standard documentation, ECE R100 regulatory texts, and vehicle production databases. Triangulation between demand-side program awards and supply-side order backlogs validates segment-level estimates.
Historical trendline analysis of powertrain validation equipment spending patterns across the analysis window informs projection frameworks. Segmentation dimensions span product type, end user archetype, technology category, and application context with additional modeling of voltage architecture transition timing between 400V and 800V systems. CAGRs derive from regression analysis of equipment procurement intensity against NEV production forecasts and regulatory mandate implementation schedules. Silicon carbide inverter adoption curves and solid-state battery chemistry transition timelines constitute industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter thermal abuse testing equipment demand. Forecasts reflect assumptions regarding Chinese NEV mandate enforcement continuity, EPA heavy-duty electrification rule finalization, and rare earth supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Transportation Predictive Analytics and Simulation Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Automotive Driving Simulators Market