
 Omega-3 Encapsulation Market | 2026-2036
Omega-3 Encapsulation Market Size, Share, and Industry Trends Forecast 2026-2036
Omega-3 Encapsulation Market Analytics
The capital-intensity gap between spray-drying tower operators and bench-scale encapsulation labs is collapsing as modular microfluidic systems cut entry thresholds for precision shell formation. Croda International Plc leverages its lipid chemistry heritage to sustain premium positioning in pharmaceutical-grade ethyl ester encapsulation. BASF SE anchors European supply through backward integration into algal fermentation, while Aker BioMarine competes on krill phospholipid matrix patents that improve bioavailability in cold-water sourcing.
Omega-3 encapsulation encloses polyunsaturated fatty acids—principally eicosapentaenoic acid and docosahexaenoic acid—within protective matrices of gelatin, modified starch, or alginate to prevent oxidative degradation and mask fishy off-notes during shelf storage and gastric transit. Softgels dominate value capture in human nutraceutical channels, while powders lead volume growth in pet nutrition and functional food premixes where thermal stability during extrusion determines specification acceptance. Krill oil phospholipid encapsulation commands the tightest supply allocation due to Antarctic catch quota constraints and specialized onboard processing requirements.
FDA GRAS notifications and EPA facility registration shape US market access for new omega-3 encapsulation entrants, while EFSA health claim authorizations determine permissible marketing language across EU member states. The EU F-Gas Regulation indirectly pressures solvent-based extraction and purification equipment choices, nudging investment toward supercritical CO2 processing. Stakeholders must monitor evolving EPA-DHA ratio specifications in pharmacopeial monographs and the trajectory of FDA enforcement discretion on structure-function claims as these will reset competitive qualification barriers faster than raw material cost cycles.
Market Dynamics
Modular microfluidic shell-formation systems are collapsing the capital barrier between industrial spray-drying towers and bench-scale labs, democratizing precision encapsulation access while compressing incumbent technology premiums.
Growth Catalysts
- EU Novel Food streamlining:The regulation accelerates algal oil approval pathways, enabling German dietary supplement brands to expand softgel portfolios without multi-year safety dossiers.
- Infant formula fortification:Specialized contract manufacturers in the United States pull encapsulated EPA and DHA volumes through dedicated pharmaceutical-grade production lines.
- Pet nutrition thermal stability specifications:Powder encapsulation formats gain specification acceptance in functional food premixes where extrusion resistance determines supplier qualification.
Market Restraints
- Antarctic catch quota constraints:Krill oil phospholipid encapsulation faces the tightest supply allocation due to specialized onboard processing requirements and seasonal harvesting limits.
- EPA facility registration barriers:New US entrants encounter FDA GRAS notification complexity and EPA enforcement discretion that resets competitive qualification timelines.
- Ethyl ester oxidation sensitivity:Pharmaceutical-grade specifications demand nitrogen-blanketed supply chains that inflate working capital requirements.
Strategic Opportunities
- Supercritical CO2 processing tailwinds:The EU F-Gas Regulation indirectly pressures solvent-based extraction equipment choices, nudging investment toward alternative purification infrastructure.
- Pharmacopeial EPA-DHA ratio standardization:Evolving monograph specifications create first-mover advantage for contract manufacturers with analytical method validation capabilities.
- Structure-function claim enforcement clarity:FDA discretion trajectories on permissible marketing language will reset competitive barriers faster than raw material cost cycles.
Industry Challenges
- Phospholipid matrix patent navigation:Krill-derived bioavailability claims require sophisticated freedom-to-operate analysis across overlapping intellectual property estates.
- Cross-functional talent scarcity:Formulation chemists with simultaneous lipid chemistry and shell-material engineering expertise command premium compensation in tight labor markets.
- Legacy gelatin supply integration:Bovine and porcine source certification timelines complicate portfolio transitions toward plant-based alginate and modified starch alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega-3 Encapsulation Market |
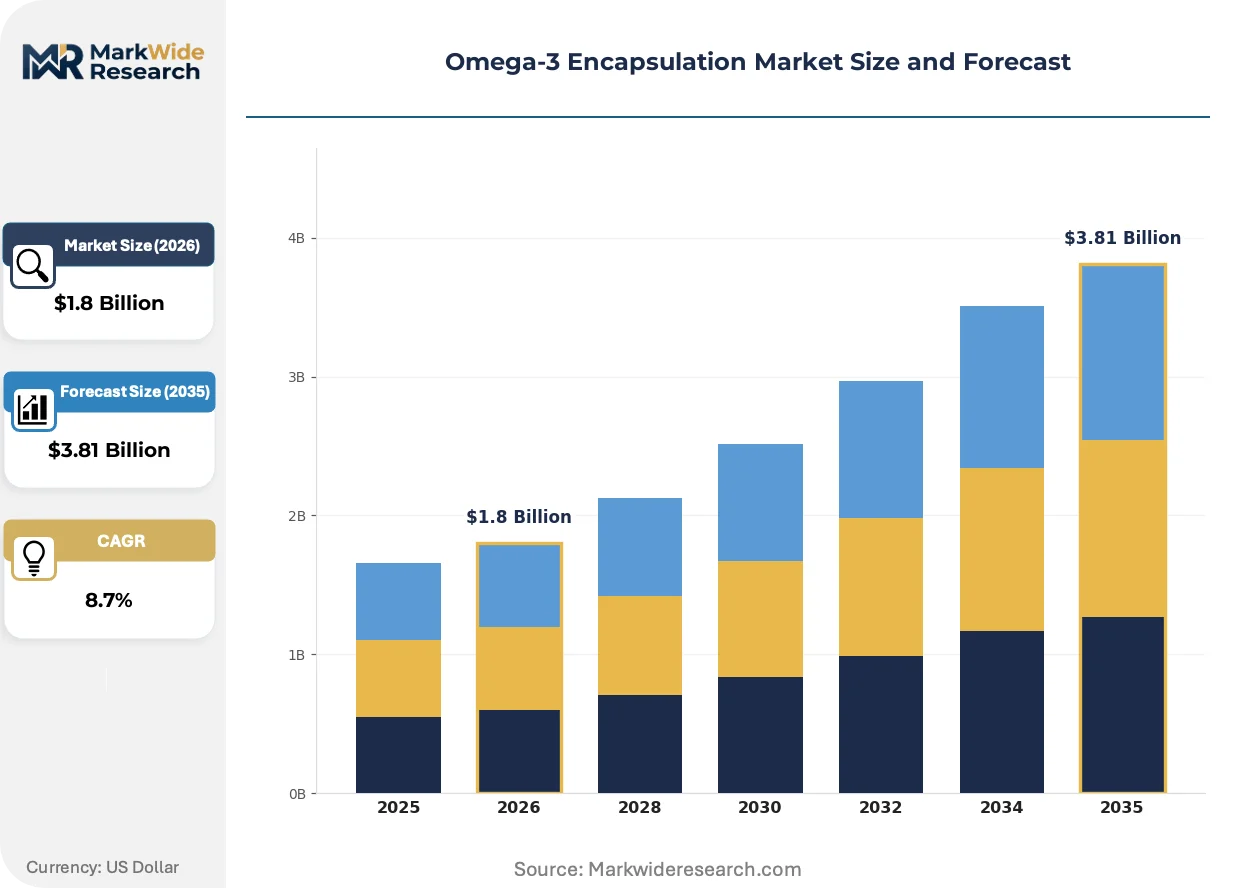
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Gummies, Powders, Liquids Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Pet Nutrition Delivery Mode: Oral, Topical, Injectable, Sublingual Source: Fish Oil, algal Oil, Krill Oil, Others |
| Companies Covered | Croda International Plc, KD Pharma Group, BASF SE, Aker BioMarine, Omega Protein Corporation, DSM Nutritional Products, Glanbia Nutritionals, Novotech Nutrition, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega-3 Encapsulation Market Evolving Landscape
Encapsulation technology trajectories are splintering between precision microfluidic platforms and commodity spray-drying economics, with regulatory chemistry requirements and end-use thermal stability demands determining which pathway captures specific value pools.
Microfluidic shell-formation technology is bifurcating the contract manufacturing landscape. Precision droplet generation enables sub-micron shell thickness control for pharmaceutical-grade ethyl ester protection. Specialty nutraceutical brands adopt these systems for premium positioning despite higher per-unit processing costs. The technology compresses batch-to-batch variability premiums that incumbent spray-drying operators previously captured through scale economies.
EFSA health claim authorization stringency is reshaping permissible marketing vocabulary across EU member states. Structure-function claim boundaries now require clinical endpoint substantiation that exceeds traditional compositional analysis. Infant formula and dietary supplement applications face the tightest evidentiary thresholds. German and French regulators are cross-referencing novel food safety dossiers with health claim applications, extending approval timelines.
Buyer concentration among specialized pet nutrition premixers is compressing supplier qualification cycles. Thermal stability during extrusion has become the primary specification gate, displacing historical prioritization of oxidation resistance alone. Functional food manufacturers now demand encapsulated powders with dual-process tolerance. This specification escalation is most visible in United States contract manufacturing agreements where pet humanization trends drive ingredient premiumization.
Omega-3 Encapsulation Market Segmentation
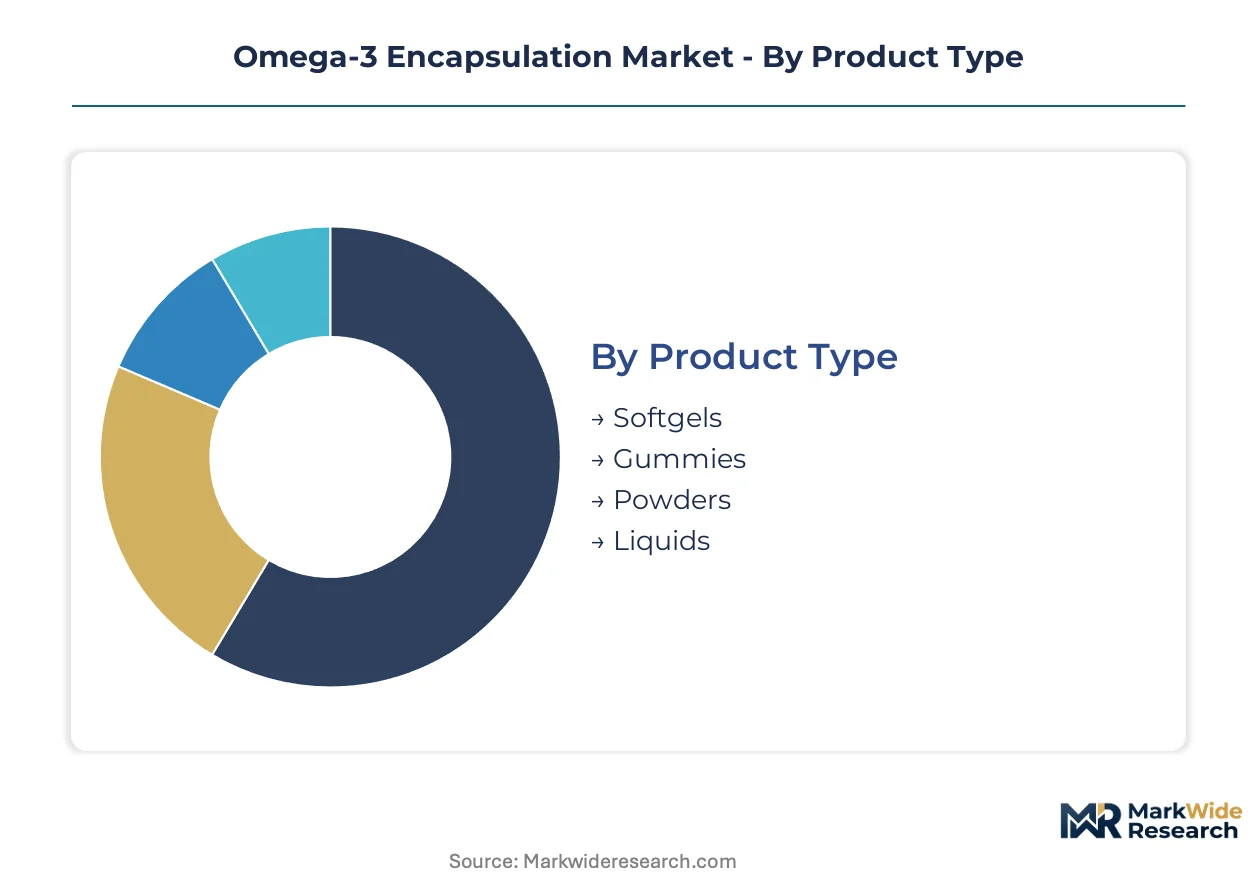
Segmentation in omega-3 encapsulation reveals how formulation chemistry, regulatory pathways, and end-use thermal requirements create distinct competitive arenas. Each dimension carries different margin structures and qualification barriers that determine supplier positioning.
Product Type:
Softgels face substitution pressure from plant-based gummy formats as clean-label preferences reshape adult supplement purchasing, while powder encapsulation resists displacement in pet and food manufacturing channels.
- Softgels:Gelatin or modified starch shells deliver precise EPA-DHA dosing with gastric acid resistance. Demand concentrates in German dietary supplement retail where algal oil lines expand under streamlined EU Novel Food pathways.
- Powders:Spray-dried or microencapsulated formats embed omega-3 in carbohydrate matrices for thermal stability. Pet nutrition premixers in the United States specify these for extrusion tolerance during kibble manufacturing.
- Gummies:Pectin-based chewable matrices target adult and pediatric compliance segments. Water activity control limits shelf life compared to softgel alternatives.
- Liquids:Emulsion concentrates serve functional beverage fortification and clinical nutrition applications. Oxidation sensitivity demands nitrogen-flushed packaging infrastructure.
Softgels anchors the volume base while powders gains share at the steepest rate.
Application:
Cost tier differentiation separates pharmaceutical-grade specifications from commodity nutraceutical positioning, with contract manufacturers capturing margin premiums through analytical validation capabilities.
- Dietary Supplements:Adult and prenatal formulations drive bulk softgel consumption. EFSA health claim stringency in France and Germany extends approval timelines for novel algal entrants.
- Pharmaceuticals:Ethyl ester concentrates meet USP monograph requirements for prescription omega-3 therapies. FDA GRAS notifications and EPA facility registration create qualification moats for new suppliers.
- Functional Foods:Microencapsulated powders withstand UHT processing and baked good thermal profiles. Infant formula fortification in the United States pulls pharmaceutical-grade volumes through specialized production lines.
- Pet Nutrition:Humanization trends elevate ingredient specifications toward human-grade oxidation thresholds. Thermal stability during extrusion determines supplier qualification cycles.
Dietary Supplements commands the revenue base while Pet Nutrition climbs the fastest.
Delivery Mode:
Application setting determines delivery mode selection, with oral formats dominating consumer channels while parenteral routes serve clinical nutrition and therapeutic indications.
- Oral:Softgels, powders, and emulsions cover nutraceutical and food fortification. Bioavailability differentiation between triglyceride, ethyl ester, and phospholipid matrices shapes competitive positioning.
- Injectable:Lipid emulsions for parenteral nutrition require sterile manufacturing and endotoxin control. Hospital and clinical settings drive specification rigor.
- Topical:Cosmetic and dermatological applications leverage omega-3 anti-inflammatory positioning. Permeation enhancement technologies determine efficacy claims.
- Sublingual:Rapid absorption formats target compliance-sensitive segments. Limited commercial penetration compared to established oral routes.
Oral anchors volume while Injectable captures the highest value per unit.
Source:
Supply concentration and regulatory approval velocity separate marine-derived from fermentation-based alternatives, with sustainability credentials increasingly influencing procurement decisions.
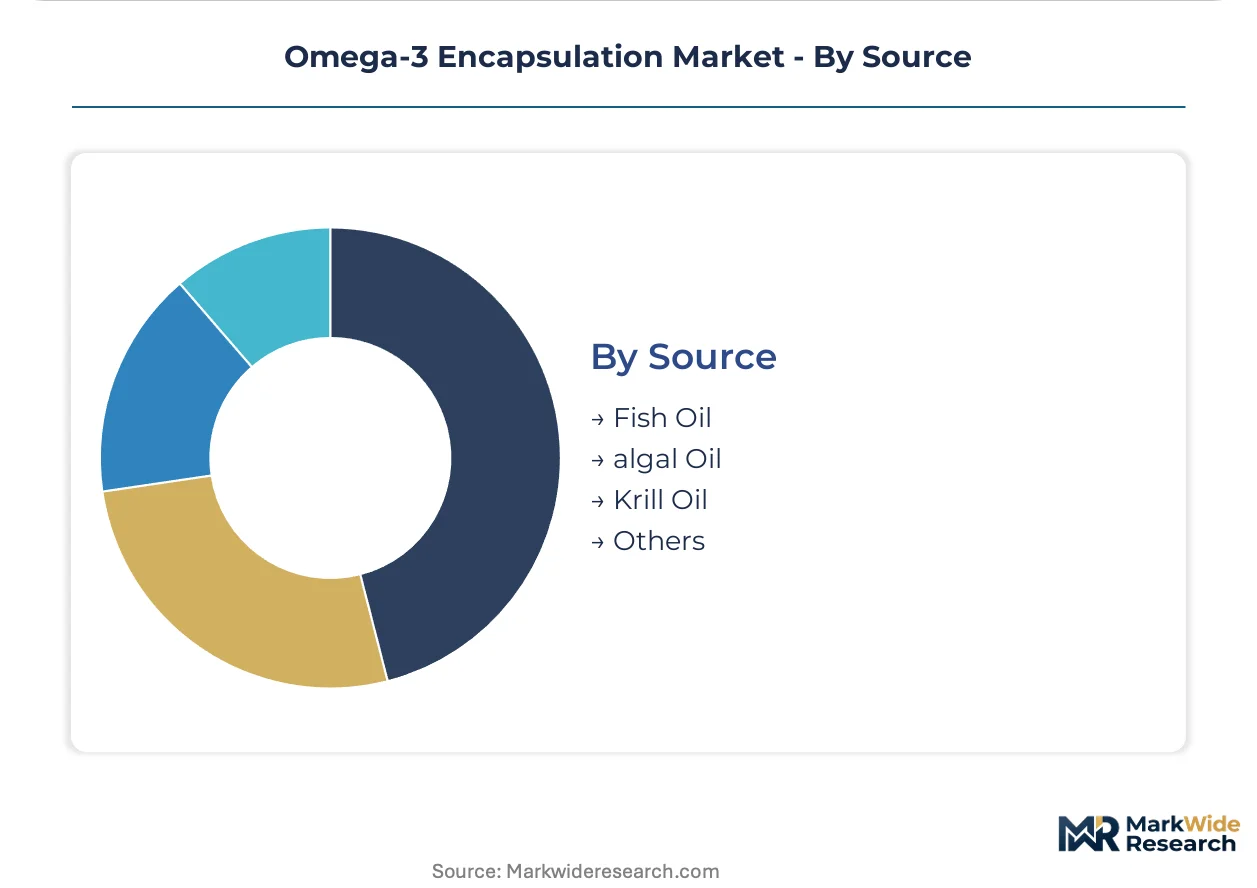
- Fish Oil:Anchovy and sardine fisheries in Peru and Chile supply bulk triglyceride concentrates. Oxidation sensitivity demands nitrogen-blanketed supply chains that inflate working capital.
- Algal Oil:Fermentation-derived DHA and EPA bypass marine ecosystem dependencies. German brands expand softgel portfolios as EU Novel Food streamlines approval pathways.
- Krill Oil:Antarctic catch quotas constrain phospholipid matrix supply. Aker BioMarine's specialized onboard processing and patent estate control bioavailability positioning.
- Others:Calamari and genetically modified land plant sources occupy niche positions. Limited scale and regulatory uncertainty restrict mainstream adoption.
Fish Oil retains volume leadership while Algal Oil expands most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States absorb pharmaceutical-grade premiums with minimal price elasticity, while German dietary supplement channels and Chinese functional food manufacturers negotiate aggressively on algal oil sourcing contracts.
United States
Infant formula fortification and pet nutrition humanization drive encapsulated EPA-DHA demand through specialized contract manufacturers. FDA GRAS notifications and EPA facility registration create qualification moats that protect incumbent suppliers. Boston and New Jersey pharmaceutical corridors concentrate ethyl ester production for prescription omega-3 therapies.
Germany
Dietary supplement brands expand algal oil softgel portfolios as streamlined EU Novel Food pathways accelerate approval timelines. EFSA health claim stringency extends marketing authorization processes for novel entrants. Frankfurt and Hamburg logistics hubs coordinate cross-border distribution into French and Benelux retail channels.
China
Functional food manufacturers specify microencapsulated powders for baked goods and UHT beverage fortification at negotiated contract prices. NMPA registration requirements and GB standards for novel food ingredients shape import qualification timelines. Yangtze River Delta fermentation clusters scale algal DHA production for domestic softgel consumption.
Japan
Aging demographics sustain pharmaceutical-grade omega-3 demand for cardiovascular and cognitive health applications with limited price sensitivity. PMDA manufacturing standards and METI functional food labeling guidelines determine market access. Kansai region nutraceutical fabricators specialize in phospholipid matrix encapsulation for premium positioning.
Brazil
ANVISA novel food regulations and import tariff structures constrain algal oil market penetration versus established fish oil concentrates. São Paulo dietary supplement distributors consolidate procurement volumes to extract supplier concessions. Southeast region contract manufacturers invest in spray-drying capacity for regional pet nutrition premix supply.
Omega-3 Encapsulation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision microfluidic specialists commanding premium positioning against commodity spray-drying operators. The vendor base concentrates around three strategic tiers: multinational chemical conglomerates with captive lipid supply, specialized marine extraction firms with Antarctic quota access, and regional contract manufacturers with analytical validation capabilities. Dominant competitive moves include backward integration into algal fermentation assets and strategic partnerships with infant formula brands for pharmaceutical-grade qualification.
Within the multinational chemical tier, BASF SE and DSM Nutritional Products exemplify scale-driven positioning through integrated supply chains. Croda International Plc and Aker BioMarine occupy specialized niches where lipid chemistry heritage and krill phospholipid matrix patents respectively anchor premium market access. These named entities represent archetypal strategies rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Croda International Plc |
| KD Pharma Group |
| BASF SE |
| Aker BioMarine |
| Omega Protein Corporation |
| DSM Nutritional Products |
| Glanbia Nutritionals |
| Novotech Nutrition |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
FDA GRAS notification requirements and EPA facility registration standards gate both supplier qualification and price differentiation simultaneously, compressing margins for unvalidated entrants while allowing incumbent contract manufacturers to sustain pharmaceutical-grade premiums through analytical method validation moats.
Pricing Analysis
After-sales service contracts for nitrogen-blanketed storage and stability monitoring drive lifetime value capture for pharmaceutical-grade ethyl ester suppliers. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and commodity fish oil concentrates separates specification tiers. Cost compression in commodity spray-dried powders is intensifying because German dietary supplement brands negotiate aggressively on algal oil sourcing. Pet nutrition premixers in the United States exhibit the lowest price sensitivity due to thermal stability specification rigor.
Supply Chain Analysis
Container availability constraints on the Peru-to-Rotterdam fish oil concentrate trade lane inflate inbound logistics costs for European softgel manufacturers. Raw material supply concentrates in Peru, Chile, and China for anchovy fisheries and algal fermentation respectively. Nitrogen-blanketed tanker fleets and gelatin shell material certification draw from bovine and porcine processing networks in Brazil and Argentina. Single-source vulnerability in Antarctic krill quota allocations threatens phospholipid matrix supply security. Distribution runs through specialized contract manufacturers with pharmaceutical-grade production lines in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The omega-3 encapsulation market is in a cyclical recovery phase, with infant formula fortification demand and pet nutrition humanization serving as the primary cyclical drivers resetting utilization rates across contract manufacturing networks.
For Market Incumbents: Fortify analytical validation capabilities to capture pharmacopeial EPA-DHA ratio standardization premiums before specification windows close. Backward integration into algal fermentation assets in Germany and China secures supply continuity against Antarctic krill quota volatility. Incumbents must also deepen channel control through dedicated pharmaceutical-grade production line partnerships with infant formula brands. For New Entrants and Emerging Players: Anchor in modular microfluidic shell-formation technology to bypass spray-drying scale disadvantages in precision encapsulation segments. The most penetrable white space sits in pet nutrition thermal stability specifications where incumbent qualification cycles lag demand growth. A direct-to-contract-manufacturer go-to-market angle bypasses retail brand concentration barriers. For Investors and Strategic Acquirers: EFSA health claim authorization stringency reshapes the acquisition landscape toward targets with clinical endpoint substantiation capabilities and EU regulatory dossier expertise. Long-term viability favors contract manufacturers with dual pharmaceutical-nutraceutical qualification infrastructure. The signal to watch is FDA enforcement discretion trajectories on structure-function claim boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algal Fermentation | BASF SE's captive supply of fermentation-derived DHA bypasses marine ecosystem dependencies and Antarctic quota constraints. |
| Pharmaceutical-Grade Production Line Expansion | Specialized contract manufacturers in New Jersey capture infant formula fortification volumes through USP monograph compliance. |
| Microfluidic Precision Encapsulation Adoption | Modular shell-formation systems enable sub-micron thickness control for ethyl ester protection at bench-scale economics. |
| EU Novel Food Dossier Investment | German dietary supplement brands accelerate algal oil softgel approval timelines through streamlined regulatory pathways. |
| Nitrogen-Blanketed Supply Chain Certification | Croda International Plc sustains premium positioning through oxidation-controlled logistics infrastructure for pharmaceutical-grade concentrates. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists, contract manufacturing procurement leads, pet nutrition premix specification managers, and dietary supplement brand managers and refined through secondary validation against FDA GRAS notification databases, EFSA health claim authorization registers, EPA facility registration records, and EU Novel Food approval tracking systems. Bottom-up volume triangulation across product type, application, delivery mode, and source segmentation was cross-checked against top-down market sizing from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each modeled segment. The analytical framework incorporates pharmaceutical-grade specification tiers, nutraceutical-grade positioning, and commodity-grade fish oil concentrates alongside regional regulatory cluster differentiation. CAGRs were derived from segment-level growth rate aggregation weighted by baseline revenue contribution. Industry-specific forecast inputs include Antarctic krill catch quota trajectories and evolving pharmacopeial EPA-DHA ratio monograph specifications.
Underlying assumptions cover sustained infant formula fortification demand, EU Novel Food pathway streamlining continuity, and pet nutrition thermal stability specification escalation, with deviation risk concentrated in FDA enforcement discretion shifts and Antarctic catch quota policy revisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Microencapsulated Oil Market
Ingredients
Citrus Based Dietary Fibers Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Potato Starch Market
Ingredients
Bouillon Market
Ingredients
Potato Flour Market
Ingredients
Europe Fruit and Vegetable Ingredients Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Hydrogenated Starch Market
Ingredients
Oat Fiber Market
Ingredients
Hops Derivative Market
Ingredients
Asparagus Extract Market
Ingredients
Hemp Seed Peptide Market
Ingredients
GCC Bakery Ingredients Market