
 Global Hydrolyzed Wheat Protein Market | 2026-2036
Global Hydrolyzed Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrolyzed Wheat Protein Market Foresight
Market Dynamics
Capital-intensity divergence between integrated millers and specialty ingredient houses is bifurcating the competitive landscape. Kerry Group plc leverages captive wheat processing infrastructure to secure cost-advantaged feedstock for hydrolysate production. Manildra Group anchors its position through backward integration into Australian grain origination and flour milling. Roquette Frères differentiates via pea-wheat protein hybrid R&D platforms that extend functionality beyond conventional hydrolysates.
Hydrolyzed wheat protein denotes enzymatically or acid-cleaved gluten fractions yielding peptides with molecular weights typically below 10 kDa, valued for film-forming and moisture-binding properties in topical and nutritional applications. Powdered protein commands the largest volume share due to shelf stability and ease of formulation blending, while liquid hydrolysate represents the fastest-expanding format as cosmetic labs adopt cold-process manufacturing. Emulsified protein variants capture disproportionate margin pools by serving premium skin care formulations requiring dual solubility behavior.
FDA cosmetic ingredient guidance, REACH registration requirements under ECHA, and EFSA novel food assessments collectively elevate compliance costs for new market entrants. These frameworks compel suppliers to maintain comprehensive toxicological dossiers and substantiate hypoallergenic claims through clinical testing protocols. Stakeholders must monitor evolving clean-label certification schemes and biotechnology-derived alternatives that could displace conventional enzymatic hydrolysis routes.
Market Dynamics
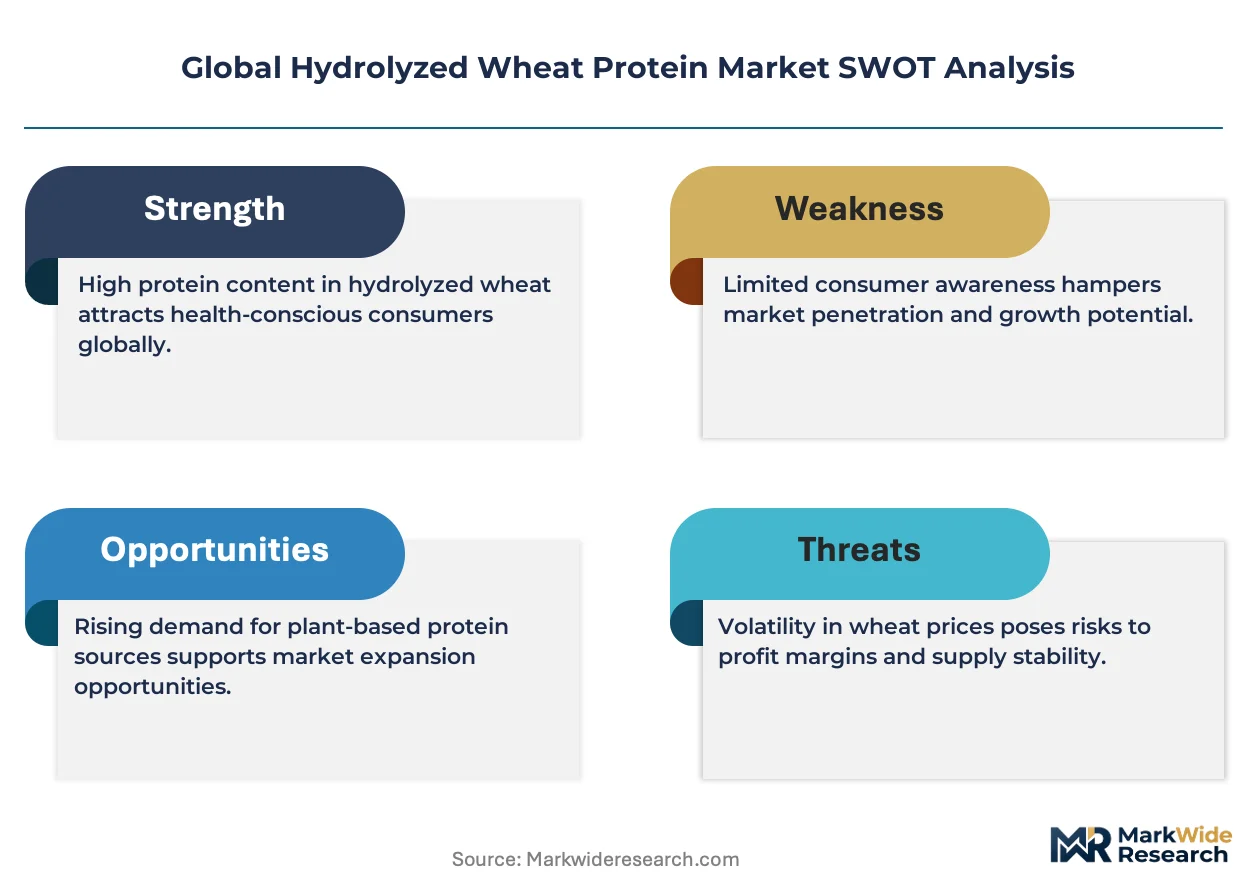
Enzymatic hydrolysis technology is fragmenting the supplier base as specialty biotech firms challenge integrated grain processors for premium cosmetic-grade hydrolysate contracts.
Growth Catalysts
- REACH Registration Thresholds:ECHA's cumulative substance evaluation protocols are accelerating consolidation among compliant European hydrolysate processors, concentrating procurement relationships with verified dossier holders.
- Cold-Process Cosmetic Manufacturing:Liquid hydrolysate formats are capturing formulation share as German and French cosmetic labs abandon heat-dependent powder reconstitution workflows.
- Film-Forming Functional Demand:Skin care brands in South Korea and Japan are specifying low-molecular-weight wheat peptides for barrier-repair serums, pulling volume from collagen alternatives.
Market Restraints
- Gluten Contamination Liability:Cross-contact risks during shared-facility production impose insurance and segregation costs that disadvantage smaller toll manufacturers.
- Australian Wheat Belt Concentration:Drought cycles in New South Wales and Victoria create origination volatility for processors dependent on Manildra Group's grain supply orbit.
- Pea Protein Substitution:Roquette Frères' hybrid R&D platforms and pure pea isolates are capturing clean-label positioning in mass-market hair care, compressing wheat hydrolysate volume in price-sensitive tiers.
Strategic Opportunities
- Brazilian ANVISA Cosmetic Pathway:Underpenetrated South American personal care markets offer first-mover positioning for suppliers completing novel ingredient notifications ahead of domestic competitor scale-up.
- Biotechnology-Derived Precision Hydrolysis:CRISPR-engineered enzyme cocktails from Danish and Dutch fermentation houses are enabling peptide-length specificity beyond conventional acid hydrolysis limits.
- Direct-to-Formulator E-Commerce:Alibaba's 1688 platform and specialty ingredient marketplaces are compressing distributor layers for mid-volume cosmetic compounders in China's Pearl River Delta.
Industry Challenges
- Clinical Validation Timeline Compression:EFSA novel food assessments and hypoallergenic claim substantiation require 18-24 month toxicological study cycles that strain R&D budgets.
- Enzyme Supply Security:Protease procurement from Novozymes and DuPont Nutrition & Biosciences faces allocation pressure from competing pharmaceutical applications.
- Legacy ERP Integration:Batch record digitization for FDA cosmetic facility registration demands capital outlays that delay smaller processors' compliance readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrolyzed Wheat Protein Market |
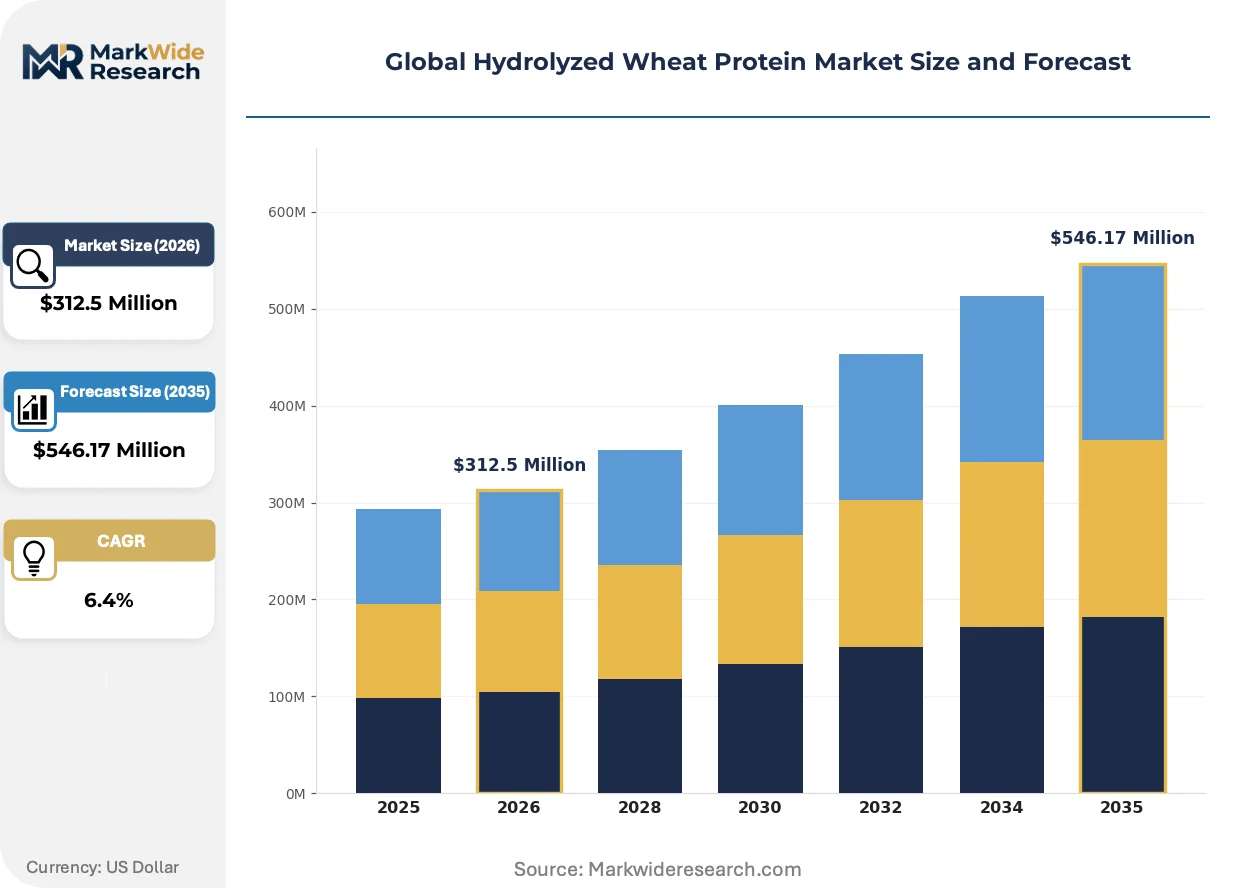
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Hydrolysate, Powdered Protein, Fluid Extract, Emulsified Protein Application: Hair Care Products, Skin Care Formulations, Nutritional Supplements, Animal Feed End User Industry: Personal Care Manufacturers, Dietary Food Producers, Pet Nutrition Companies, Cosmetic Labs Packaging Type: Plastic Containers, Glass Bottles, Sachets, Bulk Drums, Tubs |
| Companies Covered | Kerry Group plc, Manildra Group, Archer Daniels Midland Company, A. Costantino & C., The Scoular Company, Roquette Frères, MGP Ingredients, Inc., Xi'an Sheerherb Biological Technology Co., Ltd., Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrolyzed Wheat Protein Market Shifts & Advancements
Precision fermentation and enzyme engineering are reconfiguring hydrolysate quality hierarchies, while regulatory data requirements and procurement centralization reshape how suppliers compete for formulation contracts.
Microbially produced wheat peptides via precision fermentation are supplanting conventional enzymatic hydrolysis for ultra-low-molecular-weight specifications. Premium skin care houses in Switzerland and South Korea are qualifying these biotech-derived inputs for next-generation barrier-repair lines. The technology is compressing margin pools for acid-hydrolysis commodity suppliers unable to fund bioreactor infrastructure.
EFSA's tightening novel food assessment protocols are extending approval timelines for hydrolysate suppliers seeking nutritional application expansion. The industrial consequence is a bifurcation between cosmetic-dedicated processors and dual-use facilities carrying heavier dossier maintenance burdens. German and French suppliers with established EFSA track records are capturing nutritional contract share from newer entrants facing 24-36 month backlog queues.
Compounders are consolidating supplier panels around vertically integrated grain processors with captive enzyme production and certified gluten-segregation infrastructure. Mid-tier cosmetic manufacturers in Italy and Spain are abandoning spot-market hydrolysate purchasing in favor of annual framework agreements with traceability guarantees. The shift is most visible in premium hair care, where clean-label certification requirements now mandate batch-level allergen testing documentation.
Global Hydrolyzed Wheat Protein Market Segmentation
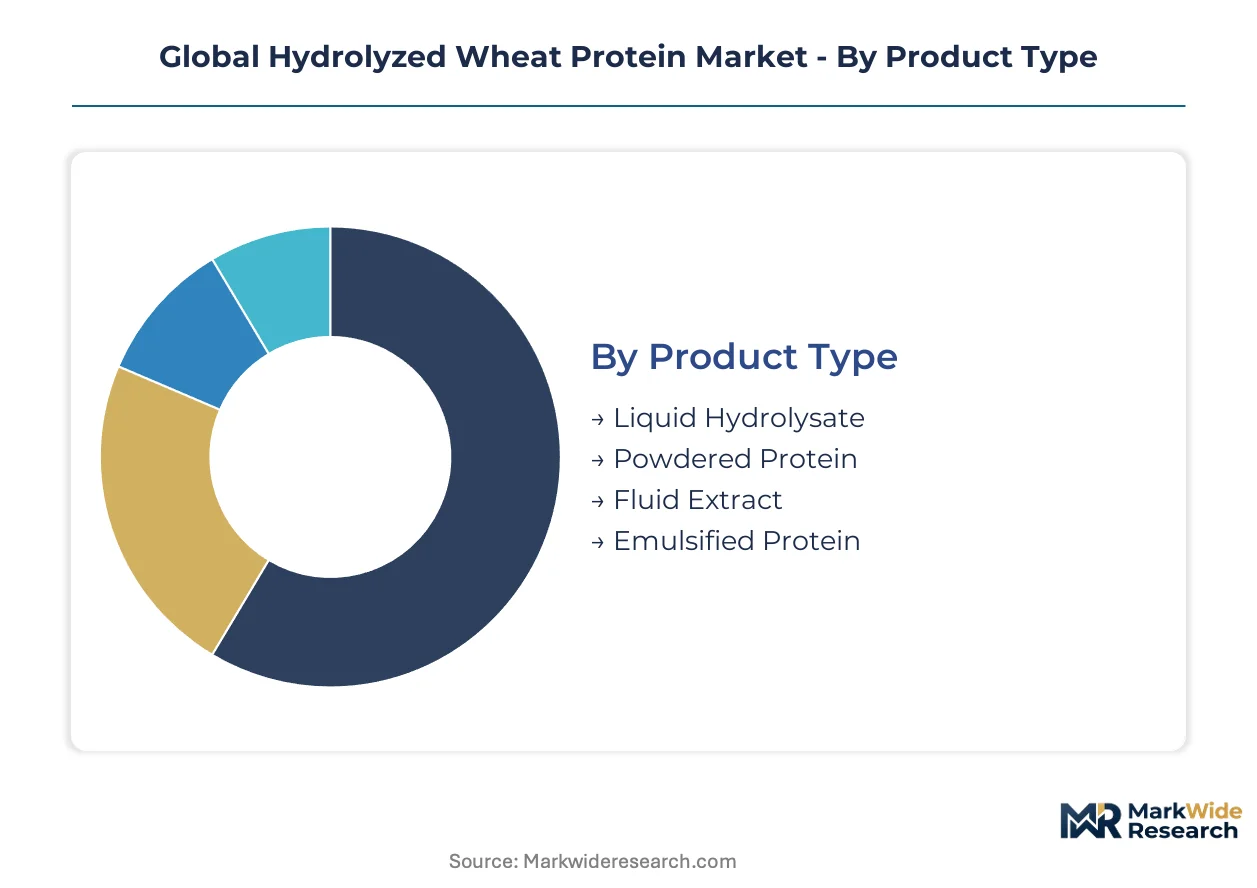
Segmentation in hydrolyzed wheat protein markets reveals how formulation requirements, regulatory pathways, and supply chain configurations create distinct competitive arenas. Each dimension exposes different margin structures, customer loyalty patterns, and barriers to entry that suppliers must navigate.
Product Type:
Domestic production concentrates powdered formats for established personal care houses, while liquid hydrolysate flows disproportionately to export-oriented cosmetic labs in South Korea and Japan seeking cold-process compatibility.
- Liquid Hydrolysate:Enzymatically cleaved peptides in aqueous suspension, typically 20-30% solids content, enable ambient-temperature formulation workflows. Demand clusters in German and French cosmetic labs abandoning heat-dependent powder reconstitution for sensitive active preservation. Cold-process manufacturing mandates are accelerating qualification timelines for sterile-filtered liquid grades.
- Powdered Protein:Spray-dried hydrolysate with sub-10 kDa molecular weight fractions dominates shelf-stable formulation portfolios. Italian and Spanish compounders source heavily from domestic toll processors for hair mask and conditioner applications. Powdered formats retain procurement preference where logistics infrastructure favors dry bulk handling.
- Fluid Extract:Concentrated aqueous preparations with higher peptide diversity serve niche nutraceutical encapsulation requirements.
- Emulsified Protein:Lipid-complexed variants command premium positioning in dual-phase skin care formulations requiring simultaneous water and oil solubility.
Powdered protein commands the established base. The steepest expansion runs through liquid hydrolysate.
Application:
Cost-tier differentiation separates premium skin care peptide specifications from commodity-grade nutritional applications, with hair care occupying the intermediate value band.
- Hair Care Products:Film-forming wheat peptides in shampoos and conditioners deliver cuticle-sealing functionality previously served by silicones. South Korean brands specify low-molecular-weight fractions for damage-repair positioning. Clean-label substitution pressures are displacing synthetic polymers in mass-market formulations.
- Skin Care Formulations:Barrier-repair serums and moisturizers leverage wheat peptide humectant properties for atopic skin positioning. Swiss and Japanese premium houses drive molecular-weight specificity requirements below 3 kDa for dermal penetration claims. Clinical substantiation burdens concentrate demand among dossier-capable suppliers.
- Nutritional Supplements:EFSA novel food assessments extend approval timelines for hydrolysate suppliers targeting sports nutrition and elderly protein fortification.
- Animal Feed:Palatability-enhancing applications in pet food manufacturing compete on cost against soy and pea protein hydrolysates.
Hair care applications anchor volume throughput. Skin care formulations generate the fastest margin expansion.
End User Industry:
Customer-type stratification separates multinational personal care conglomerates with dedicated supplier development programs from mid-tier compounders purchasing through distributor channels.
- Personal Care Manufacturers:Integrated formulation houses in Germany and France negotiate annual framework agreements with traceability documentation for clean-label certification. Procurement centralization is compressing supplier panels toward vertically integrated grain processors with captive enzyme production.
- Cosmetic Labs:Independent R&D facilities in China's Pearl River Delta source through Alibaba's 1688 platform, bypassing traditional distributor layers for mid-volume requirements.
- Dietary Food Producers:Nutritional application expansion faces EFSA assessment backlogs that disadvantage newer market entrants.
- Pet Nutrition Companies:Palatant applications prioritize cost position over molecular-weight specificity, sourcing from commodity hydrolysate tiers.
Personal care manufacturers concentrate procurement relationships. Cosmetic labs are gaining share fastest through platform-based purchasing.
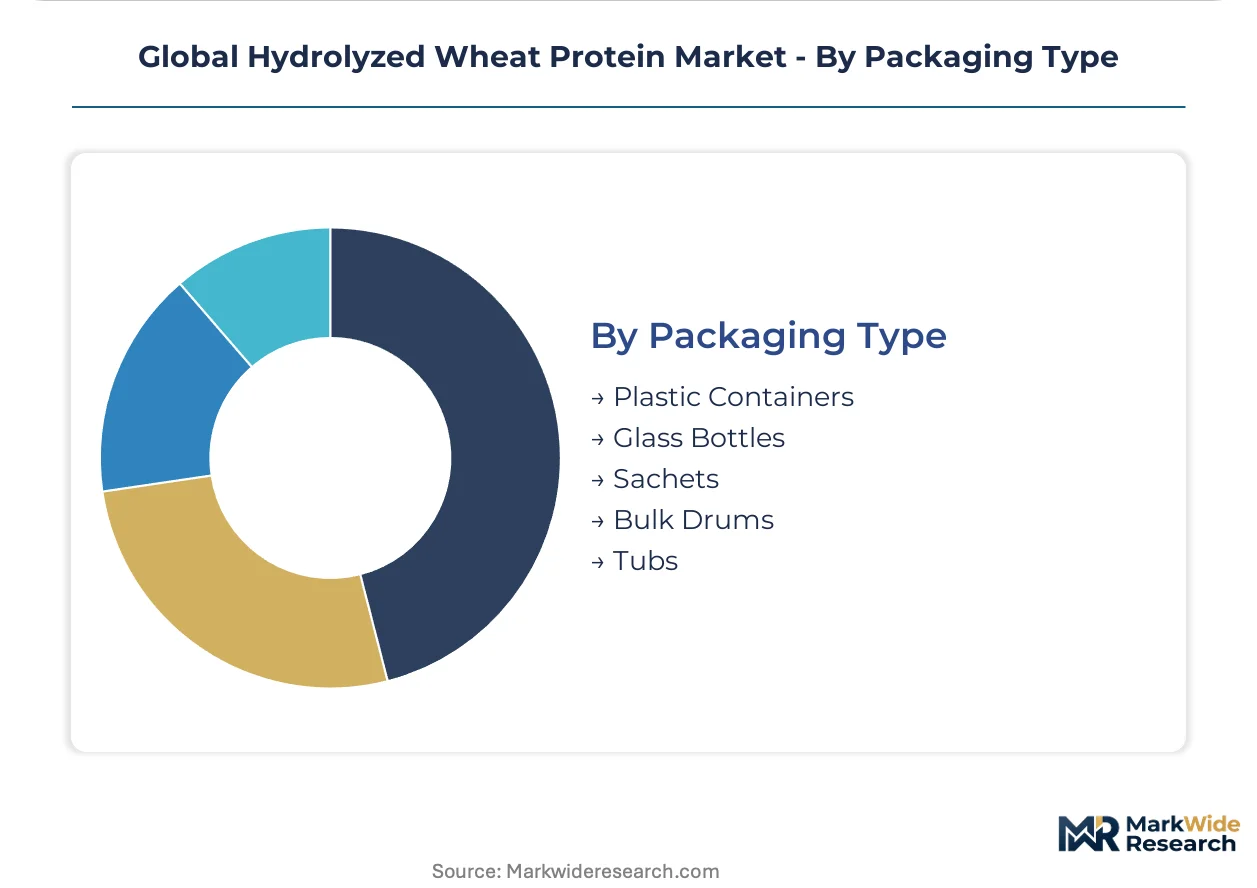
Packaging Type:
Supply concentration in Australian and German processing clusters dictates regional packaging preferences, with bulk formats dominating origin-proximate procurement and unitized packaging serving distant formulation sites.
- Bulk Drums:200-liter steel and HDPE containers serve high-volume compounders with dedicated formulation suites and material handling infrastructure. German cosmetic manufacturers with integrated milling supply chains favor drum formats for powder hydrolysate receiving.
- Sachets:Single-use aluminum-laminate pouches enable sample-scale qualification and travel-size retail positioning. South Korean skin care brands specify sachet formats for barrier-repair serum trial distribution.
- Plastic Containers:HDPE bottles with pump dispensers serve mid-volume liquid hydrolysate requirements in salon-professional hair care.
- Glass Bottles:Amber and clear glass formats support premium positioning for pharmaceutical-grade peptide specifications.
- Tubs:Wide-mouth polypropylene containers facilitate powder scooping in nutritional supplement retail channels.
Bulk drums command the established base. Sachet formats are climbing the fastest as trial-size distribution expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German processors command premium pricing for REACH-compliant hydrolysates while Australian suppliers absorb origination volatility from drought-exposed wheat belts. This asymmetry reshapes procurement geography as cosmetic formulators diversify supply sources.
Germany
Cosmetic labs in Hamburg and Düsseldorf drive demand for cold-process liquid hydrolysates with molecular-weight specifications below 3 kDa. ECHA's cumulative substance evaluation protocols favor incumbent dossier holders, accelerating procurement consolidation around established processors. The Ruhr industrial corridor hosts specialized enzyme houses supplying protease cocktails to domestic hydrolysate manufacturers.
United States
FDA cosmetic ingredient guidance elevates toxicological documentation burdens for hydrolysate suppliers targeting premium skin care brands. Personal care manufacturers in New Jersey and California negotiate annual framework agreements with traceability guarantees for clean-label certification. The Midwest grain belt supplies captive wheat processing infrastructure to integrated ingredient houses.
China
Cosmetic compounders in the Pearl River Delta source mid-volume hydrolysate requirements through Alibaba's 1688 platform, bypassing traditional distributor layers. SAMR's tightening cosmetic ingredient standards compel suppliers to maintain comprehensive safety dossiers. Zhengzhou and Xi'an host biological technology firms specializing in plant-derived peptide production.
South Korea
Premium skin care houses in Seoul specify ultra-low-molecular-weight wheat peptides for barrier-repair serums, pulling volume from collagen alternatives. MFDS cosmetic ingredient notification requirements extend qualification timelines for new hydrolysate entrants. The Songdo biocluster attracts precision fermentation startups developing microbially produced peptide alternatives.
Brazil
Underpenetrated personal care markets offer first-mover positioning for suppliers completing ANVISA novel ingredient notifications ahead of domestic competitor scale-up. Hair care brands in São Paulo specify film-forming wheat peptides for silicone-free positioning. The São Paulo state industrial corridor hosts toll processors serving Latin American cosmetic manufacturers.
Global Hydrolyzed Wheat Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Specialty biotech firms with precision fermentation capabilities capture premium cosmetic-grade contracts, while integrated grain processors leverage captive wheat origination for cost-advantaged commodity supply. Three archetypes dominate: vertically integrated millers with in-house enzyme production, precision fermentation specialists, and regional toll manufacturers. Competitive moves concentrate on backward integration into grain supply and bioreactor capacity expansion for peptide-length specificity.
Among integrated processors, Kerry Group plc and Manildra Group exemplify the captive-feedstock archetype, securing cost-advantaged wheat supply through upstream milling infrastructure. Roquette Frères occupies a hybrid position, bridging grain processing and biotechnology through pea-wheat protein R&D platforms. These three companies represent the dominant competitive anchors, with Kerry and Manildra emphasizing scale-driven supply security and Roquette pursuing functionality differentiation through alternative protein blending.
| Leading Market Players |
|---|
| Kerry Group plc |
| Manildra Group |
| Archer Daniels Midland Company |
| A. Costantino & C. |
| The Scoular Company |
| Roquette Frères |
| MGP Ingredients, Inc. |
| Xi'an Sheerherb Biological Technology Co., Ltd. |
| Cargill, Incorporated |
| Others |
Supply & Pricing Matrix
REACH registration dossiers gate both supplier qualification and price stratification, forcing cosmetic compounders to pay premiums for ECHA-verified hydrolysates while commodity-grade processors absorb margin compression from excluded buyer pools. This regulatory filtration simultaneously concentrates procurement relationships and widens the spread between certified and uncertified supply tiers.
Pricing Analysis
Configured-to-order pricing for peptide-length-specific hydrolysates commands spreads exceeding standard powder grades, with molecular-weight fractions below 3 kDa carrying certification premiums from Swiss and South Korean skin care houses. Three-tier pricing structure across premium, standard, and economy levels reflects gluten-segregation infrastructure, cold-process compatibility, and clinical dossier depth. Cost compression in commodity powder tiers is intensifying because pea protein hybrids from Roquette Frères capture clean-label positioning at lower price points. Mid-tier Italian and Spanish compounders exhibit highest price sensitivity, while German cosmetic labs prioritize specification adherence over unit cost.
Supply Chain Analysis
Australia and Germany anchor wheat hydrolysate production, with New South Wales grain origination feeding Manildra Group's captive milling infrastructure and Ruhr corridor processors leveraging domestic enzyme supply chains. Raw material flows draw from drought-exposed Australian wheat belts, Novozymes protease allocations, and specialty fermentation inputs from Danish biotech houses. Single-source vulnerability concentrates in enzyme procurement, where pharmaceutical demand competes for limited protease capacity. Distribution runs through annual framework agreements for high-volume personal care manufacturers, with Alibaba's 1688 platform capturing mid-volume cosmetic lab spot purchasing in China's Pearl River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from precision fermentation-derived peptides that bypass conventional enzymatic hydrolysis entirely, requiring defensive repositioning around bioreactor capabilities and clinical validation assets.
For Market Incumbents: Fortify dossier depth through EFSA novel food track record accumulation and captive enzyme production capacity in the Ruhr corridor. Precision fermentation startups in South Korea's Songdo biocluster threaten premium contract capture, demanding accelerated bioreactor partnerships or acquisition screening. Backward integration into certified gluten-segregation infrastructure protects margin pools from toll manufacturer competition.
For New Entrants and Emerging Players: Anchor in Brazil's ANVISA notification pathway, where first-mover positioning ahead of domestic scale-up offers protected pricing windows for silicone-free hair care formulations. Underpenetrated South American personal care markets present the most penetrable geography, with São Paulo-based toll processors serving as distribution anchors. Direct-to-formulator e-commerce through specialty ingredient marketplaces provides the lowest-friction go-to-market angle for mid-volume qualification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation specialists holding CRISPR-engineered enzyme platforms but lacking ECHA dossier completion. Long-term viability hinges on regulatory moat durability and biotech-derived peptide substitution timelines. Watch EFSA approval velocity for novel food applications as the inflection signal distinguishing cosmetic-dedicated from dual-use facility valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Bioreactor infrastructure enables peptide-length specificity beyond acid hydrolysis limits for Swiss barrier-repair lines. |
| EFSA Novel Food Dossier Completion | Regulatory track records compress qualification timelines for nutritional application expansion against backlog queues. |
| Captive Enzyme Production Integration | In-house protease supply secures allocation priority against competing pharmaceutical demand from Novozymes. |
| Direct-to-Formulator E-Commerce Launch | Alibaba 1688 platform access bypasses distributor layers for Pearl River Delta cosmetic lab procurement. |
| Gluten-Segregation Certification Investment | Batch-level allergen testing documentation satisfies clean-label mandates from Italian and Spanish compounders. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hydrolysate procurement managers at German and French personal care manufacturers, cosmetic lab formulators in South Korea, and grain processing operations directors; alongside secondary validation through ECHA registration databases, EFSA novel food assessment records, and customs trade flows for wheat protein hydrolysate categories. Primary fieldwork captured formulation specification evolution, supplier panel consolidation patterns, and enzyme procurement allocation pressures. Secondary sources included REACH dossier filings, ANVISA cosmetic ingredient notifications, and Alibaba 1688 platform transaction data. Bottom-up volume builds from processor capacity utilization and top-down demand estimates from personal care formulation trends were triangulated for convergence.
Across the analysis window, the forecasting framework modeled hydrolysate demand through product type segmentation, application tier stratification, and regional regulatory cluster differentiation. CAGRs were derived from elasticity-adjusted volume projections incorporating substitution coefficients for pea protein alternatives and biotechnology-derived peptide penetration rates. Industry-specific inputs captured cold-process manufacturing adoption velocity in German cosmetic labs and SAMR cosmetic ingredient standard tightening trajectories in China.
Material uncertainties — drought recurrence in Australian wheat belts, protease supply allocation shocks from pharmaceutical demand spikes, and CRISPR enzyme platform regulatory acceptance timelines — sit outside the modeled envelope. Forecasts reflect assumptions about EFSA assessment velocity and clean-label certification scheme evolution. Recalibration cycles align with material shifts in REACH substance evaluation protocols and precision fermentation scale-up milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Free Premix Market
Ingredients
Ground-Nut Oil Market
Ingredients
Rye Bran Beta-Glucan Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
Cocoa Fiber Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Kilned Malt Market
Ingredients
Global Egg White Peptide Market
Ingredients
High Oleic Oil Market
Ingredients
Mediterranean Women’s Cycle Support Ingredient Systems Market
Ingredients
Bromelain Ingredient Market
Ingredients
Mustard Oil Market
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Pea Protein Ingredients Industry Status and Prospects Professional Market
Ingredients
Italy Soy Protein Market
Ingredients
United States Wheat Protein Market