
 Encapsulated Ingredients Market | 2026-2036
Encapsulated Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Encapsulated Ingredients Market Analytics
Ingredient delivery service revenue is fragmenting between standalone encapsulation houses and integrated flavor houses. BASF SE leverages its polymer science heritage to sustain captive supply of shell materials for pharmaceutical-grade microcapsules. Kerry Group plc anchors its position through backward integration into dairy-derived carrier systems. DSM-Firmenich AG competes by dominating the vitamins segment with fermentation-to-encapsulation control.
Encapsulated ingredients are active compounds sealed within protective matrices—typically 1-1000 micron particles of gelatin, gum arabic, or modified starch—to shield core materials from oxidation, moisture, and gastric degradation until targeted release. The primary commercial purpose centers on extending shelf stability and enabling controlled delivery in functional foods and extended-release pharmaceuticals. Probiotics command premium positioning due to viability sensitivity demanding cryoprotectant-enhanced matrices, while spray drying occupies volume leadership through capital efficiency and scale. Liposome technology leads growth trajectory in cosmetics and injectable pharmaceuticals where bilayer specificity enables transdermal and intracellular targeting.
FDA GRAS determinations and EFSA Novel Food opinions shape market access timelines for new encapsulation formats and carrier substances. REACH compliance in Europe and EPA environmental release assessments for industrial enzyme encapsulates constrain material choices and manufacturing site locations. Stakeholders must monitor evolving pharmacopeial monographs for dissolution testing standards that will separate validated suppliers from commodity encapsulation houses.
Market Dynamics
Precision encapsulation scale-up in Germany is compressing lead times for pharmaceutical-grade microcapsules, forcing standalone encapsulation houses to consolidate or specialize in niche cryoprotectant matrices for probiotics.
Growth Catalysts
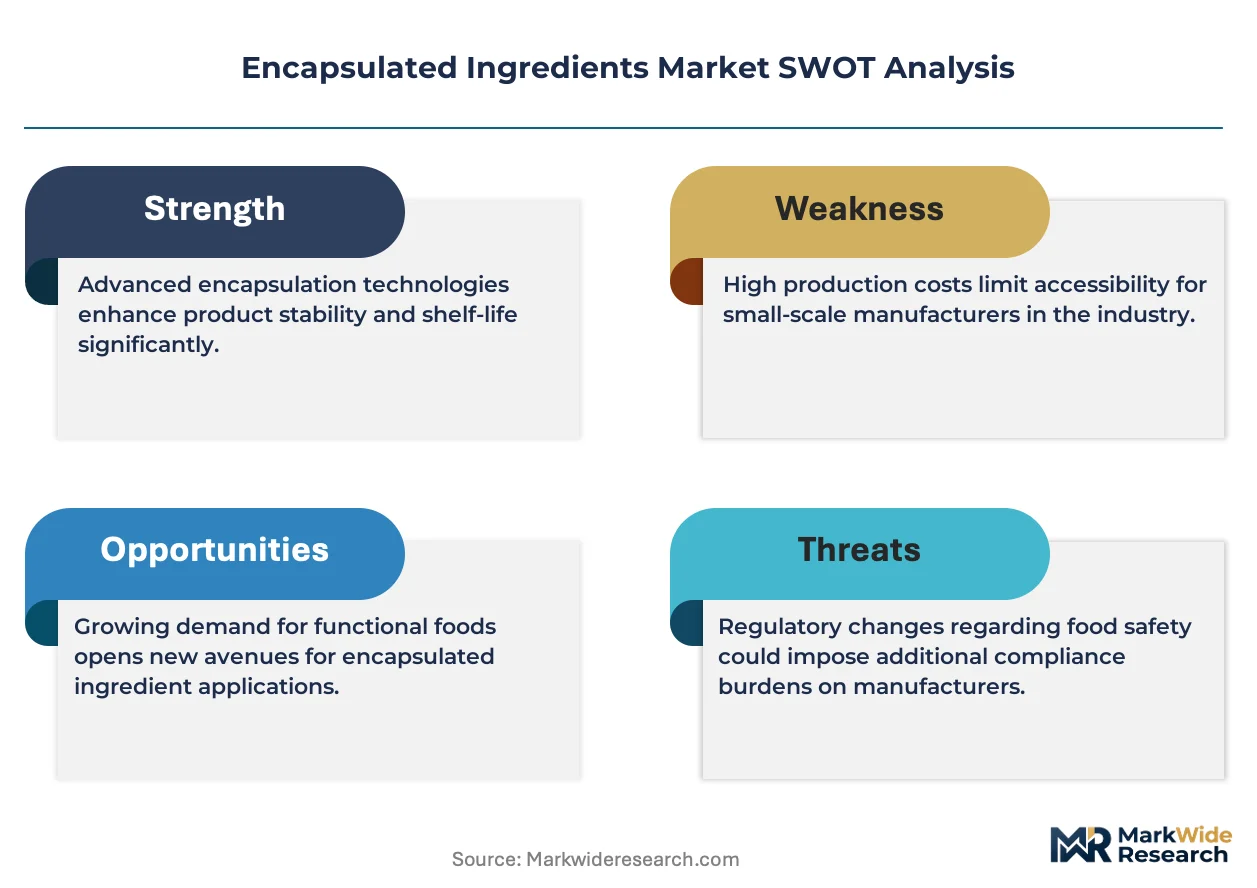
- EU Novel Food Regulation:Streamlined safety assessments for novel carrier substances accelerate market entry timelines for liposome-based nutraceuticals, expanding the addressable product pipeline.
- Pharmaceutical formulation adoption:Drug makers seeking bioavailability enhancement for poorly soluble APIs drive demand for polymeric shell materials and complex multi-layer particle architectures.
- Cosmetics transdermal targeting:Bilayer specificity in liposome manufacturing enables intracellular delivery of active compounds, opening premium positioning in dermatological and anti-aging segments.
Market Restraints
- Gelatin supply concentration:Bovine and porcine-derived shell material sourcing clusters in specific geographies, exposing formulators to zoonotic disease-related supply interruptions and religious dietary compliance costs.
- REACH compliance burden:ECHA substance registration requirements for new encapsulation polymers extend development timelines by 18-36 months and multiply regulatory filing expenditures.
- Spray drying energy intensity:Thermal processing of carrier systems consumes natural gas and electricity at rates that compress margins when energy markets spike.
Strategic Opportunities
- Plant-based carrier innovation:Modified starch and alginate matrices from non-animal sources capture share in vegan-certified functional foods and halal/kosher pharmaceutical segments.
- Injectable pharmaceutical liposomes:Parenteral drug delivery applications exploit bilayer specificity for oncology and vaccine adjuvant formulations with higher technical barriers to entry.
- Precision fermentation-to-encapsulation:Control over vitamin production and subsequent protective matrix integration reduces third-party dependency and quality variance.
Industry Challenges
- Pharmacopeial dissolution testing:Evolving USP and EP monographs for controlled-release validation separate qualified suppliers from commodity encapsulators, requiring capital investment in analytical infrastructure.
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in polymer science, food safety, and pharmaceutical GMP command premium compensation and extend hiring cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Encapsulated Ingredients Market |
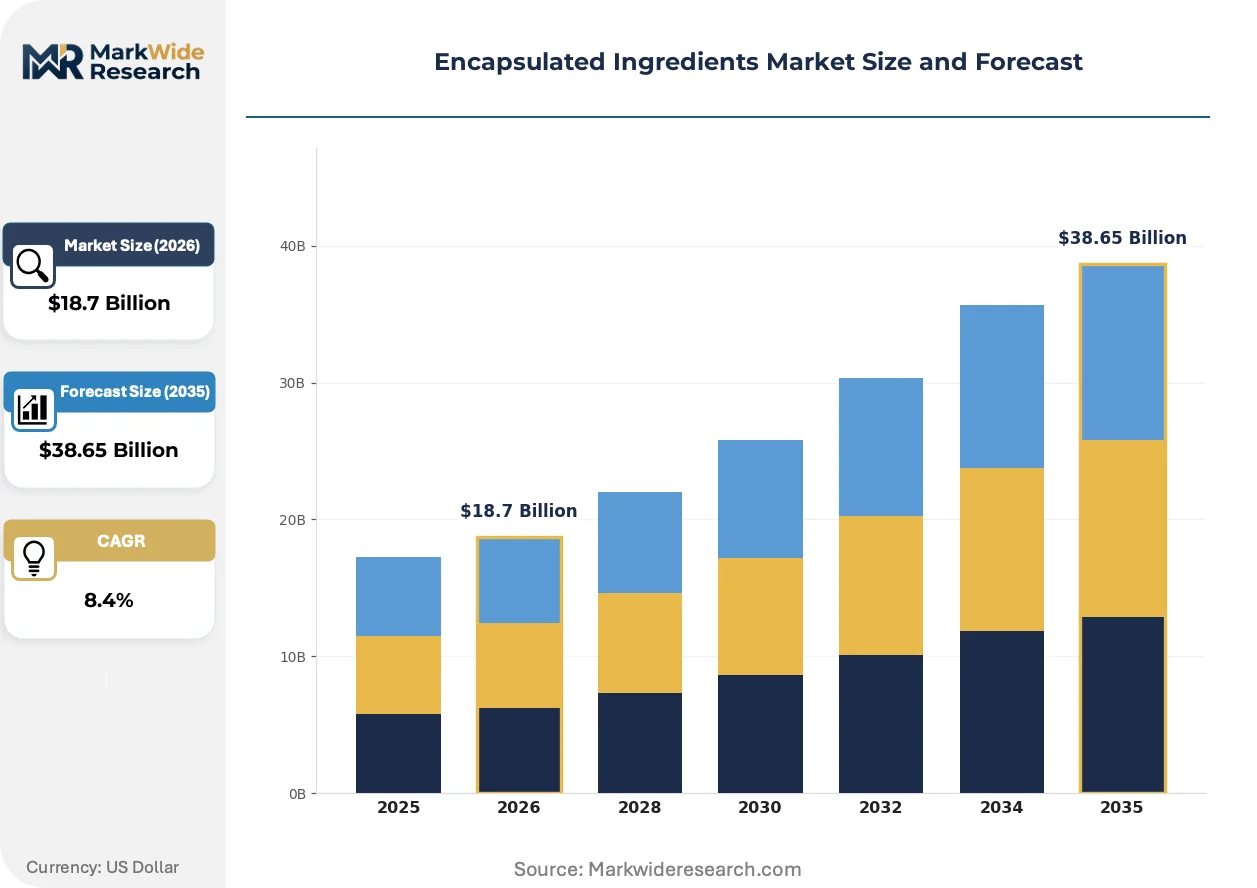
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Vitamins, Minerals, Enzymes Application: Food & Beverages, Pharmaceuticals, Nutraceuticals, Cosmetics Technology: Coacervation, Spray Drying, Liposome, Microencapsulation End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | BASF SE, Cargill, Incorporated, DSM-Firmenich AG, Ingredion Incorporated, Kerry Group plc, Givaudan SA, International Flavors & Fragrances Inc., Symrise AG, Balchem Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Encapsulated Ingredients Market Evolving Landscape
Active compound protection strategies are bifurcating between cost-optimized spray-dried matrices and precision-engineered lipid-based systems, with adoption patterns diverging sharply by end-use margin structure.
Liposome manufacturing is migrating from cosmetic topical applications toward injectable pharmaceuticals and advanced nutraceuticals. Oncology drug developers and mRNA vaccine producers now specify bilayer vesicles for intracellular payload delivery. This shift is compressing the addressable market for conventional emulsion-based encapsulation in high-value therapeutic categories.
EFSA Novel Food opinions and FDA GRAS determinations are hardening evidentiary standards for new carrier substances. Regulators now demand comprehensive toxicological dossiers and stability data across gastrointestinal conditions. Small and mid-sized encapsulation houses face capital constraints in assembling submission packages, advantaging integrated players with captive regulatory affairs functions.
Ingredient buyers are consolidating supplier relationships around vertically integrated partners offering fermentation-through-encapsulation control. Functional food manufacturers and pharmaceutical formulators alike now prioritize single-source accountability for active compound potency and release profile consistency. Germany and the Netherlands exhibit the most concentrated procurement consolidation, with multi-year framework agreements displacing spot purchasing for core vitamins and probiotics.
Encapsulated Ingredients Market Segmentation
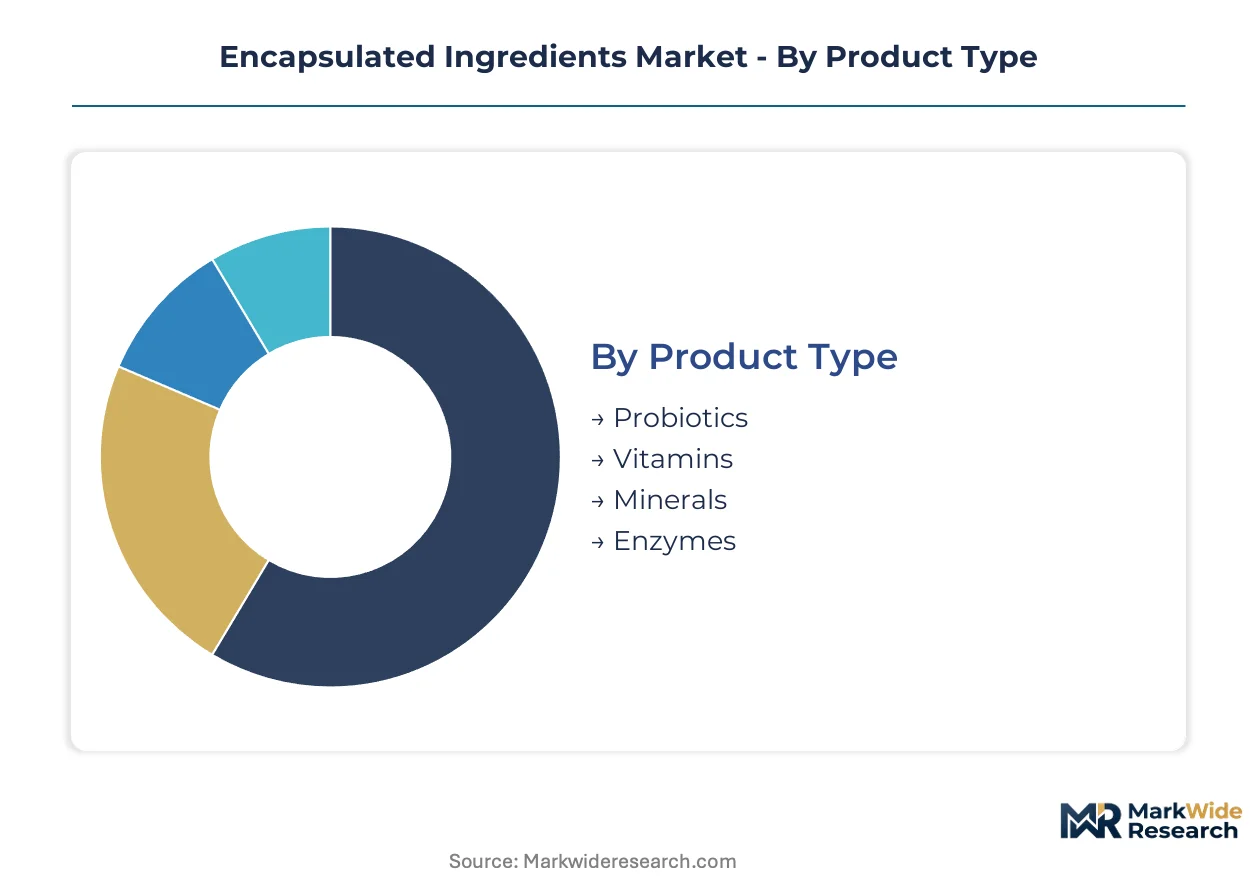
Encapsulated ingredients demand fragments sharply across production cycles and technical specifications. Spray-dried vitamins turn inventory in weeks while liposome-based pharmaceuticals require months of validation. Understanding these velocity differentials separates working capital efficiency from stranded capacity risk.
Product Type:
Probiotics command the longest production cycles due to cryoprotectant matrix development and viability testing protocols. Vitamins and minerals move through formulation faster, with standardized carrier systems compressing lead times.
- Probiotics:Live microbial cultures sealed in alginate or protein matrices with cryoprotectant enhancement to maintain CFU counts through gastric transit. Demand concentrates in Germany and the Netherlands where precision fermentation clusters enable integrated production-to-encapsulation control, though thermal sensitivity during spray drying constrains scale economics.
- Vitamins:Oil-soluble and water-soluble compounds protected against oxidation through modified starch or gum arabic shells. Pharmaceutical formulators in Switzerland and the United States drive specification intensity for bioavailability-enhanced retinol and ascorbic acid derivatives, with DSM-Firmenich AG's fermentation-to-encapsulation integration setting the reference standard.
- Minerals:Inorganic salts and chelated compounds requiring pH-buffered matrices to prevent ionic degradation during shelf storage. Functional food manufacturers specify iron and zinc encapsulates for fortified cereals and infant nutrition.
- Enzymes:Protein catalysts demanding moisture-barrier protection to preserve catalytic activity in industrial and digestive applications. Bakery and detergent formulators in Japan and South Korea specify granulated lipase and protease encapsulates for controlled release.
Probiotics dominate installed base value due to premium positioning and technical barriers. Vitamins are where expansion concentrates as pharmaceutical-grade specifications proliferate.
Application:
Cosmetics applications command margin premiums through bilayer specificity requirements. Food and beverage volumes move through commodity pricing structures with thinner returns per kilogram.
- Food & Beverages:Shelf-stable fortification of dairy alternatives, sports nutrition, and functional beverages through spray-dried matrices. Major formulators in Germany and the Netherlands specify clean-label carrier systems to meet EFSA Novel Food compliance for emerging plant-based encapsulation formats.
- Pharmaceuticals:Extended-release and bioavailability-enhanced drug delivery systems requiring validated dissolution profiles per USP and EP monographs. Injectable liposomes for oncology applications command the steepest technical barriers and pricing premiums.
- Nutraceuticals:Dietary supplement formats spanning softgels, tablets, and powder sachets with GRAS or Novel Food regulatory clearance. Direct-to-consumer brands in the United States consolidate procurement around vertically integrated suppliers.
- Cosmetics:Transdermal delivery systems exploiting liposome bilayer fusion with stratum corneum lipids. Anti-aging and dermatological serums in France and South Korea specify sub-micron vesicle architectures for intracellular payload delivery.
Food and beverages anchor volume throughput. Pharmaceuticals are climbing the fastest as oncology and vaccine adjuvant applications multiply.
Technology:
Capital intensity varies by an order of magnitude across these methods. Spray drying operates on standard dairy processing equipment while liposome manufacturing requires specialized extrusion and sterile filtration infrastructure.
- Coacervation:Phase separation of hydrocolloid polymers around oil-based active cores, historically dominant in flavor and fragrance encapsulation. Swiss and German flavor houses maintain captive coacervation capacity for volatile compound protection.
- Spray Drying:Atomization of active-carrier slurries into heated chambers, occupying volume leadership through capital efficiency and scale. Energy intensity during thermal processing compresses margins when natural gas markets spike.
- Liposome:Phospholipid bilayer vesicles enabling transdermal and intracellular targeting through membrane fusion. Manufacturing migration from cosmetics toward injectable pharmaceuticals and mRNA vaccine adjuvants is reshaping capacity allocation.
- Microencapsulation:General category spanning fluid bed coating, extrusion, and interfacial polymerization for controlled-release architectures. Pharmaceutical formulators specify multi-layer particles for colon-targeted or sustained-release APIs.
Spray drying dominates installed capacity tonnage. Liposome manufacturing is where capital deployment concentrates.
End User:
Procurement consolidation patterns diverge sharply by buyer scale and technical capability. Manufacturers with in-house formulation expertise demand specification control while retailers prioritize turnkey supply.
- Manufacturers:Integrated food, pharmaceutical, and cosmetic producers with captive encapsulation or toll-manufacturing relationships. German and Dutch ingredient technology clusters support precision scale-up for pharmaceutical-grade microcapsules.
- Distributors:Intermediate traders consolidating spot and contract volumes for smaller formulators lacking direct supplier relationships. Inventory risk concentrates in probiotic and enzyme categories with shorter shelf stability.
- Retailers:Private-label functional food and supplement brands outsourcing complete formulation and encapsulation to turnkey suppliers. EFSA and FDA compliance documentation requirements favor established integrated partners.
- Consumers:Direct purchasing of encapsulated supplement formats through e-commerce and specialty channels, limited by regulatory constraints on therapeutic claims and dosage form sophistication.
Manufacturers control the deepest specification relationships. Retailers are gaining share fastest as private-label functional food proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland tolerate premium pricing for pharmaceutical-grade encapsulation, while functional food manufacturers in India and Brazil prioritize cost-optimized spray-dried matrices. This elasticity gap shapes regional capacity allocation and technology migration patterns.
Germany
Pharmaceutical formulators in Baden-Württemberg and North Rhine-Westphalia drive specification intensity for bioavailability-enhanced APIs. EMA guidance on liposomal drug products tightens validation requirements for dissolution testing. The Mannheim-Heidelberg corridor hosts precision encapsulation scale-up facilities serving oncology and vaccine adjuvant applications.
United States
Dietary supplement brands consolidate procurement around vertically integrated suppliers for GRAS-compliant vitamin encapsulates. FDA enforcement of 21 CFR Part 111 cGMP for dietary supplements elevates documentation burdens for contract manufacturers. New Jersey and California clusters specialize in probiotic cryoprotectant matrices for direct-to-consumer brands.
Switzerland
Nutraceutical and cosmetic formulators demand sub-micron liposome architectures for transdermal delivery systems. Swissmedic pharmacopeial standards for parenteral liposomes exceed EMA baselines, filtering supplier qualification. Basel and Geneva house integrated fermentation-to-encapsulation operations for vitamin derivatives.
India
Functional food manufacturers seek cost-competitive mineral encapsulates for fortified staples and infant nutrition. FSSAI notification on novel food ingredients delays market entry for plant-based carrier systems by 12-18 months. Maharashtra and Gujarat clusters specialize in spray-dried vitamin premixes for domestic and export markets.
Netherlands
Dairy alternative and sports nutrition brands specify clean-label encapsulation formats for omega-3 and probiotic fortification. EFSA Novel Food opinions on modified starch carriers accelerate compliance timelines for plant-based matrices. Wageningen and Eindhoven anchor ingredient technology clusters linking precision fermentation to protective matrix integration.
Encapsulated Ingredients Market Competitive Landscape
Integrated chemical conglomerates and specialized flavor houses split the market into divergent capability tiers. The vendor base concentrates around players with captive polymer science expertise or backward integration into fermentation-derived actives. Three archetypes dominate: diversified chemical majors controlling shell material supply, flavor houses leveraging coacervation heritage, and nutrition specialists with end-to-end vitamin production. Competitive moves center on multi-year framework agreements displacing spot purchasing and capital deployment into liposome manufacturing infrastructure.
Within the integrated chemical tier, BASF SE anchors polymer science capabilities for pharmaceutical-grade microcapsule production. Kerry Group plc exemplifies flavor house evolution into dairy-derived carrier systems through Irish and Dutch manufacturing footprints. DSM-Firmenich AG represents the fermentation-to-encapsulation archetype with Swiss and German operational integration. These three occupy positions across distinct strategic vectors rather than direct segment competition.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| DSM-Firmenich AG |
| Ingredion Incorporated |
| Kerry Group plc |
| Givaudan SA |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Balchem Corporation |
| Others |
Value Network & Pricing Analysis
The Mannheim-Heidelberg corridor's precision encapsulation scale-up capacity commands premium pricing power for pharmaceutical-grade microcapsules, compressing margins for standalone encapsulation houses unable to match EMA-validated dissolution testing infrastructure. German ingredient technology clusters feed downstream pricing stratification across probiotics, vitamins, and liposome-based actives.
Pricing Analysis
After-sales revenue from multi-year framework agreements and technical service contracts drives lifetime value for integrated encapsulation suppliers. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and food-economy levels separates validated USP/EP-compliant suppliers from commodity spray-dried operators. Cost compression in food-grade spray-dried matrices is intensifying because energy market volatility erodes thermal processing margins. Functional food manufacturers in India and Brazil exhibit the highest price sensitivity, while Swiss and German pharmaceutical formulators tolerate premiums for liposome bilayer specificity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from integrated chemical conglomerates strain liquidity for mid-sized encapsulation houses competing for bovine gelatin and phospholipid feedstock. Manufacturing capacity concentrates in Germany, the Netherlands, and Switzerland, with raw material sourcing drawing from Brazilian gum arabic plantations, Indian modified starch processors, and Chinese phospholipid refiners. Single-source vulnerability around porcine-derived gelatin exposes formulators to zoonotic disease-related supply interruptions. Distribution runs through manufacturer-direct frameworks for large pharmaceutical accounts and distributor intermediaries for smaller nutraceutical brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as pharmaceutical formulation adoption for bioavailability-enhanced APIs rebounds from prior development timeline compression. Liposome manufacturing capacity expansion for oncology and vaccine adjuvant applications anchors the cyclical driver.
For Market Incumbents: Harden analytical infrastructure investments to defend against evolving USP and EP dissolution testing monographs that threaten to disqualify commodity encapsulators. Deepen backward integration into fermentation-derived actives to reduce third-party dependency for vitamin and probiotic supply security. Capacity addition in the Wageningen-Eindhoven corridor captures EFSA Novel Food compliance advantages for plant-based carrier systems. For New Entrants and Emerging Players: Establish a beachhead in injectable pharmaceutical liposomes where bilayer specificity requirements create defendable technical barriers against established spray-dried competitors. Target Swiss and South Korean cosmetic formulators seeking sub-micron transdermal delivery systems with limited qualified supplier options. A go-to-market angle emphasizing single-source accountability for active compound potency and release profile consistency displaces fragmented multi-vendor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-to-encapsulation integrated players with captive regulatory affairs functions and multi-year framework agreement pipelines. Long-term viability over a five-to-ten year window rests on pharmacopeial validation capabilities rather than commodity tonnage scale. Acquisition target archetype: mid-cap specialists with EMA/FDA submission experience in liposomal drug products. The signal to watch is EFSA Novel Food opinion acceleration for plant-based carrier substances as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Liposome Manufacturing Scale-Up | Injectable pharmaceutical and mRNA vaccine adjuvant applications command premium positioning through EMA-validated bilayer specificity. |
| Backward Integration into Fermentation | Captive vitamin production and protective matrix integration reduces quality variance for DSM-Firmenich AG and comparable integrated players. |
| Plant-Based Carrier Innovation | Modified starch and alginate matrices capture share in vegan-certified functional foods and halal/kosher pharmaceutical segments. |
| Regulatory Affairs Capability Buildout | Integrated GRAS and Novel Food submission functions advantage large players against capital-constrained mid-sized encapsulation houses. |
| Multi-Year Framework Agreements | German and Dutch procurement consolidation around single-source accountability displaces spot purchasing for core vitamins and probiotics. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings for this encapsulated ingredients analysis. Formulation chemists at pharmaceutical manufacturers, regulatory affairs leads at integrated chemical conglomerates, procurement directors at functional food brands, and plant managers at spray-drying facilities provided operational perspective. Secondary sources encompassed EFSA Novel Food opinions, FDA GRAS determinations, ECHA REACH registration databases, USP and EP pharmacopeial monographs, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up capacity modeling and top-down demand triangulation validated segment-level outputs.
Calibration against historical capacity utilization rates and validated dissolution testing adoption curves informed the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, application, technology, and end-user procurement consolidation patterns. CAGRs were derived from slope analysis of adoption curves rather than extrapolation. Industry-specific forecast inputs included EMA guidance trajectory on liposomal drug products and FSSAI notification timelines for novel food ingredients in India.
Stress conditions across energy market volatility, gelatin supply interruption scenarios, and regulatory opinion delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding pharmacopeial standard evolution and procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mustard Oil Market
Ingredients
Oak Chips White Extract Market
Ingredients
North America Agar Market
Ingredients
Plant Based Thickener Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Potato Peel Powder Market
Ingredients
Carotenes Market
Ingredients
Bran Market
Ingredients
Oat Ingredients Market
Ingredients
Yeast Flakes Market
Ingredients
Global Dairy Protein Ingredients Market
Ingredients
US Vegetable Oil Market
Ingredients
Bakery Ingredients Market
Ingredients
Omega 6 Market
Ingredients
Agave Inulin Market
Ingredients
Omega 9 Market