
 Hops Derivative Market | 2026-2036
Hops Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Hops Derivative Market Foresight
Market Context
Specialty hop oil extraction is reshaping margin pools away from basic pellet sales toward refined aromatic concentrates. BarthHaas leverages its integrated breeding and processing infrastructure across Germany and the United States to dominate premium extract supply. YCH HOPS sustains its position through cooperative farmer networks in the Yakima Valley that secure proprietary varietal access. Hopsteiner differentiates via molecular breeding programs targeting disease-resistant cultivars with elevated terpene profiles.
Technical Definition and Segment Structure
Hops derivatives comprise processed outputs from Humulus lupulus flowers, including CO2-extracted resins containing alpha acids, beta acids, and essential oils used for bittering, aroma, and antimicrobial stabilization in beer and beyond. Supercritical carbon dioxide extraction at pressures exceeding 300 bar preserves volatile terpenes while eliminating organic solvent residues, yielding food-grade concentrates suitable for precision dosing. Hops extract captures the dominant value share among product types due to its concentration efficiency and extended shelf stability relative to whole-flower equivalents. Within applications, brewing industry demand remains structurally mature while pharmaceutical interest in xanthohumol isolates for nutraceutical formulations represents the fastest-expanding margin pool.
Regulatory Frame and Outlook
The FDA governs hops derivatives as generally recognized as safe food ingredients in the United States, while the EPA regulates solvent discharge from extraction facilities under Clean Air Act provisions. In Europe, EFSA evaluates novel hop compounds for health claims, and REACH mandates full toxicological dossiers for imported extract solvents. Germany's BfR sets residue limits for pesticide carryover in processed hop materials. Stakeholders must monitor tightening xanthohumol purity standards in pharmaceutical applications and assess extraction facility relocation risks under evolving carbon border adjustment mechanisms.
Market Dynamics
Supercritical CO2 extraction infrastructure is consolidating processing capacity around Germany's Hallertau region and Washington's Yakima Valley, compressing margins for smaller pellet producers while elevating barrier thresholds for pharmaceutical-grade isolate supply.
Growth Catalysts
- REACH solvent compliance mandates:European ECHA registration requirements for extraction solvents are accelerating facility upgrades toward closed-loop CO2 systems, disqualifying older hexane-based operations from premium supply tiers.
- Craft brewing precision dosing:North American microbreweries are standardizing on terpene-specific oil blends for flavor replication across distributed brewing locations, creating pull for standardized analytical certificates.
- Xanthohumol nutraceutical applications:Pharmaceutical formulators in Japan and South Korea are expanding preclinical programs targeting prenylated flavonoid isolates for metabolic health indications.
Market Restraints
- Alpha acid price volatility:Weather-driven yield fluctuations in Hallertau and Yakima concentrate input cost risk for bittering extract producers without contracted acreage.
- Supercritical equipment capex intensity:300-bar CO2 extraction vessels require specialized pressure-rated fabrication, limiting processor entry to well-capitalized operators.
- Essential oil substitution:Laboratory-synthesized hop aroma compounds from flavor houses in Switzerland and the Netherlands are penetrating economy-tier brewing applications.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO's expanding GMP certification capacity for botanical extracts creates pathway for xanthohumol API registration targeting domestic nutraceutical formulators.
- Carbon border adjustment positioning:EU CBAM implementation is incentivizing renewable-powered extraction facilities in Portugal and Spain to capture preferential tariff treatment.
- Bioreactor cultivation convergence:Precision fermentation of hop terpenes combined with plant cell culture is opening pharmaceutical-grade supply independent of agricultural seasonality.
Industry Challenges
- Supercritical engineering talent scarcity:Process optimization for terpene preservation at elevated pressures requires specialized chemical engineering expertise concentrated in German technical universities.
- Dual-use export licensing complexity:Concentrated alpha acid isolates face controlled substance scrutiny under national pharmaceutical precursor regulations, complicating cross-border pharmaceutical supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hops Derivative Market |
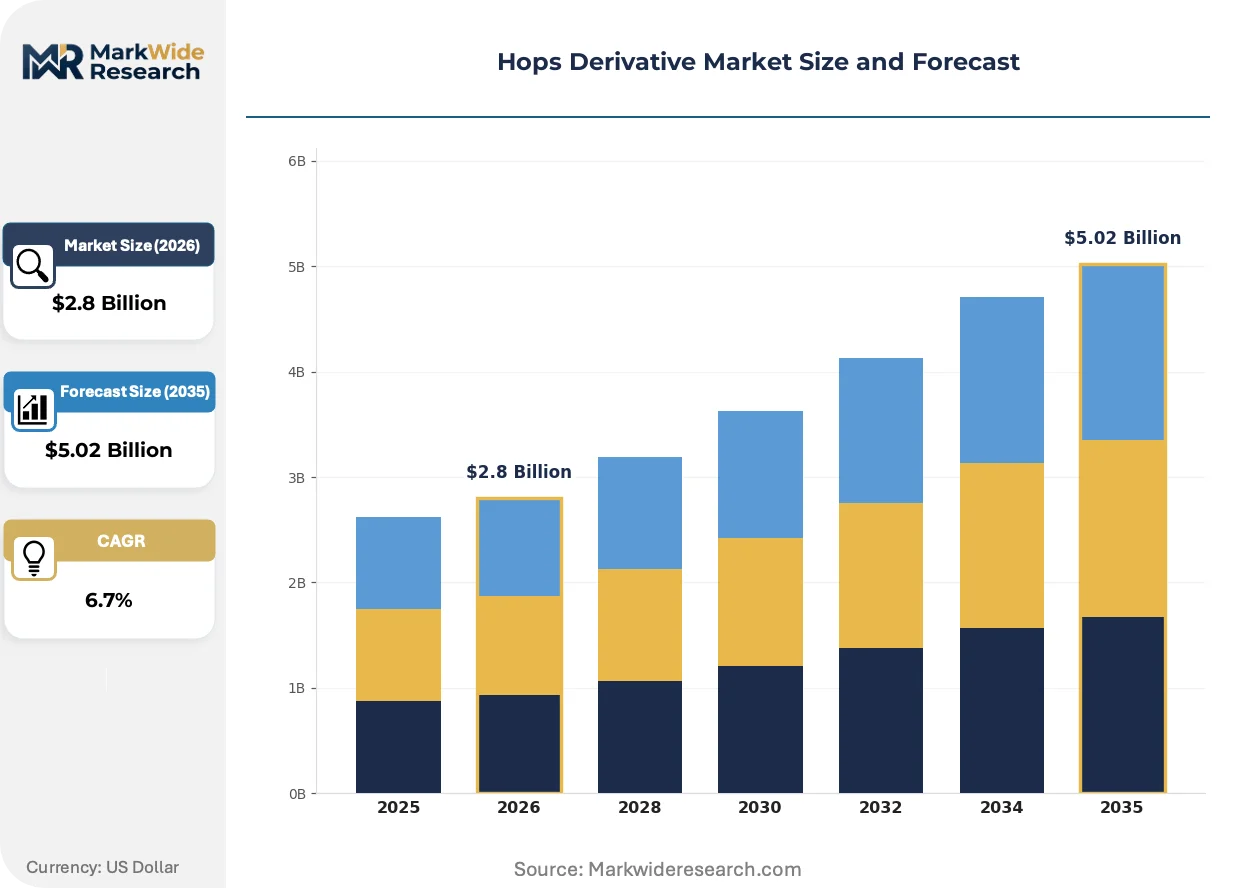
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hops Extract, Hops Pellets, Liquid Hops, Hop Oil Application: Brewing Industry, Food Flavoring, Pharmaceuticals, Cosmetics Form: Solid, Liquid, Powder, Concentrate End User: Breweries, Food Manufacturers, Cosmetic Companies, Research Institutions |
| Companies Covered | Kalsec Inc, New Zealand Hops Limited, BarthHaas, Hopsteiner, John I. Haas, YCH HOPS, Charles Faram & Co Ltd, Crosby Hops, Steiner Hops, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hops Derivative Market Shifts & Advancements
Processing technology and regulatory chemistry standards are converging to separate commodity pellet supply from value-captured extract and isolate tiers, with quality verification systems becoming the primary competitive differentiator.
Supercritical CO2 extraction is migrating from batch-operated pilot systems toward continuous-flow processing architectures. Mid-scale craft brewing suppliers in Oregon and Colorado are adopting modular 50-liter hourly throughput units. The technology is migrating from artisan-scale equipment toward industrial-grade installations capable of pharmaceutical COA documentation.
REACH F-Gas Regulation amendments are tightening solvent recovery efficiency thresholds for extraction facilities operating above 100-ton annual CO2 throughput. German BfR is coordinating residue limit harmonization with EFSA novel food evaluations. Pharmaceutical-grade hop oil producers in Bavaria are retrofitting closed-loop refrigeration systems to maintain operating licenses.
Brewery technical buyers are consolidating supplier relationships around integrated breeding-to-extract providers capable of varietal traceability documentation. Procurement committees at multi-site brewing groups are displacing spot-market pellet purchasing with contracted extract volume commitments. This consolidation pattern is most pronounced among top-50 US craft brewing groups restructuring their hop supply agreements.
Hops Derivative Market Segmentation
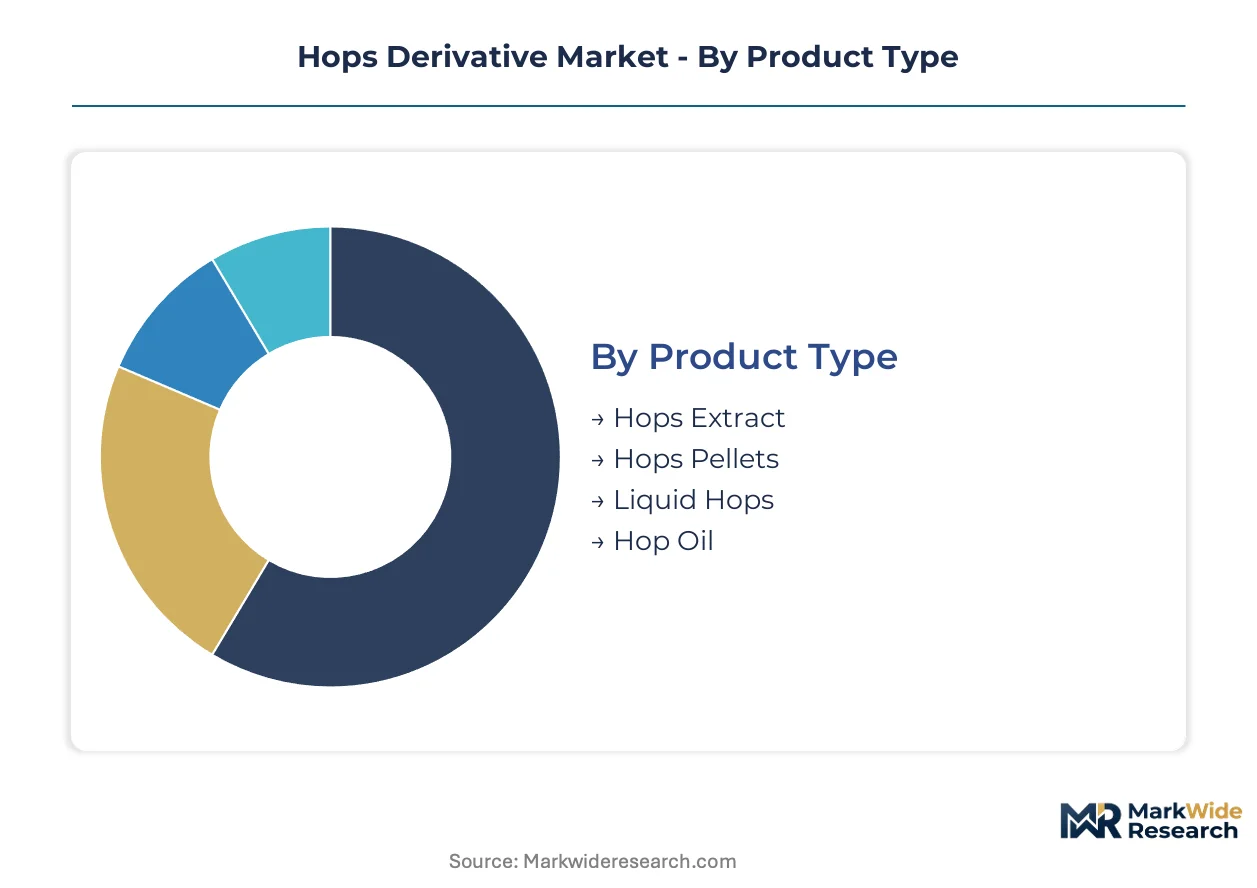
Hops derivatives fragment across four distinct classification axes that determine pricing power, regulatory pathway, and customer procurement behavior. Product form dictates extraction technology requirements and shelf stability. Application end-use separates commodity brewing supply from pharmaceutical-grade isolate premiums.
Product Type:
Cost tier differentiation separates concentrated extracts commanding formulation precision premiums from basic pellet commodities serving volume brewing operations.
- Hops Extract:Supercritical CO2-derived concentrates containing standardized alpha acid and essential oil fractions enable precise bittering and aroma dosing in automated brewing systems. German Hallertau processors and Yakima Valley facilities dominate supply for craft breweries demanding batch-to-batch consistency.
- Hops Pellets:Hammer-milled whole hop flowers compressed into 6mm cylinders retain vegetative matter requiring kettle filtration. Demand concentrates among traditional European lager producers and mid-scale North American breweries without extract handling infrastructure.
- Liquid Hops:Aqueous or oil-based suspensions of hop compounds enable direct tank addition without dissolution steps. Food manufacturers in Japan leverage liquid formats for non-alcoholic hop-flavored beverages.
- Hop Oil:Terpene-rich fractions isolated through steam distillation or molecular distillation capture volatile aromatic compounds. Cosmetic formulators in South Korea incorporate hop oil into scalp care products for antimicrobial properties.
Hops Extract commands the established base. The steepest expansion runs through Hop Oil as cosmetic and nutraceutical applications multiply.
Application:
Application maturity spans from structurally saturated brewing demand to emerging pharmaceutical interest in prenylated flavonoid bioactives.
- Brewing Industry:Bittering, aroma, and antimicrobial stabilization functions in beer production consume the majority of processed hop volumes. German purity law compliance and American craft brewing standardization sustain extract procurement at scale.
- Pharmaceuticals:Xanthohumol isolation for metabolic health and hormonal modulation applications requires chromatographic purification to API-grade specifications. CDSCO-registered Indian manufacturers are building GMP capacity for nutraceutical formulators.
- Food Flavoring:Hop-derived bittering agents and aromatic extracts flavor non-alcoholic beverages, confectionery, and savory applications. Swiss flavor houses integrate hop terpenes into natural flavor compounding.
- Cosmetics:Antioxidant and antimicrobial properties drive hop extract inclusion in skin and hair care formulations. South Korean cosmetic companies lead formulation innovation for hop-derived bioactives.
Brewing Industry anchors volume throughput. Pharmaceuticals deliver the fastest margin expansion as clinical validation progresses.
Form:
Physical state determines logistics economics, dosing automation compatibility, and stability requirements across supply chain configurations.
- Liquid:Pumpable formats integrate directly into continuous brewing processes and automated flavor dosing systems. Oregon and Colorado craft brewing clusters standardize on liquid extract for distributed production networks.
- Concentrate:High-potency reduced-volume formats minimize cold chain burden and enable long-haul export economics. REACH-registered European processors concentrate supply for pharmaceutical and premium brewing tiers.
- Powder:Spray-dried or freeze-dried preparations enable dry blending in food and supplement manufacturing. Powder handling infrastructure limits adoption to integrated food processing facilities.
- Solid:Pellet and whole-flower formats retain traditional brewing workflow compatibility. German and Czech lager producers maintain solid hop procurement for decoction mashing protocols.
Liquid form dominates craft brewing procurement. Concentrate formats gain share fastest in pharmaceutical and export-oriented supply.
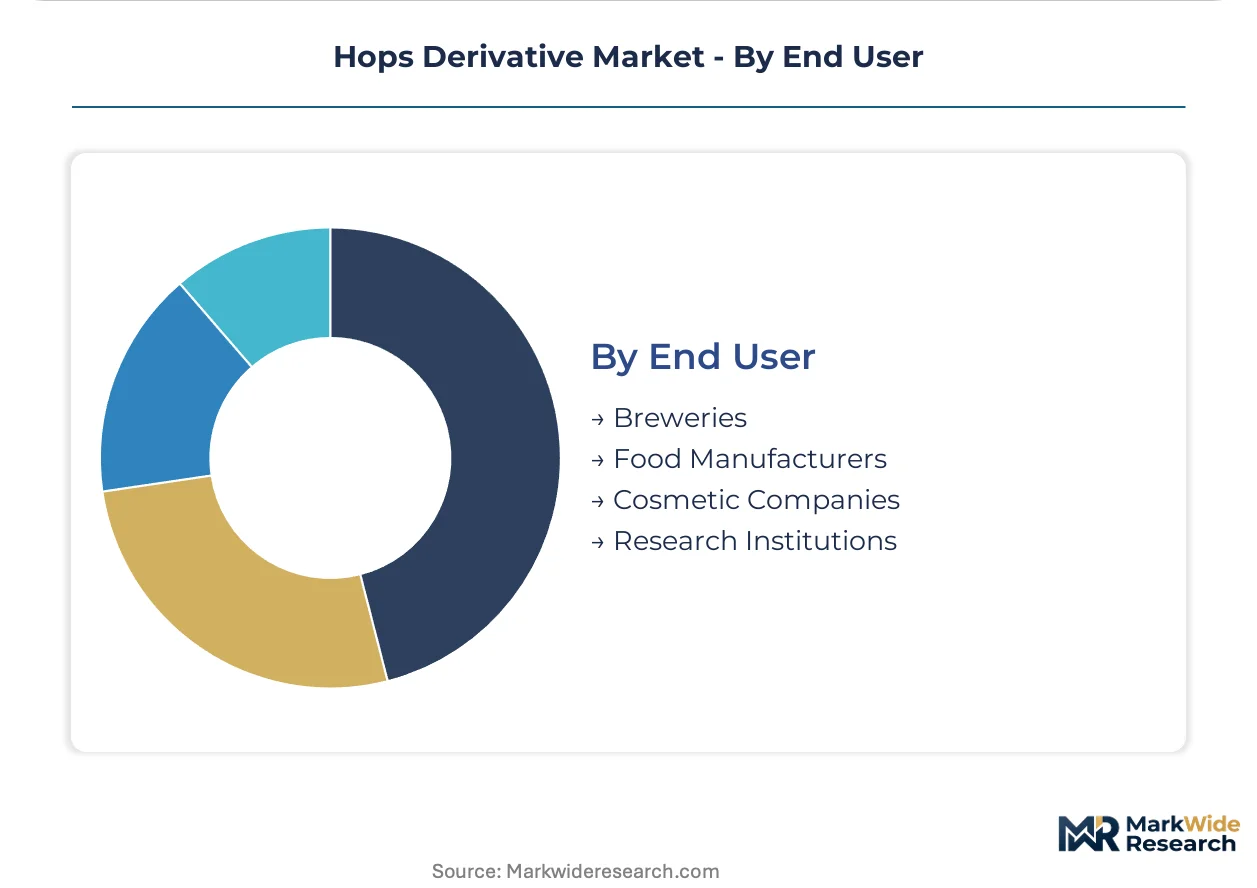
End User:
Customer type segmentation separates procurement committees at multi-site brewing groups from specialized pharmaceutical formulators with distinct quality documentation requirements.
- Breweries:Volume purchasers range from multinational lager producers to regional craft groups consolidating supplier relationships around integrated breeding-to-extract providers capable of varietal traceability documentation.
- Food Manufacturers:Natural flavor and bittering ingredient procurement targets clean-label positioning in functional beverages and snack applications. Japanese and South Korean food companies lead hop flavor adoption outside brewing.
- Cosmetic Companies:Botanical extract sourcing emphasizes sustainable cultivation certification and pesticide residue compliance. European cosmetic formulators drive demand for organic-certified hop derivatives.
- Research Institutions:Academic and commercial R&D programs require small-batch, high-characterization hop compounds for preclinical and analytical studies. University partnerships with German breeding programs secure proprietary genetic material access.
Breweries represent the established demand base. Research Institutions expand most quickly as xanthohumol clinical programs multiply across Asian pharmaceutical markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes hop derivatives primarily as standardized extracts for lager consistency, while the United States deploys terpene-specific oils for distributed craft brewing networks. Japan and South Korea diverge toward pharmaceutical-grade xanthohumol isolates for nutraceutical applications.
United States
Yakima Valley processors supply CO2-extracted alpha acid concentrates to craft breweries demanding batch-to-batch flavor replication. EPA Clean Air Act provisions regulate solvent discharge from Washington State extraction facilities. Oregon and Colorado brewing clusters drive adoption of modular liquid hop dosing systems for distributed production networks.
Germany
Hallertau-based cooperatives convert heritage varietals into REACH-compliant supercritical extracts for domestic and export lager producers. BfR residue limits for pesticide carryover shape processing protocols across Bavarian facilities. BarthHaas maintains integrated breeding-to-extract infrastructure spanning Hallertau and Yakima supply zones.
Japan
Pharmaceutical formulators in Osaka and Tokyo preclinical pipelines target xanthohumol isolates for metabolic health indications. PMDA botanical extract guidelines create registration pathways for prenylated flavonoid APIs. Food manufacturers leverage liquid hop formats for non-alcoholic hop-flavored beverage development.
South Korea
Seoul-based cosmetic companies incorporate hop oil into scalp care formulations for antimicrobial positioning. MFDS regulates botanical extract purity standards for topical applications. Domestic nutraceutical brands source xanthohumol concentrates from Indian CDSCO-registered manufacturers for metabolic supplement lines.
India
CDSCO's expanding GMP certification capacity enables domestic processors to supply xanthohumol API for Asian pharmaceutical formulators. FSSAI standards govern hop-derived food additive imports for craft brewing ingredient distributors. Maharashtra and Karnataka brewing clusters experiment with liquid hop extracts for flavor consistency in distributed production.
Hops Derivative Market Competitive Landscape
Capability concentration sits with integrated breeding-to-extract operators; scale advantage sits with cooperative farmer networks securing proprietary varietal access. The market structures around three tiers: multinational specialists controlling supercritical infrastructure, regional processors serving contracted brewing volumes, and emerging pharmaceutical-grade isolators targeting nutraceutical APIs. Dominant competitive moves include backward integration into captive hop acreage and technology licensing partnerships for continuous-flow CO2 extraction systems.
Among German-integrated specialists, BarthHaas and Hopsteiner occupy positions defined by controlled supply chain architecture from varietal development through pharmaceutical-grade extraction. YCH HOPS anchors the cooperative-network tier through farmer-owned infrastructure in the Yakima Valley. These three archetypes—integrated multinational, cooperative scale operator, and molecular breeding specialist—represent the competitive vectors shaping procurement consolidation among top-50 craft brewing groups.
| Leading Market Players |
|---|
| Kalsec Inc |
| New Zealand Hops Limited |
| BarthHaas |
| Hopsteiner |
| John I. Haas |
| YCH HOPS |
| Charles Faram & Co Ltd |
| Crosby Hops |
| Steiner Hops |
| Others |
Supply & Pricing Matrix
Hallertau and Yakima Valley processing concentration funnels margin capture toward integrated breeders with captive CO2 extraction infrastructure, leaving commodity pellet producers exposed to input cost volatility without downstream value capture.
Pricing Analysis
Long-term offtake contracts dominate premium extract procurement, with multi-year volume commitments from top-50 craft brewing groups displacing spot-market pellet purchasing. Three-tier pricing structure across pharmaceutical-grade isolates, premium brewing extracts, and commodity pellets reflects certification burden and analytical documentation depth. Cost compression in standard pellet tiers intensifies as weather-driven alpha acid yield fluctuations concentrate input risk among non-integrated processors. Price-sensitive mid-scale breweries without extract handling infrastructure face the steepest procurement pressure, while pharmaceutical formulators in Japan and South Korea demonstrate lowest sensitivity due to API-grade purity requirements.
Supply Chain Analysis
Extended payment terms from German and American brewing groups strain working capital for smaller pellet producers, accelerating consolidation around well-capitalized supercritical operators. Raw material flows draw from Germany's Hallertau heritage acreage, Washington's Yakima Valley proprietary networks, and emerging Portuguese renewable-powered facilities. Supply chain risk centers on single-source vulnerability for disease-resistant cultivars with elevated terpene profiles, as molecular breeding programs concentrate proprietary genetics at BarthHaas and Hopsteiner. Distribution runs through integrated breeding-to-extract providers capable of varietal traceability documentation, displacing fragmented spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as brewery technical buyers consolidate supplier relationships around integrated providers with interoperable quality verification systems, replacing fragmented multi-vendor procurement.
For Market Incumbents: Insulate premium extract margins by deepening backward integration into captive hop acreage in Yakima Valley and Hallertau, while retrofitting closed-loop CO2 systems to preempt REACH F-Gas compliance disqualification. Laboratory-synthesized hop aroma compounds from Swiss and Dutch flavor houses threaten economy-tier brewing applications; incumbents must defend through varietal exclusivity and terpene-specific oil blend standardization. For New Entrants and Emerging Players: Indian pharmaceutical manufacturing underpenetration offers the most accessible white-space target, where CDSCO GMP certification capacity expansion enables xanthohumol API registration for Asian nutraceutical formulators. Precision fermentation of hop terpenes combined with plant cell culture represents a convergent technology entry point independent of agricultural seasonality. New entrants should pursue technology licensing partnerships for continuous-flow CO2 extraction systems to bypass supercritical equipment capex barriers. For Investors and Strategic Acquirers: Capital is best deployed toward integrated breeding-to-extract operators with established REACH compliance infrastructure and proprietary varietal pipelines, as these archetypes capture margin migration from commodity pellets toward pharmaceutical-grade isolates. Long-term viability over the next decade hinges on carbon border adjustment positioning and renewable-powered extraction facility access. The signal to watch is EU CBAM implementation pace, which will determine preferential tariff treatment for Iberian and German facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Acreage | BarthHaas and YCH HOPS secure proprietary varietal access across Hallertau and Yakima supply zones. |
| Continuous-Flow CO2 Extraction Licensing | Modular 50-liter hourly throughput units enable mid-scale craft brewing suppliers in Oregon and Colorado. |
| CDSCO GMP Certification Investment | Indian processors build API-grade capacity for xanthohumol supply to Asian pharmaceutical formulators. |
| Renewable-Powered Facility Relocation | Portuguese and Spanish extraction sites capture EU CBAM preferential tariff treatment. |
| Precision Fermentation Convergence | Bioreactor cultivation opens pharmaceutical-grade terpene supply independent of agricultural seasonality. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with supercritical extraction engineers, brewery procurement committees, pharmaceutical formulators, and cooperative farmer network managers; and secondary validation through ECHA REACH registration databases, EPA Clean Air Act facility filings, CDSCO GMP certification records, and customs trade data for hop derivative flows. Bottom-up volume modeling across product type, application, form, and end user segments triangulated against top-down value estimates from processor capacity disclosures and brewing group ingredient spend patterns.
Forecast inputs considered supercritical CO2 extraction capacity expansion timelines, REACH F-Gas Regulation amendment implementation trajectories, and craft brewing consolidation patterns among top-50 groups. Segmentation dimensions modeled include product concentration tier, end-use application maturity, physical form logistics economics, and customer procurement sophistication across the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory compliance acceleration and pharmaceutical application pipeline progression.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bioreactor cultivation startups or carbon border adjustment arbitrageurs would shift outcomes. Macroeconomic deviation in agricultural input costs, regulatory tightening on xanthohumol purity standards, or breakthrough success in laboratory-synthesized hop aroma compounds would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Lactase Enzyme Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Home Baking Ingredients Market
Ingredients
Global Yeast Market
Ingredients
India Soy Protein Market
Ingredients
Konjac Flour Market
Ingredients
Polydextrose Ingredients Market
Ingredients
North America Potato Starch Market
Ingredients
Middle East and Africa Fruit and Vegetable Ingredients Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
South America Spirulina Extract Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Sesame Seed Extract Market
Ingredients
Green Gram Powder Market
Ingredients
Europe Plant Protein Ingredients Market