
 Oil and Gas Pipeline Management Software Market | 2026-2036
Oil and Gas Pipeline Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Pipeline Management Software Market Analytics
A shift from single-source SCADA contracts toward multi-vendor digital ecosystems is broadening procurement flexibility across midstream operators. Siemens AG leverages its electrification portfolio to anchor integrated pipeline automation suites in European utility corridors. Honeywell International sustains competitive positioning through specialized leak detection algorithms tied to its Experion platform. Emerson Electric differentiates via embedded analytics for predictive maintenance in Permian Basin gathering systems.
Oil and gas pipeline management software encompasses SCADA, GIS, and enterprise asset management platforms that ingest real-time pressure, flow, and corrosion data from distributed sensor networks to optimize throughput and integrity decisions. The software typically integrates with DCS architectures through OPC-UA or Modbus protocols, enabling centralized visibility across hundreds of miles of pipeline infrastructure. Cloud-based deployment is gaining traction fastest among gas distributors seeking elastic compute for seasonal demand spikes, while on-premise installations retain dominance among national oil companies with sovereign data requirements. Monitoring software occupies the largest revenue pool due to mandatory continuous surveillance under pipeline safety codes, though asset management modules are widening margin contribution through subscription renewal structures.
PHMSA in the United States enforces Part 195 and Part 192 integrity management rules that mandate documented risk assessment and anomaly response protocols, directly stimulating demand for compliance-oriented software modules. The EU Green Deal and F-Gas Regulation are pressuring European pipeline operators to deploy methane quantification and venting detection systems, reshaping product roadmaps for vendors serving that region. Stakeholders must weigh interoperability investments against the fragmentation emerging from proprietary IoT protocols and national cybersecurity certification schemes.
Market Dynamics
Cloud-native SCADA architectures are dismantling the single-vendor lock-in that has dominated pipeline automation for three decades, forcing incumbent suppliers to modularize their platforms or cede procurement decisions to system integrators.
Growth Catalysts
- PHMSA Part 195 Integrity Mandates:United States regulators now require continuous pressure monitoring and documented anomaly response protocols, compelling operators to replace legacy manual inspection cycles with automated compliance dashboards.
- Methane Quantification Technologies:Satellite-linked emissions monitoring is becoming standard for midstream gas distributors facing EU Green Deal border-adjustment mechanisms and domestic EPA reporting thresholds.
- Permian Basin Infrastructure Renewal:Texas and New Mexico shale operators are retiring 1980s-era gathering systems, creating replacement demand for integrated SCADA-GIS platforms with embedded predictive corrosion models.
Market Restraints
- Proprietary IoT Protocol Fragmentation:Sensor manufacturers deploy incompatible wireless standards (LoRaWAN, Sigfox, private 5G), forcing operators to maintain multiple gateway infrastructures and data translation layers.
- Cybersecurity Certification Divergence:NERC CIP in North America, IEC 62443 in Europe, and GB/T standards in China require redundant compliance engineering, inflating software development overhead for multi-regional vendors.
- Specialized OT Engineering Talent Scarcity:Pipeline control systems demand expertise spanning process engineering, network security, and cloud architecture, with fewer than fifteen accredited university programs producing qualified graduates annually.
Strategic Opportunities
- Hydrogen Pipeline Repurposing:European operators are piloting software modules that model hydrogen embrittlement risks in converted natural gas lines, creating first-mover advantage for vendors with materials science integration.
- Edge Computing Convergence:Distributed inference engines running directly on pipeline compressor stations are reducing latency for leak detection algorithms, opening subscription revenue from real-time anomaly scoring services.
- India National Gas Grid Expansion:The Petroleum and Natural Gas Regulatory Board's 33,000 km pipeline buildout is attracting SaaS providers willing to localize platforms for Hindi-language interfaces and domestic cloud sovereignty requirements.
Industry Challenges
- Legacy DCS Integration Complexity:Brownfield installations require protocol bridges between 1990s-era Modbus RTU networks and modern OPC-UA architectures, extending deployment timelines and inflating commissioning costs.
- API 1165 HMI Certification Delays:Pipeline operators face 14-18 month validation cycles for customized human-machine interface designs, compressing software release windows and complicating agile development workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Pipeline Management Software Market |
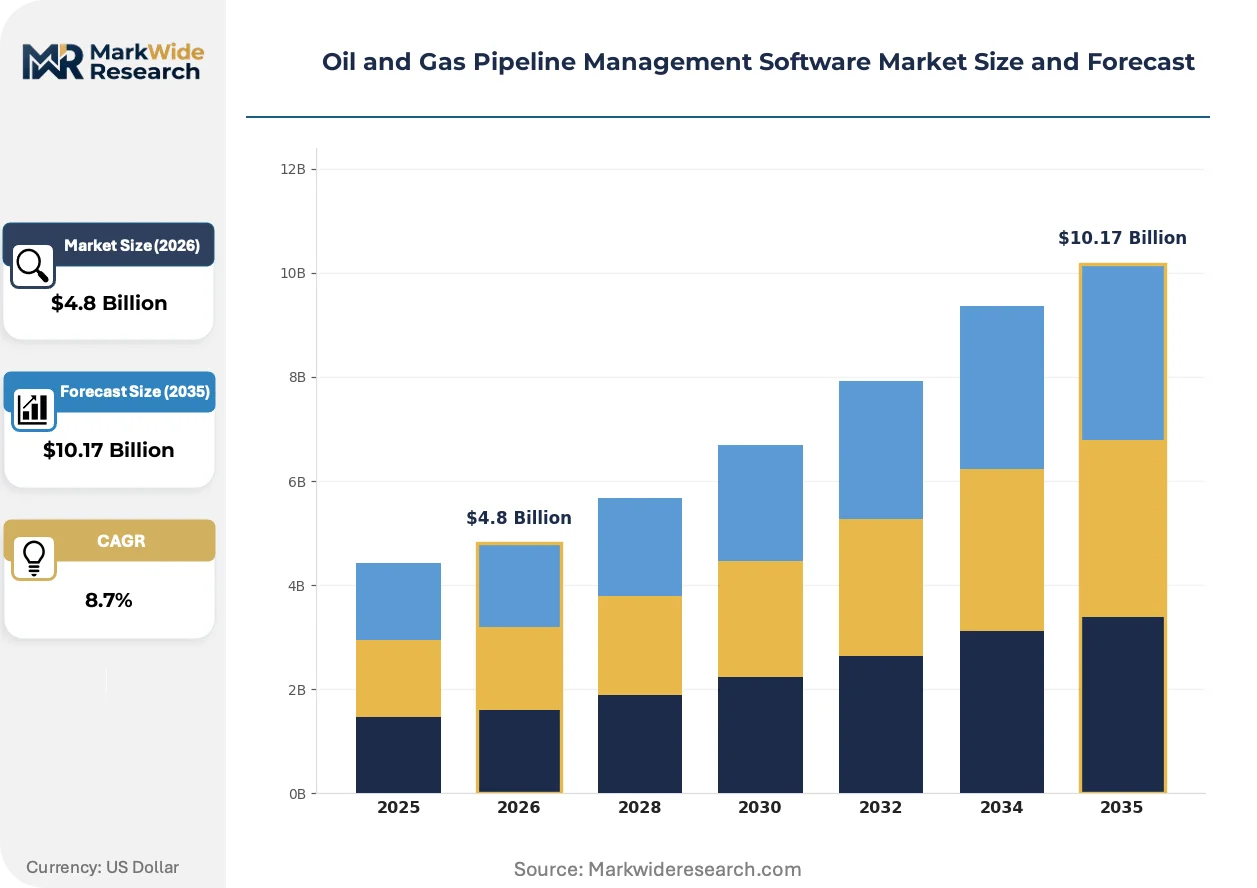
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Software, Maintenance Management, Leak Detection, Asset Management Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Oil Producers, Gas Distributors, Pipeline Operators, Engineering Firms Application: Pipeline Construction, Operational Efficiency, Regulatory Compliance, Risk Management |
| Companies Covered | Schneider Electric, Honeywell International, Siemens AG, Emerson Electric, ABB Ltd, General Electric Company, Rockwell Automation, Yokogawa Electric Corporation, AVEVA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Pipeline Management Software Market Evolving Landscape
Digital twin fidelity is advancing from static 3D models to real-time physics simulations, enabling operators to test pressure scenarios without interrupting live flow. This shift is compressing the feedback loop between field anomaly detection and engineering response.
Edge-deployed machine learning inference is overtaking centralized cloud analytics for time-critical leak detection decisions. These models process acoustic and pressure signatures locally on ruggedized gateways, eliminating 200-400 millisecond latency penalties from satellite uplinks. Gas transmission operators in the United States are deploying this architecture fastest, driven by PHMSA incident response timelines that leave no margin for round-trip data delays.
EU F-Gas Regulation amendments are mandating quantified methane venting reporting for all transmission pipelines above 7 megawatts thermal input. This rule is forcing software vendors to integrate satellite emissions data and ground-based sensor fusion into unified regulatory filings. German and Dutch operators are piloting vendor platforms that automate this reconciliation, creating template workflows for broader European adoption.
Subscription pricing for asset integrity modules is displacing perpetual license models among independent midstream operators. These buyers prefer operational expenditure treatment and bundled update cycles over capital-intensive upfront commitments. The pattern is most pronounced in Texas and Oklahoma, where private equity-backed pipeline aggregators prioritize cash flow predictability over long-term ownership economics.
Oil and Gas Pipeline Management Software Market Segmentation
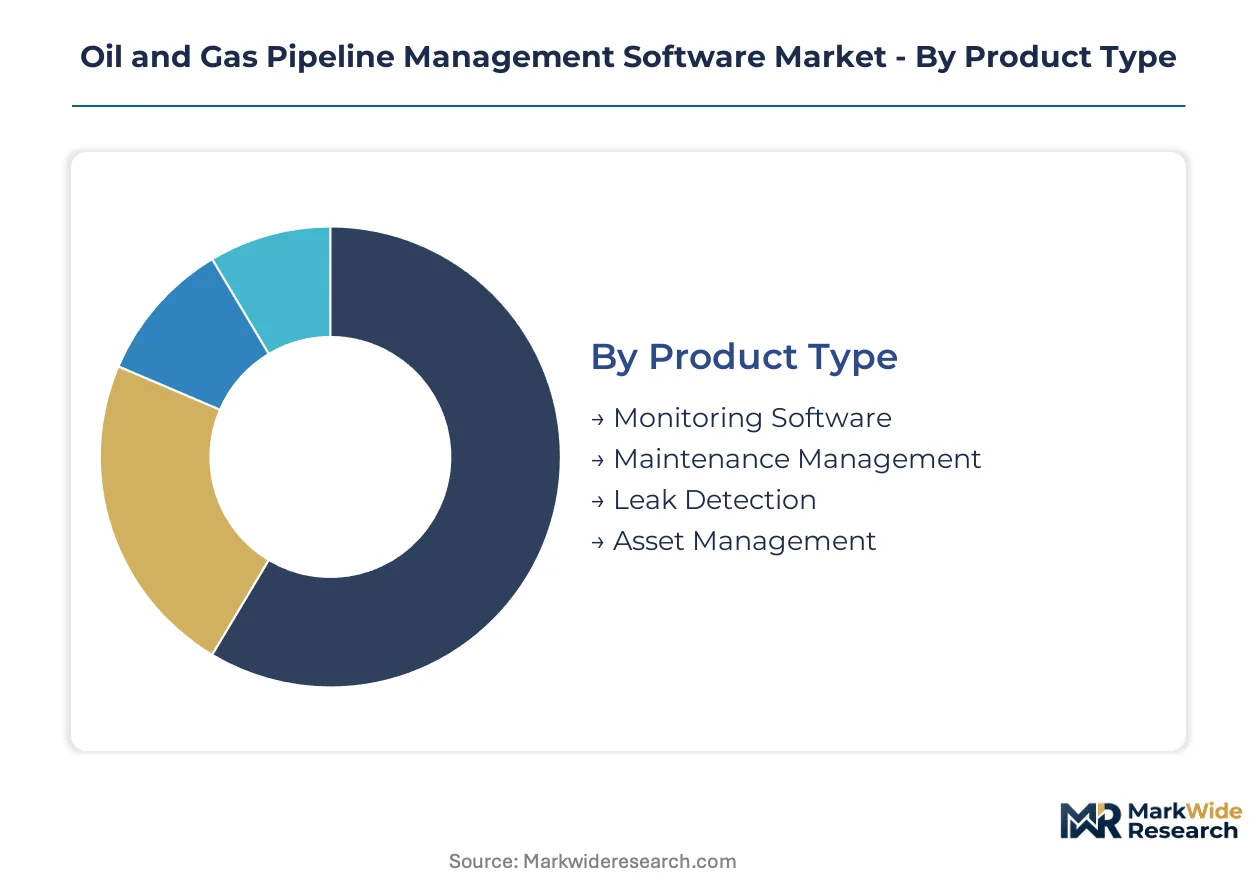
Pipeline management software segments diverge sharply by integration depth. Standalone monitoring platforms dominate brownfield retrofits, while embedded analytics modules penetrate new compressor station builds. Procurement patterns split between capital-intensive perpetual licenses and recurring SaaS subscriptions, reshaping vendor revenue recognition across each category.
Product Type:
Integration depth varies dramatically across product categories, with monitoring software typically deployed as standalone SCADA overlays while asset management modules embed deeply within enterprise ERP architectures.
- Monitoring Software:Real-time pressure, flow, and temperature surveillance systems ingesting sensor data through OPC-UA or Modbus protocols. PHMSA Part 195 mandates in the United States drive replacement cycles for manual inspection regimes among Permian Basin operators facing documented anomaly response requirements.
- Asset Management:Enterprise platforms correlating corrosion data, inspection histories, and replacement schedules into unified integrity dashboards. Gas distributors in Texas and Oklahoma prefer subscription pricing for these modules, prioritizing operational expenditure treatment over capital-intensive perpetual licenses.
- Maintenance Management:Work order automation and resource scheduling systems for pipeline crews.
- Leak Detection:Acoustic signature analysis and computational pipeline monitoring algorithms.
Monitoring software leads volumes today; asset management is gaining share fastest through subscription renewal structures.
Deployment:
Cost tier stratification separates sovereign-data national oil companies from elastic-compute gas distributors facing seasonal demand spikes.
- Cloud-Based:Elastic infrastructure scaling compute resources during peak throughput periods without permanent hardware commitment. Midstream operators in shale corridors deploy this architecture fastest, driven by private equity-backed aggregators prioritizing cash flow predictability over ownership economics.
- On-Premise:Air-gapped installations maintaining complete data sovereignty within operator-controlled facilities. National oil companies with cybersecurity certification requirements under NERC CIP retain dominance here, accepting higher capital burdens for compliance assurance.
- Hybrid:Split architectures keeping critical control functions local while pushing analytics to cloud tiers.
- SaaS:Fully managed subscription platforms with bundled update cycles and vendor-operated infrastructure.
On-premise retains revenue concentration today; cloud-based deployments are climbing the fastest among independent midstream buyers.
End User:
Application maturity separates vertically integrated producers from specialized engineering contractors.
- Pipeline Operators:Direct owners of transmission and gathering infrastructure requiring integrated SCADA-GIS platforms. United States-based operators retiring 1980s-era systems in the Permian Basin generate replacement demand for predictive corrosion models and automated compliance dashboards.
- Gas Distributors:Local distribution companies managing last-mile delivery networks. These buyers in Texas and Oklahoma are shifting procurement toward SaaS asset integrity modules, treating software spend as operational rather than capital expenditure.
- Oil Producers:Upstream operators focused on gathering system optimization.
- Engineering Firms:EPC contractors specifying platforms for greenfield construction projects.
Pipeline operators dominate procurement volumes today; gas distributors are expanding most quickly through subscription adoption.
Application:
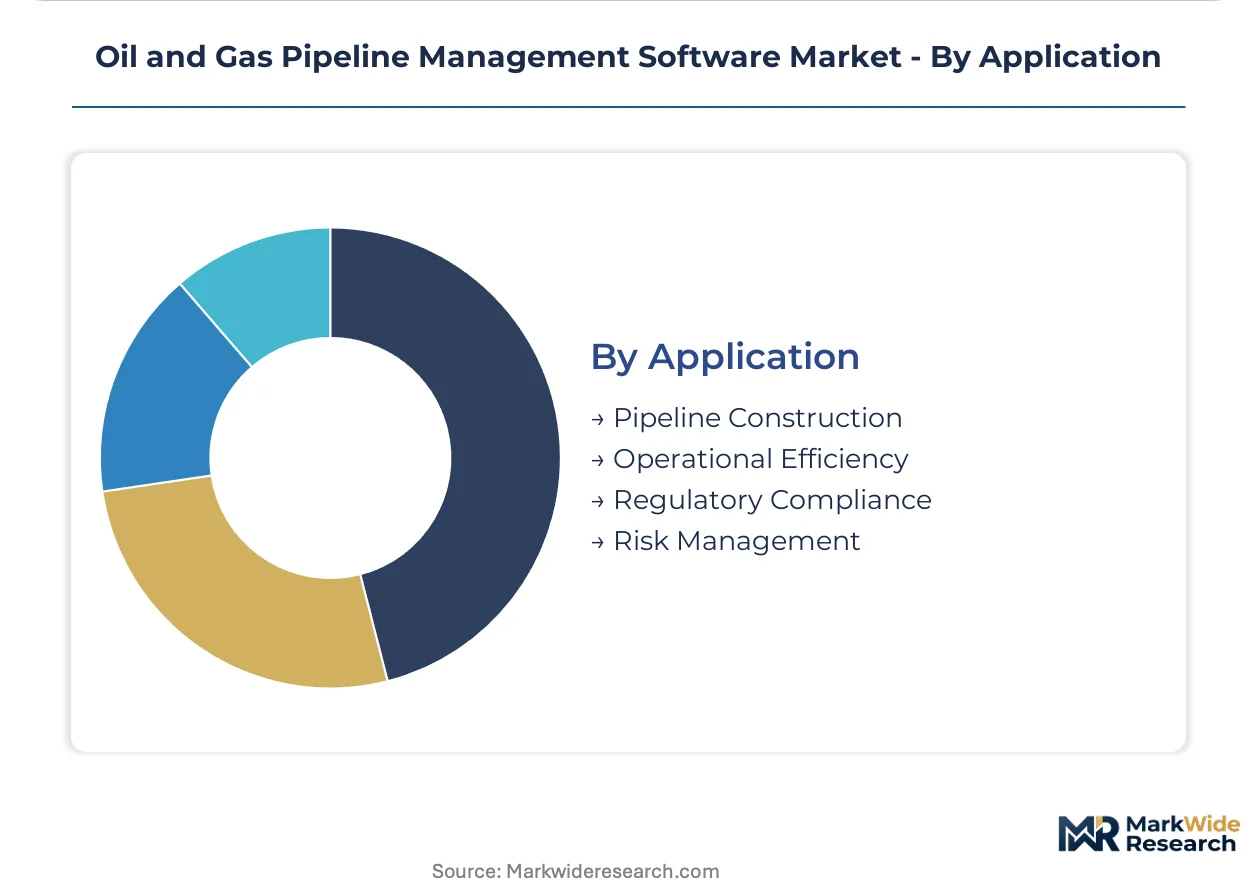
Regulatory pressure intensity separates mandatory compliance spend from discretionary efficiency investments.
- Regulatory Compliance:Documented risk assessment, anomaly response protocol, and audit trail modules satisfying PHMSA Part 195 and Part 192 requirements. United States operators face mandatory continuous surveillance rules, stimulating dedicated procurement for compliance-oriented software dashboards.
- Operational Efficiency:Throughput optimization, energy consumption reduction, and predictive maintenance scheduling. Shale infrastructure renewal in Texas and New Mexico creates demand for integrated platforms embedding real-time physics simulations without interrupting live flow.
- Pipeline Construction:Project management and commissioning tools for greenfield builds.
- Risk Management:Scenario modeling and consequence analysis for integrity decisions.
Regulatory compliance leads mandatory spend today; operational efficiency is expanding most quickly through digital twin adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline corridor anchors procurement intensity for integrated SCADA-GIS platforms, with shale operators retiring legacy gathering systems and deploying predictive corrosion models at scale.
United States
Texas and New Mexico shale corridors drive replacement cycles for 1980s-era infrastructure, with private equity-backed aggregators prioritizing SaaS asset integrity modules. PHMSA Part 195 mandates continuous pressure monitoring and documented anomaly response protocols, compelling automated compliance dashboard procurement. The Permian Basin and Eagle Ford formations concentrate deployment of edge-computing leak detection architectures.
Germany
Natural gas transmission operators pilot hydrogen pipeline repurposing software, modeling embrittlement risks in converted infrastructure under EU Green Deal timelines. The EU F-Gas Regulation mandates quantified methane venting reporting for pipelines above 7 megawatts thermal input, forcing satellite-ground sensor fusion into unified regulatory filings. The Ruhr industrial corridor and North Sea pipeline terminals anchor vendor platform localization efforts.
China
National oil companies with sovereign data requirements retain dominance of on-premise installations, accepting higher capital burdens for cybersecurity assurance under GB/T certification schemes. The dual carbon goals accelerate methane quantification technology deployment across West-East Gas Pipeline corridors. The Sichuan-Chongqing shale basin and Xinjiang production clusters generate demand for predictive maintenance modules embedding real-time physics simulations.
India
The Petroleum and Natural Gas Regulatory Board's 33,000 km pipeline buildout attracts SaaS providers localizing platforms for Hindi-language interfaces and domestic cloud sovereignty requirements. BIS standards and PLI scheme incentives shape procurement specifications for integrated monitoring systems. The Mumbai High offshore complex and Gujarat industrial corridor concentrate early deployment of subscription-based asset management modules.
Canada
Alberta oil sands operators face methane reduction mandates from federal regulations, stimulating demand for emissions quantification software tied to satellite monitoring networks. Health Canada and provincial regulators enforce pipeline integrity documentation requirements comparable to PHMSA frameworks. The Calgary-D Edmonton corridor and Fort McMurray production zone anchor procurement of hybrid cloud-on-premise architectures for seasonal throughput scaling.
Oil and Gas Pipeline Management Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native analytics and hydrogen-transition tooling. The market structures around three tiers: diversified industrial conglomerates with electrification portfolios, specialized automation vendors with deep OT integration expertise, and cloud-native challengers attacking compliance-as-a-service segments. Strategic moves concentrate on modularizing legacy platforms to escape single-vendor lock-in, and on acquiring materials science capabilities for hydrogen pipeline repurposing.
Within the diversified industrial tier, Schneider Electric, Siemens AG, and Emerson Electric exemplify platform consolidation strategies. These Paris-based, Munich-based, and St. Louis-based conglomerates anchor integrated automation suites through embedded analytics and predictive maintenance modules. Their positioning reflects a shift from monolithic SCADA contracts toward API-first architectures that system integrators can assemble into multi-vendor ecosystems.
| Leading Market Players |
|---|
| Schneider Electric |
| Honeywell International |
| Siemens AG |
| Emerson Electric |
| ABB Ltd |
| General Electric Company |
| Rockwell Automation |
| Yokogawa Electric Corporation |
| AVEVA Group |
| Others |
Value Network & Pricing Analysis
Midstream operators in Texas and Oklahoma anchor pricing power through subscription-based procurement, compressing perpetual license premiums as private equity-backed aggregators prioritize operational expenditure treatment over capital ownership.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and specialized OT engineering talent scarcity shapes vendor margin structures. Three-tier pricing separates enterprise-grade SCADA suites with embedded predictive analytics from mid-market monitoring overlays and entry-level compliance modules. Price differentiation rests on certification depth under PHMSA Part 195 and API 1165 standards versus basic anomaly logging. Margins are tightening due to modularization pressure from system integrators assembling multi-vendor stacks. Independent gas distributors exhibit highest price sensitivity, while national oil companies with sovereign data requirements accept premium tiers for air-gapped installations.
Supply Chain Analysis
India's PLI scheme and domestic-content mandates for critical infrastructure software are reshaping vendor localization strategies across the Asia-Pacific corridor. Engineering talent concentrates in the United States, Germany, and India, with control systems expertise anchored in St. Louis, Munich, and Bangalore clusters. Component dependencies span ruggedized edge gateways, satellite communications modules, and corrosion-resistant sensor housings. Single-source vulnerability runs through proprietary IoT protocol stacks from LoRaWAN and private 5G equipment vendors. Distribution runs through direct enterprise sales teams for national oil companies and channel partners serving independent midstream aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with PHMSA Part 195 integrity mandates forcing replacement cycles that outpace discretionary capital freezes.
For Market Incumbents: Anchor platform consolidation through API-first architectures that system integrators can assemble into multi-vendor ecosystems, escaping single-source SCADA lock-in erosion. Defend against cloud-native challengers by modularizing legacy Experion and Ovation suites into subscription-tiered compliance-as-a-service offerings. Deepen materials science partnerships for hydrogen embrittlement modeling ahead of European pipeline repurposing timelines.
For New Entrants and Emerging Players: EU F-Gas Regulation amendments in Germany and the Netherlands open a window for satellite-ground sensor fusion platforms automating methane quantification reporting. Target SaaS asset integrity modules for Texas and Oklahoma gas distributors treating software spend as operational expenditure. Penetrate through Hindi-language localization and domestic cloud sovereignty compliance for India's 33,000 km pipeline buildout.
For Investors and Strategic Acquirers: Industrial automation conglomerates with electrification portfolios are the most active acquirers in this space, seeking edge-native analytics capabilities and hydrogen-transition tooling. Long-term viability rests on regulatory compliance compounding rather than cyclical energy prices. Watch for inflection signals in European hydrogen pipeline pilot awards and PHMSA anomaly response protocol enforcement actions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Modularization | API-first architectures dismantle single-vendor SCADA lock-in, enabling system integrator assembly. |
| Hydrogen Transition Tooling | Materials science integration for embrittlement risk modeling captures European repurposing demand. |
| Edge Computing Convergence | Distributed inference engines on compressor stations eliminate satellite latency for leak detection. |
| Regulatory Compliance Automation | PHMSA Part 195 dashboards transform mandatory anomaly response into recurring subscription revenue. |
| Geographic Localization | Hindi-language interfaces and domestic cloud sovereignty unlock India's national gas grid expansion. |
Research Methodology
Bottom-up pipeline operator procurement modeling reconciled against top-down vendor revenue tracking forms the analytical core. Primary interviews with SCADA integration specialists, PHMSA compliance officers, midstream engineering directors, and private equity operating partners supply demand-side calibration. Secondary validation draws from PHMSA enforcement databases, API standards documentation, FERC pipeline filings, and EIA infrastructure surveys. Triangulation between deployment volume estimates and disclosed platform subscription metrics ensures segmentation integrity.
Historical trendline analysis of SCADA replacement cycles and cloud migration patterns establishes baseline growth parameters. The projection horizon spans product type segmentation across monitoring software, asset management, and leak detection modules; deployment models from on-premise through SaaS; and end-user categories separating pipeline operators from gas distributors. CAGRs derive from regression against integrity management spend intensity and regulatory enforcement frequency. Forecast inputs incorporate edge computing adoption curves and hydrogen pipeline pilot conversion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cybersecurity certification divergence and OT talent scarcity constraints. Assumptions reflect sustained PHMSA enforcement continuity and EU Green Deal methane quantification timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Coal Mining Market
Oil & Gas
Turkmenistan Oil and Gas Market
Oil & Gas
Middle-East Completion Equipment and Services Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
North America Completion Equipment and Services Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Russia Drill Pipe Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Downhole Equipment Market
Oil & Gas
Unconventional Gas Market