
 Floating Storage and Regasification Unit Market | 2026-2036
Floating Storage and Regasification Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Storage and Regasification Unit Market Intelligence
Market Context
Buyer concentration among utility off-takers is consolidating as national energy champions in emerging markets aggregate LNG procurement through long-term FSRU charters rather than spot-market exposure. Excelerate Energy leverages its integrated project development model to control terminal delivery timelines from vessel conversion through commissioning. Höegh LNG anchors the competitive landscape with the largest operational FSRU fleet and established relationships with creditworthy utility counterparties across multiple continents. Keppel Offshore & Marine competes through its Singapore-based shipyard dominance in LNG carrier and FSRU newbuild and conversion work.
Technical Definition and Structural Segments
A floating storage and regasification unit is a marine vessel or barge equipped with LNG containment systems—typically membrane-type cargo tanks operating at near-atmospheric pressure and cryogenic temperatures below minus 160 degrees Celsius—and onboard regasification skids that vaporize liquid natural gas for direct injection into shoreside pipelines or power generation facilities. Membrane-type containment dominates new FSRU construction due to superior volumetric efficiency and compatibility with both storage and regasification operational profiles, while Moss-type spherical tanks persist in legacy conversions where structural reinforcement costs constrain economic retrofit decisions. Large-scale units above 200,000 cubic meters command premium charter rates from utility end users seeking baseload supply security, though small-scale and modular configurations are gaining traction among industrial consumers in island and remote coastal markets where infrastructure minimalism reduces capital commitment.
Regulatory Framework and Outlook
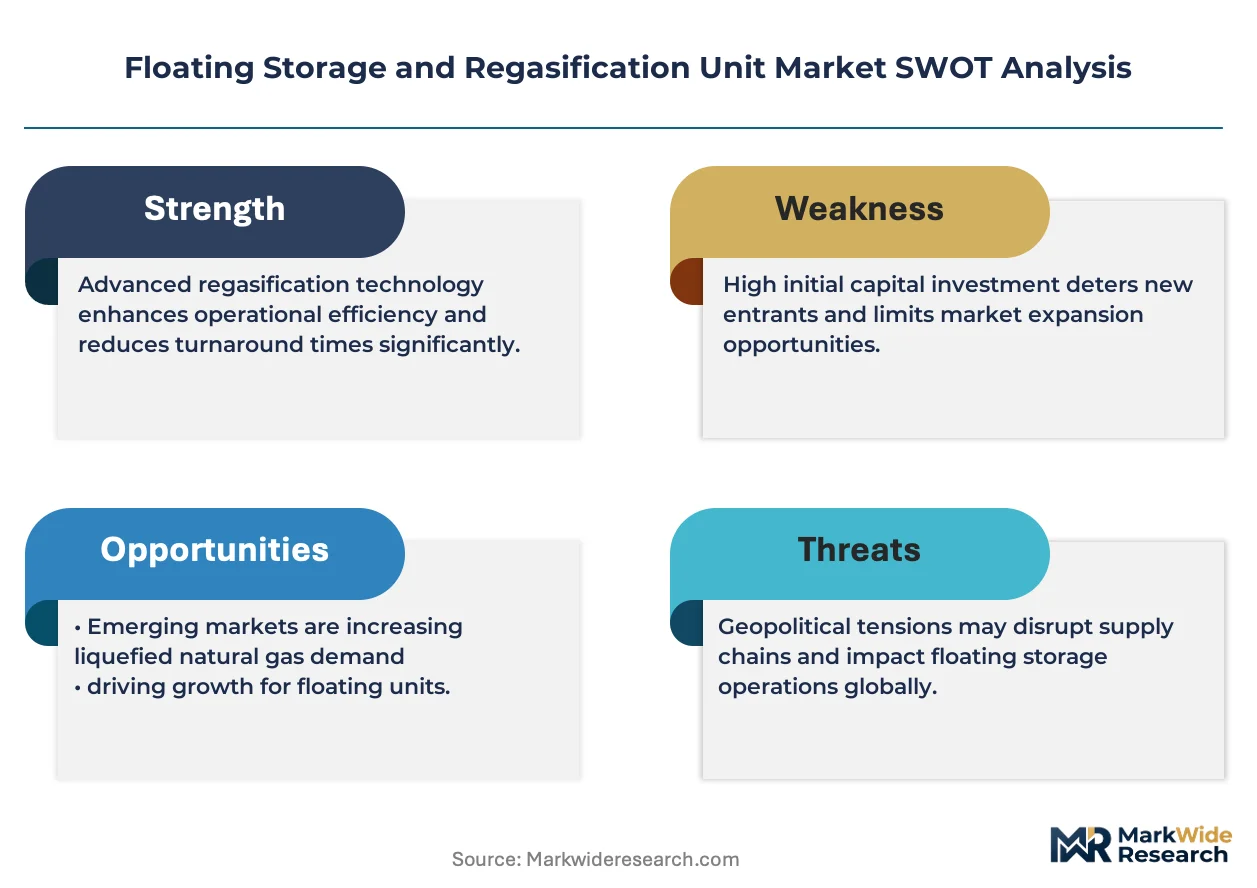
The International Maritime Organization's Energy Efficiency Existing Ship Index and Carbon Intensity Indicator regulations are reshaping FSRU operational economics by penalizing vessels with poor emissions profiles, while the EU's Methane Regulation imposes measurement, reporting, and verification requirements on LNG imports that extend to floating terminal operations in European waters. Classification societies including DNV and Bureau Veritas have tightened prescriptive rules for cryogenic containment system integrity and regasification module safety integration, elevating compliance costs for new entrants. Stakeholders must monitor evolving carbon border adjustment mechanisms and methane intensity benchmarks that threaten to bifurcate charter demand between low-emission FSRU assets and legacy vessels facing accelerated obsolescence.
Market Dynamics
The International Maritime Organization's carbon intensity regulations are compressing vessel economics and forcing charterers toward dual-fuel propulsion systems, fundamentally altering asset valuation and deployment strategies across the FSRU fleet.
Growth Catalysts
- IMO CII Compliance Pressure:The Carbon Intensity Indicator mandates annual efficiency improvements, driving utilities to favor modern FSRU assets with lower emissions profiles over legacy tonnage.
- Coal-to-Gas Substitution:Bangladesh, Pakistan, and Vietnam are accelerating LNG import infrastructure to displace coal-fired baseload generation, creating immediate demand for rapid-deployment floating terminals.
- Membrane Containment Dominance:GTT Mark III and NO96 membrane systems deliver superior volumetric efficiency versus Moss spherical tanks, reducing unit cargo capacity costs for newbuild FSRU projects.
Market Restraints
- Shipyard Capacity Bottleneck:South Korean and Singaporean yards command premium pricing for LNG-qualified newbuild slots, extending delivery timelines to 36-48 months and inflating capital commitments.
- Specialized Labor Scarcity:Cryogenic welding and regasification system commissioning require certified technicians whose global pool remains concentrated in fewer than twelve maritime training centers.
- Pipeline Interconnection Delays:Shoreside infrastructure permitting in emerging markets often lags vessel readiness, stranding FSRU capacity and inflating standby charter costs.
Strategic Opportunities
- Small-Scale Island Markets:Caribbean and Pacific island utilities present untapped demand for modular barge-mounted regasification units below 50,000 cubic meters, bypassing large-scale terminal economics.
- EU Methane Regulation Alignment:The EU's measurement, reporting, and verification framework for LNG imports creates first-mover advantage for FSRU operators deploying continuous emissions monitoring systems.
- Bunkering Integration:Dual-fuel FSRU designs enabling simultaneous cargo discharge and LNG bunkering operations are converging with port authority demand for maritime refueling infrastructure.
Industry Challenges
- Cryogenic Certification Timelines:Classification society review cycles for containment system modifications have extended to 14-18 months, compressing project commissioning windows.
- Utility Creditworthiness Assessment:Emerging market offtakers present heterogeneous sovereign risk profiles, complicating long-term charter financing and requiring enhanced political risk insurance structures.
- Regasification-Supply Chain Coordination:Synchronizing vessel delivery with floating storage unit availability and subsea pipeline completion demands multi-party project management capabilities few charterers possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Storage and Regasification Unit Market |
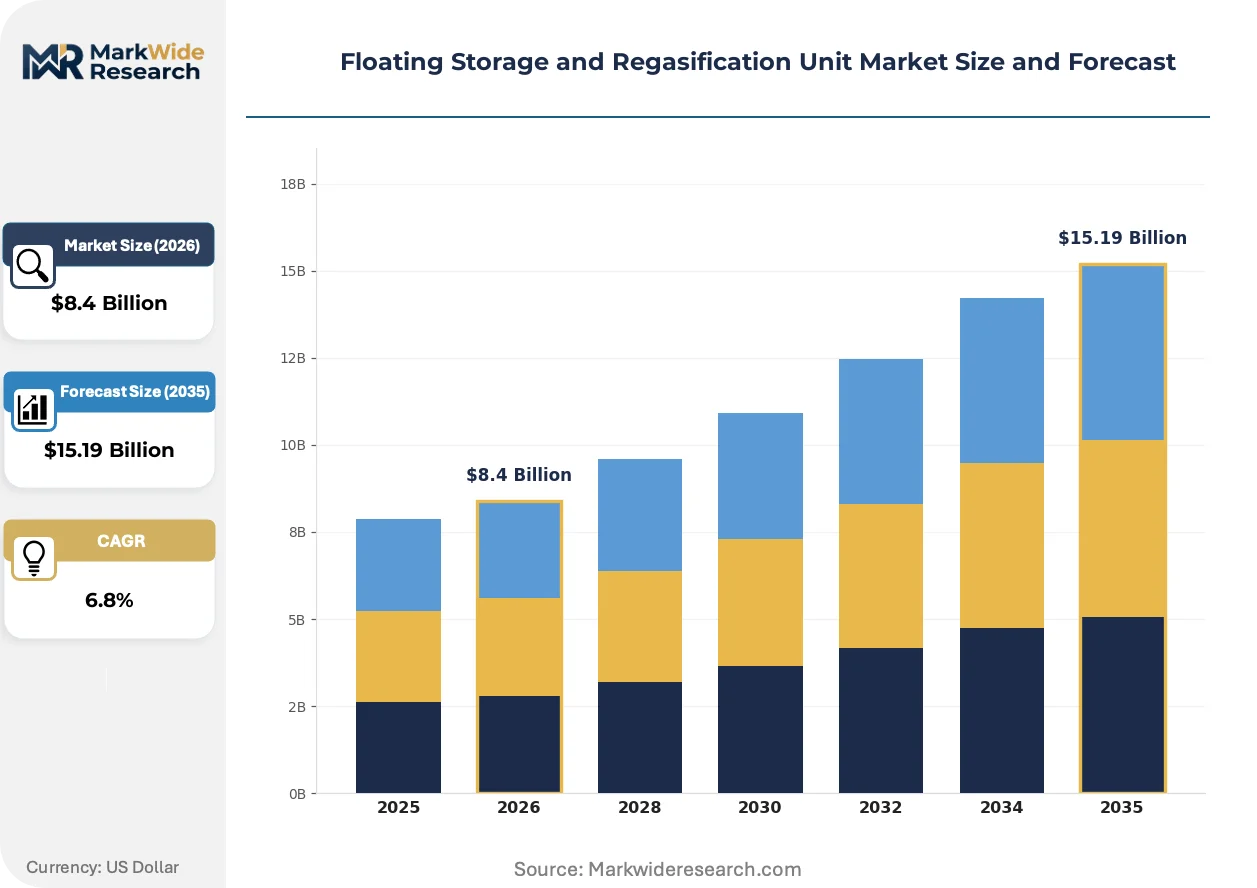
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Type, Moss Type, SPB Type, FSRU with LNG Storage Capacity: Small Scale, Medium Scale, Large Scale, Floating Units End User: Utilities, Industrial Consumers, LNG Traders, Exporters Technology: Conventional, Regasification, Integrated Systems, Modular |
| Companies Covered | BW LPG, Exmar, Excelerate Energy, Keppel Offshore & Marine, Mitsui & Co., Höegh LNG, FLEX LNG Management, Cosco Shipping International, Golar LNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Storage and Regasification Unit Market Strategic Shifts & Innovations
Digital twin technology and predictive maintenance systems are penetrating FSRU operations, while regulatory pressure on methane emissions and vessel efficiency is accelerating propulsion system upgrades and operational transparency requirements.
Integrated automation platforms combining process control systems with machine learning-based cargo monitoring are converging with remote operations center deployment, enabling shore-based supervision of regasification processes. Major utility charterers in Southeast Asia are mandating these systems for new fixtures, compressing the competitive gap between integrated operators and vessel-only providers. The technology is converging with satellite connectivity improvements to reduce onboard manning requirements and shift operational economics toward capital-light management models.
The EU Methane Regulation imposes granular emissions accounting on LNG imports, extending verification obligations to floating terminal operations in European waters. Industrial consequence includes mandatory leak detection and repair protocols, continuous emissions monitoring equipment installation, and third-party verification of cargo custody transfer measurements. FSRU assets serving Italian, Greek, and German terminals are most affected, with operators retrofitting infrared cameras and quantification sensors to maintain charter eligibility.
Utility procurement departments are consolidating LNG procurement through national energy champions, aggregating demand into multi-year FSRU charters rather than maintaining spot-market exposure. This pattern displaces fragmented utility tendering with centralized offtake negotiations, compressing the vendor base accessible to independent terminal developers. The shift is most visible across Bangladesh, Pakistan, and Vietnam, where state-owned power utilities now control import infrastructure deployment timelines and vessel specification requirements.
Floating Storage and Regasification Unit Market Segmentation
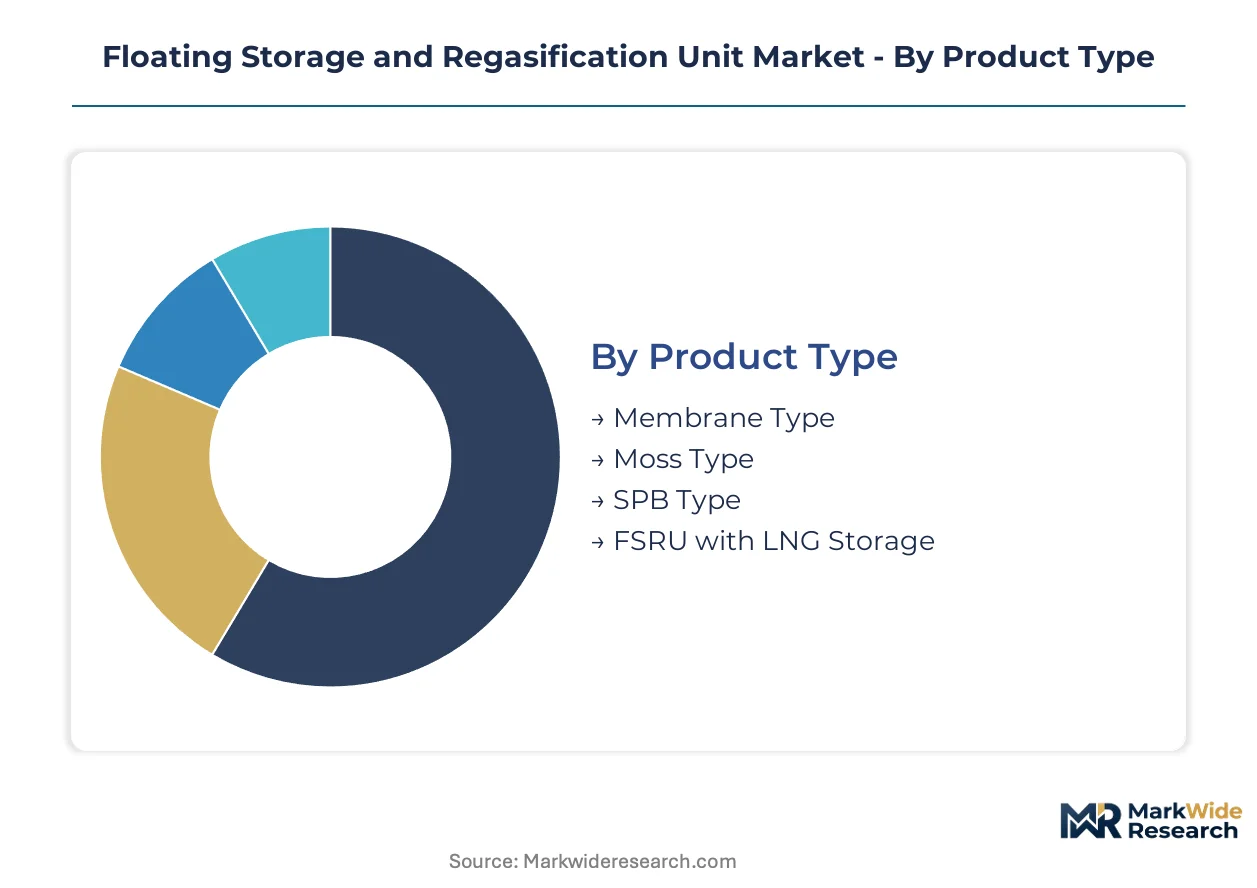
FSRU procurement decisions hinge on containment technology, throughput scale, and end-use configuration. Each segment carries distinct capital requirements, operational complexity, and charter rate structures that reshape fleet deployment economics.
Product Type:
Capital intensity varies sharply across containment architectures, with membrane systems demanding specialized shipyard infrastructure but delivering superior volumetric returns.
- Membrane Type:GTT-licensed membrane tanks employ corrugated stainless steel or Invar primary barriers with secondary foil insulation, maximizing cargo volume within hull constraints. Bangladesh and Vietnam utilities specify membrane FSRUs exclusively for baseload power projects where cargo efficiency determines project returns. Newbuild contracts for membrane units absorb 60-70% of shipyard commissioning schedules.
- Moss Type:Spherical aluminum tanks suspended in hull void spaces offer structural simplicity and reduced insulation complexity. Legacy LNG carriers converted to FSRU service retain Moss containment where hull reinforcement costs would exceed membrane retrofit economics. Pakistan's second FSRU deployment utilized Moss-type conversion to accelerate commissioning.
- SPB Type:Self-supporting prismatic tanks with independent cargo boundaries suit barge-mounted applications requiring structural rigidity.
- FSRU with LNG Storage:Hybrid configurations integrating dedicated storage alongside regasification skids address markets with intermittent supply patterns.
Most installed capacity flows through Membrane Type. Expansion is steepest in FSRU with LNG Storage.
Capacity:
Throughput scale determines charter rate tiers and utility offtake commitment structures, with large-scale units commanding decade-long contracts.
- Large Scale:Units exceeding 200,000 cubic meters serve national grid injection and combined-cycle power blocks exceeding 1,500 MW. State-owned utilities in Vietnam anchor demand for large-scale FSRUs where single-vessel supply security displaces multi-terminal fragmentation.
- Small Scale:Modular barge-mounted systems below 50,000 cubic meters target island utilities and industrial parks with constrained jetty infrastructure. Caribbean power cooperatives drive small-scale adoption where pipeline interconnection proves economically unviable.
- Medium Scale:Mid-range configurations balance capital efficiency with operational flexibility for seasonal demand peaks.
- Floating Units:Non-propelled barge designs eliminate propulsion capital for permanent mooring applications.
Large Scale absorbs the majority of committed capital. Small Scale is climbing the fastest as distributed generation spreads.
End User:
Creditworthiness and procurement centralization patterns fragment demand across utility, industrial, and trading counterparties.
- Utilities:State-owned power generation companies aggregate national LNG demand into sovereign-backed FSRU charters. Bangladesh Power Development Board and Pakistan State Oil centralize procurement, compressing vendor access for independent developers.
- Industrial Consumers:Fertilizer, petrochemical, and steel producers seek dedicated small-scale FSRU moorings to bypass grid gas pricing. Vietnamese industrial zones along the Cai Mep corridor are negotiating direct regasification supply.
- LNG Traders:Portfolio players charter FSRU capacity for arbitrage and short-term supply optimization.
- Exporters:Upstream liquefaction projects deploy FSRUs as temporary loading solutions during terminal construction.
Utilities dominate committed charter tonnage. Industrial Consumers are gaining share fastest as zone-based energy parks proliferate.
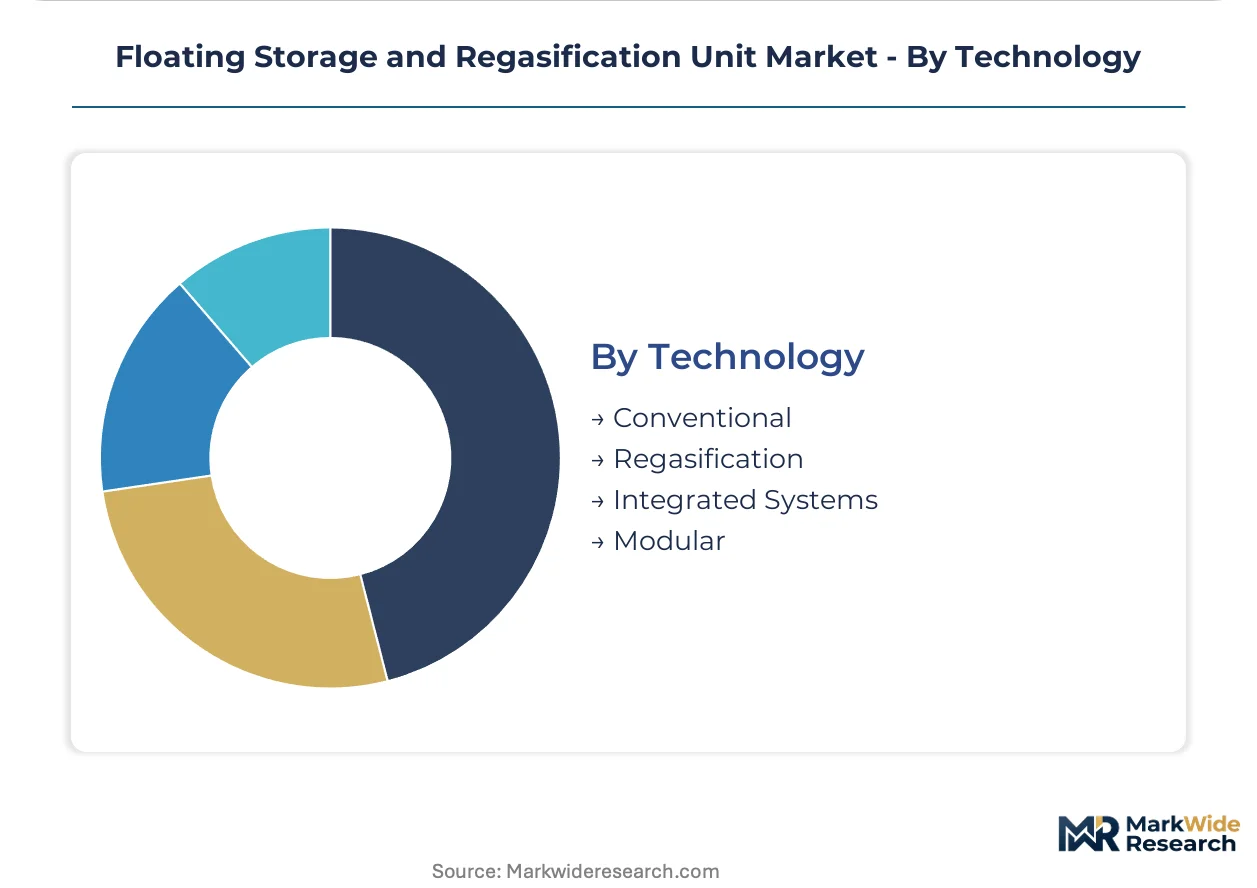
Technology:
System integration depth shapes operational manning requirements and maintenance cost profiles across the technology spectrum.
- Integrated Systems:Unified process control architectures combining cargo handling, regasification, and boil-off gas management reduce onboard crew complements. Southeast Asian utilities now mandate integrated automation for new fixtures.
- Modular:Skid-mounted regasification packages enable rapid redeployment between sites and standardized maintenance protocols. Remote coastal markets in Indonesia and the Philippines favor modular designs for logistics simplicity.
- Conventional:Segregated mechanical and electrical systems persist in legacy conversions where upgrade economics prove marginal.
- Regasification:Stand-alone vaporization-focused configurations serve markets with separate storage infrastructure.
Integrated Systems anchor newbuild specifications. Modular is expanding most quickly for redeployment flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangladesh deploys FSRU capacity faster than Pakistan despite similar grid constraints, while Vietnam accelerates import infrastructure to fuel southern industrial zones. Utility procurement centralization and coastal access determine deployment velocity across emerging Asian markets.
Bangladesh
The Bangladesh Power Development Board aggregates LNG demand through sovereign-backed charters at Moheshkhali and Payra. The government's Power System Master Plan mandates gas-fired generation expansion through 2030. Cox's Bazar anchors offshore mooring infrastructure where Excelerate Energy operates the nation's first FSRU terminal.
Pakistan
Port Qasim Authority manages FSRU moorings serving Karachi's grid-deficient power corridor. The National Electric Power Regulatory Authority oversees LNG terminal tariffs under the 2015 LNG Policy. Engro Elengy operates the country's second FSRU deployment utilizing Moss-type containment for accelerated commissioning.
Vietnam
PetroVietnam Gas centralizes LNG procurement for the Thi Vai and Son My terminals in Ba Ria-Vung Tau province. The Ministry of Industry and Trade's Power Development Plan VIII prioritizes gas-to-power substitution for coal baseload. The Cai Mep industrial corridor drives small-scale FSRU demand from steel and petrochemical off-takers.
Indonesia
PLN subsidiaries charter FSRU capacity across Java-Bali and eastern archipelago markets lacking pipeline interconnectivity. The Ministry of Energy and Mineral Resources regulates LNG import licensing under the 2009 Oil and Gas Law. The Java Sea and Sulawesi clusters favor modular barge-mounted regasification for distributed generation.
Philippines
First Gen Corporation and Aboitiz Power pursue FSRU moorings at Batangas Bay to displace Malampaya field decline. The Department of Energy's LNG terminal guidelines require open-access regasification infrastructure. The Luzon grid deficiency concentrates demand in Batangas and Quezon provinces.
Floating Storage and Regasification Unit Market Key Industry Players
Singapore-based shipyards anchor one tier; Norwegian and US operators hold chartering and project development specializations. Market structure concentrates around integrated vessel owners with captive shipyard relationships and utility-facing charter specialists. Three archetypes dominate: fleet-scale operators controlling multiple FSRU assets, conversion-focused shipyards with membrane containment expertise, and project developers aggregating offtake contracts. Competitive dynamics center on long-term charter tenor extension and dual-fuel propulsion retrofit acceleration.
Among Norwegian fleet operators, Höegh LNG exemplifies the scale-driven archetype through operational FSRU concentration across multiple continents. Excelerate Energy occupies the integrated project developer position, controlling terminal delivery timelines from vessel sourcing through utility commissioning. Keppel Offshore & Marine represents the Asia-Pacific shipyard tier, leveraging Singapore-based construction dominance for newbuild and conversion contracting. These three entities illustrate how geographic specialization and capability stacking determine competitive positioning.
| Leading Market Players |
|---|
| BW LPG |
| Exmar |
| Excelerate Energy |
| Keppel Offshore & Marine |
| Mitsui & Co. |
| Höegh LNG |
| FLEX LNG Management |
| Cosco Shipping International |
| Golar LNG |
| Others |
Cost & Logistics Intelligence
Utility off-taker concentration among Bangladesh Power Development Board, Pakistan State Oil, and PetroVietnam Gas anchors long-term charter contracting as the dominant pricing mechanism, compressing spot-market liquidity and elevating vessel specification premiums for integrated project delivery.
Pricing Analysis
Capacity additions in South Korean and Singaporean shipyards are reshaping price floors for membrane-containment newbuilds, forcing charter rate compression on legacy Moss-type conversions. Three-tier pricing structure across premium dual-fuel propulsion, standard single-fuel, and economy conversion tiers differentiates assets by IMO Carbon Intensity Indicator compliance grade. Pricing pressure stems from yard slot scarcity extending delivery timelines. National utilities exhibit lowest price sensitivity due to sovereign-backed procurement, while industrial zone offtakers in Vietnam negotiate hardest on unit cargo costs.
Supply Chain Analysis
Cryogenic welding technician availability in South Korea, Singapore, and Norway constrains commissioning velocity for regasification module integration. Nickel-alloy containment materials, GTT membrane licensing fees, and dual-fuel engine blocks constitute critical input dependencies. Single-source vulnerability concentrates in GTT's membrane technology patents. Distribution runs through utility-led terminal development consortia coordinating vessel delivery with subsea pipeline completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Floating Storage and Regasification Unit Market functions as a stable compounder underpinned by irreversible coal-to-gas substitution mandates across Southeast Asian power development plans.
For Market Incumbents: Hedge against IMO regulatory obsolescence by accelerating dual-fuel propulsion retrofits on legacy tonnage before Carbon Intensity Indicator penalties harden. Secure captive shipyard slots in Singapore through equity partnerships, insulating delivery timelines from Korean yard congestion. Prioritize long-term charter tenor extension with Bangladesh and Vietnam utilities to lock in baseload demand against modular barge-mounted competition. For New Entrants and Emerging Players: Industrial zone developers in Vietnam's Cai Mep corridor represent the most penetrable entry point, bypassing sovereign utility procurement centralization. Caribbean island utilities present secondary white-space demand for sub-50,000 cubic meter modular configurations. Pursue equipment-leasing partnerships with established membrane containment licensors to circumvent GTT licensing barriers. For Investors and Strategic Acquirers: Integrated energy majors with captive LNG portfolios are the most active acquirer in this space, seeking terminal development capabilities to secure offtake routes. Five-to-ten-year viability hinges on methane emissions verification infrastructure alignment with EU regulatory expansion. Acquisition targets should display integrated automation platforms and established utility relationships. Monitor EU Methane Regulation enforcement scope expansion as the critical inflection signal for asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Propulsion Retrofit | IMO Carbon Intensity Indicator compliance preserves charter eligibility with Bangladesh and Vietnam utilities. |
| Membrane Containment Newbuild | GTT Mark III systems maximize cargo efficiency for baseload power projects in emerging Asian markets. |
| Small-Scale Barge Deployment | Modular configurations unlock Caribbean and Pacific island markets lacking pipeline infrastructure. |
| Continuous Emissions Monitoring Installation | EU Methane Regulation alignment secures European terminal access for Italian and Greek moorings. |
| Integrated Automation Platform Deployment | Machine learning-based cargo monitoring reduces manning costs and satisfies Southeast Asian utility mandates. |
Research Approach
Bottom-up utility procurement modeling reconciled against top-down shipyard orderbook tracking forms the analytical core of this study. Primary interviews with FSRU project developers, utility planning officers, shipyard commercial managers, and classification society surveyors combined with secondary validation from Lloyd's List vessel databases, IMO regulatory filings, and national power development plans. Trade flow analysis of LNG carrier-to-FSRU conversions and newbuild contracting patterns anchored supply-side calibration.
Input-output matrices mapped containment technology selection, capacity tier deployment, and end-user creditworthiness against charter rate formation across the projection horizon. Segmentation dimensions encompassed membrane versus Moss versus SPB containment architectures, large-scale versus small-scale throughput configurations, utility versus industrial versus trader offtake structures, and integrated versus modular technology systems. CAGRs derived from vessel delivery schedules, regasification capacity commissioning timelines, and national gas demand projections. Forecast inputs included shipyard slot availability, cryogenic certification review cycles, and pipeline interconnection permitting velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO regulatory stringency evolution and EU carbon border adjustment mechanism expansion. Forecasts reflect documented assumptions regarding utility procurement centralization persistence and membrane containment technology dominance. Material deviation in methane emissions verification enforcement scope or South Korean shipyard labor availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Offshore Drilling Riser Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Denmark Oil and Gas Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Floating Liquefied Natural Gas (FLNG) Market
Offshore Oil and Gas
FPSO Market