
 Abyssinian Oil Market | 2026-2036
Abyssinian Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Abyssinian Oil Market Outlook
A capital-intensity divergence between integrated seed processors and toll refiners is rotating competitive advantage toward upstream asset holders. Croda International leverages captive cultivation partnerships across temperate growing regions to secure feedstock consistency. Henry Lamotte Oils anchors its position through ISO-certified cold-press infrastructure that sustains oxidative stability metrics below industry thresholds. Nature's Crops International specializes in identity-preserved supply chains that dominate premium cosmetic ingredient channels.
Abyssinian oil is a long-chain mono-unsaturated vegetable oil extracted from Crambe abyssinica seeds, characterized by over 50% erucic acid content and a smoke point exceeding 230°C that suits high-heat food processing and lubricant formulations. Refined oil commands the largest value share due to downstream formulation flexibility in cosmetics and pharmaceutical excipients, while organic oil segments are pulling fastest volume growth from clean-label personal care brands. Direct sales channels concentrate margin pools through long-term supply agreements with multinational formulators, though online platforms are fragmenting procurement access for mid-tier buyers.
REACH registration requirements in Europe and FDA cosmetic ingredient guidelines in the United States impose compositional disclosure thresholds that filter non-compliant suppliers from premium market tiers. ECHA substance evaluations and USDA organic certification protocols are tightening traceability documentation, elevating compliance costs for smaller exporters. Stakeholders must monitor evolving biofuel blending mandates and renewable diesel feedstock classifications that could redirect oilseed crush capacity away from cosmetic and food-grade channels.
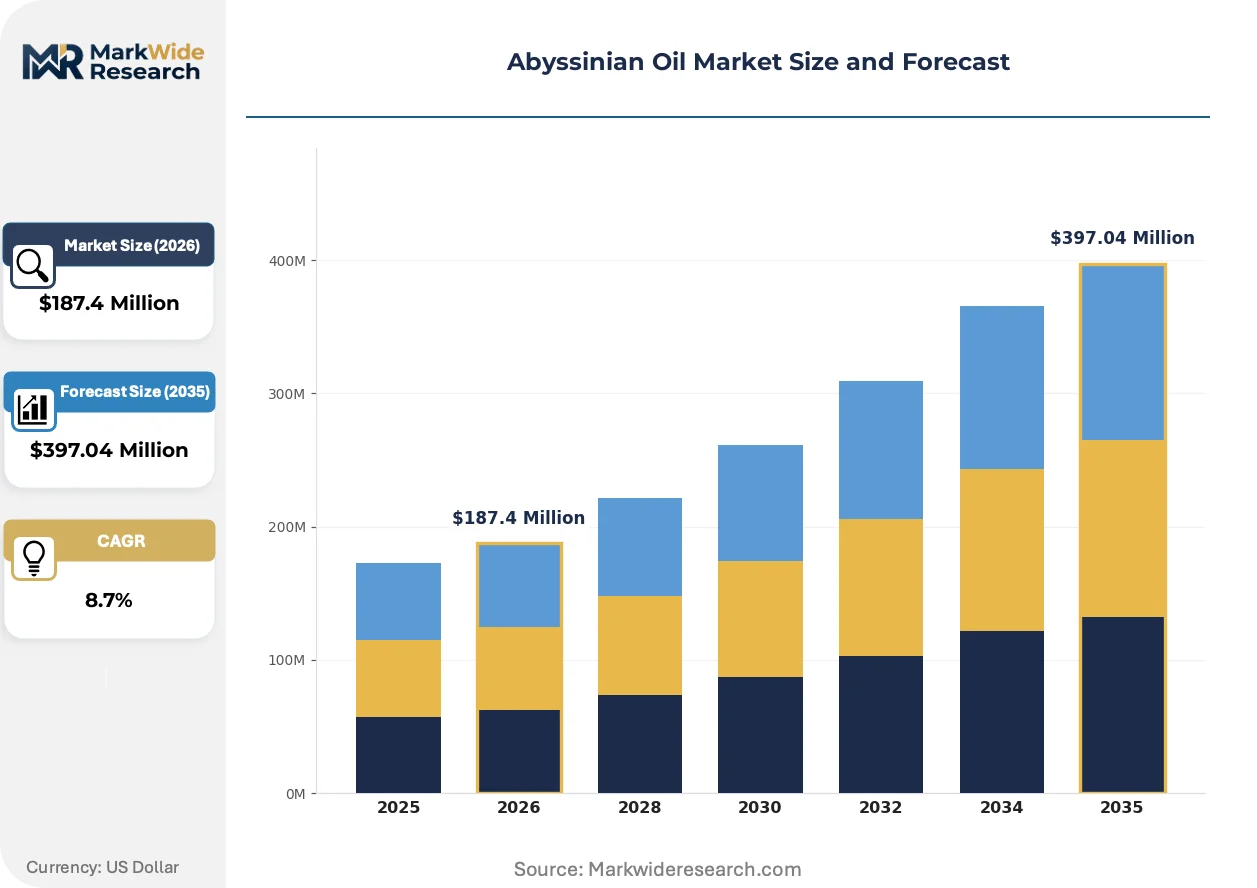
Market Dynamics
Seed oil processors are consolidating crushing capacity around identity-preserved supply chains to meet REACH-mandated traceability requirements for cosmetic-grade Abyssinian oil, compressing margin pools for commodity traders lacking upstream asset control.
Growth Catalysts
- REACH substance evaluation protocols:ECHA's tightening compositional disclosure thresholds filter non-compliant suppliers, concentrating volume with certified processors capable of full chain-of-custody documentation.
- High-heat food processing demand:Abyssinian oil's smoke point exceeding 230°C suits commercial frying and lubricant formulations requiring thermal stability.
- Clean-label personal care:Formulators in the United States are substituting synthetic emollients with cold-pressed organic grades to meet retailer sustainability scorecards.
Market Restraints
- Crambe seed supply concentration:Temperate growing regions in Canada and northern Europe dominate feedstock cultivation, exposing processors to weather-driven yield volatility.
- Erucic acid regulatory ceilings:Food-grade applications face strict residual limits under FDA and EFSA guidelines, restricting refining flexibility.
- Substitute oil competition:Meadowfoam and jojoba oils offer comparable oxidative stability at scale, pressuring price premiums for Abyssinian grades.
Strategic Opportunities
- Biofuel feedstock reclassification:Renewable diesel mandates in the United States and EU Green Deal targets could redirect crush capacity toward energy applications.
- Direct-to-brand digital channels:Indie beauty brands are bypassing distributors through B2B platforms, fragmenting procurement access for mid-tier buyers.
- Pharmaceutical excipient expansion:Refined oil segments are penetrating parenteral and topical drug formulations requiring high-purity lipid bases.
Industry Challenges
- ISO 17025 laboratory certification timelines:Analytical method validation for erucic acid quantification delays market entry for new processors.
- Identity-preserved infrastructure capex:Segregated storage and transport systems require capital deployment that smallholders cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abyssinian Oil Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Refined Oil, Organic Oil, Edible Oil Application: Cosmetics, Food Industry, Pharmaceuticals, Biofuels Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Exporters End User: Personal Care, Food Manufacturers, Healthcare Providers, Biodiesel Producers |
| Companies Covered | Henry Lamotte Oils, Clariant, Tate & Lyle, Croda International, Elementis, Nature's Crops International, Carrubba, Jedwards International, Phyto Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abyssinian Oil Market Strategic Shifts
Cold-press extraction technology is bifurcating competitive advantage between artisanal processors serving premium cosmetic channels and industrial refiners optimizing for volume. Formulation science and regulatory compliance are simultaneously reshaping how value accrues across the supply chain.
Supercritical CO2 extraction is bifurcating the refined oil segment. High-end cosmetic formulators in France and Switzerland are adopting solvent-free methods to preserve heat-sensitive phytosterols. This technology is bifurcating margin pools: processors with installed supercritical capacity command 40-60% price premiums over hexane-extracted alternatives, while conventional refiners face volume compression in premium tiers.
EU Green Deal sustainable sourcing requirements are tightening documentation burdens for imported specialty oils. The Corporate Sustainability Reporting Directive mandates scope 3 emissions disclosure for cosmetic manufacturers, forcing upstream traceability investments. Small exporters in Eastern Europe and Central Asia are consolidating around third-party certification providers to maintain market access.
Long-term supply agreements are displacing spot-market procurement for multinational formulators. Contract manufacturers in the United States are locking in three-to-five-year offtake commitments with integrated seed processors to secure volume certainty. This pattern concentrates in California and New Jersey, where indie beauty clusters rely on predictable feedstock flows for SKU planning.
Abyssinian Oil Market Segmentation
Abyssinian oil value pools fragment across extraction grades, end-use specifications, and procurement channels. Each segment carries distinct margin profiles and regulatory burdens that reshape supplier competitive positioning.
Product Type:
Channel mix varies sharply by refinement level—direct sales dominate pharmaceutical and cosmetic volumes, while commodity traders handle crude oil flows to industrial processors.
- Crude Oil:Unrefined extract retains native erucic acid profiles above 50% and requires further processing before cosmetic or food contact. Biodiesel producers in the United States and industrial lubricant formulators absorb most volume, tolerating higher free fatty acid content in exchange for feedstock cost advantages.
- Refined Oil:Bleached and deodorized grades achieve oxidative stability metrics below industry thresholds, unlocking formulation flexibility across high-performance emulsions and pharmaceutical excipients. Contract manufacturers in New Jersey and California lock in long-term supply agreements for this grade to sustain SKU planning predictability.
- Organic Oil:Cold-pressed certified grades command shelf space at clean-label personal care retailers. USDA organic protocols and EU organic regulations impose segregated handling requirements that filter out non-compliant traders.
- Edible Oil:Food-grade refinement meets FDA and EFSA residual limits for erucic acid, restricting addressable volume to specialty frying and culinary applications where smoke point performance justifies premium positioning.
Refined oil dominates installed base. Organic oil is where expansion concentrates.
Application:
Cost tier stratification separates premium cosmetic formulations from commodity biofuel feedstock, with pharmaceutical applications occupying a high-specification middle ground.
- Cosmetics:Formulators leverage erucic acid's emollient properties in hair serums and facial oils, with supercritical CO2 extraction preserving heat-sensitive phytosterols for Swiss and French premium brands.
- Food Industry:Commercial frying operations exploit the 230°C smoke point for extended oil life cycles, though erucic acid ceilings under FDA and EFSA guidelines constrain refining flexibility and volume scale.
- Pharmaceuticals:High-purity refined grades penetrate parenteral and topical drug formulations as lipid excipients, with ISO 17025 laboratory certification filtering supplier eligibility.
- Biofuels:Renewable diesel mandates in the United States and EU Green Deal targets redirect crush capacity toward energy applications, potentially tightening cosmetic-grade feedstock availability.
Cosmetics anchors revenue concentration. Biofuels is climbing the fastest as policy incentives reshape oilseed crush allocation.
Distribution Channel:
Customer type determines channel selection—multinational formulators favor direct procurement, while indie brands fragment access through digital platforms.
- Direct Sales:Long-term offtake agreements with integrated seed processors secure volume certainty for contract manufacturers. Three-to-five-year contracts concentrate in California and New Jersey beauty clusters.
- Retail Stores:Specialty ingredient distributors serve mid-tier formulators lacking procurement scale for direct processor relationships.
- Online Platforms:B2B marketplaces fragment access for indie beauty brands, enabling smaller minimum order quantities but compressing margin pools through price transparency.
- Exporters:REACH-registered processors in Canada and northern Europe dominate premium cosmetic ingredient channels into France, Switzerland, and Germany.
Direct sales captures margin concentration. Online platforms is gaining share fastest as digital procurement penetrates mid-market buyers.
End User:
Supply concentration aligns with geographic clustering of downstream demand—personal care formulators concentrate on the US coasts, while biodiesel producers anchor Midwest crush capacity.
- Personal Care:Indie beauty brands and contract manufacturers in the United States scale cold-pressed oil procurement to meet retailer sustainability scorecards, with REACH compliance filtering European import eligibility.
- Food Manufacturers:Commercial frying and culinary oil packagers specify refined grades within erucic acid limits, with tempering growing regions in Canada and northern Europe exposing processors to weather-driven yield volatility.
- Healthcare Providers:Pharmaceutical manufacturers demand identity-preserved supply chains with full chain-of-custody documentation for excipient qualification.
- Biodiesel Producers:Renewable diesel refiners compete for Crambe abyssinica crush capacity, with feedstock reclassification risks redirecting supply away from cosmetic channels.
Personal care commands premium pricing. Biodiesel producers is expanding most quickly as energy policy reshapes oilseed economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Switzerland and France absorb steep price premiums for supercritical CO2-extracted grades, while biodiesel producers in the United States Midwest squeeze feedstock costs aggressively. This demand-elasticity contrast shapes regional procurement patterns.
United States
Indie beauty brands in California and New Jersey contract for cold-pressed organic volumes to meet retailer sustainability scorecards. FDA cosmetic ingredient guidelines impose compositional disclosure thresholds that filter non-compliant imports. The New Jersey contract manufacturing cluster locks in three-to-five-year offtake agreements with integrated seed processors.
Canada
Temperate growing regions in Saskatchewan and Manitoba supply Crambe abyssinica feedstock to North American crush capacity. Health Canada and PMRA oversight aligns with FDA thresholds for cross-border cosmetic ingredient trade. Prairie province processors consolidate identity-preserved infrastructure to serve REACH-registered export channels into France and Germany.
Germany
REACH substance evaluation protocols under ECHA tighten traceability documentation for imported specialty oils. The country's chemical processing hub around Leverkusen and Ludwigshafen demands full chain-of-custody certification for pharmaceutical excipient applications. German formulators pay premiums for ISO 17025-validated erucic acid quantification.
Switzerland
Swiss premium cosmetic brands in Geneva and Basel adopt solvent-free supercritical CO2 extraction to preserve heat-sensitive phytosterols. Swissmedic oversight for pharmaceutical-grade lipids reinforces purity benchmarks exceeding standard cosmetic specifications. The Basel pharmaceutical corridor sources high-purity refined grades for parenteral drug formulations.
France
French formulators in the Grasse fragrance and cosmetics cluster substitute synthetic emollients with cold-pressed Abyssinian grades. ANSM cosmetic safety evaluations align with ECHA REACH protocols for erucic acid disclosure. The Provence-Alpes-Côte d'Azur region concentrates supercritical extraction capacity serving luxury skincare houses.
Abyssinian Oil Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Abyssinian oil supply chain. Integrated seed processors with captive cultivation partnerships command feedstock consistency advantages, while toll refiners optimize hexane extraction throughput for volume markets. Three archetypes dominate: upstream-integrated agricultural processors, ISO-certified cold-press specialists, and supercritical CO2 technology licensors. Competitive moves concentrate on backward integration into temperate growing regions and long-term supply agreement lock-ins with multinational formulators.
Within the upstream-integrated tier, Henry Lamotte Oils and Nature's Crops International exemplify distinct geographic anchoring strategies. Croda International occupies a position bridging agricultural procurement and cosmetic ingredient formulation. Clariant represents the diversified chemical conglomerate archetype with cross-portfolio lipid capabilities. These three company structures illustrate how capital intensity divergences rotate advantage toward feedstock controllers versus downstream refiners.
| Leading Market Players |
|---|
| Henry Lamotte Oils |
| Clariant |
| Tate & Lyle |
| Croda International |
| Elementis |
| Nature's Crops International |
| Carrubba |
| Jedwards International |
| Phyto Life Sciences |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between integrated seed processors and contract manufacturers lock in both supply access and price visibility for cosmetic-grade Abyssinian oil, insulating premium tiers from spot-market volatility while compressing margins for commodity traders lacking upstream asset control.
Pricing Analysis
Service and certification-tier bundling drives lifetime value in Abyssinian oil procurement. Three-tier pricing structure across supercritical CO2-extracted, cold-pressed certified organic, and hexane-refined standard grades separates Swiss premium cosmetic houses from mid-tier formulators and industrial biodiesel buyers. Cost compression in standard refined tiers intensifies because meadowfoam and jojoba substitutes offer comparable oxidative stability at scale. Biodiesel producers exhibit highest price sensitivity, while Swiss and French luxury skincare brands absorb steep premiums for solvent-free extraction preserving heat-sensitive phytosterols.
Supply Chain Analysis
Strategic stockpiling of Crambe abyssinica seed inventories dominates processor behavior in Canada and northern Europe, where temperate growing regions expose supply to weather-driven yield volatility. The supply chain draws from Saskatchewan and Manitoba cultivation, hexane and CO2 extraction inputs, and ISO 17025 laboratory certification infrastructure. Single-source vulnerability concentrates in seed supply, with prairie province weather patterns creating crush capacity constraints. Distribution runs through direct sales channels for multinational formulators and B2B platforms fragmenting access for indie beauty brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage in Abyssinian oil, as digital procurement marketplaces disintermediate traditional distributors and REACH-mandated traceability documentation becomes the interoperability standard for premium market access.
For Market Incumbents: Shield margin pools by deepening captive cultivation partnerships across temperate growing regions and accelerating ISO 17025 certification timelines that filter non-compliant entrants. Meadowfoam and jojoba substitution threats demand reinforcing identity-preserved infrastructure investments that smaller processors cannot finance. Long-term supply agreement lock-ins with California and New Jersey contract manufacturing clusters anchor volume certainty against spot-market fragmentation. For New Entrants and Emerging Players: Lead with supercritical CO2 extraction capacity serving Swiss and French premium cosmetic channels, where solvent-free methods command 40-60% price premiums over hexane alternatives. The pharmaceutical excipient segment offers most penetrable white space, with parenteral and topical drug formulations requiring high-purity lipid bases and ISO-certified chain-of-custody documentation. Digital-native B2B platforms enable direct-to-brand access bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors upstream-integrated agricultural processors with captive seed supply and REACH-registered export infrastructure. Long-term viability over the next decade hinges on feedstock control rather than downstream refining scale. Acquisition targets should display identity-preserved supply chain certification and established offtake relationships with multinational formulators. The signal to watch is biofuel feedstock reclassification policy that could redirect crush capacity away from cosmetic-grade channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Cultivation | Captive Crambe abyssinica supply in Saskatchewan and Manitoba insulates processors from weather-driven yield volatility. |
| Supercritical CO2 Extraction Scale-Up | Solvent-free capacity unlocks 40-60% price premiums from Swiss and French premium cosmetic formulators. |
| REACH Registration and ISO 17025 Certification | Full chain-of-custody documentation filters non-compliant suppliers from ECHA-regulated European cosmetic channels. |
| Long-term Supply Agreement Lock-ins | Three-to-five-year offtake commitments with California and New Jersey contract manufacturers secure volume predictability. |
| Pharmaceutical Excipient Market Entry | High-purity refined grades penetrate parenteral and topical drug formulations requiring lipid base excipients. |
Study Parameters
Cross-validation between primary interviews with seed oil processors, cosmetic formulators, and pharmaceutical procurement managers and secondary validation through ECHA substance evaluation databases, USDA organic certification records, and customs trade data anchors the qualitative findings. The analysis combines bottom-up volume modeling from crush capacity and cultivation acreage with top-down demand segmentation across cosmetics, pharmaceuticals, food processing, and biofuel applications.
Sensitivity analysis across extraction technology cost curves, seed yield volatility scenarios, and regulatory compliance burden trajectories shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include refinement grade tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs derive from triangulated demand growth assumptions, capacity expansion pipelines, and substitution elasticity estimates for competing specialty oils.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity, stable prairie province cultivation economics, and continued clean-label personal care brand expansion would require recalibration. Forecasts reflect documented assumptions regarding oilseed crush allocation between cosmetic and energy applications. Revision becomes warranted when biofuel blending mandate thresholds cross levels that materially redirect Crambe abyssinica feedstock availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Midstream Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market