
 Singapore LNG Storage Tank Market | 2026-2036
Singapore LNG Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore LNG Storage Tank Market Insights
Modular tank configurations is recalibrating buyer procurement patterns across Singapore's LNG infrastructure sector. CIMC Enric Holdings Ltd leverages its manufacturing scale to supply standardized cryogenic storage modules for island-based terminals. Wärtsilä Corporation anchors its position through integrated gas solutions spanning storage, regasification, and power generation systems. Rotary Engineering Pte. Ltd. specializes in domestic fabrication and site assembly, competing on proximity to Singapore's port and industrial zones.
Singapore LNG storage tanks are double-walled cryogenic vessels designed to maintain liquefied natural gas at minus 162 degrees Celsius, employing perlite vacuum insulation or polyurethane foam systems to minimize boil-off gas losses. These structures serve as critical buffer inventory for power generation, marine bunkering, and regional re-export operations. Double containment tank types command premium positioning due to Singapore's stringent safety codes and limited land availability. Stainless steel material grades dominate specification sheets where corrosion resistance and thermal cycling durability justify higher upfront capital outlays.
Singapore's Energy Market Authority enforces facility licensing under the Gas Act, while the National Environment Agency administers emissions and hazardous substances controls for LNG terminal operations. Workplace safety standards from Singapore's Ministry of Manpower mandate periodic inspection protocols that sustain replacement demand for aging tank assets. Stakeholders must monitor Jurong Island's liquefaction capacity expansions and the Maritime and Port Authority's LNG bunkering licensing timeline to align storage investment with vessel refueling infrastructure rollout.
Market Dynamics
Modular cryogenic storage architectures are compressing project timelines and reshaping capital deployment patterns across Singapore's LNG infrastructure sector. The Energy Market Authority's licensing framework now explicitly accommodates prefabricated tank systems, accelerating approval cycles for island-based terminals.
Growth Catalysts
- Jurong Island Petrochemical Cluster Expansion:Integrated refining-petrochemical complexes are mandating dedicated LNG buffer storage to secure feedstock supply chains against maritime delivery delays.
- Gas Act Licensing Reforms:Streamlined facility permitting under Singapore's Energy Market Authority reduces regulatory friction for cryogenic storage investments.
- Marine Bunkering Infrastructure:The Maritime and Port Authority's LNG vessel refueling licensing is creating synchronized demand for shore-side storage tanks at Singapore's port terminals.
Market Restraints
- Nickel Alloy Input Volatility:Stainless steel grade 304/316 price swings directly impact cryogenic tank fabrication costs, squeezing margins for domestic fabricators.
- Limited Domestic Fabrication Capacity:Singapore's specialized cryogenic welding workforce constrains throughput for double-walled tank assembly, creating project bottlenecks.
- Land Scarcity Premium:Jurong Island's constrained footprint elevates site preparation costs, compressing returns on storage infrastructure investments.
Strategic Opportunities
- Regional Re-Export Hub Positioning:Singapore's location astride Southeast Asian shipping lanes enables transshipment storage services for Indonesian and Malaysian power utilities.
- Hybrid Storage-Power Integration:Co-located LNG tanks and combined-cycle gas turbines are attracting integrated project finance from regional development banks.
- Small-Scale LNG Distribution:Island-based satellite storage terminals can serve off-grid industrial consumers across Indonesia's Riau Archipelago.
Industry Challenges
- Cryogenic Welding Certification Delays:Singapore's Ministry of Manpower inspection protocols for ASME IX-qualified welders extend project staffing timelines.
- Legacy Tank Asset Integration:Retrofitting existing single-containment tanks to meet current Energy Market Authority double-containment standards requires complex structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore LNG Storage Tank Market |
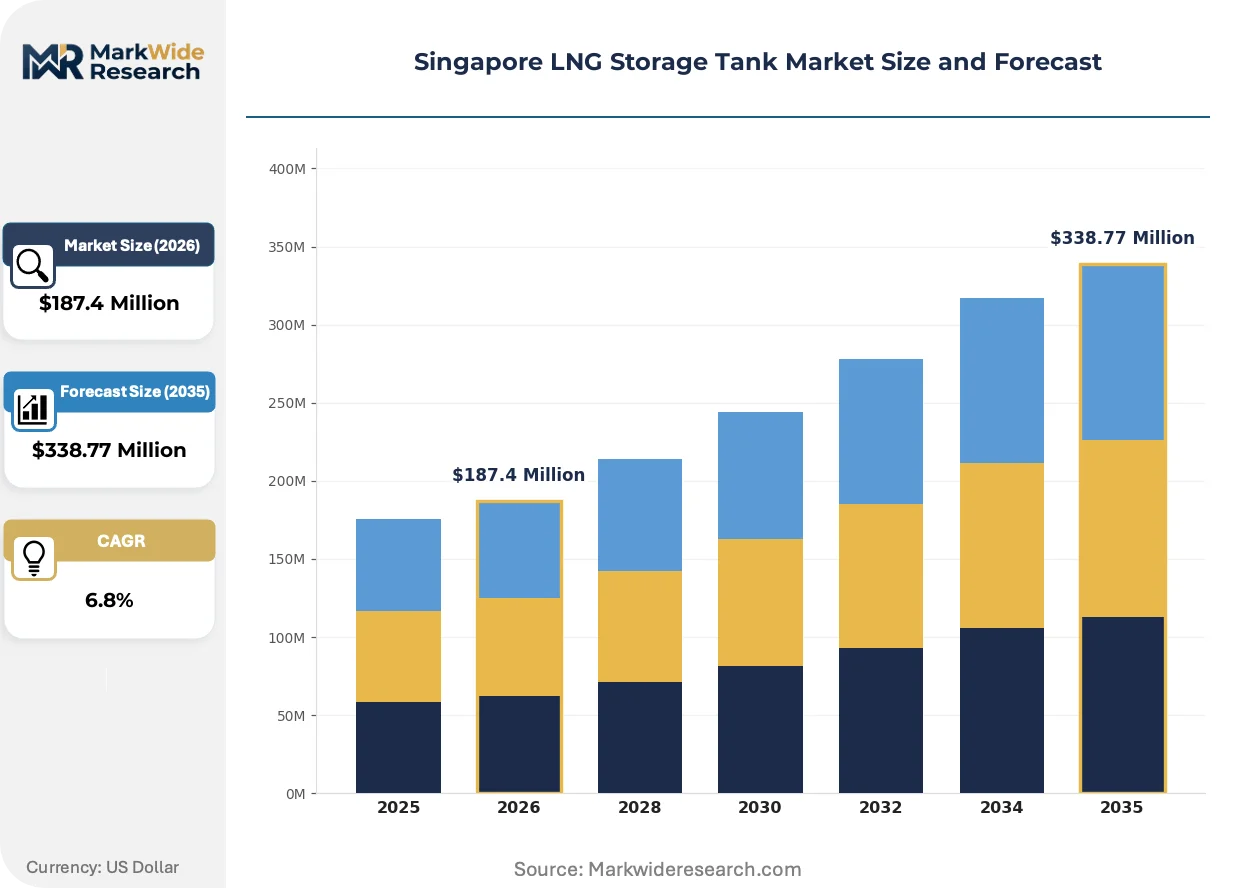
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tank Type: Horizontal, Vertical, Double Containment, Spherical Material: Carbon Steel, Stainless Steel, Aluminum, Reinforced Concrete Application: Power Generation, Industrial Use, Transport, Export End User: Utilities, Industrial Manufacturers, Oil & Gas Companies, Distributors |
| Companies Covered | Linde PLC, Wärtsilä Corporation, CIMC Enric Holdings Ltd, Rotary Engineering Pte. Ltd., Singapore LNG Corporation Pte Ltd, IHI Corporation, McDermott, Chart Industries, Air Water Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore LNG Storage Tank Market Trends and Innovations
Electrification of auxiliary systems and digital monitoring architectures are transforming how Singapore's LNG storage assets operate and maintain thermal integrity. These shifts reduce operational personnel exposure while tightening boil-off gas management.
Full-containment membrane tank systems are electrifying project economics for mid-scale Singapore terminals. Power generation utilities adopting these configurations report faster commissioning schedules than conventional 9% nickel steel designs. The technology is electrifying competitive positioning among engineering contractors bidding for Jurong Island expansion contracts.
Singapore's Energy Market Authority has tightened Gas Act facility licensing to mandate real-time leak detection and automated emergency isolation systems. Terminal operators must now demonstrate integrated safety instrumented functions before receiving operational permits. Double-walled above-ground tanks face the most stringent compliance timelines, with retrofit deadlines compressing capital planning cycles.
Buyers are consolidating procurement authority under integrated project delivery frameworks rather than fragmented engineering-procurement-construction contracts. Singapore LNG terminal developers now specify single-point accountability for storage tank performance guarantees. This concentration is most visible among power generation utilities seeking to transfer operational risk to turnkey contractors.
Singapore LNG Storage Tank Market Segmentation
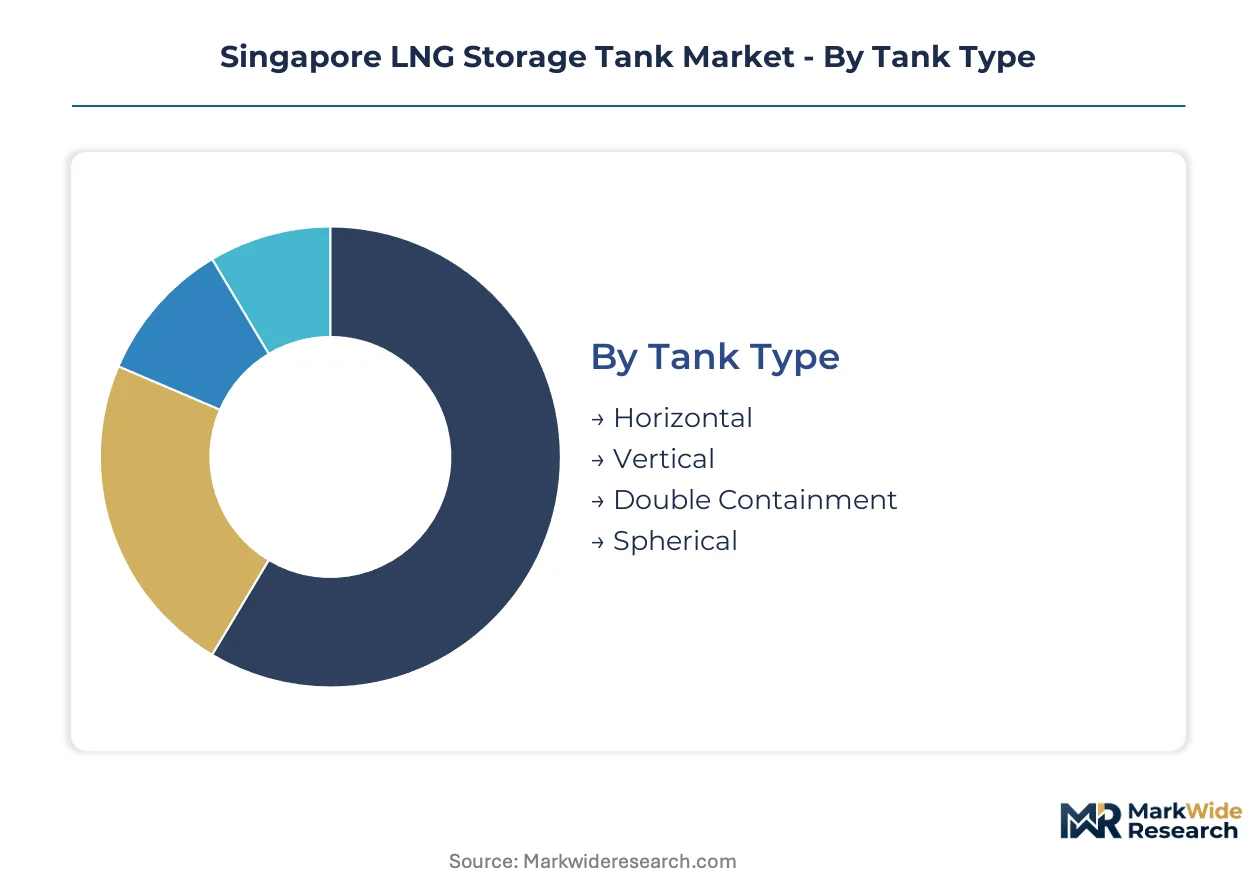
Singapore's LNG storage infrastructure serves distinct operational profiles across power generation, marine bunkering, and regional re-export. Tank specifications diverge sharply based on thermal cycling demands, safety containment levels, and integration with downstream regasification systems.
Tank Type:
Buyers differentiate primarily by footprint constraints and safety tier requirements rather than capacity alone.
- Double Containment:These tanks integrate primary cryogenic vessels with secondary liquid-tight barriers and vapor containment, satisfying Singapore's Energy Market Authority Gas Act licensing for high-consequence facilities. Demand concentrates at Jurong Island's integrated refining-petrochemical complexes where proximity to dense process units mandates maximum spill protection. Land scarcity premiums justify the higher capital outlay.
- Vertical:Upright cylindrical configurations optimize storage density on constrained Jurong Island plots, stacking LNG inventory above ground while minimizing foundation footprints. Singapore LNG terminal operators specify these for buffer storage serving peak-shaving power generation units. The Maritime and Port Authority's bunkering licensing timeline is synchronizing demand with vessel refueling infrastructure.
- Horizontal:Low-profile designs suit retrofit installations and satellite terminals with height restrictions.
- Spherical:Geodesic dome structures offer uniform stress distribution for specialized high-pressure applications.
Volume sits with Vertical configurations; growth tilts toward Double Containment as safety codes tighten.
Material:
Specification sheets track corrosion resistance against thermal cycling durability under Singapore's humid coastal conditions.
- Stainless Steel:Grade 304 and 316 alloys dominate cryogenic tank fabrication for their resistance to chloride-induced stress corrosion cracking. Fabricators like Rotary Engineering Pte. Ltd. source these grades for double-walled assemblies serving power generation utilities. Nickel alloy input volatility directly squeezes project margins.
- Carbon Steel:Lower-grade specifications with protective coatings anchor budget-constrained satellite storage projects.
- Aluminum:Lightweight alloys enable modular transport for small-scale distribution terminals.
- Reinforced Concrete:Pre-stressed concrete outer shells provide secondary containment for full-containment membrane systems.
Stainless Steel commands current procurement volumes; Carbon Steel is climbing fastest among hybrid storage-power integration projects.
Application:
End-use economics determine boil-off gas tolerance, regasification integration depth, and dispatch flexibility requirements.
- Power Generation:Combined-cycle gas turbine operators specify large-scale buffer tanks to secure feedstock against maritime delivery delays. Singapore's utilities are diversifying from coal and oil, mandating dedicated LNG storage at Jurong Island power blocks. Co-located tanks and turbines attract integrated project finance from regional development banks.
- Industrial Use:Petrochemical crackers and hydrogen production facilities require steady-state vaporization for process heat.
- Transport:Marine bunkering infrastructure demands rapid-turnover shore-side tanks aligned with vessel refueling schedules.
- Export:Regional re-export positioning enables transshipment storage for Indonesian and Malaysian power utilities.
Power Generation absorbs dominant capacity; Transport is gaining share fastest under Maritime and Port Authority licensing expansion.
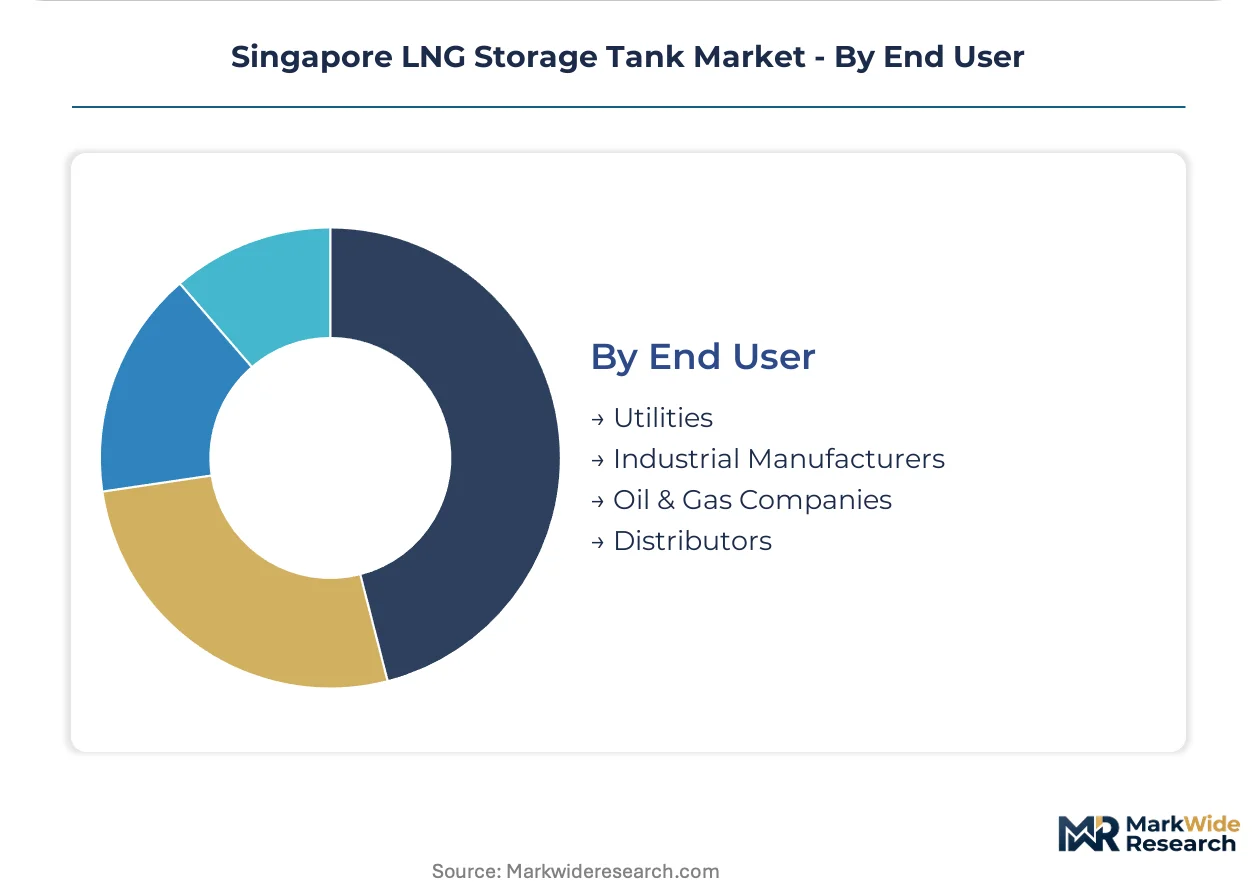
End User:
Procurement authority concentrates under integrated project delivery frameworks rather than fragmented contracts.
- Utilities:Power generation companies consolidate storage tank performance guarantees under single-point accountability with turnkey contractors. These buyers transfer operational risk while mandating real-time leak detection and automated emergency isolation per Energy Market Authority Gas Act requirements.
- Oil & Gas Companies:Integrated majors leverage existing Jurong Island terminal infrastructure for expansion.
- Industrial Manufacturers:Petrochemical clusters procure dedicated buffer storage against supply chain disruptions.
- Distributors:Trading houses position storage for regional re-export arbitrage across Southeast Asian shipping lanes.
Utilities anchor current investment; Oil & Gas Companies show steepest expansion trajectory as legacy terminal operators diversify into LNG.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
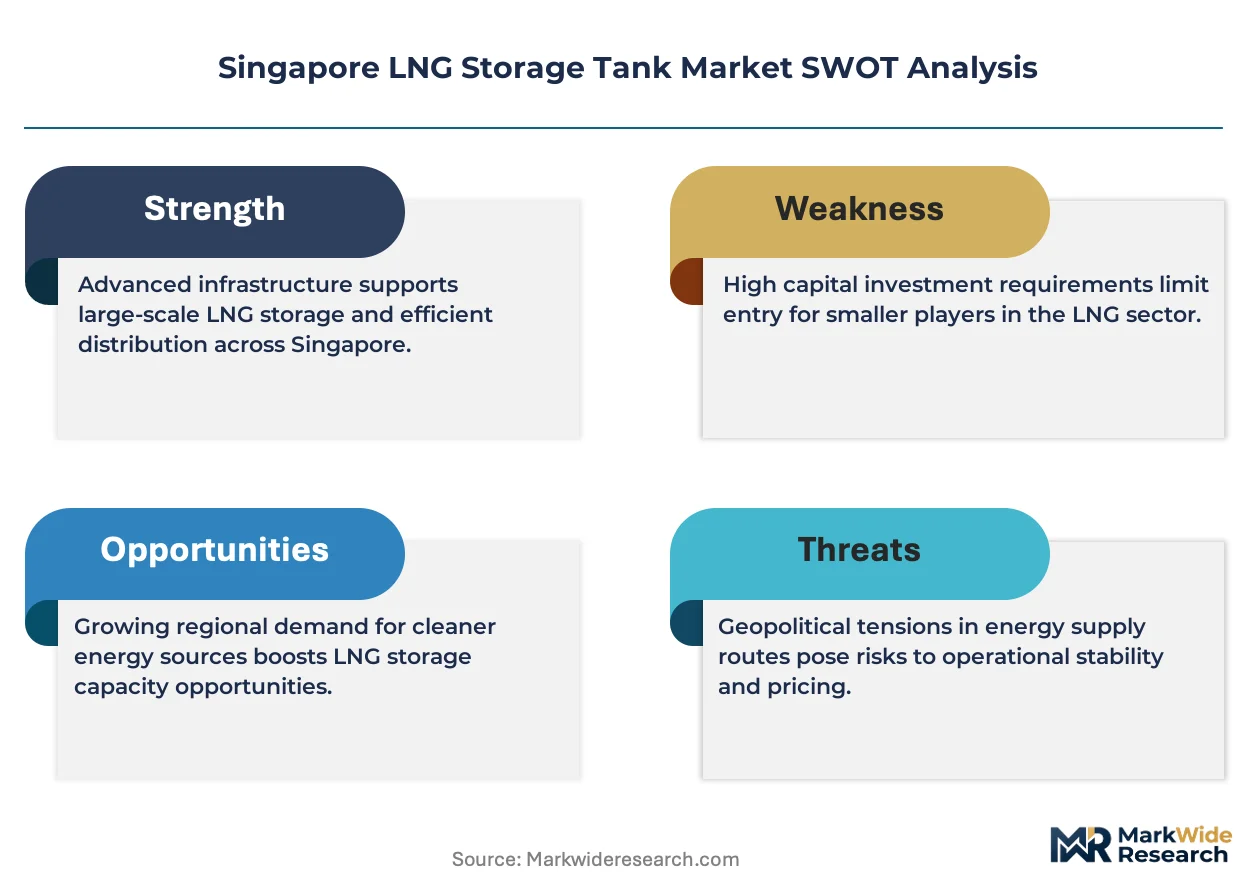
Jurong Island anchors Singapore's LNG storage concentration, with the Energy Market Authority's Gas Act licensing framework and Maritime and Port Authority bunkering permits synchronizing infrastructure rollout across the city-state's industrial zones.
Jurong Island Industrial Zone
Integrated refining-petrochemical complexes mandate dedicated LNG buffer storage to secure feedstock supply chains against maritime delivery delays. Singapore's Energy Market Authority enforces facility licensing under the Gas Act, mandating double-containment systems for high-consequence facilities. The island's constrained footprint elevates site preparation costs, compressing returns on storage infrastructure investments while concentrating demand among power generation utilities diversifying from coal and oil.
Tuas Power Generation Cluster
Combined-cycle gas turbine operators specify large-scale buffer tanks to secure feedstock against supply disruptions. Singapore's Ministry of Manpower workplace safety standards mandate periodic inspection protocols that sustain replacement demand for aging tank assets. Co-located LNG tanks and turbines attract integrated project finance from regional development banks, with electrification of auxiliary systems reducing operational personnel exposure.
Pulau Bukom Petrochemical Hub
Petrochemical crackers and hydrogen production facilities require steady-state vaporization for process heat, driving specifications for stainless steel grade 304/316 alloys. The National Environment Agency administers emissions and hazardous substances controls for LNG terminal operations. Shell's integrated operations on Pulau Bukom exemplify hybrid storage-power integration patterns across Singapore's energy transition.
Port Terminals and Bunkering Infrastructure
Marine bunkering infrastructure demands rapid-turnover shore-side tanks aligned with vessel refueling schedules. The Maritime and Port Authority's LNG vessel refueling licensing creates synchronized demand for storage capacity at Singapore's port terminals. Real-time leak detection and automated emergency isolation systems are now mandatory prerequisites for operational permits under tightened Energy Market Authority standards.
Singapore LNG Storage Tank Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Singapore's LNG storage tank procurement landscape. The vendor base clusters around three strategic archetypes: integrated engineering-procurement-construction contractors, modular cryogenic equipment fabricators, and site-assembly specialists leveraging domestic fabrication capabilities. Capacity expansion and strategic partnerships dominate competitive moves, with turnkey contractors consolidating performance guarantee accountability under single-point delivery frameworks.
Among Singapore-based fabricators, Rotary Engineering Pte. Ltd. occupies a position exemplifying domestic site-assembly specialization, while CIMC Enric Holdings Ltd represents the modular equipment fabrication archetype with manufacturing scale advantages. Wärtsilä Corporation anchors the integrated solutions tier, spanning storage, regasification, and power generation systems. These three entities collectively illustrate the competitive segmentation between proximity-driven domestic players, scale-driven equipment suppliers, and technology-integrated system providers.
| Leading Market Players |
|---|
| Linde PLC |
| Wärtsilä Corporation |
| CIMC Enric Holdings Ltd |
| Rotary Engineering Pte. Ltd. |
| Singapore LNG Corporation Pte Ltd |
| IHI Corporation |
| McDermott |
| Chart Industries |
| Air Water Inc. |
| Others |
Pricing and Supply Chain Analysis
Full-containment membrane tank electrification is compressing project economics while concentrating procurement leverage among turnkey contractors who bundle storage with regasification systems. Singapore's Energy Market Authority Gas Act licensing timeline accelerates cost recovery for prefabricated configurations, reshaping how buyers negotiate performance guarantees and supplier accountability.
Pricing Analysis
Lead-time premiums dominate Singapore's LNG tank procurement, with modular cryogenic vessels commanding price advantages over conventional 9% nickel steel designs due to accelerated commissioning schedules. Price differentiation rests on ASME IX welding certification tiers and double-containment safety ratings mandated by the Energy Market Authority. Cost compression in stainless steel grade 304/316 inputs is intensifying because of nickel alloy volatility, squeezing domestic fabricator margins. Power generation utilities show lowest price sensitivity given integrated project finance structures, while satellite terminal operators face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Japan and South Korea for 9% nickel steel plate and specialized cryogenic insulation systems. Singapore's fabricators draw from Chinese stainless steel mills, Finnish membrane technology licensors, and German cryogenic valve suppliers. Tariff exposure runs through nickel alloy feedstock imports subject to commodity price swings. Distribution runs through engineering-procurement-construction contractors who consolidate equipment sourcing under single-point accountability frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's cryogenic welding certification bottleneck constrains domestic fabrication throughput, propping pricing power for qualified suppliers who can guarantee Energy Market Authority compliance timelines.
For Market Incumbents: Deploy backward integration into stainless steel grade 304/316 distribution to hedge nickel alloy input volatility threatening project margins. Incumbents should anchor Gas Act licensing expertise as a defensive moat against modular equipment suppliers entering from China and Europe, while expanding Jurong Island site-assembly capacity to capture premium for proximity-driven procurement. For New Entrants and Emerging Players: Digital-channel routes through integrated project delivery platforms offer lower-friction entry than fragmented engineering-procurement-construction bidding. New entrants should target small-scale LNG distribution terminals serving Indonesia's Riau Archipelago, where Maritime and Port Authority bunkering licensing creates synchronized demand without requiring Jurong Island land access. For Investors and Strategic Acquirers: Re-rating potential sits with domestic site-assembly specialists given Energy Market Authority's tightened inspection protocols extending project staffing timelines. Long-term viability favors acquirers of cryogenic welding certification capacity and membrane technology licensing rights, with the signal to watch being Jurong Island liquefaction expansion announcements that would trigger synchronized storage investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Supply | Captive sourcing of grade 304/316 alloys insulates margins from nickel price volatility affecting cryogenic tank fabrication. |
| Membrane Technology Licensing | Full-containment systems from Finnish and Japanese licensors accelerate commissioning schedules for Jurong Island terminals. |
| ASME IX Welder Certification Expansion | Qualified cryogenic welding capacity addresses Singapore's Ministry of Manpower inspection bottleneck constraining project throughput. |
| Hybrid Storage-Power Integration | Co-located LNG tanks and combined-cycle turbines attract regional development bank finance for utility-scale projects. |
| Small-Scale Satellite Terminal Development | Island-based storage serving Indonesia's Riau Archipelago leverages Maritime and Port Authority bunkering licensing expansion. |
Research Methodology
Independent corroboration across terminal operators, EPC contractors, and cryogenic equipment fabricators underwrites the qualitative findings on procurement pattern shifts. Primary interviews with Singapore LNG Corporation planning officers, Rotary Engineering project managers, and Energy Market Authority licensing specialists combined with secondary validation from Gas Act regulatory filings, Maritime and Port Authority bunkering permits, and stainless steel trade flow data. Bottom-up project pipeline assessment and top-down infrastructure investment tracking triangulate market sizing.
Comparable-period anchoring to historical capacity commissioning cycles and replacement demand patterns shaped the projection framework across the analysis window. Segmentation dimensions modeled include tank type, material grade, application end-use, and procurement authority concentration under integrated project delivery. CAGRs were derived from capacity expansion announcements, Gas Act licensing timelines, and power generation fuel diversification commitments. Forecast inputs incorporated Jurong Island petrochemical cluster expansion schedules and Maritime and Port Authority LNG bunkering infrastructure rollout.
The model holds under stable Energy Market Authority regulatory enforcement and continued power generation diversification from coal; deviation in nickel alloy price volatility or cryogenic welder certification delays would shift commissioning timelines and capital deployment patterns. Forecasts reflect documented assumptions on modular technology adoption rates and regional re-export demand from Indonesian and Malaysian utilities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Well Logging Tools Market
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Oil and Gas Downhole Vibration Monitoring and Control System Market
Oil & Gas
Drill Collar Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Algeria Oil and Gas Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Europe Digital Oilfield Market