
 FTIR Oil Condition Monitoring Market | 2026-2036
FTIR Oil Condition Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
FTIR Oil Condition Monitoring Market Foresight
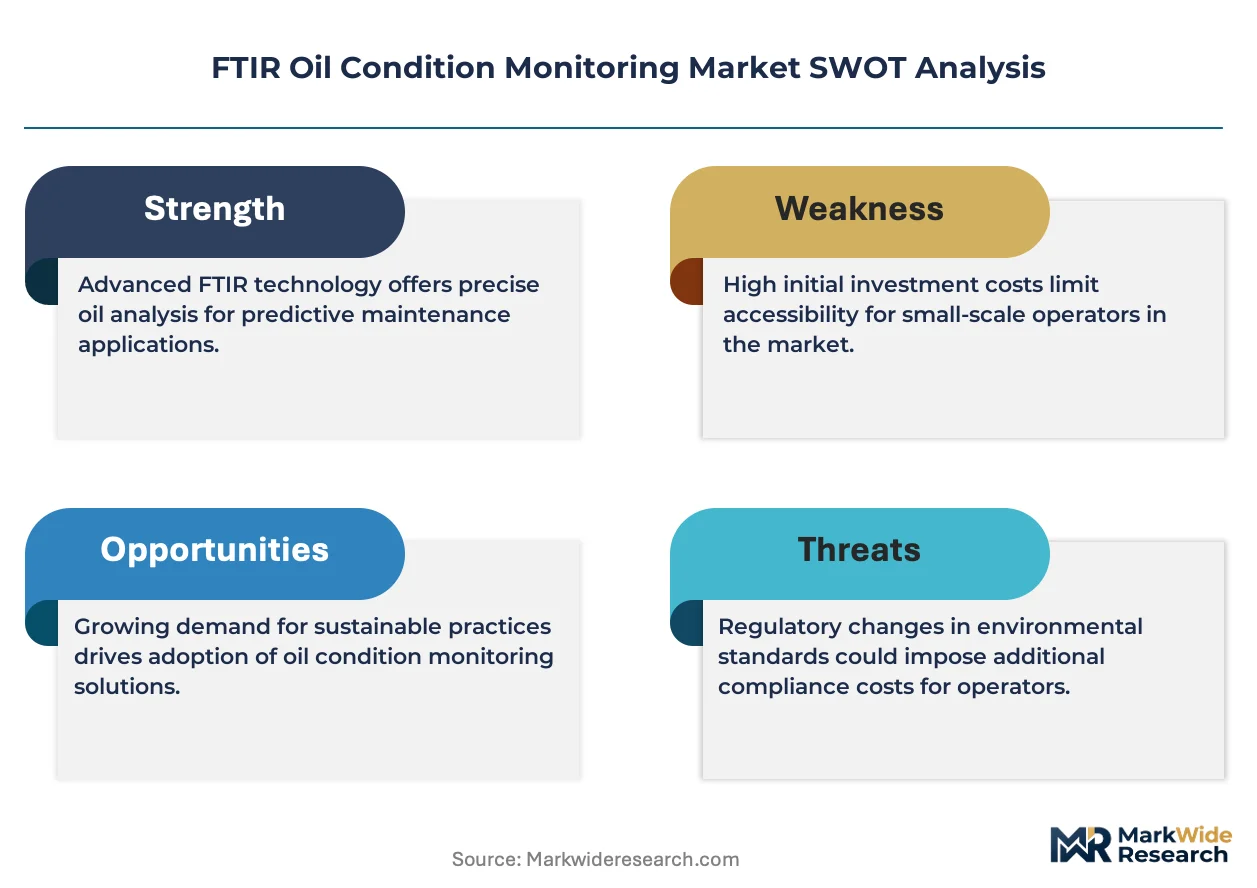
The shift from outsourced laboratory testing toward in-house online monitoring systems is broadening vendor engagement models across the FTIR oil condition monitoring landscape. PerkinElmer leverages its spectroscopy heritage to anchor premium laboratory instrument positions. SGS SA competes through its global inspection network, sustaining credibility among marine and aerospace clients. Bureau Veritas differentiates via integrated testing and certification workflows that span lubricant quality and environmental compliance.
Fourier transform infrared spectroscopy oil condition monitoring measures molecular absorption across the mid-infrared spectrum to detect oxidation, nitration, sulfation, and additive depletion in lubricating fluids, typically scanning wavenumber ranges from 4000 to 400 cm-1. The technique enables non-destructive identification of contaminants and degradation byproducts without sample preparation, serving preventive maintenance programs in rotating equipment and power systems. Fourier transform infrared spectroscopy retains the dominant technology position due to established ASTM and DIN standard methods, while portable devices represent the fastest-expanding deployment category as field technicians prioritize point-of-use diagnostics over laboratory turnaround. Cloud-based platforms attract emerging interest from multi-site manufacturing plants seeking centralized lubricant health dashboards.
The U.S. EPA regulates waste oil classification and disposal thresholds that directly shape analysis frequency and parameter breadth for industrial generators. ASTM D7412 and ASTM D7414 standardize FTIR test methods for in-service lubricant monitoring, creating compliance-driven demand for instrument calibration and protocol adherence. Germany's DIN 51575 and the EU REACH framework govern chemical disclosure in lubricant formulations, affecting how monitoring systems report additive package breakdown. Stakeholders must weigh capital deployment between portable field units and centralized laboratory infrastructure as regulatory stringency and operational scale diverge across end-user segments.
Market Dynamics
The migration from centralized laboratory analysis to distributed field-deployable FTIR systems is compressing equipment procurement cycles and forcing vendors to recalibrate service revenue models around predictive analytics subscriptions.
Growth Catalysts
- OSHA maintenance standards:The U.S. tightened lubricant analysis frequency mandates for industrial machinery, compelling facilities to expand monitoring coverage beyond critical rotating equipment.
- Power generation utilities:Predictive maintenance program adoption accelerates as grid operators seek to minimize unplanned turbine outages through real-time oil degradation tracking.
- Mid-infrared detector advances:Solid-state detector miniaturization enables portable FTIR units to match laboratory-grade resolution, collapsing the performance gap between field and benchtop instruments.
Market Restraints
- Reference standard scarcity:Certified lubricant reference materials for calibration concentrate among three European suppliers, creating supply vulnerability for instrument manufacturers.
- ASTM method fragmentation:Competing standard protocols across ASTM D7412, D7414, and DIN 51575 force end-users to maintain multiple calibration curves, raising operational complexity.
- Vibrational spectroscopy substitutes:Raman and near-infrared systems encroach on routine screening applications where molecular specificity requirements are less stringent.
Strategic Opportunities
- EU REACH chemical disclosure:Additive package breakdown reporting requirements create demand for FTIR systems capable of quantitative degradation product identification.
- Marine shipping corridors:IMO 2020 sulfur regulations and subsequent lubricant formulation changes position vessel operators for expanded oil condition monitoring adoption.
- Cloud-based dashboard convergence:Multi-site manufacturing plants seek centralized lubricant health visibility, opening subscription revenue streams for instrument-software bundles.
Industry Challenges
- Spectroscopy technician shortage:Interpretation of complex FTIR spectra for diagnostic decision-making requires specialized training that outpaces vocational program output.
- Legacy DCS integration:Plant historians and distributed control systems lack native data ingestion protocols for portable analyzer outputs, demanding custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FTIR Oil Condition Monitoring Market |
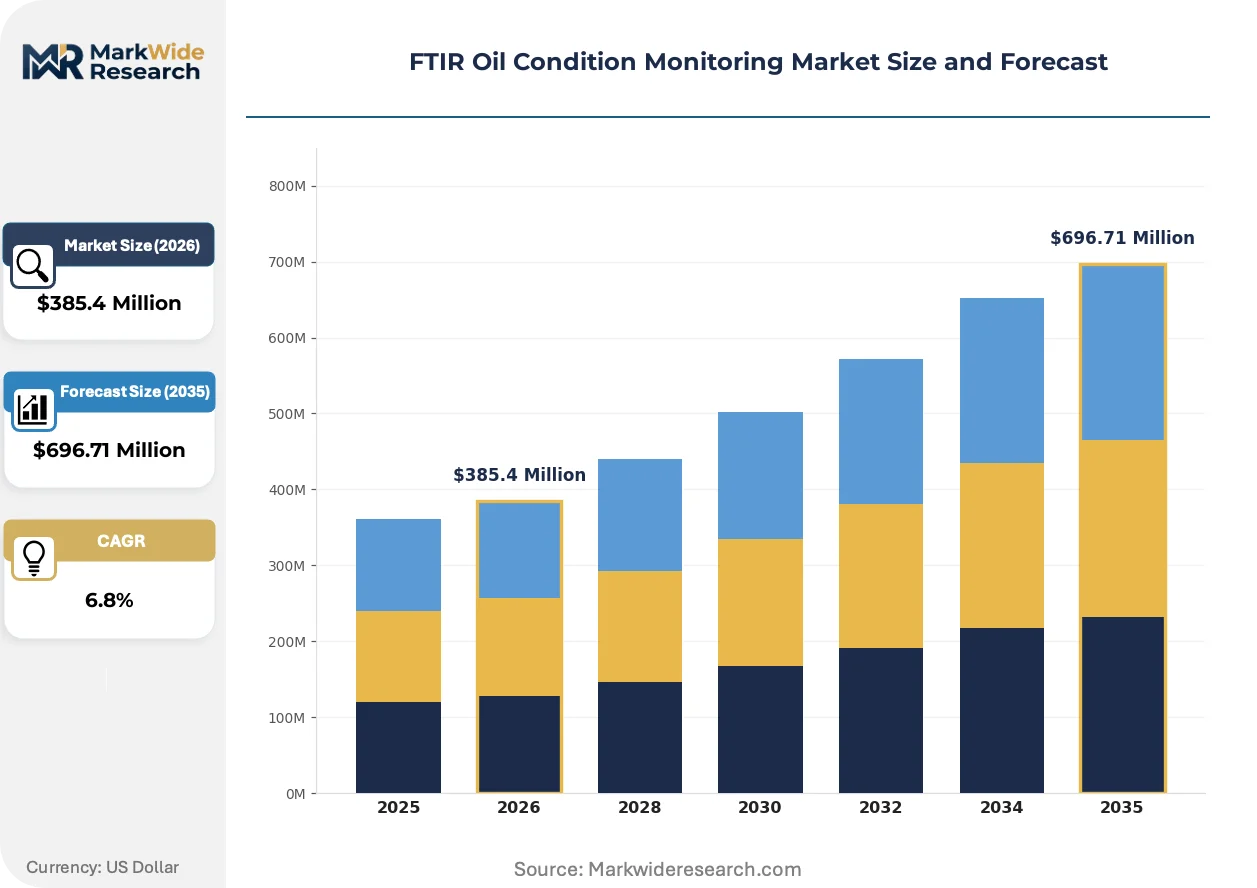
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fourier Transform Infrared Spectroscopy, Near Infrared Spectroscopy, Raman Spectroscopy, Ultraviolet-Visible Spectroscopy Application: Engine Lubricants, Hydraulic Oils, Turbine Oils, Gear Oils, Transformer Oils End User Industry: Power Generation, Aerospace, Construction Equipment, Marine Vessels, Manufacturing Plants Deployment: Online Monitoring Systems, Portable Devices, Laboratory Instruments, Cloud-Based Platforms |
| Companies Covered | PerkinElmer, Optimas Instruments, SGS SA, Parker Hannifin, Spectro Scientific, Bureau Veritas, eralytics, Oil Check Laboratory Services, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FTIR Oil Condition Monitoring Market Shifts & Advancements
Instrumentation architecture is fragmenting as field technicians demand diagnostic autonomy and regulatory bodies mandate more frequent sampling intervals across hazardous machinery classes.
Portable FTIR analyzers is modularizing around interchangeable sampling interfaces—transmission cells for clean lubricants, attenuated total reflectance probes for contaminated fluids, and flow-through cells for continuous pipeline monitoring. Wind farm operators and mining fleet managers deploy these units at point-of-use, eliminating sample transport logistics. This distributed architecture compresses laboratory service contract renewal rates while expanding consumables revenue for sampling accessories.
REACH chemical disclosure amendments now require lubricant formulators to document additive depletion pathways through standardized analytical methods. The European Chemicals Agency enforcement timeline pressures industrial lubricant consumers to adopt FTIR-based tracking systems that generate auditable degradation curves. German automotive component suppliers lead compliance investment, cascading requirements through their tiered supply bases.
Condition-based service contracts now displace fixed-fee oil analysis subscriptions as maintenance providers absorb performance risk. Equipment OEMs bundle FTIR monitoring with extended warranty coverage, capturing lubricant health data to refine predictive algorithms. This shift concentrates procurement authority among reliability engineering teams rather than laboratory managers, altering vendor sales engagement protocols in North American manufacturing corridors.
FTIR Oil Condition Monitoring Market Segmentation
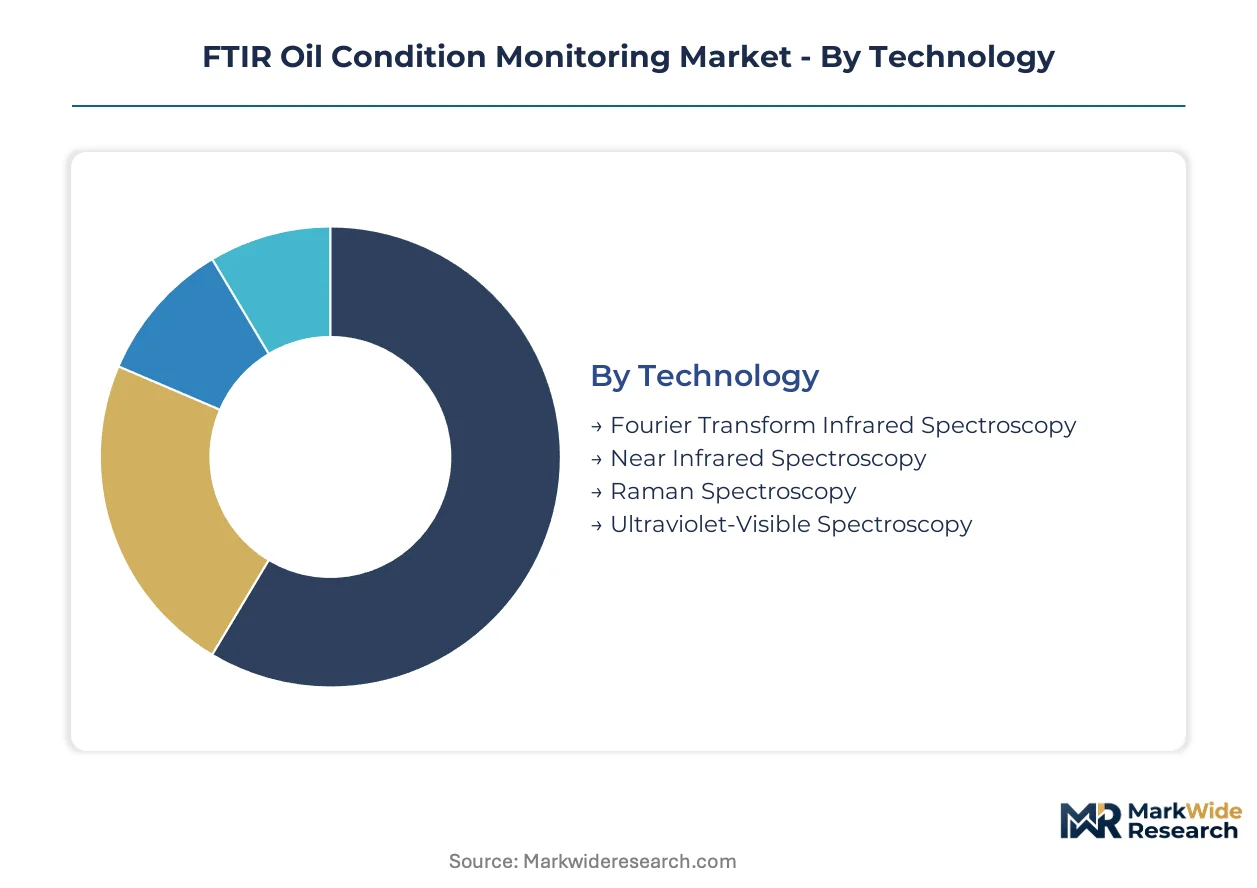
FTIR oil condition monitoring vendors configure product portfolios around four intersecting dimensions that determine integration architecture and customer procurement patterns. Technology selection dictates detector specifications and spectral resolution requirements, while deployment mode shapes whether systems operate as embedded plant infrastructure or standalone diagnostic tools.
Technology:
Fourier transform infrared spectroscopy anchors laboratory-grade installations, whereas complementary techniques fill speed and portability gaps in distributed monitoring networks.
- Fourier Transform Infrared Spectroscopy:Mid-infrared absorption scanning from 4000 to 400 cm-1 enables oxidation, nitration, and additive depletion quantification per ASTM D7412 and DIN 51575 protocols. Power generation utilities in Germany deploy these systems for turbine oil compliance tracking under REACH chemical disclosure mandates.
- Near Infrared Spectroscopy:Shorter wavelength detection permits faster throughput without sample preparation, sacrificing molecular specificity for screening velocity. Manufacturing plants with high-volume lubricant testing programs adopt NIR for preliminary contamination flagging before FTIR confirmation.
- Raman Spectroscopy:Scattering-based detection avoids water interference that complicates infrared measurements in aqueous-contaminated hydraulic fluids.
- Ultraviolet-Visible Spectroscopy:Limited to conjugated degradation products and specific additive chromophores in transformer oil antioxidant monitoring.
Fourier transform infrared spectroscopy leads volumes today; Raman spectroscopy is gaining share fastest in marine and field applications where water ingress is prevalent.
Application:
Lubricant chemistry and operating severity create distinct performance requirements that shape instrument configuration and consumables demand.
- Engine Lubricants:Complex additive packages containing detergents, dispersants, and anti-wear compounds generate dense spectral signatures requiring deconvolution algorithms. Fleet operators in the U.S. prioritize these applications under EPA waste oil classification protocols that mandate contamination documentation.
- Turbine Oils:Thermal stress produces specific oxidation byproducts tracked through ester carbonyl absorption bands at 1740 cm-1. Power generation utilities concentrate procurement here to satisfy OSHA maintenance standards for critical rotating machinery.
- Hydraulic Oils:Water ingression and particulate contamination dominate failure modes in construction equipment exposed to outdoor environments.
- Gear Oils:Extreme pressure additive depletion monitoring supports wind turbine drivetrain maintenance programs.
- Transformer Oils:Dissolved gas analysis integration with FTIR furanic compound detection addresses electrical utility asset management requirements.
Engine lubricants dominate current installed base; turbine oil monitoring is climbing the fastest as predictive maintenance contracts expand in power generation.
End User Industry:
Capital intensity and regulatory exposure determine whether customers prioritize laboratory precision or field-deployable convenience.
- Power Generation:Grid operators mandate continuous oil degradation tracking for gas and steam turbines, driving online monitoring system adoption with direct DCS integration.
- Aerospace:MRO facilities and airline engineering departments require certified reference standard traceability for jet engine lubricant analysis.
- Marine Vessels:IMO sulfur regulations and cylinder oil formulation changes position vessel operators for expanded condition monitoring adoption on international shipping corridors.
- Construction Equipment:Distributed fleet operations favor portable analyzers over laboratory contracts due to site remoteness and turnaround constraints.
- Manufacturing Plants:Multi-site operations seek centralized lubricant health dashboards through cloud-based platform convergence.
Power generation anchors procurement volumes; marine applications show steepest expansion trajectory from regulatory-driven lubricant formulation changes.
Deployment:
Procurement authority is migrating from laboratory managers toward reliability engineering teams as distributed architectures displace centralized testing.
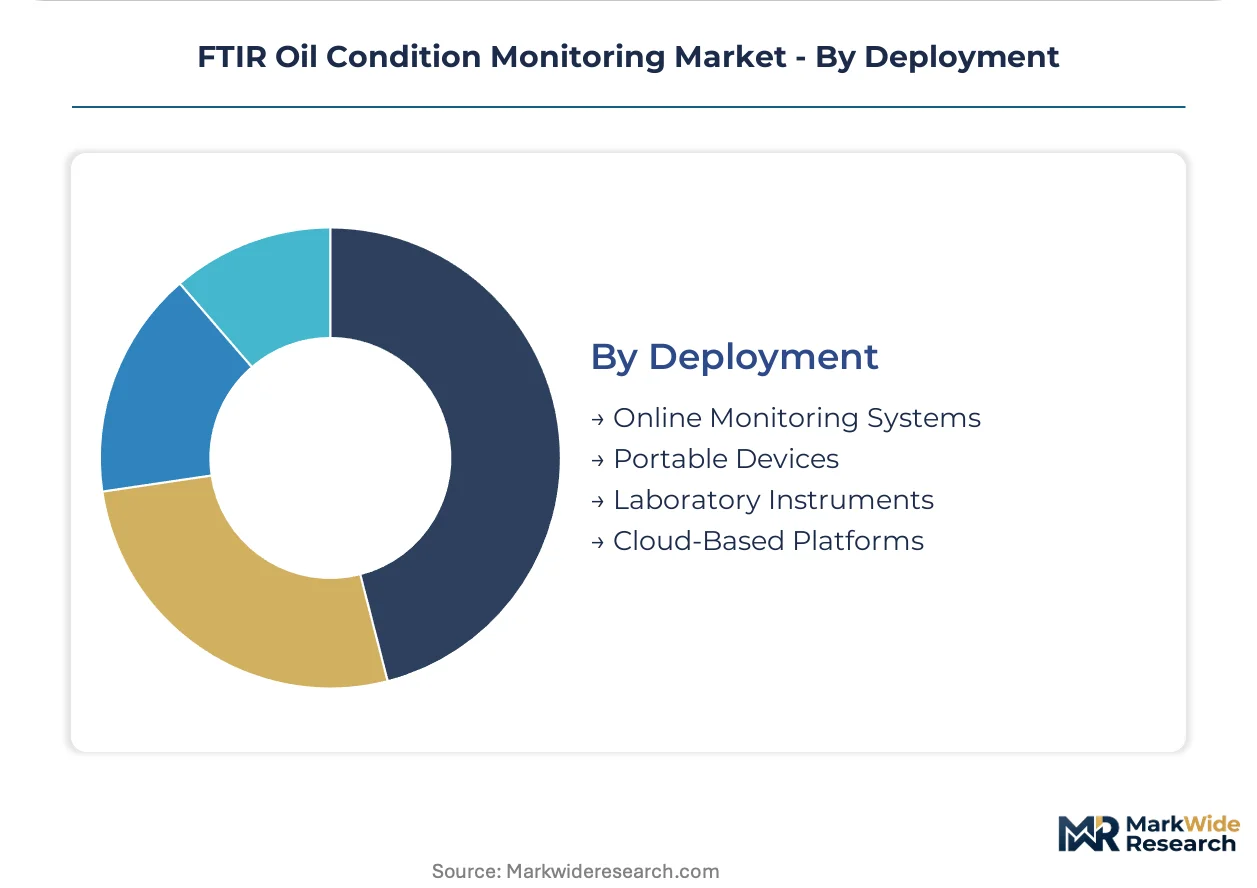
- Portable Devices:Solid-state detector miniaturization enables field technicians to match laboratory resolution at point-of-use. Wind farm operators and mining fleet managers eliminate sample transport logistics through modular sampling interfaces including transmission cells and ATR probes.
- Online Monitoring Systems:Continuous flow-through cells pipeline oil directly from circulating systems to spectrometers, generating real-time degradation curves for predictive algorithms.
- Laboratory Instruments:Benchtop systems retain dominance in third-party testing facilities serving marine and aerospace certification workflows.
- Cloud-Based Platforms:Multi-site manufacturing plants aggregate portable analyzer outputs into centralized lubricant health dashboards, opening subscription revenue streams for instrument-software bundles.
Portable devices are expanding most quickly; online monitoring systems lead capital deployment in power generation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping FTIR oil condition monitoring procurement patterns as manufacturers relocate analytical service contracts toward jurisdictions with streamlined REACH compliance frameworks and consolidated laboratory certification pathways.
United States
OSHA maintenance standards mandate expanded lubricant analysis frequency for industrial machinery classes, compelling power generation utilities to deploy continuous monitoring infrastructure. The EPA waste oil classification protocols require contamination documentation that drives laboratory instrument calibration demand. Houston's petrochemical corridor anchors Gulf Coast predictive maintenance program adoption for refinery rotating equipment.
Germany
Industrial machinery density across automotive component supply chains sustains laboratory instrument utilization rates above regional averages. DIN 51575 standardization and ECHA REACH enforcement timelines pressure formulators to document additive depletion through auditable FTIR tracking systems. Stuttgart's automotive tier-one supplier cluster leads compliance investment, cascading requirements through Bavarian and North Rhine-Westphalian manufacturing bases.
China
State grid operators accelerate predictive maintenance adoption for thermal power assets under MIIT equipment reliability directives. GB standards for lubricant quality testing converge with international ASTM protocols, reducing calibration complexity for multinational instrument vendors. Yangtze River Delta manufacturing zones concentrate portable analyzer procurement as export-oriented machinery producers face EU-bound REACH documentation requirements.
Japan
METI industrial efficiency programs subsidize online monitoring system deployment for steel and shipbuilding maintenance operations. JIS standard harmonization with ASTM D7412 reduces protocol fragmentation for laboratory service providers. Nagoya's precision machinery cluster drives demand for transmission-cell FTIR configurations in automotive component quality assurance workflows.
United Arab Emirates
Desalination and power co-generation facilities prioritize real-time oil degradation tracking under MOHAP industrial safety frameworks for critical rotating machinery. IMO 2020 sulfur regulation compliance positions Dubai maritime services for expanded vessel lubricant analysis contracts. Jebel Ali port logistics hubs concentrate third-party testing facility investment serving Red Sea and Gulf shipping corridors.
FTIR Oil Condition Monitoring Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-integrated predictive analytics subscriptions. The vendor base stratifies across three maturity tiers: heritage spectroscopy instrument manufacturers, global inspection networks with laboratory infrastructure, and specialized fluid analysis service providers. Strategic archetypes include integrated testing-certification workflows, point-of-use diagnostic portability, and multi-site dashboard convergence. Dominant competitive moves encompass predictive analytics subscription bundling and field-deployable unit modularization around interchangeable sampling interfaces.
Among heritage spectroscopy specialists, PerkinElmer occupies a position exemplifying premium laboratory instrument anchoring through spectral resolution heritage. SGS SA and Bureau Veritas represent the global inspection network archetype, sustaining credibility among marine and aerospace certification workflows through integrated testing and standardized reference material traceability. These three entities illustrate how vendor engagement models diverge between capital equipment procurement and recurring service contract structures.
| Leading Market Players |
|---|
| PerkinElmer |
| Optimas Instruments |
| SGS SA |
| Parker Hannifin |
| Spectro Scientific |
| Bureau Veritas |
| eralytics |
| Oil Check Laboratory Services |
| Intertek Group |
| Others |
Supply & Pricing Matrix
Solid-state detector miniaturization simultaneously collapses manufacturing cost curves for portable FTIR units and concentrates sourcing leverage among German and Japanese optical component specialists. This technology transition redistributes value capture from laboratory instrument vendors toward field-deployable system integrators who bundle predictive analytics subscriptions.
Pricing Analysis
Distributor margins on portable FTIR analyzers compress as direct-to-utility procurement channels expand under power generation predictive maintenance contracts. Three-tier pricing structure across premium laboratory systems, standard portable units, and economy screening devices reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from Raman spectroscopy substitutes encroaching on routine contamination screening where molecular specificity requirements are less stringent. Construction equipment fleet operators exhibit highest price sensitivity due to distributed site economics, while aerospace MRO facilities prioritize reference standard traceability over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with certified lubricant reference material suppliers concentrated in Germany, the United Kingdom, and Switzerland. Mid-infrared detector production draws from Japanese semiconductor foundries and German precision optics manufacturers, with calibration standard synthesis anchored in European chemical laboratories. Tariff exposure on optical-grade germanium and zinc selenide crystals creates input cost volatility for detector assembly. Distribution runs through specialized analytical instrument distributors serving power generation and petrochemical corridors, supplemented by direct OEM relationships for online monitoring system deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FTIR oil condition monitoring vendors capture margin expansion through predictive analytics subscription bundling that transforms capital equipment sales into recurring revenue streams. Solid-state detector cost curves and cloud platform convergence enable this premium-tier shift.
For Market Incumbents: Deepen vertical integration into mid-infrared detector supply chains to insulate against germanium and zinc selenide tariff volatility. Anchor laboratory instrument positions through ASTM D7412 and DIN 51575 certification investments that emerging Raman competitors cannot replicate. Consolidate service revenue models around condition-based contracts that absorb turbine outage performance risk.
For New Entrants and Emerging Players: Capture marine shipping corridor demand from IMO 2020 sulfur regulation compliance by positioning portable analyzers with modular ATR probes for vessel point-of-use deployment. Target construction equipment fleet operators in China's Yangtze River Delta manufacturing zones where REACH documentation requirements for EU-bound exports create analytical service gaps. Pursue cloud-native dashboard convergence as the primary go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized fluid analysis service providers lacking predictive algorithm capabilities. Long-term viability favors vendors with installed base data feeds that refine degradation curve accuracy across the projection horizon. Acquisition targets should demonstrate direct DCS integration competence for power generation utility procurement. Watch for REACH chemical disclosure enforcement timeline acceleration as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Subscription Bundling | Transforms capital equipment vendors into recurring revenue platforms serving multi-site manufacturing plants. |
| Modular Sampling Interface Expansion | Enables portable FTIR units to address transmission cell, ATR probe, and flow-through cell applications without hardware replacement. |
| REACH Compliance Documentation Integration | Positions systems for ECHA enforcement timelines requiring auditable additive depletion tracking in German automotive supply chains. |
| Cloud-Based Dashboard Convergence | Aggregates distributed analyzer outputs into centralized lubricant health visibility for reliability engineering teams. |
| Direct DCS Integration Development | Eliminates custom middleware barriers that currently block portable analyzer adoption in legacy plant historian environments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with reliability engineering directors, predictive maintenance program managers, laboratory service contract administrators, and FTIR instrument procurement leads at power generation utilities with secondary validation against ASTM D7412 standard documentation, EPA waste oil classification protocols, ECHA REACH enforcement timelines, and customs trade data on optical component imports. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
Segment-weighting approaches modeled technology selection, deployment mode, end-user industry vertical, and application chemistry across the projection horizon. Analytical frameworks derived CAGRs from historical adoption curves in predictive maintenance program penetration, regulatory mandate expansion timelines, and portable device miniaturization cost trajectories. Forecast inputs incorporated power generation utility capital expenditure patterns and marine shipping corridor lubricant formulation change schedules.
Regulatory enforcement delays, reference standard supply disruptions, and vibrational spectroscopy substitution acceleration are the dominant revision risks that could compress or extend modeled adoption curves. Forecasts reflect documented assumptions about OSHA maintenance standard expansion and REACH chemical disclosure amendment timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
United States Natural Gas Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market