
 Global Anti-Fog Additives Market | 2026-2036
Global Anti-Fog Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Fog Additives Market Foresight
ISO 22000 food-contact certification is collapsing the supplier base into qualified compounders with verified migration testing. Croda International Plc leverages its bio-based surfactant portfolio to anchor premium positions in European food packaging. Evonik Industries AG sustains R&D intensity across additive masterbatch formulations for high-clarity agricultural films. Clariant AG dominates specialty surfactant supply to Asian flexible packaging converters with localized technical service.
Anti-fog additives are surface-active compounds, typically glycerol esters or sorbitan derivatives, that lower interfacial tension between condensed moisture and polymer substrates to maintain optical clarity in packaging and glazing applications. These additives migrate to the film surface at controlled rates, forming a hydrophilic layer that spreads water droplets into uniform sheets rather than discrete fogging beads, preserving visibility and product presentation. Surfactant-based formulations lead volume due to cost efficiency in polyethylene food wrap, while additive masterbatches capture expanding margin pools as converters seek dosing precision and reduced handling complexity. Powder and granule forms compete on processing compatibility, though liquid emulsions gain traction in inline coating operations for electronics and automotive glazing where film thickness tolerances tighten.
REACH registration through ECHA governs surfactant chemistries in Europe, while FDA food-contact notifications under 21 CFR constrain migration limits for U.S. packaged food applications. China's GB standards for food-contact plastics, administered by SAMR, add a third compliance layer for exporters serving dual-region customers. Stakeholders must monitor regulatory divergence between these three frameworks when selecting base chemistries, as future restriction expansions could disqualify legacy glycerol ester formulations from select end uses.
Market Dynamics
REACH registration deadlines through ECHA are forcing compounders to retire legacy glycerol ester formulations ahead of restriction expansions, collapsing the qualified supplier base into verified migration testers with ISO 22000 certification.
Growth Catalysts
- Shelf-life extension mandates:Food retailers in Germany and China demand longer visibility windows for fresh produce, driving masterbatch adoption in polyethylene food wrap.
- REACH compliance acceleration:ECHA's surfactant registration requirements are disqualifying unqualified compounders, concentrating volume with certified suppliers.
- Agricultural film clarity standards:High-clarity greenhouse specifications in the Netherlands and Spain require precision-dosed additive systems for optical performance.
Market Restraints
- Palm oil derivative volatility:Sorbitan ester feedstock costs fluctuate with Malaysian and Indonesian export policies, compressing margin predictability for European formulators.
- Migration testing bottlenecks:ISO 22000 certification queues at European laboratories extend qualification timelines for new compound entrants.
- Polymer substrate incompatibility:Glycerol ester formulations demonstrate poor adhesion in polypropylene agricultural films, limiting application scope.
Strategic Opportunities
- Bio-based surfactant white space:European converters seeking Green Deal alignment present premium positioning potential for plant-derived alternatives to petroleum-based esters.
- Electronics glazing inline coating:Liquid emulsion application systems for automotive display covers remain underpenetrated versus film-based solutions.
- India flexible packaging expansion:FSSAI food-contact standard harmonization with CODEX principles opens qualification pathways for export-certified compounders.
Industry Challenges
- Migration testing talent scarcity:Qualified analytical chemists capable of ISO 22000 verification protocols command premium compensation in Germany and Switzerland.
- Multi-jurisdiction compliance stacking:Simultaneous REACH, FDA 21 CFR, and SAMR GB standard navigation requires dedicated regulatory affairs infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Fog Additives Market |
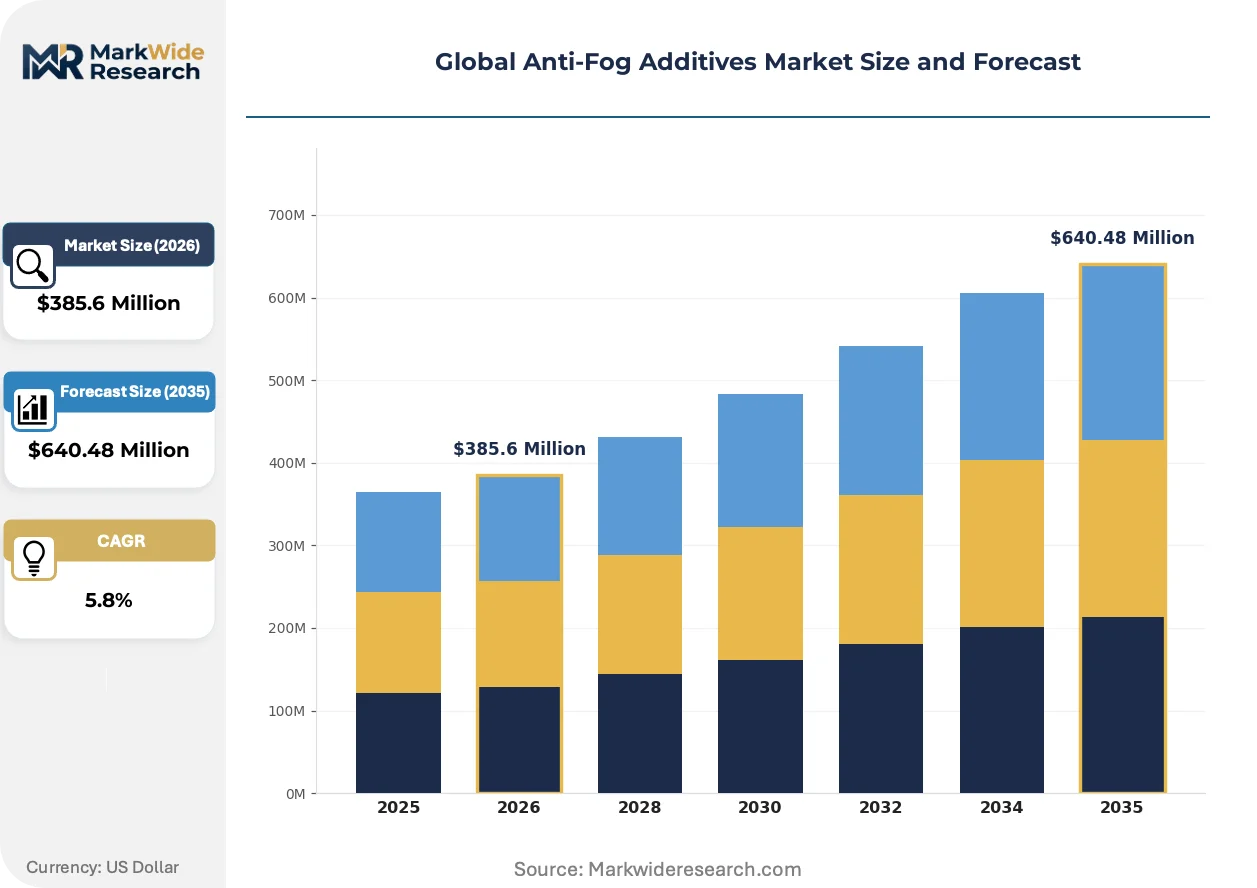
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Polyethylene, Polypropylene, Additive Masterbatches Application: Food Packaging, Electronics, Automotive, Construction Form: Liquid, Powder, Granules, Emulsion End User: Manufacturers, Distributors, Retailers, Suppliers |
| Companies Covered | Clariant AG, Croda International Plc, Evonik Industries AG, Avient Corporation, Ashland Inc., Corbion, Palsgaard, LyondellBasell Industries Holdings B.V., Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Fog Additives Market Shifts & Advancements
Formulation chemistry is pivoting toward controlled-release architectures that synchronize additive migration rates with film thickness tolerances, enabling thinner gauge applications without optical degradation.
Additive masterbatch technology is miniaturizing dosing precision through twin-screw compounding advances that distribute surfactant loads below 1% by weight. Agricultural film converters in Spain and Italy adopt these systems to maintain clarity thresholds across variable greenhouse climates. The technology is miniaturizing batch-to-batch variation, compressing quality control overhead for mid-volume compounders.
EU F-Gas Regulation amendments are accelerating refrigerant containment standards that indirectly tighten anti-fog performance requirements for cold-chain packaging. Film converters serving Nordic retail chains must now demonstrate sub-zero clarity retention under accelerated aging protocols. Agricultural film segments in Poland and Romania face the steepest compliance ramps as distribution networks expand temperature-controlled fresh produce lanes.
Buyer concentration among German retail cooperatives is consolidating procurement decisions into centralized technical specifications that specify certified compounders exclusively. Smaller flexible packaging converters in Bavaria and Baden-Württemberg lose direct supplier relationships as purchasing authority migrates to cooperative headquarters. This pattern is most visible in fresh produce wrap segments where shelf-life guarantees carry penalty clauses for optical failure.
Global Anti-Fog Additives Market Segmentation
Anti-fog additive specifications diverge sharply across regulatory jurisdictions, with REACH-registered surfactants commanding premium positioning in European food-contact applications while FDA-compliant formulations dominate U.S. flexible packaging procurement. Segmentation strategy must align base chemistry selection with end-use compliance requirements rather than treating product categories as interchangeable.
Product Type:
REACH registration status through ECHA separates qualified surfactant suppliers from legacy compounders facing formulation retirement deadlines.
- Surfactants:Glycerol esters and sorbitan derivatives constitute the foundational chemistry, with migration-controlled architectures enabling sub-1% dosing precision in polyethylene food wrap. German retail cooperatives now mandate ISO 22000-certified surfactant sources exclusively, collapsing procurement options to verified compounders with ECHA-registered dossiers.
- Additive Masterbatches:Twin-screw compounding technology distributes surfactant loads with batch-to-batch variation below 0.3%, compressing quality control overhead for mid-volume converters. Agricultural film specifications in the Netherlands and Spain specify masterbatch delivery to ensure optical clarity consistency across variable greenhouse climates.
- Polyethylene:Base resin compatibility drives surfactant selection for fresh produce packaging, with glycerol ester adhesion limitations constraining application scope.
- Polypropylene:Poor surfactant adhesion in agricultural film substrates restricts penetration despite volume potential in greenhouse glazing segments.
Established volume favors surfactants; emerging adoption favors additive masterbatches.
Application:
Cold-chain packaging specifications in Nordic distribution networks are tightening clarity retention thresholds under accelerated aging protocols.
- Food Packaging:Shelf-life extension mandates from German and Chinese retailers drive masterbatch conversion in polyethylene wrap, with penalty clauses for optical failure concentrating procurement authority among certified compounders. EU F-Gas Regulation amendments indirectly tighten performance requirements through refrigerant containment standards.
- Automotive:Display cover glazing demands liquid emulsion application systems for electronics integration, with inline coating operations gaining traction as film thickness tolerances tighten below 50 microns.
- Electronics:Precision coating requirements for automotive display assemblies remain underpenetrated versus film-based solutions despite technical suitability.
- Construction:Glazing applications face polymer substrate incompatibility constraints that limit surfactant formulation options.
Food packaging commands current volume concentration; automotive electronics coating represents the steepest expansion trajectory.
Form:
Processing compatibility determines form selection, with liquid systems capturing inline coating applications where dosing precision outweighs handling complexity.
- Liquid:Emulsion systems enable direct inline coating for electronics and automotive glazing, eliminating masterbatch compounding steps while demanding precise viscosity control.
- Granules:Twin-screw feeding compatibility makes this the default form for high-volume agricultural film extrusion in Spain and Italy.
- Powder:Dust generation during handling limits adoption to specialized compounding operations with containment infrastructure.
- Emulsion:Water-based delivery systems serve niche electronics coating segments where solvent restrictions apply.
Granules dominate agricultural film throughput; liquid systems are gaining share fastest in precision electronics applications.
End User:
Buyer concentration among German retail cooperatives is consolidating technical specification authority away from regional converters.
- Manufacturers:Polymer compounders in Germany, China, and the United States integrate anti-fog additives into captive masterbatch production, capturing margin pools through vertical control over formulation and distribution.
- Distributors:Technical service capabilities separate qualified distributors from commodity resellers, with localized migration testing support commanding premium positioning in European markets.
- Retailers:Centralized procurement at German cooperative headquarters now specifies certified compounders exclusively, eliminating direct supplier relationships for smaller Bavarian and Baden-Württemberg converters.
- Suppliers:Raw material sourcing for palm oil derivatives faces Malaysian and Indonesian export policy volatility, compressing margin predictability for European formulators.
Manufacturers retain formulation control; distributor technical service capabilities determine competitive survival.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail cooperative procurement in Germany and flexible packaging converter clusters in China concentrate buyer authority, while regulatory divergence across ECHA, FDA, and SAMR frameworks fragments supplier qualification pathways.
United States
Food-contact notification requirements under FDA 21 CFR constrain migration limits for polyethylene fresh produce wrap, driving converters toward certified compounders with verified testing protocols. Cold-chain packaging specifications from major retail distributors now mandate sub-zero clarity retention under accelerated aging protocols. The Midwest polymer compounding corridor around Chicago and Detroit anchors masterbatch production capacity serving domestic flexible packaging demand.
Germany
REACH registration through ECHA disqualifies legacy glycerol ester formulations, collapsing procurement options to ISO 22000-certified suppliers with registered surfactant dossiers. Buyer concentration among Bavarian and Baden-Württemberg retail cooperatives centralizes technical specifications at cooperative headquarters. The Rhine-Main industrial cluster hosts specialized analytical laboratories managing certification queues for migration testing protocols.
China
GB standards administered by SAMR impose food-contact plastic requirements that exporters must navigate alongside REACH and FDA frameworks for dual-region customers. Flexible packaging converter density in the Yangtze River Delta drives surfactant demand for polyethylene food wrap applications. Shanghai and Jiangsu province host polymer compounding infrastructure aligned with high-volume agricultural film and food packaging production.
Netherlands
EU F-Gas Regulation amendments tighten refrigerant containment standards that indirectly raise anti-fog performance thresholds for cold-chain distribution networks serving Nordic retail chains. High-clarity greenhouse specifications in the Westland horticultural district require precision-dosed additive systems for optical performance under variable climate conditions. Rotterdam's logistics hub facilitates surfactant import flows serving European converter demand.
India
FSSAI food-contact standard harmonization with CODEX principles opens qualification pathways for export-certified compounders seeking entry into flexible packaging expansion. Agricultural film demand in Maharashtra and Gujarat drives surfactant consumption for greenhouse glazing applications. Mumbai-Pune industrial corridor polymer processors represent emerging conversion capacity for masterbatch integration.
Global Anti-Fog Additives Market Competitive Landscape
Player mix skews toward specialty chemical multinationals with registered surfactant portfolios, creating a tiered structure where ECHA-compliant compounders capture premium positioning. Three archetypes dominate: vertically integrated polymer producers with captive additive production, independent specialty surfactant houses with migration testing capabilities, and regional masterbatch compounders serving agricultural film converters. Competitive moves concentrate on portfolio diversification into bio-based alternatives and geographic expansion through technical service localization.
Within the specialty surfactant tier, Croda International Plc and Evonik Industries AG exemplify the premium positioning archetype anchored by registered dossier portfolios. Clariant AG occupies a position representing the technical service-intensive model serving Asian flexible packaging converters. These three entities sit within the qualified supplier base that German retail cooperatives now specify exclusively, reflecting the market collapse toward certified compounders with verified migration testing infrastructure.
| Leading Market Players |
|---|
| Clariant AG |
| Croda International Plc |
| Evonik Industries AG |
| Avient Corporation |
| Ashland Inc. |
| Corbion |
| Palsgaard |
| LyondellBasell Industries Holdings B.V. |
| Nouryon |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day ISO 22000 certification queues at German analytical laboratories concentrate pricing power among established compounders with verified migration testing infrastructure, while palm oil derivative volatility feeds cost-plus contract escalations across European surfactant formulations.
Pricing Analysis
Cost-plus contracts indexed to Malaysian palm oil futures dominate surfactant procurement between European formulators and flexible packaging converters. Three-tier pricing structure across REACH-registered premium, FDA-compliant standard, and economy glycerol ester levels separates qualified compounders from legacy suppliers facing formulation retirement. Pricing pressure stems from sorbitan ester feedstock volatility under Indonesian export policy shifts. Small Bavarian converters exhibit highest price sensitivity as retail cooperative procurement centralization eliminates direct supplier negotiation leverage.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes inflate inbound logistics costs for surfactant raw materials sourced from Malaysian and Indonesian oleochemical producers. Supply concentrates in Germany, China, and the United States where polymer compounding infrastructure aligns with flexible packaging converter density. Raw material dependencies rest on palm oil derivatives, glycerol feedstocks, and twin-screw compounding equipment. Single-source vulnerability characterizes REACH-registered surfactant supply as ECHA deadlines collapse the qualified supplier base. Distribution runs through certified masterbatch compounders with localized technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for migration testing and formulation support expand faster than commodity surfactant sales, creating recurring-revenue attach opportunities for compounders with ISO 22000 certification infrastructure.
For Market Incumbents: Shield premium positioning by accelerating bio-based surfactant R&D ahead of EU Green Deal restriction expansions that threaten legacy glycerol ester formulations. Deepen backward integration into palm oil derivative sourcing to compress feedstock volatility exposure. Capture margin pools through captive masterbatch production capacity additions in the Yangtze River Delta serving Chinese flexible packaging converter clusters. For New Entrants and Emerging Players: FSSAI harmonization with CODEX principles in India offers the fastest certification pathway for export-qualified compounders seeking entry into flexible packaging expansion. Target agricultural film converters in Maharashtra and Gujarat with precision-dosed masterbatch systems for greenhouse glazing applications. Penetrate through technical service partnerships with Mumbai-Pune polymer processors lacking in-house formulation expertise. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because REACH, FDA, and SAMR framework divergence creates durable competitive moats for multi-jurisdiction certified compounders. Acquisition targets center on mid-tier European surfactant houses with ECHA-registered dossiers and underutilized analytical laboratory capacity. Watch ISO 22000 certification queue lengths at Rhine-Main laboratories as the inflection signal for supply-constrained pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oleochemical Feedstocks | Captive palm oil derivative supply insulates margins from Malaysian export policy volatility. |
| ISO 22000 Certification Fast-Track Investment | Accelerated migration testing capacity captures procurement mandates from German retail cooperatives. |
| Bio-Based Surfactant Platform Development | Plant-derived ester chemistry aligns with EU Green Deal premium positioning requirements. |
| Twin-Screw Masterbatch Capacity Expansion | Precision dosing below 1% surfactant load serves Netherlands high-clarity greenhouse specifications. |
| Technical Service Localization in Asia | Shanghai-based formulation support penetrates Yangtze River Delta flexible packaging converter clusters. |
Research Methodology
The analysis maps surfactant chemistry tiers, additive masterbatch formulations, and application-specific compliance requirements, each validated through technical directors at polymer compounders, procurement leads at German retail cooperatives, regulatory affairs specialists navigating ECHA-FDA-SAMR frameworks, and agricultural film converters in the Netherlands and Spain. Primary interview insights triangulate against secondary sources including ECHA registration dossiers, FDA 21 CFR food-contact notifications, SAMR GB standards publications, and SEC filings from listed specialty chemical producers. Bottom-up volume estimates from end-use consumption patterns reconcile with top-down value projections across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions spanning product type chemistry architectures, application compliance requirements, form factor processing compatibility, and regional regulatory cluster intensity. CAGRs derive from regression analysis of historical consumption patterns and forward-looking capacity expansion announcements. Industry-specific forecast inputs include REACH registration deadline impacts on supplier base consolidation and EU F-Gas Regulation amendments affecting cold-chain packaging performance specifications.
Underlying assumptions cover sustained palm oil derivative supply availability, stable ECHA-FDA regulatory divergence, and continued retail cooperative procurement centralization, with deviation risk concentrated in Malaysian-Indonesian export policy shifts and ISO 22000 certification bottleneck persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Glycol Acetate Market
Additives
Chemical Silage Additives Market
Additives
Global Butyric Acid Derivatives Market
Additives
Global Dicalcium Phosphate (Feed Grade) Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
Europe Fuel Additives Market
Additives
South America Sodium Reduction Agents Market
Additives
Thallium Acetate Market
Additives
Pectin Market
Additives
Green Polymer Additive Market
Additives
Benzoates Market
Additives
Spain Anti Caking Market
Additives
Sorbitan Tristearate Market
Additives
Viscosity Index Improvers Market
Additives
Global Low-Profile Additive Market
Additives
Plastics Modifiers Market