
 Benzoates Market | 2026-2036
Benzoates Market Size, Share, and Industry Trends Forecast 2026-2036
Benzoates Market Analysis
Direct procurement channels between benzoate producers and multinational food processors is rewriting traditional distributor relationships in the preservatives trade. LANXESS AG leverages its integrated aromatics platform to sustain cost advantages across European supply corridors. Emerald Kalama Chemical anchors North American availability through its Kalama, Washington manufacturing complex. Eastman Chemical Company differentiates via specialized grades for pharmaceutical and personal care applications.
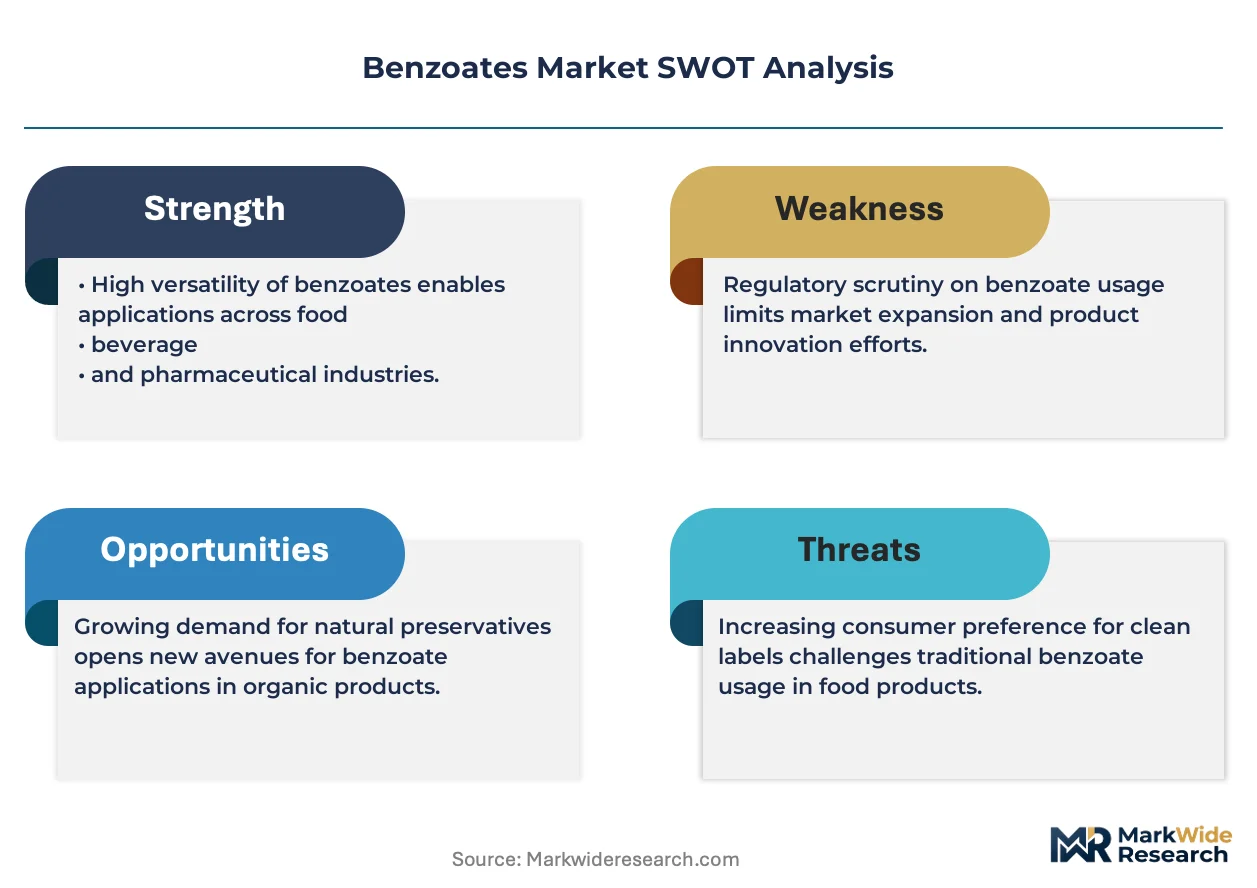
Benzoates are aromatic carboxylate salts and esters derived from benzoic acid, typically manufactured through catalytic oxidation of toluene followed by neutralization with alkali metals; these compounds function primarily as antimicrobial preservatives, pH buffers, and chemical intermediates across formulated goods. Sodium benzoate occupies the dominant volume position due to its solubility profile and cost efficiency in beverage systems, while potassium benzoate is gaining traction in low-sodium formulations where substitution ratios favor cleaner-label positioning. The powder form commands the largest share of commodity transactions, though liquid benzoate concentrates are expanding in automated dosing installations.
The FDA governs benzoate usage limits under 21 CFR 184.1733, while REACH and F-Gas Regulation in Europe impose purity and environmental handling standards that filter non-compliant suppliers from qualified vendor lists. China's SAMR and GB standards for food additives create a parallel compliance architecture that shapes export eligibility for domestic manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to align formulation strategies and avoid reformulation costs.
Market Dynamics
Direct procurement channels between benzoate producers and multinational food processors are compressing traditional distributor margins while REACH compliance and FDA food additive standards tighten purity benchmarks across supply corridors.
Growth Catalysts
- Processed food preservation demand:Sodium benzoate adoption accelerates in beverage systems and shelf-stable sauces as manufacturers seek cost-efficient antimicrobial solutions.
- REACH compliance filtering:European purity benchmarks are disqualifying non-compliant suppliers from qualified vendor lists, consolidating procurement toward certified producers.
- Low-sodium formulation pivot:Potassium benzoate gains traction in clean-label positioning where substitution ratios favor reduced sodium content.
Market Restraints
- Toluene feedstock volatility:Catalytic oxidation input costs fluctuate with aromatic hydrocarbon pricing, compressing margin stability for neutralization-stage producers.
- China supply concentration:Wuhan Youji Industries and domestic chemical clusters anchor regional capacity, creating single-source vulnerability for international buyers.
- Benzoic acid substitution threat:Sorbates and natural preservation systems displace benzoates in premium organic formulations where label simplicity commands priority.
Strategic Opportunities
- Pharmaceutical-grade specialization:USP and EP-compliant benzoate grades for injectable formulations command pricing premiums in parenteral drug manufacturing.
- Liquid concentrate automation:Automated dosing installations in high-volume beverage bottling plants favor liquid benzoate concentrates over powder handling systems.
- SAMR export alignment:Chinese manufacturers aligning with GB food additive standards unlock eligibility for processed food supply chains serving domestic and export markets.
Industry Challenges
- Regulatory divergence management:Formulation teams must reconcile 21 CFR 184.1733 limits, REACH purity tiers, and SAMR GB standards to avoid cross-border reformulation costs.
- Legacy powder handling infrastructure:Beverage manufacturers with established pneumatic conveying systems face capital friction converting to liquid concentrate dosing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzoates Market |
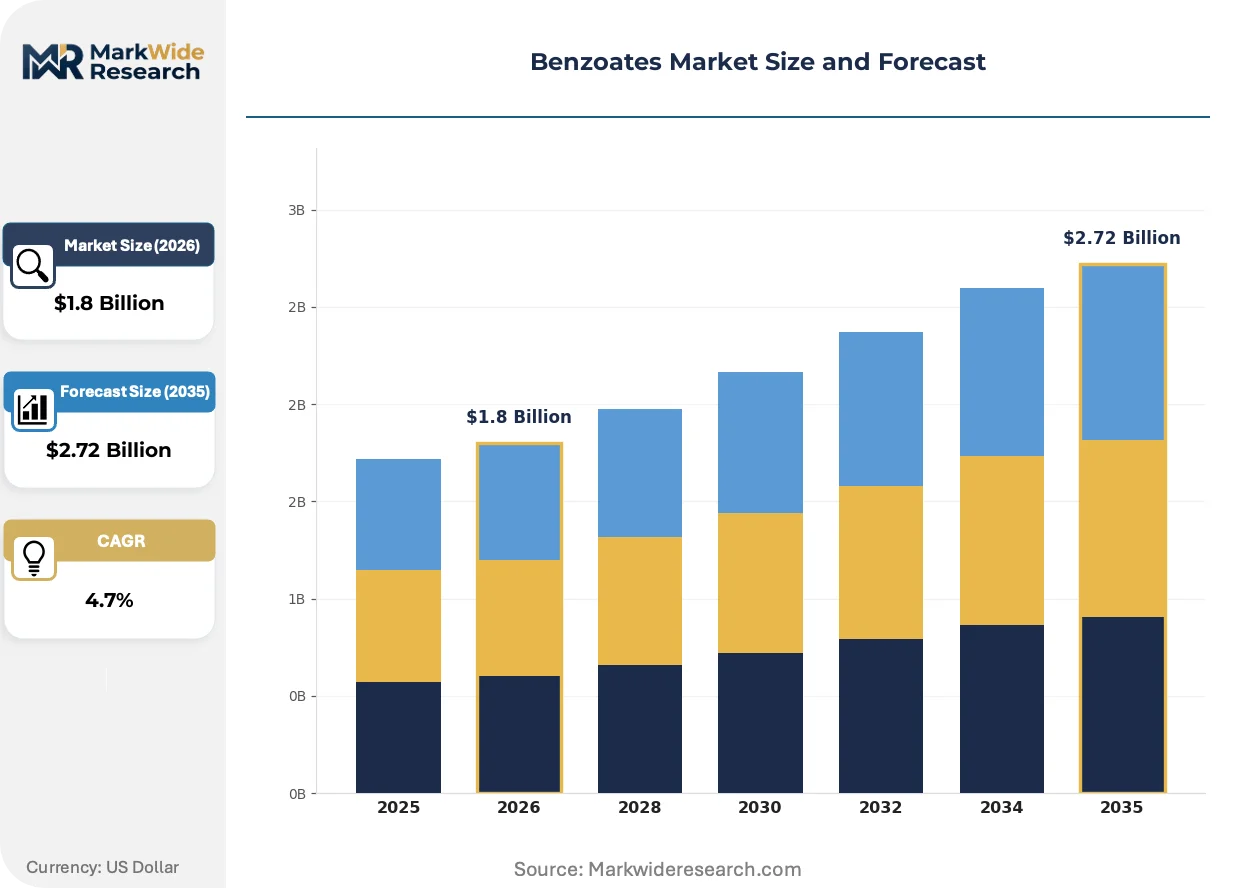
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Benzoate, Potassium Benzoate, Benzoic Acid, Calcium Benzoate End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Agriculture Form: Powder, Liquid, Granule, Crystal Application: Preservative, Flavoring Agent, pH Control Agent, Chemical Intermediate |
| Companies Covered | LANXESS AG, Eastman Chemical Company, Emerald Kalama Chemical, Wuhan Youji Industries Co., Ltd., Tengzhou Tenglong Chemical Co., Ltd., Ganesh Benzoplast Limited, Merck KGaA, Vertellus, Tokyo Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzoates Market Emerging Trajectories
Clean-label preservation strategies and automated manufacturing architectures are compressing traditional benzoate deployment models while regulatory fragmentation forces parallel compliance investments.
Continuous flow reactor technology for toluene oxidation is collapsing batch manufacturing economics in benzoic acid production. European aromatics platforms adopt these systems to reduce solvent waste and energy intensity. The capital efficiency gains are compressing regional cost differentials between integrated and merchant producers.
REACH F-Gas Regulation and evolving ECHA substance evaluation protocols are tightening environmental handling standards for benzoate manufacturing effluents. European producers invest in closed-loop neutralization and crystallization systems to maintain qualified supplier status. Food-grade certification timelines now extend eighteen to twenty-four months for new market entrants.
Direct supplier-procurement relationships between benzoate manufacturers and multinational beverage processors are displacing regional distributor networks. Large-scale bottlers in North America and Western Europe negotiate volume commitments with integrated producers. The channel compression is most visible in carbonated soft drink and ready-to-drink tea manufacturing where formulation consistency requirements dominate sourcing decisions.
Benzoates Market Segmentation
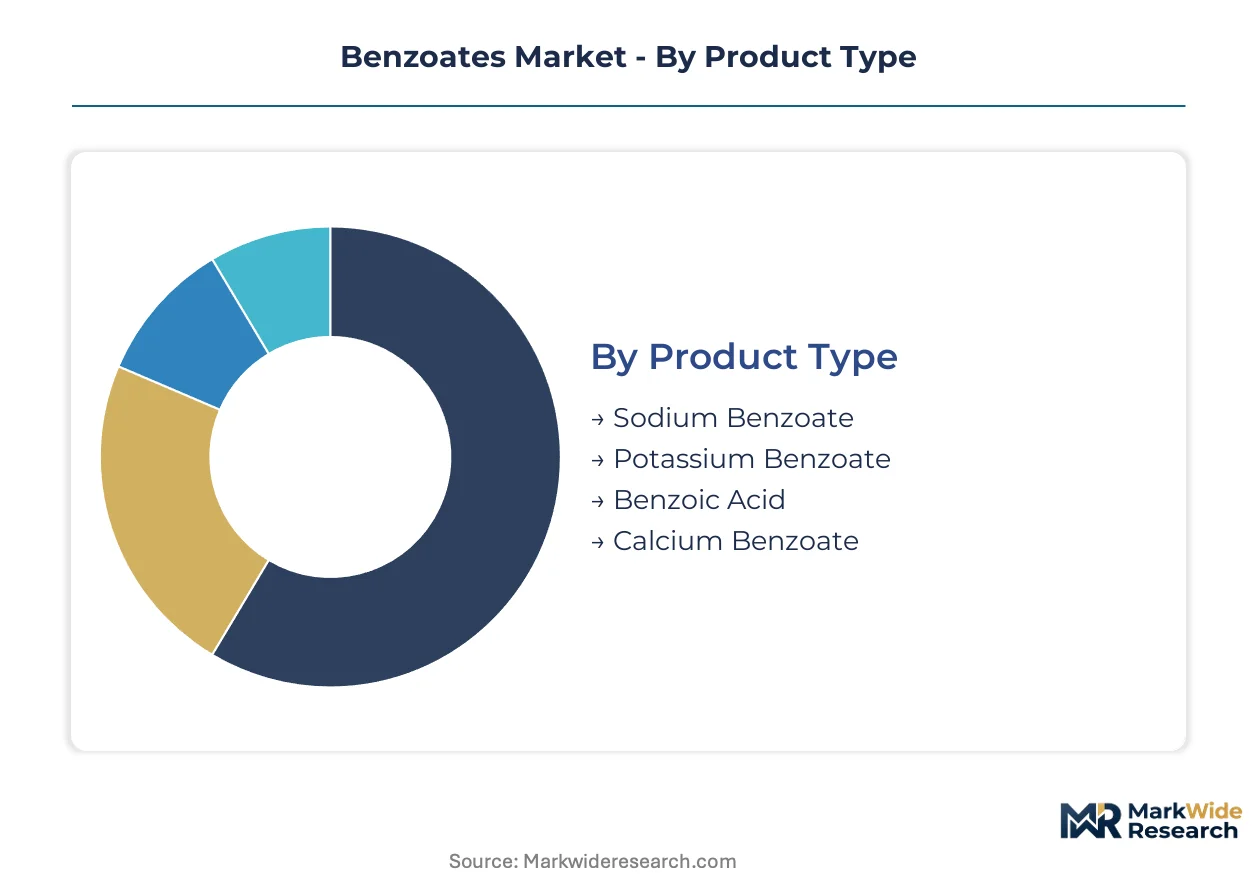
Benzoate procurement patterns diverge sharply across product chemistry, end-use specifications, and physical form. Understanding these segment boundaries clarifies why pharmaceutical-grade sodium benzoate commands fundamentally different pricing logic than commodity powder grades destined for beverage preservation.
Product Type:
Cycle times vary dramatically across benzoate chemistries, with sodium benzoate turning inventory weekly in beverage supply chains while calcium benzoate sits in pharmaceutical safety stock for months.
- Sodium Benzoate:The sodium salt of benzoic acid delivers superior water solubility, making it the default preservative in acidic beverage systems. Demand concentrates in carbonated soft drink and ready-to-drink tea manufacturing across the United States and Western Europe, where FDA 21 CFR 184.1733 compliance is non-negotiable for supplier qualification.
- Potassium Benzoate:Potassium substitution enables sodium reduction claims in clean-label formulations targeting health-conscious consumers. German and French beverage processors favor this grade for mineral water and functional drink lines where sodium content faces regulatory scrutiny under EFSA guidelines.
- Benzoic Acid:The parent acid serves chemical synthesis and intermediate applications rather than direct food use, with longer production runs and slower inventory velocity.
- Calcium Benzoate:Limited adoption in specialized pharmaceutical buffering and select agricultural formulations, with procurement cycles driven by batch manufacturing schedules rather than continuous processing.
Sodium benzoate anchors the volume base while potassium benzoate gains share at the steepest rate.
End Use Industry:
Margin structures stratify sharply across end-use verticals, with pharmaceutical applications tolerating purity premiums that food processors reject.
- Food & Beverage:The dominant consumption channel, spanning carbonated beverages, sauces, dressings, and shelf-stable condiments. Sodium benzoate integration at 0.05-0.1% concentrations provides cost-efficient antimicrobial protection against yeast and mold in acidic pH environments.
- Pharmaceuticals:USP and EP-compliant grades for parenteral and oral drug formulations command substantial pricing premiums. Injectable applications demand particulate-free specifications with extended certification timelines.
- Cosmetics:Personal care preservation in lotions and creams, where benzoate esters compete with paraben alternatives in formulation decisions.
- Agriculture:Niche applications in animal feed preservation and crop protection intermediates, with seasonal demand patterns tied to planting cycles.
Food and beverage anchors the volume base while pharmaceuticals gains share at the steepest rate.
Form:
Capital investment requirements separate form segments, with powder handling infrastructure already sunk across legacy facilities while liquid dosing demands new automation expenditure.
- Powder:Standard particulate grades dominate commodity transactions, compatible with existing pneumatic conveying and batch weighing systems in established processing plants.
- Liquid:Pre-dissolved concentrates reduce dust exposure and enable automated inline dosing in high-speed bottling operations. German and Dutch beverage manufacturers lead adoption of liquid delivery systems.
- Granule:Intermediate flow characteristics for applications where dust generation must be minimized but full dissolution is not pre-engineered.
- Crystal:High-purity crystalline grades for pharmaceutical and laboratory specifications, with slower throughput and higher unit economics.
Powder anchors the volume base while liquid gains share at the steepest rate.
Application:
Functional positioning determines pricing power, with preservative applications competing on cost while chemical intermediate sales track aromatic hydrocarbon feedstock indices.
- Preservative:Antimicrobial functionality against bacteria, yeast, and mold in acidic food systems. Sodium and potassium salts dominate this application, with performance validated against specific pathogen panels under FDA and EFSA protocols.
- Flavoring Agent:Benzoate derivatives contribute bitter, medicinal, or aromatic notes in specific flavor compositions, though this application represents minor volume.
- pH Control Agent:Buffering capacity in pharmaceutical formulations and industrial processes, where precise acidity management is critical.
- Chemical Intermediate:Feedstock for plasticizers, perfumes, and specialty chemical synthesis, with demand tied to downstream aromatic chemistry cycles rather than food industry patterns.
Preservative anchors the volume base while chemical intermediate gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European benzoate producers command pricing premiums through REACH-certified purity tiers, while Chinese manufacturers anchor volume supply at compressed margins through Wuhan and Shandong chemical clusters. This asymmetry reshapes procurement geography as multinational food processors dual-source across both corridors.
United States
Carbonated beverage bottlers and sauce manufacturers drive sodium benzoate consumption through high-throughput automated lines. FDA 21 CFR 184.1733 compliance requirements filter supplier qualification toward certified domestic and import sources. The Kalama manufacturing complex in Washington anchors North American supply capacity for preservative-grade output.
Germany
Functional drink and mineral water processors favor potassium benzoate for sodium-reduced formulations targeting EFSA-aligned nutrition claims. REACH and F-Gas Regulation impose closed-loop manufacturing standards that extend certification timelines for new entrants. The Cologne-Leverkusen aromatics corridor sustains integrated production economics through LANXESS AG's captive feedstock access.
China
Processed food export manufacturing and domestic beverage expansion concentrate demand in coastal provinces. SAMR GB standards for food additives create parallel compliance architecture alongside import-market regulations. Wuhan Youji Industries anchors Central China supply capacity, while Shandong chemical clusters compete on neutralization-stage cost efficiency.
India
Pickle, chutney, and ready-to-eat meal preservation drives sodium benzoate adoption in acidic food systems. FSSAI food additive standards and BIS quality certifications shape import and domestic sourcing decisions. Maharashtra and Gujarat pharmaceutical corridors generate parallel demand for USP-grade benzoates in parenteral drug manufacturing.
Japan
Precision beverage formulation and cosmetic preservation sustain demand for high-purity benzoate grades. METI chemical substance regulations and JIS standards enforce manufacturing quality protocols that limit qualified supplier pools. The Kansai industrial belt maintains specialized crystallization capacity for pharmaceutical and electronics-grade specifications.
Benzoates Market Vendor Landscape
Integrated aromatics platforms and neutralization-stage specialists split the market between captive feedstock advantages and merchant chemical flexibility. The vendor base concentrates around three strategic archetypes: multinational diversified chemical conglomerates with backward integration into toluene oxidation, regional merchant producers serving food-grade commodity demand, and pharmaceutical-grade specialists commanding certification premiums. Competitive positioning hardens through REACH compliance investments and direct procurement relationships with multinational beverage processors.
Within the integrated conglomerate tier, LANXESS AG exemplifies European aromatics platform economics, while Eastman Chemical Company occupies a position spanning specialty grades for regulated end-uses. Among Asia-Pacific merchant producers, Wuhan Youji Industries Co., Ltd. represents the scale-driven neutralization-stage archetype serving export-oriented food manufacturing demand.
| Leading Market Players |
|---|
| LANXESS AG |
| Eastman Chemical Company |
| Emerald Kalama Chemical |
| Wuhan Youji Industries Co., Ltd. |
| Tengzhou Tenglong Chemical Co., Ltd. |
| Ganesh Benzoplast Limited |
| Merck KGaA |
| Vertellus |
| Tokyo Chemical Industry Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Toluene feedstock volatility compresses margin stability across neutralization-stage producers, forcing a three-tier pricing structure across premium, standard, and economy levels while simultaneously reshaping procurement geography toward integrated aromatics platforms with captive oxidation capacity.
Pricing Analysis
The customization-premium spread separates pharmaceutical-grade USP/EP specifications from commodity beverage-grade powder, with injectable particulate-free standards commanding substantial premiums over standard preservative tiers. Price differentiation rests on certification timelines and REACH compliance status, with eighteen-to-twenty-four-month food-grade certification windows filtering new entrants. Cost compression in standard-grade sodium benzoate intensifies because of merchant producer competition in Shandong chemical clusters. Large-scale beverage processors exhibit lowest price sensitivity due to formulation consistency requirements, while regional sauce manufacturers face highest cost pressure.
Supply Chain Analysis
Tariff exposure between Chinese neutralization-stage producers and European beverage processors dominates supply chain risk calculus, accelerating dual-sourcing strategies across Wuhan and Kalama manufacturing corridors. Geographic supply concentration centers on China, Germany, and the United States, with Wuhan Youji Industries and LANXESS AG anchoring regional capacity. Raw material dependencies draw from toluene aromatic hydrocarbons, alkali metal hydroxides, and catalytic oxidation catalysts. Single-source vulnerability concentrates in Central China chemical clusters. Distribution runs through direct procurement channels between integrated producers and multinational food processors, displacing traditional regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement relationships between multinational beverage processors and integrated aromatics producers, consolidating volume commitments and squeezing regional distributor margins across North American and European supply corridors.
For Market Incumbents: Entrench REACH-certified supplier status through closed-loop neutralization and crystallization system investments, defending against sorbate and natural preservation substitution threats in premium organic formulations. Deepen backward integration into toluene oxidation capacity to neutralize feedstock volatility exposure and sustain cost advantages across European supply corridors. For New Entrants and Emerging Players: Establish a beachhead in liquid benzoate concentrate automation for high-speed beverage bottling installations, where capital friction from legacy powder handling infrastructure creates white-space opportunity. Target pharmaceutical-grade parenteral specifications with USP/EP-compliant production, leveraging extended eighteen-to-twenty-four-month certification timelines as a competitive moat against commodity producers. For Investors and Strategic Acquirers: REACH F-Gas Regulation and evolving ECHA substance evaluation protocols reshape the acquisition landscape, elevating environmental handling compliance as a valuation differentiator. Long-term viability favors integrated aromatics platforms with captive feedstock access over merchant neutralization-stage specialists. Monitor SAMR GB standard alignment progress among Chinese manufacturers as the signal indicating export eligibility inflection for processed food supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Oxidation | Captive aromatic feedstock access insulates LANXESS AG from merchant toluene price swings. |
| Pharmaceutical-Grade Certification Investment | USP and EP compliance unlocks parenteral drug manufacturing premiums in Maharashtra corridors. |
| Liquid Concentrate Production Capacity | Automated dosing compatibility captures German and Dutch beverage manufacturer procurement shifts. |
| Closed-Loop Manufacturing Transition | REACH F-Gas Regulation compliance maintains qualified supplier status for European food processors. |
| Direct Procurement Channel Development | Volume commitments with multinational bottlers displace regional distributor intermediaries in North America. |
Methodological Framework
Desk research of customs and trade flow databases, SEC 10-K filings, and ECHA substance evaluation protocols preceded structured interviews with plant managers at benzoate production facilities, procurement leads at multinational beverage processors, distribution channel partners in European food-grade chemicals, and technical R&D directors at preservatives formulators. Bottom-up volume triangulation across sodium benzoate, potassium benzoate, and benzoic acid chemistries was cross-validated against top-down value estimates derived from aromatics platform economics and merchant neutralization-stage cost structures.
Fixed assumptions across the projection horizon held regulatory frameworks constant at current REACH, FDA 21 CFR 184.1733, and SAMR GB standard specifications, while toluene feedstock pricing and clean-label substitution rates were varied across stress-test bands. Segmentation dimensions modeled included product chemistry tier, end-use industry vertical, physical form factor, and regional production hub clustering. CAGRs were derived from slope analysis of historical volume trajectories adjusted for capacity expansion announcements and demand elasticity estimates from beverage and pharmaceutical formulation trends.
Stress conditions across toluene aromatic hydrocarbon volatility, REACH compliance timeline extensions, and sorbate substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification timeline stability and dual-sourcing procurement pattern persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Disodium Inosinate Market
Additives
Global Silica-Based Matting Agents Market
Additives
Fluoropolymer Additives Market
Additives
Caustic Sulphite Caramel Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Driveline Additives Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Potting Mix Additives Market
Additives
China Citric Acid Market
Additives
Metal Deactivators Market
Additives
Sorbitan Oleate Market
Additives
Hydroxyethyl Cellulose Market
Additives
Low VOC Coating Additives Market
Additives
Rheological Additives Market
Additives
Binder Excipients Market