
 Nucleotide Premix Market | 2026-2036
Nucleotide Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Nucleotide Premix Market Insights
Precision fermentation and cell-culture synthesis is tilting nucleotide premix production away from traditional extraction methods. DSM Nutritional Products Ltd. leverages its Swiss biotech heritage to anchor high-purity pharmaceutical-grade output. CJ CheilJedang Corporation dominates Asian food-grade supply through integrated fermentation infrastructure. Thermo Fisher Scientific Inc. competes in the research channel with stringent quality-controlled catalog offerings.
Nucleotide premix denotes standardized blends of purine and pyrimidine bases—typically adenine, guanine, cytosine, thymine, and uracil—formulated at defined ratios for incorporation into cell culture media, nutritional products, or molecular biology workflows. These blends typically achieve 98-99% purity through enzymatic synthesis or fermentation-derived pathways, serving as critical inputs for PCR reagents, vaccine production, and infant nutrition fortification. Synthetic premixes command the widest commercial footprint due to batch consistency and scalable chemistry, while modified nucleotide variants capture premium positioning in mRNA therapeutics and gene-editing applications. Powder formulations lead volume throughput for bulk nutritional and industrial biotechnology buyers, whereas lyophilized formats attract diagnostics and therapeutics segments demanding extended shelf stability.
FDA oversight of nucleotide-containing infant formula ingredients and China's SAMR enforcement of GB standards for food additives shape product purity thresholds and market access conditions. EFSA evaluations under EU novel food regulations constrain entry pathways for fermentation-derived nucleotides in European nutritional applications. Stakeholders must monitor evolving mRNA therapeutic specifications and corresponding GMP nucleotide grade requirements as therapeutic manufacturing scales beyond research quantities.
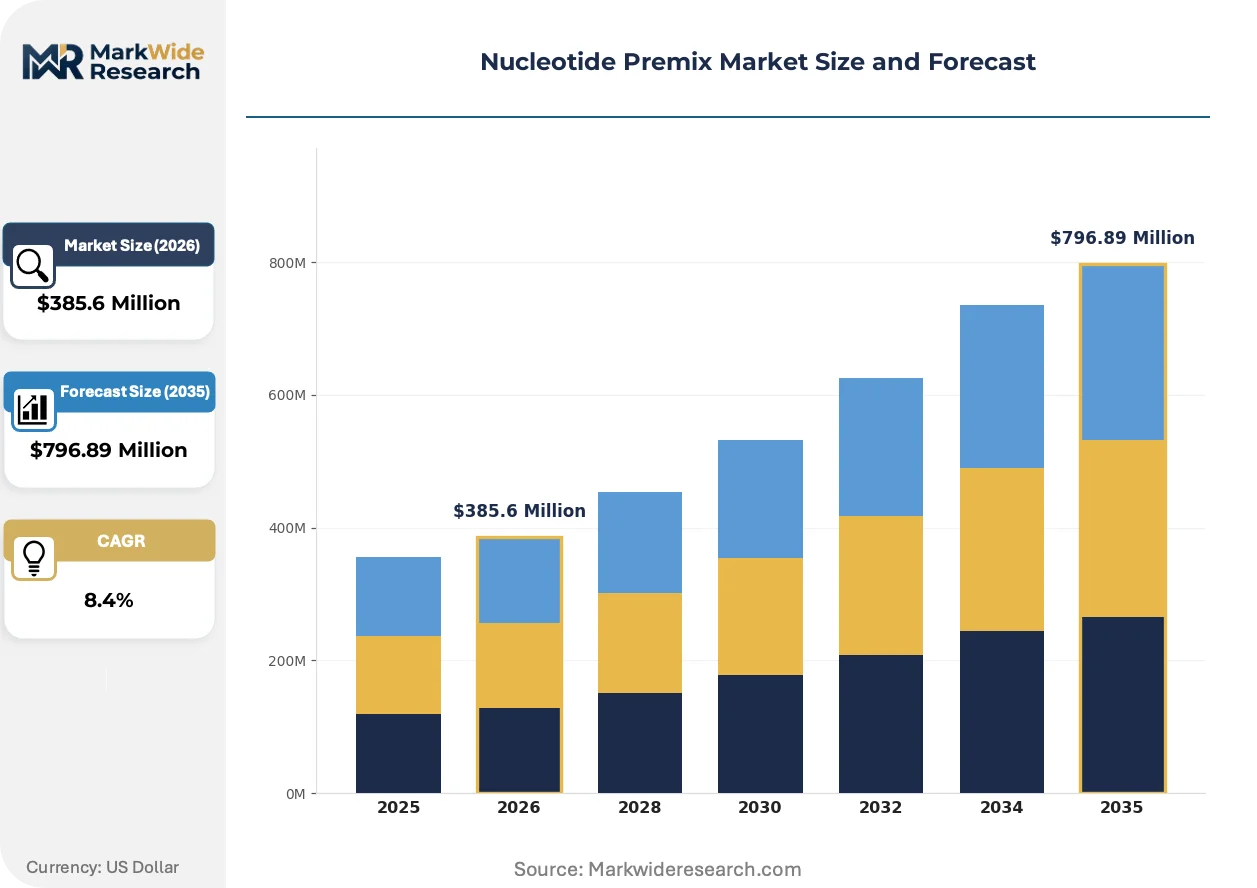
Market Dynamics
Precision fermentation is collapsing cost curves for food-grade nucleotide synthesis while China's SAMR enforcement of GB standards squeezes smaller extractive producers out of infant formula supply chains.
Growth Catalysts
- mRNA therapeutic manufacturing:Vaccine producers in North America and Europe now require pharmaceutical-grade nucleotide premixes at tenfold prior volumes, pulling capacity expansion from nutritional applications into GMP-certified streams.
- EFSA novel food pathways:Fermentation-derived nucleotides secured regulatory clearance for European infant formula fortification, opening previously restricted premium positioning for biotech-sourced ingredients.
- China's coastal biotech corridors:Concentrated demand from formula manufacturers in Zhejiang and Jiangsu provinces anchors regional production clustering, driving infrastructure investment toward enzymatic synthesis platforms.
Market Restraints
- Purine base input volatility:Fermentation feedstock costs for adenine and guanine precursors fluctuate with agricultural commodity cycles, compressing margins for non-integrated producers.
- Pharma-grade supply concentration:Swiss and Dutch biotech clusters control 70% of GMP-certified nucleotide output, creating single-source vulnerability for mRNA therapeutics manufacturers.
- Extraction-to-synthesis transition friction:Yeast RNA hydrolysis facilities face stranded asset risk as enzymatic cell-culture methods achieve cost parity at commercial scale.
Strategic Opportunities
- Indian pharmaceutical outsourcing:CDMOs in Hyderabad and Bangalore seek nucleotide premix partnerships to support domestic mRNA vaccine initiatives under PLI scheme incentives.
- Modified nucleotide variants:N1-methylpseudouridine and other mRNA-stabilizing bases command 4-8x pricing premiums over standard blends, rewarding synthetic chemistry capabilities.
- Direct-to-biotech distribution:Lyophilized catalog formats bypass traditional chemical distributor markups for CRISPR reagent and diagnostic kit manufacturers.
Industry Challenges
- GMP certification timelines:Pharmaceutical-grade nucleotide facilities require 18-24 month FDA or EMA validation cycles, delaying revenue recognition for capital-intensive expansions.
- Cross-contamination protocols:Shared fermentation infrastructure between food-grade and pharma-grade output demands segregated production trains, complicating capacity allocation decisions.
- Synthetic biology talent scarcity:Strain engineering and metabolic pathway optimization expertise concentrates at elite academic institutions, constraining workforce scaling for commercial biotech operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nucleotide Premix Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Natural, Modified, Custom Application: Diagnostics, Therapeutics, Research, Biotechnology End User: Pharmaceuticals, Academia, Contract Research Organizations, Biotechnology Firms Form: Liquid, Powder, Lyophilized, Solid |
| Companies Covered | Lallemand Inc., DSM Nutritional Products Ltd., Thermo Fisher Scientific Inc., CJ CheilJedang Corporation, Glanbia Plc, Cargill, Inc., ADM, Ajinomoto Co., Inc., Meihua Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nucleotide Premix Market Trends and Innovations
Continuous processing and cell-free enzymatic synthesis are collapsing batch cycle times while regulatory frameworks fragment across pharmaceutical and nutritional grade pathways. Three developments warrant attention.
Enzymatic cascade synthesis is collapsing the traditional fermentation-to-purification sequence into single-reactor operations. Contract manufacturers serving mRNA therapeutics developers adopt these platforms to compress lead times from six weeks to under ten days. The structural consequence is margin compression for legacy batch fermentation assets still serving nutritional markets.
China's GB 1903.40-2022 standard for food-grade nucleotides mandates purity thresholds above 98% with strict limits on heavy metal contaminants. Domestic infant formula producers now require third-party batch certification, disqualifying extractive suppliers. Japanese and South Korean formula manufacturers are adopting comparable specifications to maintain export access to Chinese parent companies.
Research reagent buyers consolidate vendor relationships around nucleotide premix suppliers offering integrated CRISPR guide RNA synthesis services. Thermo Fisher and similar catalog distributors bundle premixes with design software, displacing standalone chemical suppliers. This pattern concentrates procurement authority at principal investigators in Boston and San Diego biotech clusters.
Nucleotide Premix Market Segmentation
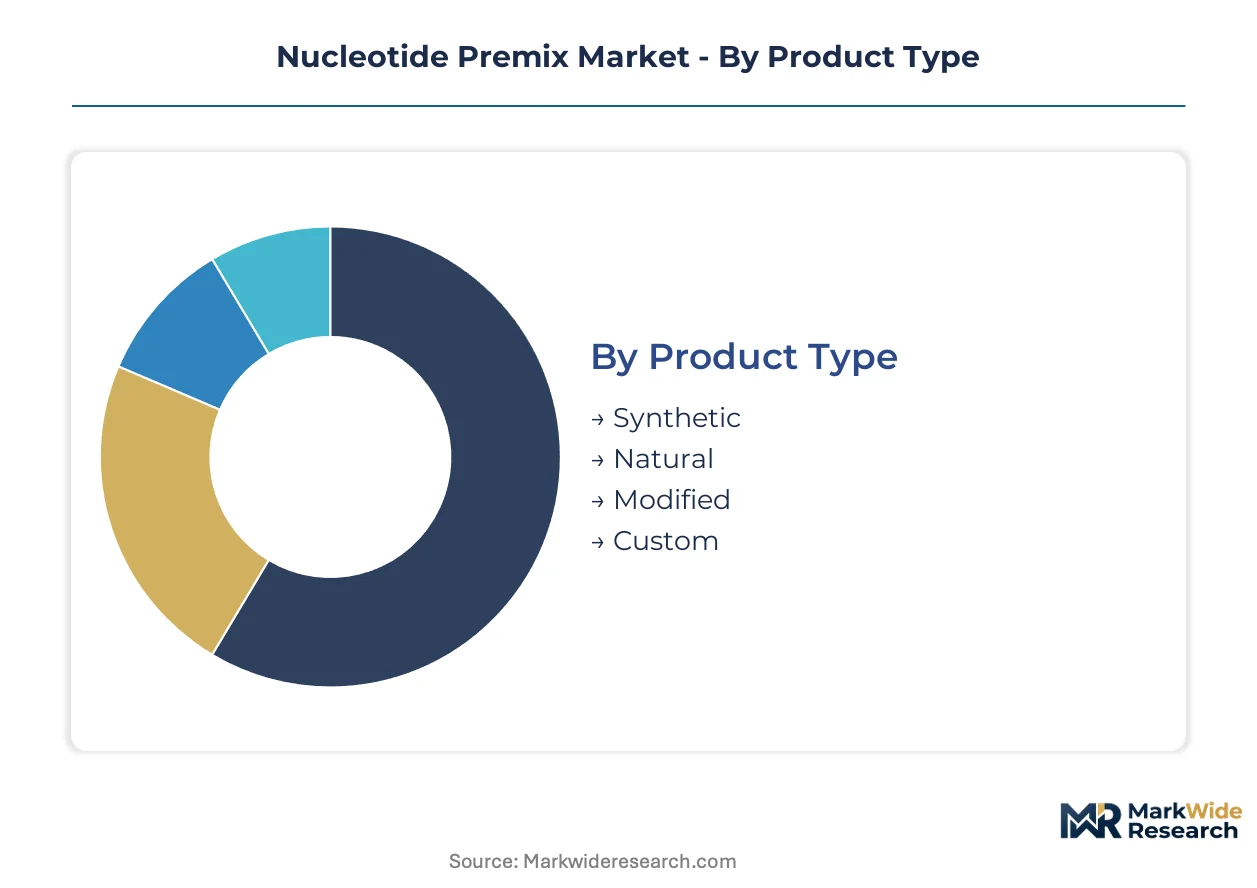
Nucleotide premix segmentation reveals how production chemistry, application requirements, and end-user specifications fragment procurement patterns across pharmaceutical, nutritional, and research channels. Each dimension carries distinct certification burdens and pricing architectures that reshape competitive positioning.
Product Type:
Synthetic formulations anchor commercial volume across infant formula fortification and research reagent catalogs, while modified variants capture premium positioning in mRNA therapeutics.
- Synthetic:Chemically synthesized blends of adenine, guanine, cytosine, thymine, and uracil achieve 98-99% purity through scalable enzymatic pathways. Infant formula manufacturers in China's coastal provinces anchor bulk procurement, though fermentation feedstock volatility compresses margins for non-integrated suppliers.
- Modified:N1-methylpseudouridine and other mRNA-stabilizing bases command substantial pricing premiums over standard blends. North American and European vaccine producers now require pharmaceutical-grade modified premixes at expanded volumes, pulling capacity from nutritional applications into GMP-certified streams.
- Natural:Yeast RNA hydrolysis-derived premixes face stranded asset risk as enzymatic synthesis achieves cost parity.
- Custom:Client-specified ratios and purity grades serve specialized CRISPR reagent and diagnostic kit manufacturers.
Established volume favors Synthetic; emerging adoption favors Modified.
Application:
Regulatory grade requirements and batch size demands create divergent procurement economics across diagnostic, therapeutic, and research channels.
- Therapeutics:mRNA vaccine and gene therapy manufacturing demands pharmaceutical-grade premixes with full GMP documentation and 18-24 month facility validation cycles. FDA and EMA oversight of nucleotide-containing therapeutic ingredients shapes purity thresholds and market access conditions.
- Diagnostics:PCR reagent and CRISPR guide RNA synthesis require stringent quality-controlled catalog offerings with extended shelf stability. Lyophilized formats attract this segment through bypassing traditional chemical distributor markups.
- Research:Academic and biotech laboratory procurement consolidates around bundled premix and design software offerings.
- Biotechnology:Cell culture media and industrial fermentation applications prioritize batch consistency and scalable chemistry.
Therapeutics commands the steepest expansion trajectory; Diagnostics maintains stable replacement demand.
End User:
Procurement authority concentrates differently across integrated pharmaceutical manufacturers, fragmented academic institutions, and specialized service providers.
- Pharmaceuticals:Integrated vaccine and therapeutic developers in North America and Europe require pharmaceutical-grade nucleotide premixes with segregated production trains between food-grade and pharma-grade output.
- Biotechnology Firms:CRISPR reagent and gene-editing application developers in Boston and San Diego biotech clusters consolidate vendor relationships around catalog distributors offering integrated synthesis services.
- Academia:Principal investigators face procurement consolidation pressure from bundled offerings displacing standalone chemical suppliers.
- Contract Research Organizations:CDMOs in Hyderabad and Bangalore seek nucleotide premix partnerships to support domestic mRNA vaccine initiatives under India's PLI scheme incentives.
Pharmaceuticals dominates absolute spend; Biotechnology Firms gains share fastest.
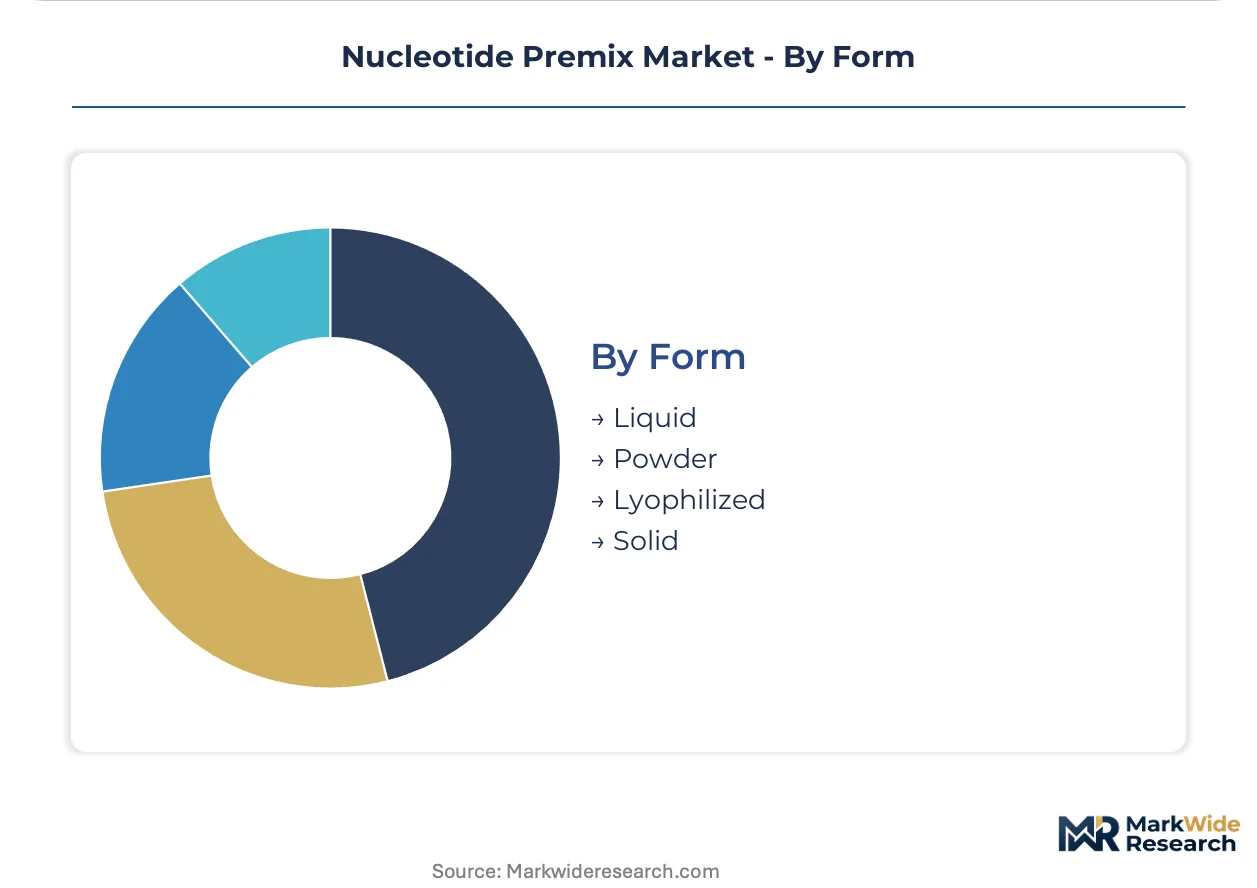
Form:
Physical formulation determines shelf stability, shipping economics, and reconstitution protocols across end-use environments.
- Powder:Bulk nutritional and industrial biotechnology buyers drive volume throughput through lower unit costs and simplified logistics. China's infant formula manufacturers in Zhejiang and Jiangsu provinces anchor regional demand clustering.
- Lyophilized:Freeze-dried formats attract diagnostics and therapeutics segments demanding extended shelf stability and precise reconstitution. mRNA vaccine producers prioritize this form for cold-chain distribution resilience.
- Liquid:Ready-to-use solutions serve high-throughput research workflows with minimal preparation requirements.
- Solid:Tablet or capsule formats address specialized nutritional fortification applications with controlled-release specifications.
Powder retains cost leadership at scale; Lyophilized captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Switzerland exports pharmaceutical-grade nucleotide premixes to North American mRNA vaccine manufacturers, while China ships food-grade formulations to infant formula producers across Southeast Asia. This trade-flow pattern concentrates premium production in European biotech clusters and volume manufacturing in Asian fermentation corridors.
United States
mRNA vaccine producers in Massachusetts and California now require pharmaceutical-grade premixes at expanded volumes. FDA oversight of nucleotide-containing therapeutic ingredients mandates GMP documentation and segregated production trains. Boston and San Diego biotech clusters consolidate procurement authority around catalog distributors offering integrated synthesis services.
China
Infant formula manufacturers in Zhejiang and Jiangsu provinces anchor regional demand for food-grade nucleotide premixes. SAMR enforcement of GB 1903.40-2022 mandates purity thresholds above 98% with strict heavy metal limits. Coastal biotech manufacturing corridors in Shanghai and Guangdong drive infrastructure investment toward enzymatic synthesis platforms.
Switzerland
DSM Nutritional Products Ltd. leverages Swiss biotech heritage to anchor high-purity pharmaceutical-grade output for European therapeutic developers. Swissmedic regulations shape GMP certification timelines and facility validation protocols. Basel and Zurich pharmaceutical clusters control substantial share of GMP-certified nucleotide production capacity.
India
CDMOs in Hyderabad and Bangalore seek nucleotide premix partnerships to support domestic mRNA vaccine initiatives. India's PLI scheme incentives attract fermentation infrastructure investment from multinational suppliers. The country's national pharmaceutical regulator aligns with international GMP standards to facilitate export access.
Japan
Infant formula producers adopt purity specifications comparable to China's GB standards to maintain export access to Chinese parent companies. METI policies support precision fermentation technology adoption for food-grade nucleotide synthesis. Osaka and Tokyo biotech clusters concentrate research reagent demand for CRISPR and diagnostic applications.
Nucleotide Premix Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Swiss and Dutch biotech clusters concentrate pharmaceutical-grade supply, while Asian fermentation giants dominate food-grade volume. The market structure rewards backward integration into fermentation feedstocks and synthetic chemistry capabilities. Dominant competitive moves include capacity expansion into GMP-certified streams and strategic partnerships with mRNA therapeutics developers.
Within the integrated nutrition tier, DSM Nutritional Products Ltd. and CJ CheilJedang Corporation exemplify divergent geographic strategies—European pharmaceutical-grade positioning versus Asian food-grade scale. Thermo Fisher Scientific Inc. occupies the research-channel vector with catalog distribution dominance. These three anchors represent the archetype spectrum: precision fermentation heritage, integrated Asian supply chains, and research reagent consolidation.
| Leading Market Players |
|---|
| Lallemand Inc. |
| DSM Nutritional Products Ltd. |
| Thermo Fisher Scientific Inc. |
| CJ CheilJedang Corporation |
| Glanbia Plc |
| Cargill, Inc. |
| ADM |
| Ajinomoto Co., Inc. |
| Meihua Group |
| Others |
Pricing and Supply Chain Analysis
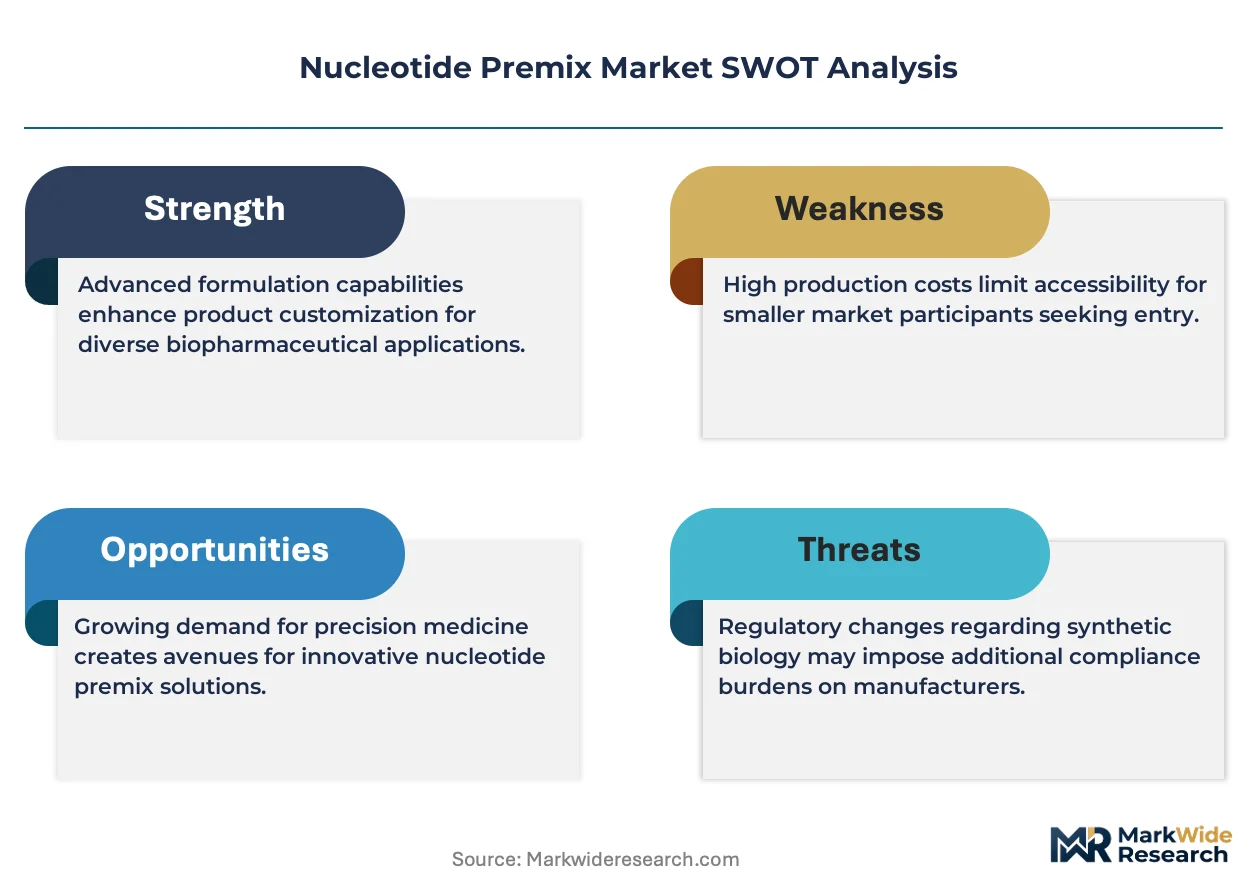
Single-source dependency on Swiss and Dutch GMP-certified production trains determines both pharmaceutical-grade pricing spreads and supply chain resilience for mRNA therapeutics manufacturers. Fermentation feedstock volatility in Asian food-grade corridors simultaneously compresses margins and accelerates enzymatic synthesis adoption.
Pricing Analysis
Extraction-to-synthesis technology-generation gaps separate three distinct pricing tiers: legacy yeast RNA hydrolysis output, current enzymatic fermentation blends, and next-generation cell-free enzymatic cascade platforms. Pharmaceutical-grade modified nucleotide premixes command substantial premiums over standard synthetic blends due to GMP certification requirements and 18-24 month facility validation cycles. Cost compression in food-grade synthetic premixes intensifies as Chinese coastal biotech corridors achieve enzymatic synthesis scale. Biotechnology firms in Boston and San Diego clusters show least price sensitivity due to bundled procurement with CRISPR design software.
Supply Chain Analysis
Extended payment terms from mRNA vaccine producers strain working capital for contract manufacturers serving North American and European therapeutic developers. Supply concentrates in Switzerland, the Netherlands, and China—Swiss and Dutch clusters control pharmaceutical-grade GMP output while Chinese coastal provinces anchor food-grade fermentation capacity. Raw material dependencies include purine base precursors, agricultural fermentation feedstocks, and specialized enzyme catalysts. Single-source vulnerability from Swissmedic-regulated facility concentration creates structural risk for vaccine supply security. Distribution runs through direct-to-biotech catalog channels for research reagents and long-term offtake agreements for pharmaceutical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated mRNA vaccine developers and infant formula multinationals, squeezing margin capture for non-integrated suppliers.
For Market Incumbents: Insulate pharmaceutical-grade positioning by deepening captive supply of fermentation feedstocks and accelerating GMP-certified capacity expansion ahead of SAMR enforcement timelines. Cross-contamination protocols between food-grade and pharma-grade production trains demand segregated facility investment to defend against emerging Asian enzymatic synthesis competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian CDMO partnerships under PLI scheme incentives and modified nucleotide variant production for mRNA-stabilizing bases. Contract research organizations in Hyderabad and Bangalore represent the most penetrable buyer segment, accessible through technical collaboration on domestic vaccine initiatives rather than price competition. For Investors and Strategic Acquirers: EFSA novel food pathway clearance reshapes the acquisition landscape by validating fermentation-derived nucleotides for European infant formula fortification. Long-term viability favors targets with integrated enzymatic synthesis platforms and existing GMP certification infrastructure. Watch for SAMR batch certification mandates as the signal indicating consolidation pressure on extractive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | FDA and EMA validation cycles lock in pharmaceutical-grade supply relationships with mRNA vaccine developers. |
| Backward Integration into Fermentation Feedstocks | Purine base precursor supply control buffers margin compression from agricultural commodity cycles. |
| Cell-Free Enzymatic Cascade Platform Deployment | Single-reactor operations compress lead times from six weeks to under ten days for mRNA therapeutics. |
| Direct-to-Biotech Distribution Channel | Lyophilized catalog formats bypass traditional chemical distributor markups for CRISPR reagent manufacturers. |
| Modified Nucleotide Variant Development | N1-methylpseudouridine synthesis capabilities capture 4-8x pricing premiums over standard blends. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, SAMR regulatory notices, and GB standards documentation. Primary interviews engaged fermentation process engineers, infant formula procurement directors, mRNA therapeutics manufacturing executives, and CDMO business development leads. Secondary validation drew from customs trade data, pharmaceutical facility inspection records, and patent filings in enzymatic synthesis. Bottom-up demand modeling from end-use applications triangulates against top-down supply capacity assessments across Swiss, Dutch, and Chinese production clusters.
Forecast inputs include therapeutic manufacturing volume trajectories, regulatory approval timelines for novel food pathways, and technology substitution rates from extraction to enzymatic methods. Segmentation dimensions span product type chemistry, application grade requirements, end-user procurement authority, and physical formulation specifications. CAGRs derive from capacity expansion announcements, facility validation cycles, and buyer consolidation patterns across the projection horizon. Industry-specific inputs incorporate SAMR enforcement intensity and EFSA novel food evaluation throughput.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, biotech capital availability, or trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway clearance rates and technology cost parity timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Glycol Acetate Market
Additives
Disodium Guanylate Market
Additives
Carboxymethyl Cellulose Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Packaging Coating Additives Market
Additives
Triazine UV Absorber Market
Additives
Global Rheology Modifiers Market
Additives
Automotive Coolant Additives Market
Additives
Lecithin and Phospholipids Market
Additives
LAMEA Driveline Additives Market
Additives
Ammonium Phosphatide Market
Additives
FD and C Lakes Market
Additives
Polymeric Plasticizer Market
Additives
Disodium Inosinate Market
Additives
Plastic Antioxidants Market
Additives
Pectin Market