
 Dewatering Aids Market | 2026-2036
Dewatering Aids Market Size, Share, and Industry Trends Forecast 2026-2036
Dewatering Aids Market Analysis
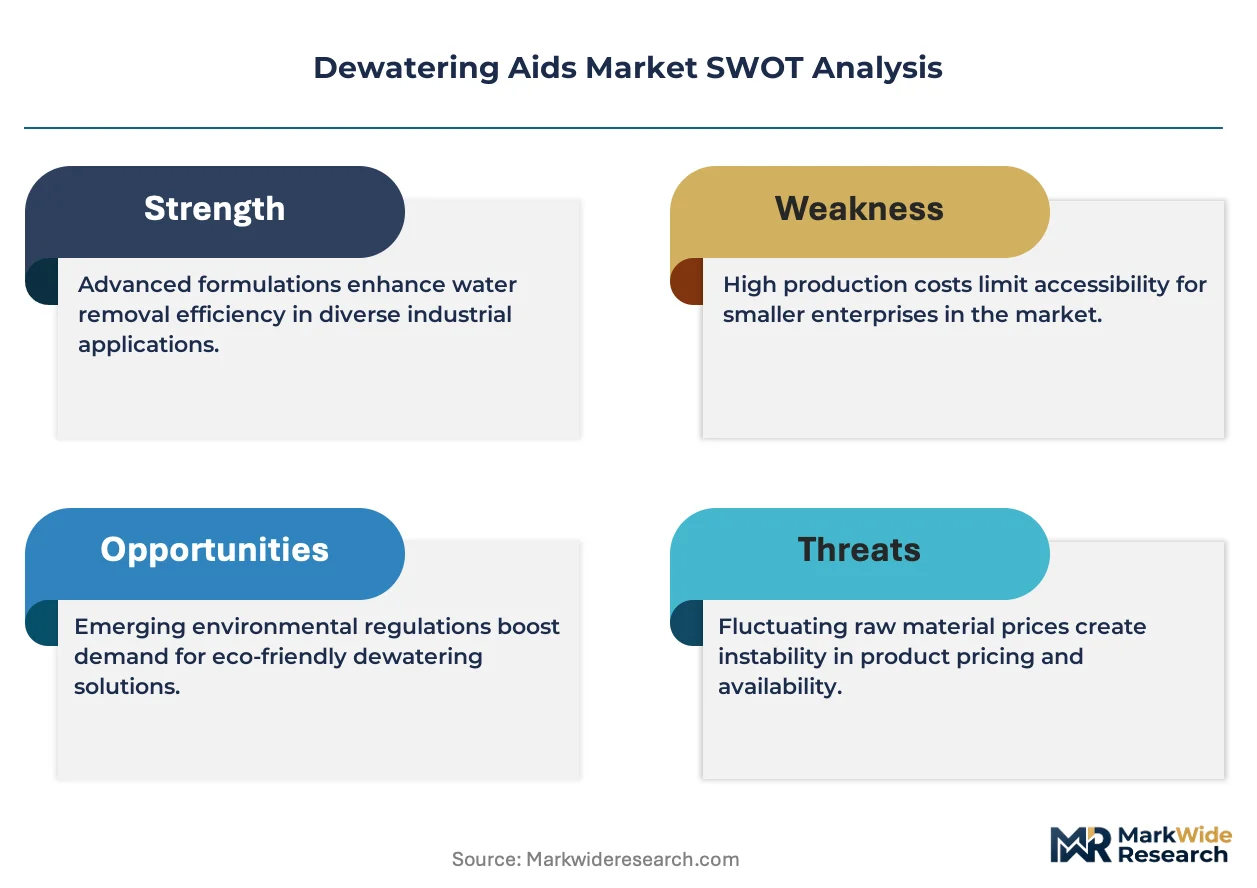
Premium-grade polyacrylamide formulations is bifurcating the competitive landscape between commodity suppliers and specification-driven specialists. BASF SE leverages its integrated monomer-to-polymer pipeline to sustain cost discipline across European industrial accounts. Kemira Oyj anchors Nordic municipal contracts through application-engineered dosing systems. SNF Group dominates global acrylamide manufacturing scale, extending its backward integration into bio-based feedstock trials.
Dewatering aids comprise synthetic and natural chemical additives that reduce moisture content in sludge, tailings, and suspensions through charge neutralization and flocculation, typically achieving 15-40% solids improvement depending on substrate chemistry. Their primary purpose centers on reducing disposal volumes, lowering transport costs, and enabling subsequent thermal processing or landfill compliance. Polymer-type flocculants command the deepest margin pools due to dosage precision requirements in mining applications, while coagulant demand accelerates fastest in municipal wastewater retrofit programs across stressed watershed regions. Application-level segmentation shows wastewater treatment occupying the volume lead, though mining end-use generates superior per-ton pricing through customized high-molecular-weight formulations.
EPA effluent limitation guidelines shape product registration and discharge compliance costs for US suppliers, while REACH registration requirements in Europe filter non-compliant polymer chemistries from cross-border trade. China's MEE standards on sludge moisture content for thermal power co-firing are redirecting formulation R&D toward higher-performance cationic polymers. India's CPCB mandates for sewage treatment plant upgrades are opening specification-driven procurement channels previously dominated by basic inorganic coagulants. Stakeholders must monitor regulatory divergence between jurisdictions with diverging biodegradability thresholds versus those prioritizing pure dewatering efficiency.
Market Dynamics
Polyacrylamide feedstock concentration among three acrylamide manufacturers is compressing margin pools for downstream formulators while simultaneously accelerating bio-based polymer R&D investment cycles across European municipal procurement channels.
Growth Catalysts
- EU Green Deal sludge mandates:Binding moisture-content thresholds for landfill diversion are forcing German and French wastewater utilities toward high-efficiency cationic flocculant systems.
- Mining tailings thickening:Copper and lithium extraction operations in Chile and Australia are retrofitting concentrator circuits with high-molecular-weight anionic polymers to reduce paste disposal volumes.
- China MEE thermal co-firing rules:Stricter sludge moisture specifications for cement kiln and power plant fuel substitution are pulling higher-performance conditioning chemicals into municipal contracts.
Market Restraints
- Acrylamide monomer oligopoly:Three producers control 80% of global supply, exposing formulators to feedstock price volatility and allocation risk during plant turnarounds.
- REACH polymer registration costs:ECHA compliance expenses for novel copolymer chemistries filter small and mid-sized suppliers from cross-border European trade.
- Natural polymer performance ceiling:Starch and chitosan derivatives fail to achieve the solids capture rates required for mining ultrafine tailings, limiting substitution in premium applications.
Strategic Opportunities
- India CPCB sewage treatment mandates:Tier-2 and Tier-3 city infrastructure buildouts are opening specification-driven procurement channels previously served by commodity alum and ferric chloride.
- Cellulosic feedstock polymerization:Enzymatic acrylamide synthesis from agricultural residues is converging with precision fermentation to enable bio-based flocculants at cost parity with petrochemical routes.
- Performance-based chemical service contracts:Mining operators in Western Australia are unbundling polymer supply from dewatering equipment maintenance, creating integrated solution provider roles.
Industry Challenges
- Application engineering talent scarcity:Formulator technical service teams require dual expertise in colloid chemistry and centrifuge/press mechanics, a skill intersection concentrated among senior specialists at equipment OEMs.
- Legacy dosing system incompatibility:Municipal plants running 1990s-era polymer make-down units face retrofit costs that delay conversion to high-efficiency emulsion products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dewatering Aids Market |
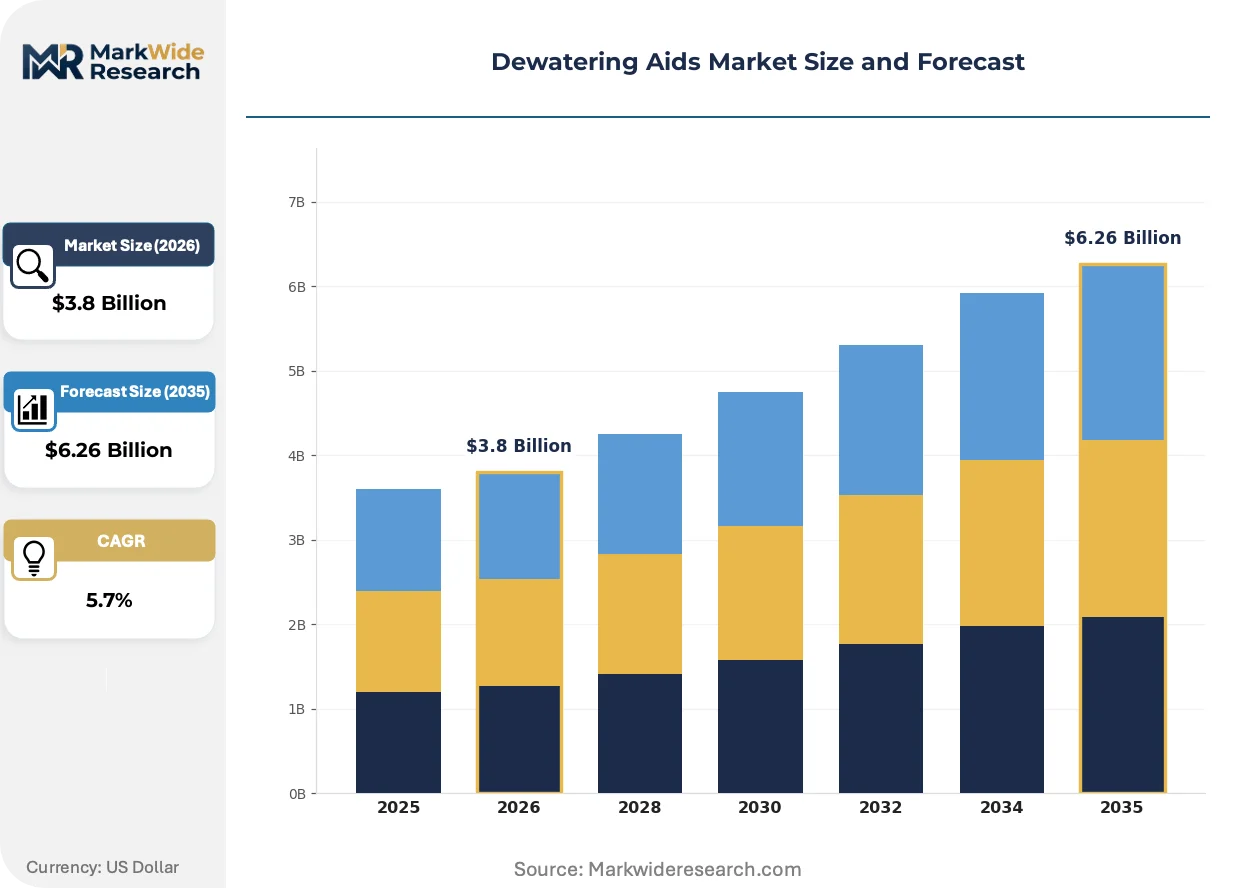
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymers, Coagulants, Flocculants, Surfactants Application: Wastewater Treatment, Mining, Construction, Agriculture End User: Municipal, Industrial, Agricultural, Environmental Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Ecolab Inc., Clariant AG, BASF SE, AkzoNobel N.V., Solvay SA, Kemira Oyj, Solenis LLC, FMC Corporation, SNF Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dewatering Aids Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-based feedstocks while digital dosing control systems rewrite procurement specifications. Equipment-chemical integration is tightening across both municipal and mining verticals.
Structured polymer architectures with precisely tuned charge density and molecular weight distribution are decomposing the traditional trade-off between dewatering efficiency and shear resistance. Mining tailings operators in Western Australia and Chile are adopting these materials for high-solids paste thickening applications. The technology is decomposing the historical segmentation between commodity polyacrylamide grades and application-engineered specialty formulations.
REACH restrictions on microplastic-containing polymers are redirecting R&D toward biodegradable backbone chemistries and natural graft copolymers. ECHA registration deadlines for 2026 are forcing reformulation of legacy emulsion products containing persistent synthetic carriers. Municipal procurement in Germany and France is responding with explicit biodegradability scoring in tender evaluations.
Buyer concentration among integrated mining houses and water utility conglomerates is compressing supplier negotiation leverage and extending payment terms. Specification-setting authority is migrating from plant operators to centralized engineering procurement functions. This pattern is most visible in Anglo-American and Rio Tino procurement frameworks across Chilean and Australian operations.
Dewatering Aids Market Segmentation
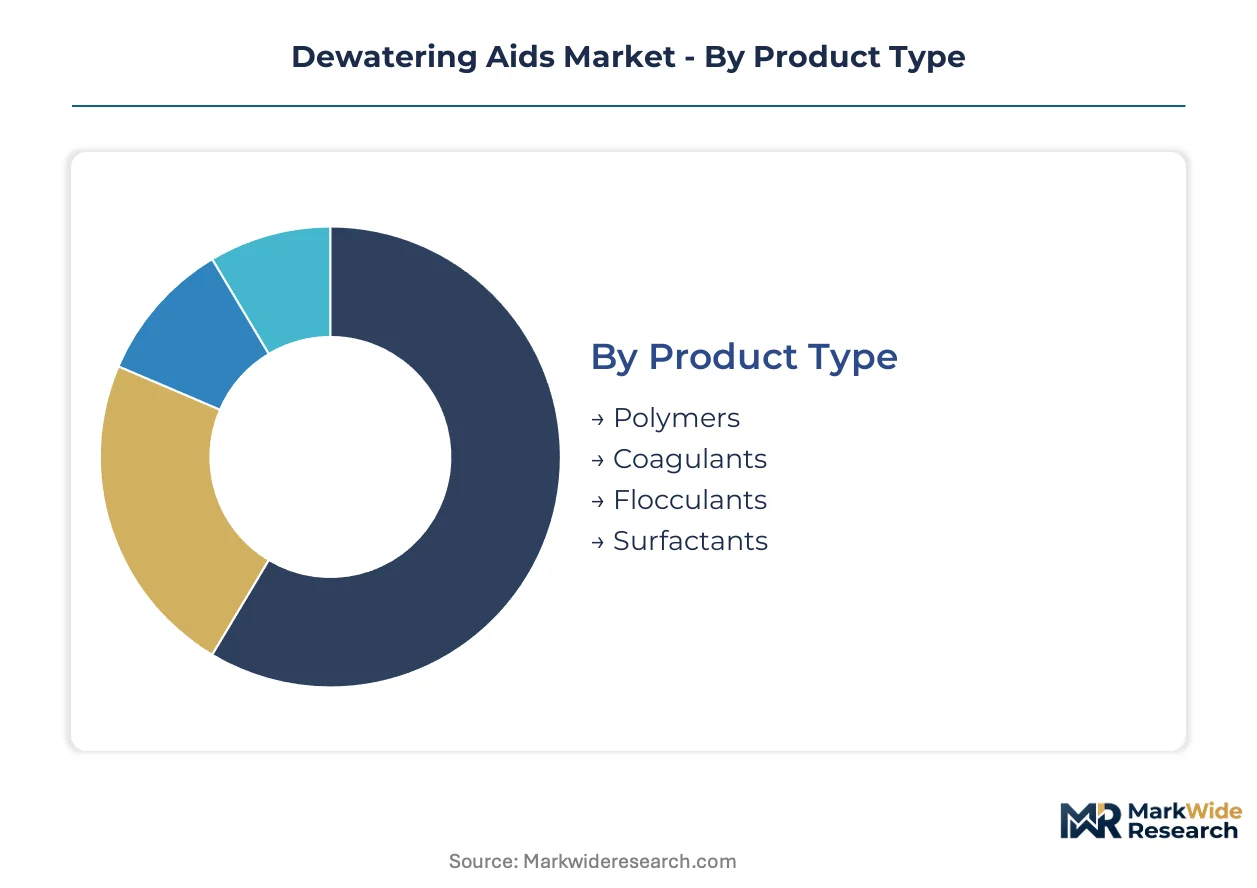
Dewatering aids demand fragments across substrate chemistry, operational scale, and procurement sophistication. Product selection hinges on solids loading, shear environment, and downstream disposal pathways rather than commodity pricing alone.
Product Type:
Margin pools concentrate in polymer formulations where molecular weight precision commands specification premiums over commodity coagulants.
- Polymers:High-molecular-weight polyacrylamide chains engineered for charge density and shear resistance dominate mining tailings thickening. German municipal utilities in the Rhine-Ruhr corridor specify cationic emulsion grades for centrifuge dewatering under EU Green Deal landfill diversion mandates.
- Coagulants:Inorganic salts including alum, ferric chloride, and polyaluminum chloride neutralize surface charge on colloidal particles. India's CPCB sewage treatment plant upgrades are displacing legacy alum systems with enhanced coagulant blends in Tier-2 and Tier-3 cities.
- Flocculants:Synthetic and natural bridging agents aggregate destabilized particles into settleable flocs.
- Surfactants:Surface-active modifiers reduce interfacial tension in oily sludge and industrial emulsions.
Polymers hold installed capacity. Coagulants are rotating up the share rankings.
Application:
Volume leadership sits with wastewater treatment, though mining generates superior per-ton pricing through customized formulation requirements.
- Wastewater Treatment:Municipal and industrial sewage sludge conditioning represents the largest addressable volume. China's MEE thermal co-firing moisture specifications are pulling higher-performance conditioning chemicals into municipal contracts nationwide.
- Mining:Copper and lithium extraction operations in Chile and Australia deploy high-molecular-weight anionic polymers for paste thickening and tailings disposal volume reduction. Rio Tinto and Anglo-American procurement frameworks centralize specification authority.
- Construction:Tunnel boring and foundation dewatering applications use rapid-set flocculant systems.
- Agriculture:Manure and digestate processing employs cost-optimized natural polymer blends.
Wastewater treatment anchors volume throughput. Mining is climbing the fastest on value contribution.
End User:
Procurement sophistication varies sharply between centralized municipal engineering functions and fragmented industrial plant operators.
- Municipal:City and regional water utilities operate under regulatory discharge limits and landfill diversion targets. France and Germany embed explicit biodegradability scoring in tender evaluations under REACH registration pressures.
- Industrial:Manufacturing and processing facilities manage trade effluent and on-site sludge. Mining houses in Western Australia unbundle polymer supply from equipment maintenance, creating integrated service contract opportunities.
- Agricultural:Livestock operations and biogas plants process manure and digestate streams.
- Environmental:Remediation contractors treat contaminated sediments and industrial legacy sites.
Municipal accounts hold contract tenure. Industrial is gaining share fastest on specification intensity.
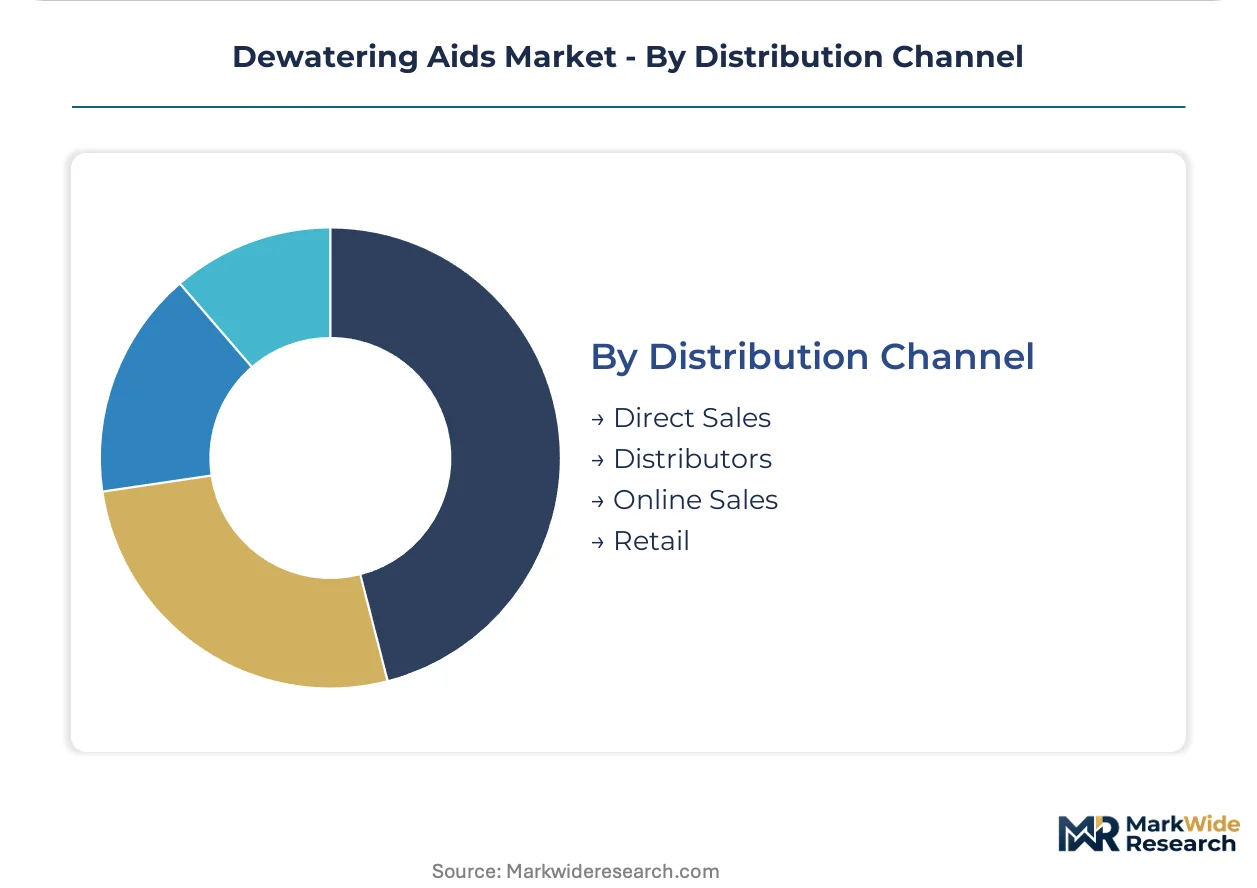
Distribution Channel:
Channel selection tracks buyer scale and technical service requirements rather than pure logistics optimization.
- Direct Sales:Integrated polymer suppliers maintain captive technical service teams for large mining and municipal accounts. BASF SE and Kemira Oyj deploy application engineers for dosing system calibration and performance optimization.
- Distributors:Regional chemical distributors serve mid-sized industrial plants and smaller municipal utilities with inventory buffering and local logistics.
- Online Sales:E-procurement platforms gain traction for standardized commodity grades and repeat purchases.
- Retail:Limited to small-volume agricultural and construction applications.
Direct sales holds relationship density. Distributors are rotating up the share rankings on geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement in Germany and France shows the lowest price elasticity due to regulatory mandates, while Indian Tier-2 utilities exhibit acute sensitivity to per-ton dosing costs. Mining operators in Chile and Australia prioritize performance over unit pricing for ultrafine tailings applications.
Germany
Rhine-Ruhr corridor wastewater utilities are retrofitting centrifuge systems with high-efficiency cationic emulsion grades. The EU Green Deal's binding moisture-content thresholds for landfill diversion are accelerating chemical substitution toward bio-based coagulants. Industrial procurement concentrates in North Rhine-Westphalia's chemical processing belt.
China
MEE standards on sludge moisture content for thermal power co-firing are redirecting formulation R&D toward higher-performance cationic polymers. Municipal contracts in the Yangtze River Delta are pulling advanced conditioning chemicals into nationwide procurement frameworks. Cement kiln operators in Jiangsu province are upgrading dewatering infrastructure.
United States
EPA effluent limitation guidelines are shaping product registration and discharge compliance costs for domestic suppliers. Mining tailings operations in Arizona and Nevada are deploying high-molecular-weight anionic polymers for paste thickening. Municipal utilities in the Great Lakes watershed face combined sewer overflow remediation deadlines.
India
CPCB mandates for sewage treatment plant upgrades are opening specification-driven procurement channels previously dominated by basic inorganic coagulants. Tier-2 and Tier-3 city infrastructure buildouts in Maharashtra and Gujarat are displacing legacy alum systems with enhanced coagulant blends. Delhi-NCR utilities are piloting precision dosing systems.
Australia
Copper and lithium extraction operations in Western Australia are retrofitting concentrator circuits with application-engineered polymer systems. Rio Tinto procurement frameworks centralize specification authority for tailings disposal volume reduction. Queensland coal operations are adopting integrated chemical service contracts unbundling supply from equipment maintenance.
Dewatering Aids Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the dewatering aids sector. Integrated petrochemical majors leverage captive monomer supply to sustain margin discipline, while specialty formulators compete on application engineering and dosing system integration. The market structure bifurcates between specification-driven specialists serving mining accounts and volume suppliers capturing municipal retrofit programs. Dominant competitive moves include backward integration into bio-based feedstock trials and performance-based chemical service contracts.
Within the integrated chemical major tier, BASF SE and Solvay SA exemplify players with captive acrylamide supply chains and European regulatory compliance infrastructure. Kemira Oyj occupies a position among Nordic-based application specialists anchoring municipal contracts through engineered dosing systems. SNF Group represents the scale-driven archetype with concentrated global acrylamide manufacturing capacity.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Clariant AG |
| BASF SE |
| AkzoNobel N.V. |
| Solvay SA |
| Kemira Oyj |
| Solenis LLC |
| FMC Corporation |
| SNF Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between acrylamide producers and downstream formulators lock in both feedstock access and price visibility across the European and Asian procurement corridors. These contracts insulate integrated suppliers from spot volatility while exposing non-integrated formulators to allocation risk during plant turnarounds.
Pricing Analysis
REACH registration dictates the pricing tier structure across European dewatering aids procurement. Three-tier pricing structure across premium, standard, and economy levels separates specification-engineered mining formulations from municipal commodity grades. Cost compression in standard-tier cationic polymers is intensifying because of acrylamide monomer oligopoly concentration. Municipal utilities in India exhibit acute price sensitivity, while mining operators in Chile and Australia prioritize performance metrics over unit dosing costs.
Supply Chain Analysis
Strategic stockpile preferences dominate mining procurement in Western Australia and Chile, where tailings thickening downtime carries severe operational penalties. Acrylamide monomer production concentrates in China, France, and the United States. Formulation chemistry draws from petroleum-derived acrylamide, bio-based cellulose feedstocks, and inorganic coagulant precursors. Single-source vulnerability from the three-producer acrylamide oligopoly presents the dominant structural risk. Distribution runs through direct technical service teams for large accounts and regional chemical distributors for mid-tier municipal utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dewatering aids sector is undergoing high-growth disruption as EU Green Deal sludge mandates force chemical substitution toward bio-based coagulants, compressing legacy formulation margins while opening premium positioning for compliant suppliers.
For Market Incumbents: Consolidate backward integration into bio-based feedstock trials to defend against REACH-driven substitution threats. Lock in municipal contract renewals in Germany and France through bundled dosing system upgrades, neutralizing commodity price pressure from Asian competitors.
For New Entrants and Emerging Players: Application engineering talent scarcity in dual-expertise colloid chemistry and centrifuge mechanics creates immediate service-layer white space. Target Tier-2 and Tier-3 Indian municipal utilities with precision dosing system pilots, displacing legacy alum through performance-based contracting rather than price competition.
For Investors and Strategic Acquirers: Capital is best deployed toward application-specialist formulators with captive technical service capabilities and proven mining account relationships. Long-term viability over the projection horizon hinges on regulatory compliance infrastructure and bio-based R&D pipelines. Watch for ECHA registration deadline compliance as the signal indicating which suppliers will retain European market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | REACH registration deadlines in Europe are forcing reformulation of legacy emulsion products toward biodegradable backbone chemistries. |
| Performance-Based Chemical Service Contracts | Mining operators in Western Australia are unbundling polymer supply from equipment maintenance, creating integrated solution provider roles. |
| Precision Dosing System Integration | Municipal procurement in Germany and France embeds explicit biodegradability scoring in tender evaluations alongside technical performance metrics. |
| Capacity Expansion in Acrylamide Monomer | Feedstock concentration among three global producers exposes formulators to allocation risk during plant turnarounds and demand surges. |
| Joint Venture with Equipment OEMs | Retrofit costs for 1990s-era polymer make-down units delay conversion to high-efficiency emulsion products without bundled financing solutions. |
Methodological Framework
A standing panel of wastewater treatment plant engineers, mining tailings operators, chemical procurement managers, and polymer R&D directors provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from customs trade data, ECHA registration databases, SEC filings of listed chemical majors, and municipal tender documentation. Bottom-up volume modeling across product grades and applications triangulated against top-down market sizing from trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled segmentation dimensions including polymer chemistry type, end-use application, procurement channel, and regional regulatory cluster. CAGRs were derived from regression analysis of historical consumption patterns and projected capacity additions. Industry-specific forecast inputs incorporated MEE sludge moisture standards, EU Green Deal implementation timelines, and CPCB sewage treatment mandates.
Forecasts assume regulatory continuity in REACH, EPA effluent guidelines, and China's MEE standards; material policy shifts would require re-modeling. Specific risks include acrylamide monomer supply disruption, accelerated biodegradability thresholds, and mining capital expenditure cycles. Revision becomes warranted when bio-based polymer cost parity thresholds cross commercial viability benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Pulp and Paper Enzymes Market