
 Well Stimulation Materials Sales Market | 2026-2036
Well Stimulation Materials Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Well Stimulation Materials Sales Market Insights
Premium-mesh proppant specifications is bifurcating the competitive landscape between high-purity northern white sand suppliers and regional brown sand producers. U.S. Silica anchors its position through captive mine access in Wisconsin and Texas. CARBO Ceramics differentiates via resin-coated and ceramic proppant technologies for high-pressure formations. Badger Mining Corporation competes on logistics density and unit-train delivery networks serving the Permian and Bakken.
Well stimulation materials encompass chemically engineered fluids and solid particulates injected into hydrocarbon-bearing formations to enhance permeability and flow conductivity, with proppant mesh size, acid concentration, and gel viscosity serving as critical performance parameters that determine fracture geometry and sustained production rates. Hydraulic fracturing applications dominate material consumption volumes due to multi-stage completion designs in shale plays, while acidizing represents a higher-margin segment tied to carbonate reservoir remediation and wellbore cleanup campaigns. Proppants command the largest share of material-type value pools, though specialty additives for friction reduction and scale inhibition are expanding fastest as operators target extended-reach laterals.
EPA underground injection control rules and OSHA silica exposure limits are elevating product testing burdens and respiratory protection costs across the supply chain, with state-level oil and gas commissions in Texas and North Dakota layering additional chemical disclosure mandates atop federal baselines. The Department of Transportation enforces specialized bulk transport classifications for acid and gel formulations that constrain carrier selection and routing flexibility. Stakeholders must monitor evolving fracturing fluid disclosure thresholds and proppant respirable silica standards to anticipate compliance-driven procurement shifts.
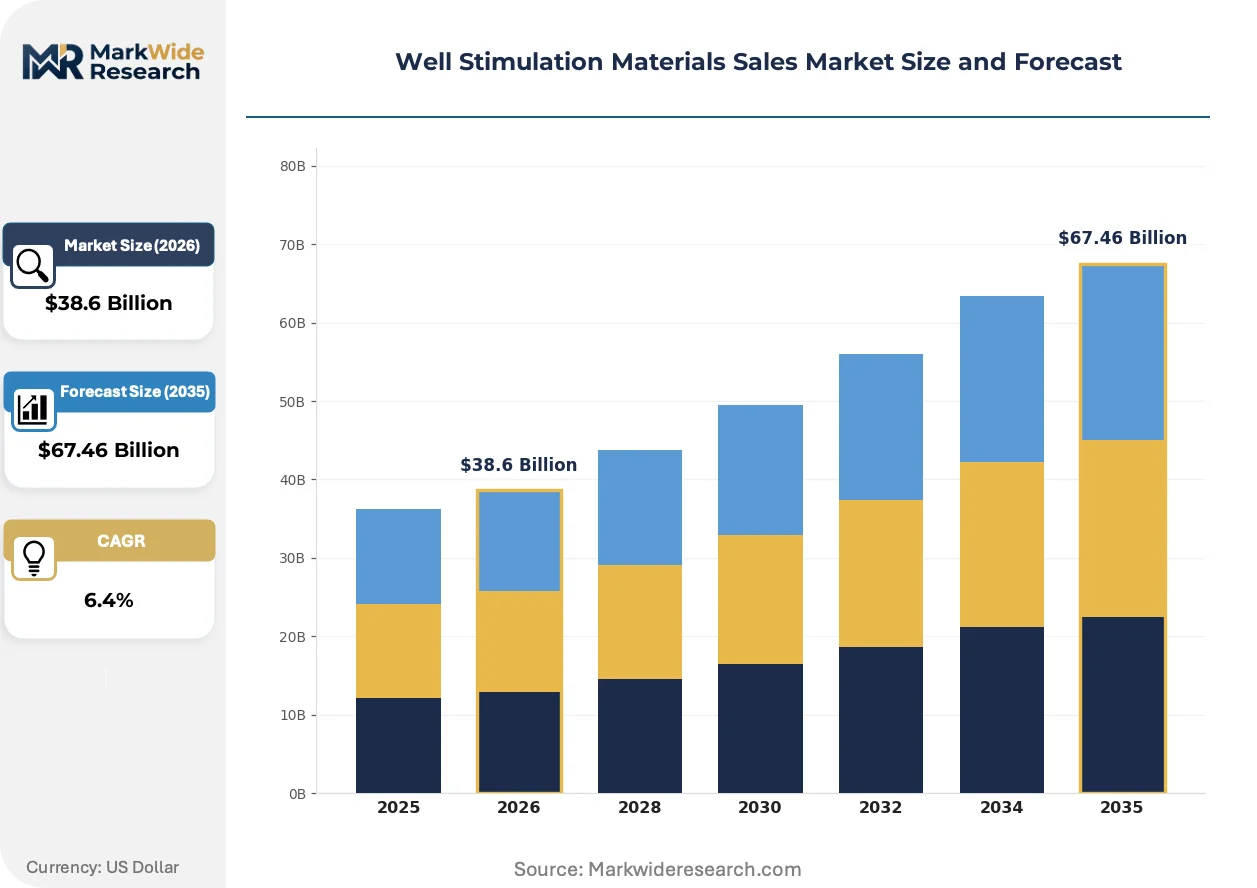
Market Dynamics
Longer lateral well designs in unconventional basins are concentrating proppant demand among fewer operators with scaled completion programs, forcing suppliers to reconfigure logistics networks around unit-train rail terminals and last-mile storage depots.
Growth Catalysts
- Extended-reach lateral technology:Multi-mile horizontal sections in the Permian and Bakken formations multiply proppant intensity per well, lifting aggregate material consumption even as rig counts fluctuate.
- EPA UIC chemical disclosure mandates:Tighter reporting requirements for fracturing fluid constituents are accelerating demand for pre-certified, pre-tested additive packages that streamline operator compliance workflows.
- Resin-coated proppant thermal tolerance:Deep, high-pressure formations in the Delaware Basin require engineered proppants that prevent crushing and embedment, sustaining conductivity at reservoir temperatures exceeding 350°F.
Market Restraints
- Northern white sand transport costs:Rail and trucking distances from Wisconsin mines to Permian demand centers impose fuel surcharge volatility that erodes delivered margins for high-purity proppant grades.
- OSHA silica exposure enforcement:Respirable crystalline silica standards elevate personal protective equipment expenditures and on-site industrial hygiene staffing requirements across transloading and wellsite operations.
- Regional brown sand quality variability:Inconsistent crush resistance and acid solubility in locally sourced Texas and Oklahoma sands limit their substitution for premium mesh specifications in high-stress completions.
Strategic Opportunities
- Alberta Montney and Duvernay development:Canadian shale plays remain underpenetrated relative to U.S. analogs, with water handling infrastructure constraints creating openings for low-water fracturing fluid technologies.
- Last-mile proppant storage and blending:Distributed silo networks near active drilling pads reduce trucking cycles and enable just-in-time mesh blending, compressing delivered costs for operators with dense development programs.
- Carbon capture utilization in proppant manufacturing:Resin coating processes present integration points for captured CO2 in binder chemistry, aligning with emerging low-carbon procurement criteria from integrated operators.
Industry Challenges
- Specialized petroleum engineering talent:Fracture design optimization for variable geology requires experienced completion engineers, with labor scarcity concentrated in the Permian and Williston basins.
- API/ISO proppant certification timelines:Third-party testing for crush resistance, roundness, and turbidity extends 8-12 weeks, delaying new mine qualification and constraining supply flexibility.
- Real-time inventory coordination:Synchronizing railcar arrivals, transloading capacity, and pad consumption rates demands predictive logistics platforms that few regional suppliers have deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Stimulation Materials Sales Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Acids, Proppants, Gels, Additives Application: Hydraulic Fracturing, Acidizing, Cementing, Injection End User: Oil Operators, Gas Producers, Service Providers, Mining Companies Distribution Channel: Direct Sales, Distributors, Online Sales, Partnerships |
| Companies Covered | Chevron Phillips Chemical Company, Linde Group, FMC Corporation, Solvay, Akzo Nobel, Badger Mining Corporation, U.S. Silica, CARBO Ceramics, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Stimulation Materials Sales Market Trends and Innovations
Material science advances and regulatory transparency mandates are bifurcating the supply base between commodity volume players and technology-integrated service providers.
Ultra-lightweight ceramic proppant formulations are fragmenting the traditional density-performance tradeoff in deep-gas completions. E&P operators in the Haynesville and Appalachia basins are adopting 2.50-2.65 specific gravity ceramics to reduce fluid viscosity requirements and pumping horsepower. This density reduction is fragmenting equipment specification standards across pressure pumping fleets, forcing service companies to maintain dual inventory for conventional and lightweight programs.
EPA's proposed expansion of UIC Class II well permitting to cover produced water recycling pits is tightening containment and monitoring obligations for stimulation fluid sourcing. The rulemaking elevates capital requirements for centralized water treatment facilities and accelerates operator preference for closed-loop chemical systems with reduced freshwater dependency. Texas Railroad Commission and North Dakota Industrial Commission are layering additional groundwater protection stipulations that exceed federal baselines, fragmenting compliance protocols across state lines.
Pad-level procurement consolidation is compressing supplier rosters as integrated operators centralize material purchasing through dedicated supply chain functions. Large independents in the Midland Basin are displacing spot-market transactions with 12-18 month volume commitments tied to storage-and-delivery service bundles. This behavioral shift is most visible among Permian-focused E&Ps with 20+ well annual programs, where logistics reliability outweighs unit price in vendor selection criteria.
Well Stimulation Materials Sales Market Segmentation
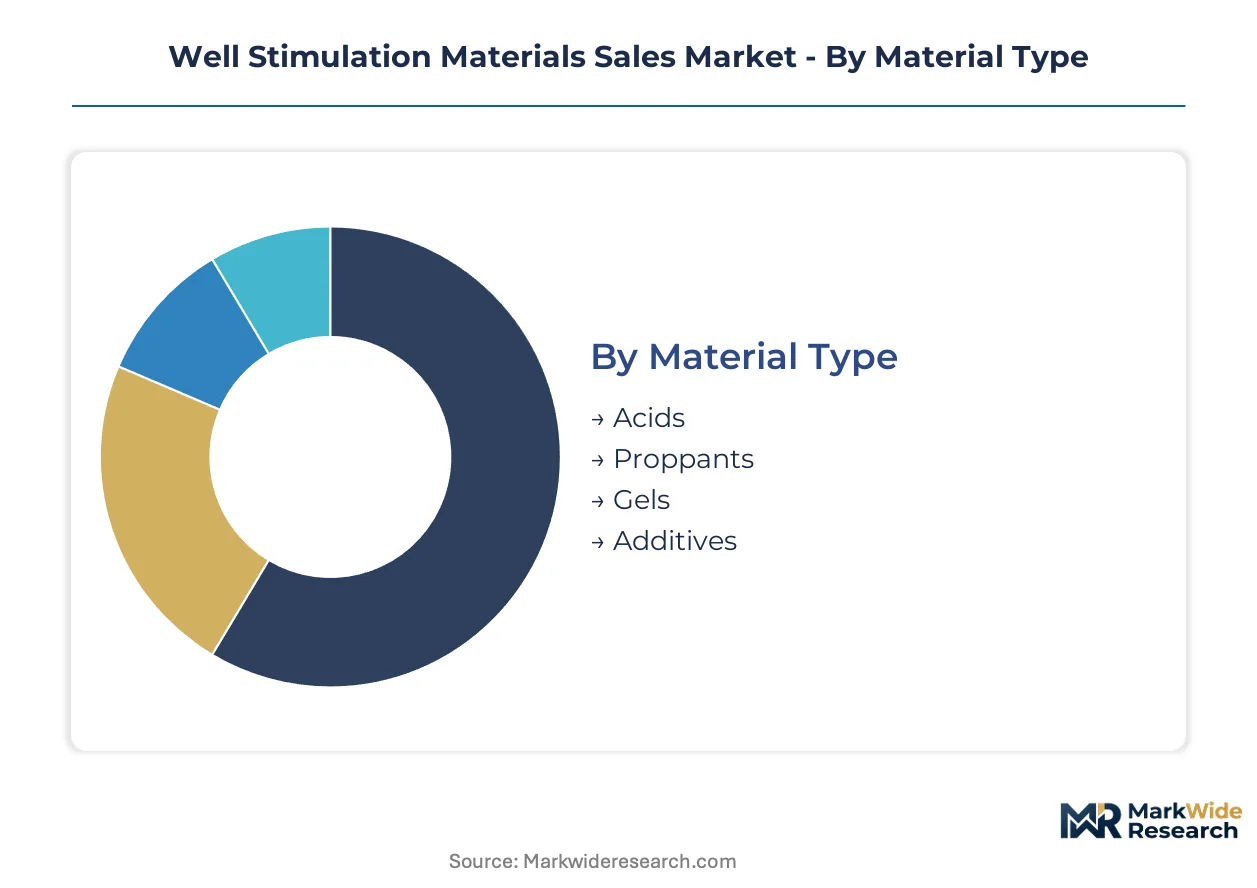
Segmentation in well stimulation materials reflects divergent supply chain economics across material types and the operational specialization required by application method. Procurement patterns vary sharply between direct operator relationships and third-party service company intermediation.
Material Type:
Domestic production dominates proppant and acid supply, while specialty additives draw significant import dependency from European chemical manufacturers.
- Acids:Hydrochloric and hydrofluoric formulations dissolve carbonate formations and remove near-wellbore damage. Demand concentrates in the Permian Basin and Alberta, where carbonate stringers in the Delaware and Montney formations require pre-fracture acid spearheads to establish injectivity.
- Proppants:Sized particulates of sand, resin-coated sand, or ceramic maintain fracture aperture under closure stress. Northern white sand from Wisconsin mines supplies premium mesh specifications for high-pressure completions, while regional brown sand from Texas and Oklahoma serves cost-sensitive Permian operators with moderate stress regimes.
- Gels:Crosslinked polymer systems suspend proppant during pumping operations. Guar and derivatized cellulose formulations face pricing volatility tied to Indian agricultural harvests.
- Additives:Friction reducers, biocides, scale inhibitors, and clay stabilizers customize base fluid performance. Low-dose, high-margin chemistry expands fastest as laterals lengthen and stage counts multiply.
Proppants hold the largest share; momentum sits with Additives.
Application:
Volume intensity separates high-material-consumption fracturing from precision acidizing campaigns with lower throughput but superior margins.
- Hydraulic Fracturing:Multi-stage horizontal completions in shale formations consume 90% of proppant volumes and drive additive demand through slickwater and hybrid fluid systems. Permian and Bakken operators deploy 50-80 stages per lateral, multiplying material intensity per wellbore.
- Acidizing:Matrix and fracture acid treatments restore permeability in carbonate reservoirs without mechanical proppant placement. Gulf of Mexico shelf operations and Middle East carbonate developments sustain demand for high-concentration HCl and retarded acid systems.
- Cementing:Primary and remedial cement operations require fluid-loss additives and spacer systems distinct from fracturing chemistry. Deepwater Gulf of Mexico and North Sea projects specify synthetic-based spacer fluids with narrow temperature stability windows.
- Injection:Water disposal and enhanced recovery injections utilize friction reducers and scale inhibitors to maintain wellbore integrity. Produced water recycling mandates in Texas and North Dakota accelerate chemical demand for filtration and biocide treatment.
Hydraulic Fracturing anchors volume; Acidizing commands premium pricing power.
End User:
Procurement scale distinguishes integrated operators with direct supplier negotiations from fragmented service company intermediation.
- Oil Operators:Independent E&Ps in the Permian and Bakken with 20-plus well annual programs centralize purchasing through dedicated supply chain functions. These operators negotiate 12-18 month volume commitments with embedded storage and logistics services.
- Gas Producers:Appalachia and Haynesville dry gas developers prioritize cost control amid commodity price compression. Proppant intensity per well runs lower than oil-weighted Permian completions, favoring regional brown sand over premium northern white specifications.
- Service Providers:Pressure pumping companies procure materials on behalf of operator clients, capturing margin through bulk purchasing and inventory management. Halliburton, Schlumberger, and Liberty Oilfield Services maintain captive proppant terminals and chemical blending facilities.
- Mining Companies:Non-petroleum mineral extraction operations utilize similar acid and explosive technologies for leaching and fragmentation. Copper heap-leach operations in Arizona and Nevada consume sulfuric acid from shared supply infrastructure.
Oil Operators drive specification standards; Service Providers capture procurement intermediation value.
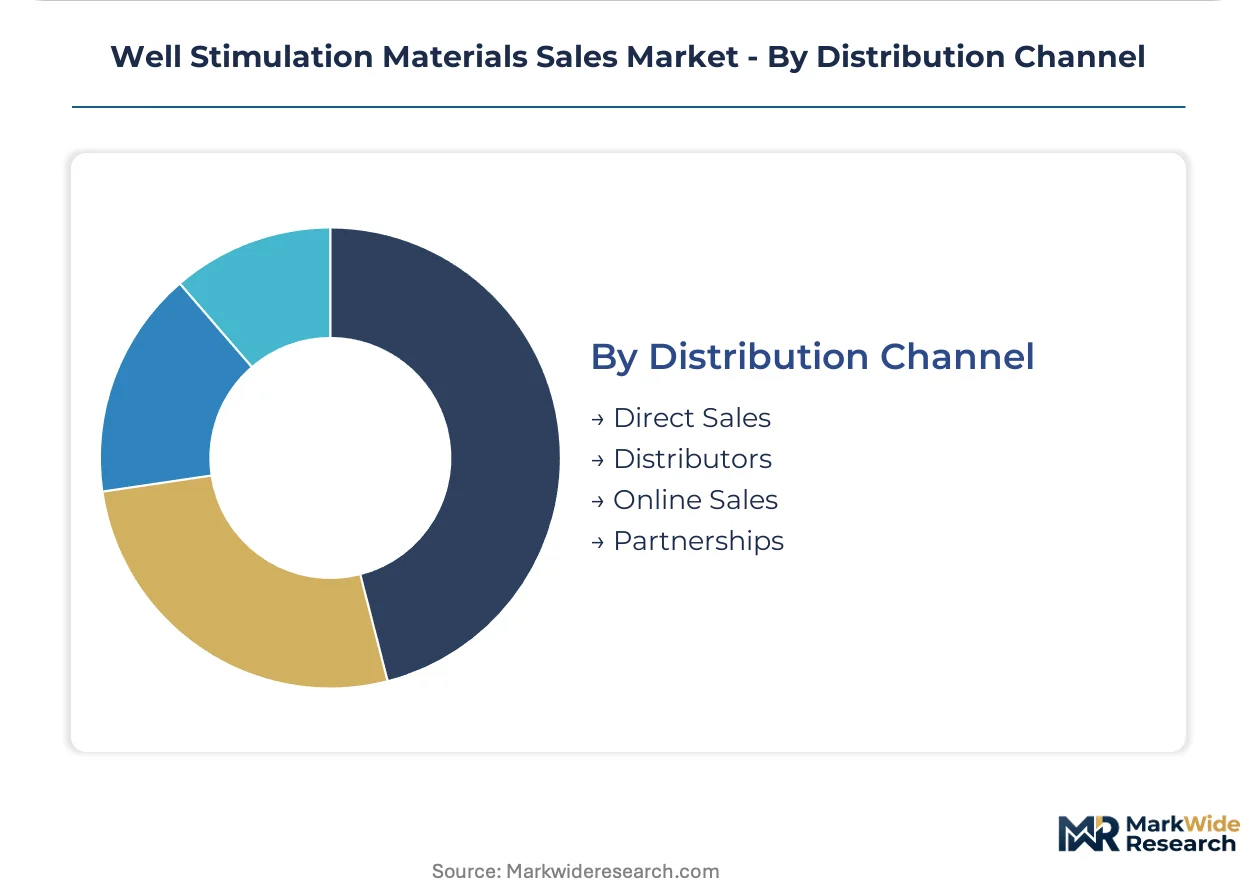
Distribution Channel:
Logistics reliability outweighs unit price in channel selection for high-volume, time-sensitive completion programs.
- Direct Sales:Proppant suppliers U.S. Silica and Badger Mining negotiate direct rail contracts and unit-train deliveries to operator-designated transload facilities. This channel eliminates distributor margin but requires minimum volume thresholds and dedicated storage infrastructure.
- Distributors:Regional chemical and proppant distributors aggregate demand from smaller operators and service companies. Texas and Oklahoma distribution networks maintain local inventory for spot-market purchases and emergency replenishment.
- Online Sales:Digital procurement platforms for standard additives and replacement parts remain nascent in stimulation materials. E-commerce penetration concentrates in consumables and PPE rather than bulk proppant or acid.
- Partnerships:Strategic alliances between chemical suppliers and pressure pumpers embed materials within integrated service contracts. These arrangements reduce procurement friction but limit operator flexibility in supplier selection.
Direct Sales commands the largest volume commitment value; Partnerships are climbing the fastest as integrated service models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in well stimulation materials tilt toward regional self-sufficiency, with the United States running surpluses in proppant and acid while European chemical imports satisfy specialty additive demand. Domestic production clusters near consumption centers to minimize rail and trucking costs.
United States
Permian Basin operators in West Texas and southeastern New Mexico consume the majority of domestic proppant volumes, with Delaware Basin deep-gas completions demanding premium northern white sand. EPA UIC Class II permitting expansions for produced water recycling are tightening containment standards for stimulation fluid sourcing. Midland-Odessa logistics hubs anchor unit-train rail terminals and last-mile silo networks serving multi-pad development programs.
Canada
Alberta's Montney and Duvernay shale plays drive proppant demand as operators extend lateral lengths to compete with U.S. economics. Alberta Energy Regulator groundwater protection stipulations exceed federal baselines, mandating enhanced chemical disclosure for fracturing operations. Grande Prairie and Fort St. John service corridors concentrate pressure pumping capacity and proppant transloading infrastructure.
Saudi Arabia
Carbonate reservoir acidizing sustains demand for high-concentration HCl and retarded acid systems in Ghawar and Khurais fields. Saudi Aramco's in-house drilling and stimulation divisions centralize procurement through long-term chemical supply agreements. Eastern Province industrial cities anchor acid manufacturing and blending facilities serving onshore and offshore development.
China
Sichuan Basin shale gas development in the Fuling and Weirong blocks multiplies proppant intensity per well as CNPC and Sinopec deploy multi-stage horizontal completions. Ministry of Ecology and Environment (MEE) water discharge regulations are elevating treatment costs for flowback fluid recycling. Chongqing logistics corridors concentrate domestic ceramic proppant manufacturing and rail distribution networks.
Brazil
Pre-salt carbonate formations in the Santos Basin require acid spearheads to establish injectivity before proppant placement. ANP local content mandates pressure service companies to source stimulation chemicals from domestic blenders where feasible. Macaé service hub anchors offshore supply vessels and acid storage terminals serving floating production units.
Well Stimulation Materials Sales Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and specialized proppant miners serving distinct tiers of the value chain. The supply base stratifies between volume-driven commodity producers and technology-integrated service providers. Two dominant archetypes emerge: captive mine operators with logistics density, and diversified chemical formulators with friction-reducer and specialty additive portfolios. Competitive moves center on rail terminal acquisitions for last-mile positioning and resin-coating technology licensing for high-temperature applications.
Among North American proppant specialists, U.S. Silica and Badger Mining Corporation exemplify the captive-mine archetype with Wisconsin and Texas mineral reserves. CARBO Ceramics occupies the engineered-materials tier, representing ceramic and resin-coated proppant capabilities for high-stress completions. BASF anchors the chemical formulation segment, exemplifying diversified supply of friction reducers, biocides, and crosslinked gel systems through integrated production networks.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company |
| Linde Group |
| FMC Corporation |
| Solvay |
| Akzo Nobel |
| Badger Mining Corporation |
| U.S. Silica |
| CARBO Ceramics |
| BASF |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of railcar transit time from Wisconsin mines to Permian Basin transload terminals concentrates pricing power among suppliers with captive unit-train capacity, while inventory carrying costs for northern white sand compress margins for operators lacking distributed silo networks. This lead-time band shapes procurement behavior toward long-term offtake contracts that embed storage services and buffer price volatility from fuel surcharge fluctuations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium northern white sand, regional brown sand, and resin-coated ceramic specifications. Price differentiation rests on crush resistance certification tiers and logistics density to wellsite, with Permian operators showing highest sensitivity to delivered cost per ton while Delaware Basin deep-gas developers prioritize thermal tolerance over unit economics. Cost compression in regional brown sand intensifies as quality variability limits substitution rates for high-stress completions, sustaining premium tiers despite narrowing absolute spreads.
Supply Chain Analysis
Just-in-time inventory preferences dominate among Permian operators with dense multi-pad programs, while strategic stockpiling persists for northern white sand ahead of winter rail constraints. Supply concentrates in the United States, Canada, and China, with ceramic proppant manufacturing drawing from bauxite and kaolin feedstocks. Single-source vulnerability runs through Union Pacific and BNSF rail corridors serving West Texas, where transloading capacity bottlenecks amplify disruption risk. Distribution runs through unit-train terminals to last-mile silo depots, with chemical additives flowing via regional distributor networks for spot-market flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in well stimulation materials outpace hardware growth, with closed-loop water recycling and predictive logistics platforms expanding faster than commodity proppant volumes as operators prioritize operational uptime over unit procurement savings.
For Market Incumbents: Compound logistics density advantages through rail terminal acquisitions in the Midland-Odessa corridor and backward integration into resin-coating technology to defend against ceramic proppant substitution in high-temperature formations. EPA chemical disclosure mandates threaten spot-market suppliers lacking pre-certified additive packages, making certification investment the critical lever for retention of integrated operator accounts. For New Entrants and Emerging Players: Last-mile silo network gaps in the Alberta Montney and Duvernay formations offer white-space entry where water handling infrastructure constraints favor low-water fracturing fluid technologies. Target Canadian shale plays with bundled storage-and-delivery service models, leveraging underdeveloped pressure pumping density relative to U.S. analogs to establish anchor contracts before incumbent logistics expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded proppant or stimulation chemical assets outside core agricultural or industrial portfolios. Five-to-ten year viability hinges on rail terminal real estate and EPA pre-certification status rather than mine reserves alone. Watch for UIC Class II permitting delays that would revalue water-independent chemical systems.| Strategic Initiative | Industry Significance |
|---|---|
| Unit-Train Terminal Acquisition | Captive rail capacity locks in Permian logistics density against BNSF/UP bottleneck exposure. |
| Resin-Coating Technology Licensing | Thermal tolerance above 350°F secures Delaware Basin deep-gas share from ceramic substitution. |
| Low-Water Fracturing Fluid Development | Alberta water constraints and Texas recycling mandates accelerate preference for reduced-fluid systems. |
| Predictive Logistics Platform Deployment | Real-time railcar-to-pad synchronization compresses working capital for 20-plus well annual programs. |
| EPA Pre-Certified Additive Packaging | Streamlined disclosure workflows capture procurement consolidation among integrated Permian operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EPA UIC permit databases, and railroad waybill data. Completion engineers at Permian and Bakken operators, procurement directors at pressure pumping service companies, and logistics managers at proppant transload facilities provided operational validation. Bottom-up well count and proppant intensity estimates triangulate against top-down trade flow analysis from U.S. Geological Survey mineral commodity summaries and Association of American Railroads carload statistics.
Segmentation dimensions modeled include material type, application method, end-user procurement scale, and distribution channel structure across the analysis window. CAGRs derive from stage-count trajectories in horizontal completions, lateral length expansion curves, and additive intensity per foot. Forecast inputs incorporate rig efficiency gains, tier-one acreage depletion patterns, and chemical disclosure compliance cost pass-through assumptions.
Forecasts assume regulatory continuity in EPA UIC and OSHA silica exposure regimes; material policy shifts would require re-modeling. Specific risks include Union Pacific service disruptions, Wisconsin mine permitting moratoria, and Canadian groundwater protection stipulations exceeding federal baselines. Revision becomes warranted when railcar fleet utilization or transloading queue depth crosses thresholds indicating systemic logistics constraint.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Global Silicone Fluid Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
High Pressure Roll Compactor Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Hydrogen Sulphide Market