
 Malaysia Oil and Gas Market | 2026-2036
Malaysia Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Oil and Gas Market Foresight
Malaysia's offshore Sarawak Basin is reshaping upstream economics through deepwater tiebacks and enhanced oil recovery campaigns. Petronas anchors domestic production through its operated Baram Delta and Samarang fields, while Shell Plc leverages subsea infrastructure at the Malikai development. Exxon Mobil Corp competes in the same basin with its interests in the Tapis and Guntong complexes. Hibiscus Petroleum Bhd differentiates through its focus on late-life asset rejuvenation and marginal field acquisitions.
Malaysia oil and gas encompasses the exploration, extraction, processing, and distribution of hydrocarbon resources including crude oil with API gravities ranging from light sweet to heavy sour grades, natural gas with methane content typically exceeding 85 percent, and associated refined products. The sector serves power generation baseload, manufacturing feedstock, and transport fuel applications across Southeast Asian trade corridors. Natural gas dominates the product mix as the cleanest-burning fossil fuel in Malaysia's energy transition pathway, while exploration technology commands disproportionate capital intensity due to ultra-deepwater drilling requirements exceeding 1,500 meters. The chemical industry end-user segment absorbs growing NGL volumes for olefin production, though direct sales channels retain margin advantages through long-term offtake contracts with Petronas and Shell.
Petroleum Development Act requirements and PETRONAS Technical Standards mandate minimum local content thresholds and safety specifications for all offshore installations. The Department of Occupational Safety and Health enforces process safety management protocols under the Occupational Safety and Health Act 1994, while the Energy Commission regulates downstream gas distribution tariffs. Stakeholders must monitor regulatory shifts around carbon pricing mechanisms and methane emissions caps that will reshape project sanctioning timelines and capital allocation priorities.
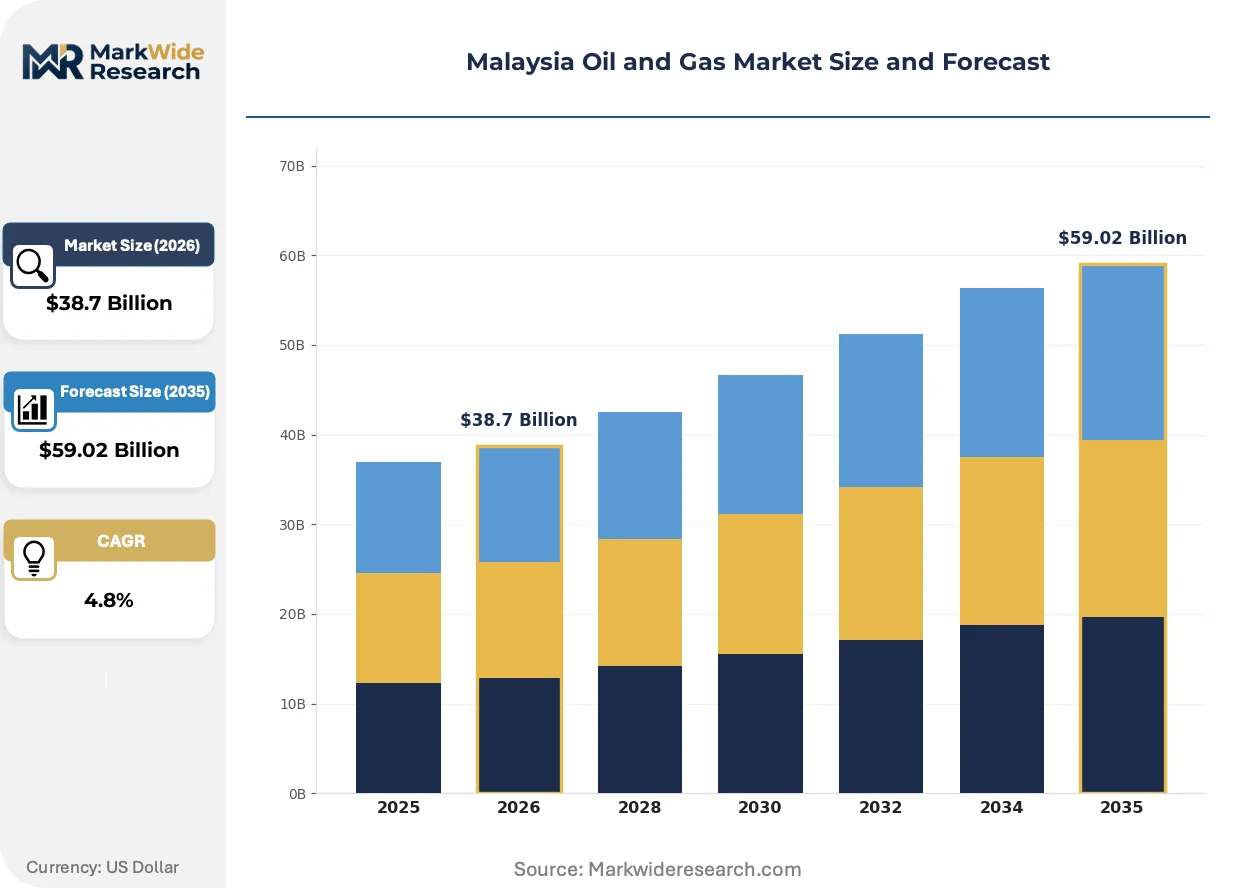
Market Dynamics
Deepwater tieback economics and PETRONAS Technical Standards compliance requirements are compressing project sanctioning timelines and reshaping capital allocation across Malaysia's offshore basins. Operators now face simultaneous pressure to extend field life while meeting escalating local content thresholds and methane intensity benchmarks.
Growth Catalysts
- Power generation fuel switching:Malaysia's coal-to-gas transition in baseload electricity is absorbing rising natural gas volumes from the Bintulu LNG complex and offshore Sarawak production.
- Enhanced oil recovery deployment:Mature field operators are deploying chemical EOR and gas injection campaigns to sustain output from the Baram Delta and Samarang complexes.
- Pengerang Integrated Complex expansion:Downstream refining and petrochemical integration at the Johor hub is creating concentrated demand for domestic crude and condensate feedstocks.
Market Restraints
- Ultra-deepwater drilling cost escalation:Well construction exceeding 1,500 meters water depth requires specialized rig fleets with limited Asia-Pacific availability, inflating development breakevens.
- Local content compliance burden:Petroleum Development Act mandates and PETRONAS Technical Standards impose procurement rigidities that extend engineering procurement construction timelines.
- Renewable substitution pressure:Grid-scale solar and offshore wind auctions under the Malaysia Renewable Energy Roadmap are capturing incremental power sector investment flows.
Strategic Opportunities
- Sarawak marginal field aggregation:Bundling subscale discoveries around existing hub infrastructure offers lower-carbon development pathways than greenfield standalone projects.
- Carbon capture utilization and storage integration:Depleted offshore reservoirs present sequestration potential aligned with Petronas Net Zero Carbon Emissions 2050 commitments.
- Digital twin adoption:Real-time production optimization and predictive maintenance platforms are reducing unplanned shutdowns across aging Peninsular Malaysia assets.
Industry Challenges
- Subsea engineering talent scarcity:Deepwater project ramp-ups are competing for finite commissioning and integrity management specialists across Southeast Asian contractor markets.
- Legacy platform decommissioning liability:Aging fixed installations in the Baram Delta require costly removal campaigns with uncertain cost recovery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Oil and Gas Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, NGL, Refined Products Technology: Exploration, Drilling, Production, Refining End User: Power Generation, Manufacturing, Transport, Chemical Industry Distribution Channel: Direct Sales, Wholesalers, Retailers, Brokers |
| Companies Covered | Petroliam Nasional Berhad (Petronas), Shell Plc, Exxon Mobil Corp, Chevron, Sapura Energy Bhd, Hibiscus Petroleum Bhd, BP, Carimin Petroleum, Perintis Kembara Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Oil and Gas Market Shifts & Advancements
Malaysia's offshore sector is converging on autonomous subsea operations and emissions-intensity benchmarking as operators seek to sustain production from maturing basins. Three interconnected developments are compressing traditional field development economics.
Subsea processing technology is hybridizing conventional topside infrastructure with seabed separation and boosting systems. Petronas and international partners are deploying subsea multiphase pumps and compact separation modules at Malikai and Gumusut-Kakap to defer platform upgrades. This compression of surface facility requirements is enabling tieback developments previously classified as subcommercial.
The Occupational Safety and Health Act 1994 and emergent carbon pricing consultations are tightening process safety and emissions disclosure obligations. The Department of Occupational Safety and Health is enforcing stricter process safety management protocols while the Energy Commission evaluates methane performance standards. Upstream operators are responding with continuous monitoring deployments and flare reduction investments concentrated in Sarawak's offshore production corridors.
Long-term offtake contracting patterns are fragmenting as power sector buyers seek shorter-tenor agreements with price reopeners. Malaysia's single-buyer gas utility and independent power producers are negotiating more flexible supply terms to accommodate renewable intermittency. This contractual evolution is most visible in Peninsular Malaysia where gas-fired generation competes directly with solar and battery storage combinations.
Malaysia Oil and Gas Market Segmentation
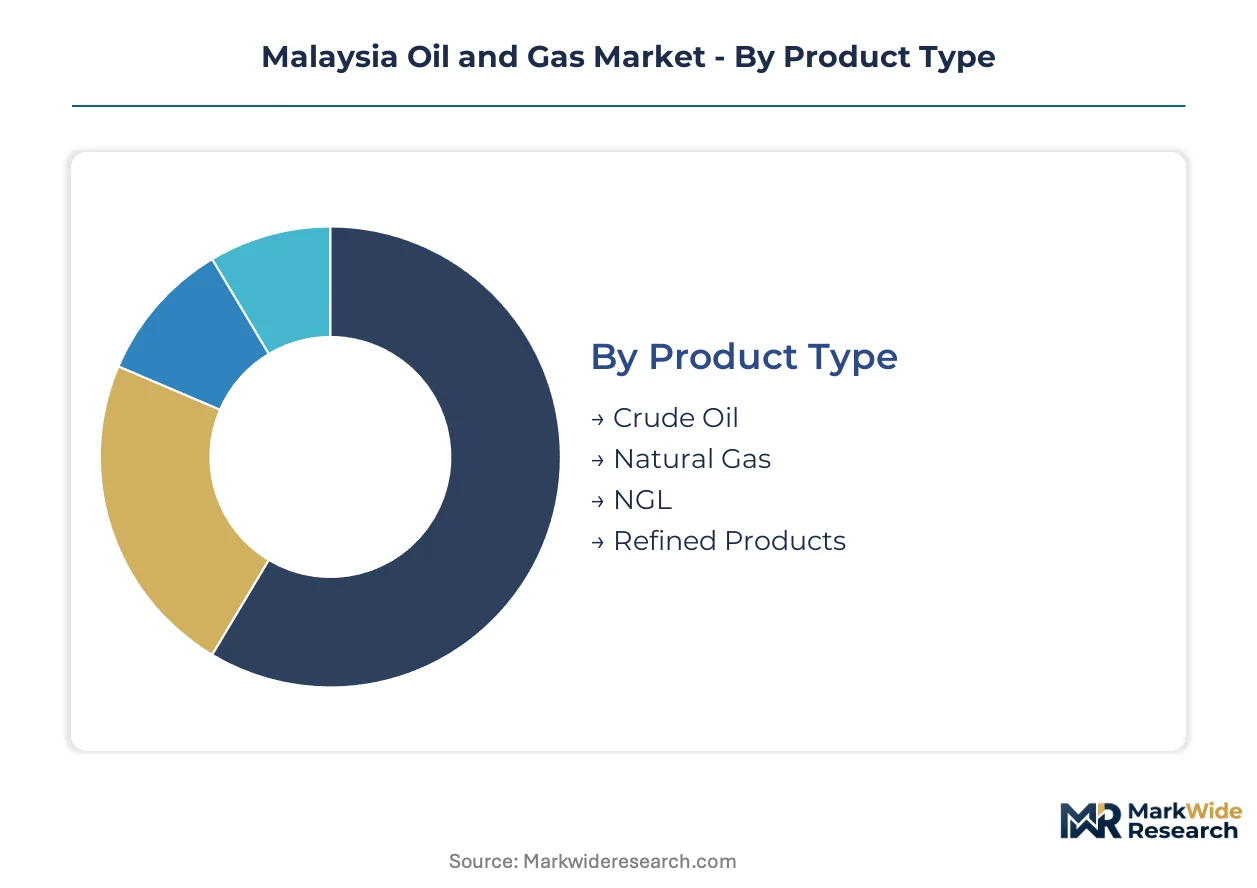
Segmentation reveals how capital flows diverge across Malaysia's hydrocarbon value chain. Product characteristics dictate infrastructure requirements, while end-user concentration shapes contracting patterns and margin capture.
Product Type:
Cost tiers separate commodities by processing intensity and transport economics across Malaysia's offshore basins and downstream complexes.
- Crude Oil:API gravities span light sweet grades from offshore Sarawak to heavy sour barrels from mature Peninsular fields. Refinery feedstock demand concentrates at the Pengerang Integrated Complex, where coking capacity handles heavier slates. The established base commands infrastructure investment.
- Natural Gas:Methane content exceeding 85 percent dominates production from the Bintulu LNG complex and offshore Sarawak pipelines. Power generation utilities under the Energy Commission absorb rising volumes as coal baseload retires. The steepest expansion runs through this segment.
- NGL:Ethane, propane, and butane fractions require cryogenic separation at gas processing facilities. Petrochemical feedstock demand from olefin crackers drives offtake contracting.
- Refined Products:Gasoline, diesel, and jet fuel output from Pengerang and Port Dickson refineries serve domestic transport and aviation corridors.
Natural gas anchors the revenue base through long-term LNG contracts. Crude oil faces the steepest margin pressure from carbon pricing consultations.
Technology:
Application maturity determines capital intensity and local content compliance burdens under Petroleum Development Act mandates.
- Exploration:Seismic acquisition and wildcat drilling in ultra-deepwater Sarawak blocks exceeds 1,500 meter depths, requiring specialized rig fleets with limited Asia-Pacific availability. PETRONAS Technical Standards govern safety specifications for all offshore installations.
- Drilling:Extended-reach and high-pressure high-temperature well construction dominates Baram Delta redevelopment campaigns. The established base commands contractor specialization.
- Production:Subsea tiebacks and enhanced oil recovery deployment sustain output from mature Samarang and Tapis complexes. The steepest expansion runs through artificial lift and chemical injection technologies.
- Refining:Hydrocracking and residue upgrading units at Pengerang process heavy sour crudes into high-value middle distillates.
Production technology absorbs the dominant capital share. Exploration faces the steepest cost escalation from rig dayrate inflation.
End User:
Customer type concentration shapes contract duration and price reopening frequency across Malaysia's energy transition pathway.
- Power Generation:Gas-fired baseload plants and combined cycle turbines under the Energy Commission absorb pipeline gas and regasified LNG. Single-buyer utility structures are fragmenting as independent power producers negotiate shorter-tenor agreements.
- Manufacturing:Steel, cement, and food processing facilities consume fuel oil and natural gas for process heat. The established base commands industrial tariff structures.
- Transport:Road diesel, marine bunkers, and aviation jet fuel serve Peninsular Malaysia logistics corridors and Singapore transshipment hubs. The steepest expansion runs through compressed natural gas for heavy trucking fleets.
- Chemical Industry:Olefin crackers and aromatics complexes at Kertih and Pengerang demand ethane, propane, and naphtha feedstocks.
Power generation anchors volume offtake. Transport fuels face the steepest substitution risk from electrification mandates.
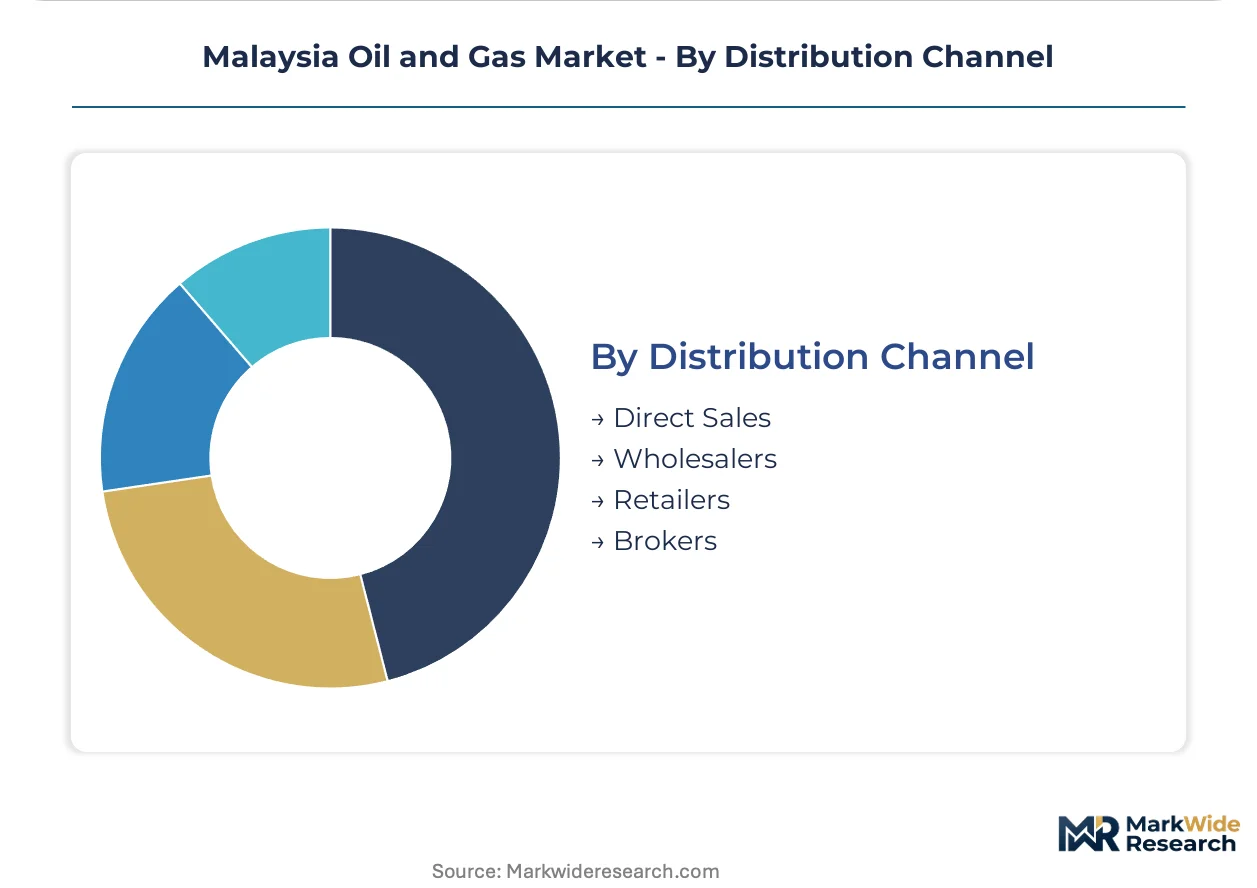
Distribution Channel:
Supply concentration determines margin retention and working capital requirements across Malaysia's regulated downstream.
- Direct Sales:Long-term offtake contracts between Petronas and major industrials eliminate intermediary margins. The established base commands premium pricing for volume certainty.
- Wholesalers:Licensed fuel oil and LPG distributors serve secondary cities and manufacturing clusters outside pipeline networks. The steepest expansion runs through consolidated wholesale networks achieving scale economies.
- Retailers:Petronas Dagangan and Shell Malaysia operate branded service stations across Peninsular Malaysia highway corridors.
- Brokers:Spot market intermediaries facilitate short-term LNG cargo optimization and crude oil trading.
Direct sales retain margin leadership through term contracting. Wholesale consolidation offers the steepest expansion pathway in underserved East Malaysia regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Natural gas consumption patterns diverge sharply across Malaysia's sub-regions, with Peninsular Malaysia prioritizing power generation feedstock while Sarawak and Sabah orient output toward LNG export and petrochemical integration.
Peninsular Malaysia
Gas-fired power plants and refining complexes drive hydrocarbon demand across the western corridor. The Energy Commission regulates pipeline tariffs under the Gas Supply Act while enforcing grid reliability standards. The Pengerang Integrated Complex in Johor processes heavy sour crudes into middle distillates for domestic transport and regional bunkering markets.
Sarawak
Deepwater production from the Baram Delta and Samarang fields sustains the Bintulu LNG complex as Malaysia's primary export hub. PETRONAS Technical Standards govern offshore safety specifications while the Petroleum Development Act mandates minimum local content thresholds. The Bintulu industrial zone concentrates gas processing, methanol production, and LNG liquefaction infrastructure.
Sabah
Offshore exploration in the Sabah Basin targets tieback opportunities to existing production infrastructure. The Department of Occupational Safety and Health enforces process safety management protocols under occupational health legislation. The Kimanis gas processing facility and adjacent industrial parks absorb domestic gas volumes for power and manufacturing applications.
Labuan
The federal territory functions as a deepwater supply base and offshore financial center supporting Sarawak and Sabah operations. Labuan offshore licensing frameworks accommodate petroleum trading and vessel registration activities. The Labuan port complex handles rig mobilization, equipment staging, and marine logistics for ultra-deepwater campaigns.
Malaysia Oil and Gas Market Competitive Landscape
Capability concentration sits with national oil companies possessing reserved acreage and regulatory influence; scale advantage sits with international majors deploying subsea engineering expertise across deepwater frontiers. Malaysia's upstream sector operates as a structured duopoly with Petronas anchoring domestic production and Shell, Exxon Mobil, and Chevron competing for operated positions in shared concessions. Two strategic archetypes dominate: integrated NOCs with preferential licensing access, and international operators with proprietary deepwater technology. Competitive dynamics center on farm-in negotiations for marginal field clusters and joint venture structuring around carbon capture integration.
Within the national champion tier, Petroliam Nasional Berhad anchors domestic production through operated positions across Peninsular Malaysia and Sarawak basins. Shell Plc and Exxon Mobil Corp exemplify the international major archetype, leveraging subsea infrastructure expertise at developments including Malikai and Tapis. Hibiscus Petroleum Bhd occupies a distinct position among listed independents focused on late-life asset rejuvenation and marginal field acquisitions.
| Leading Market Players |
|---|
| Petroliam Nasional Berhad (Petronas) |
| Shell Plc |
| Exxon Mobil Corp |
| Chevron |
| Sapura Energy Bhd |
| Hibiscus Petroleum Bhd |
| BP |
| Carimin Petroleum |
| Perintis Kembara Sdn Bhd |
| Others |
Supply & Pricing Matrix
Ultra-deepwater rig concentration in Singapore and South Korea yards anchors upstream cost structures and dictates where margin pools concentrate across Malaysia's offshore value chain. Long-term LNG offtake contracts at the Bintulu complex insulate Petronas from spot volatility while specialized drilling contractors extract premium dayrates from limited Asia-Pacific fleet availability.
Pricing Analysis
Contract-based long-term offtake dominates Malaysia's natural gas pricing, with power generation utilities under the Energy Commission negotiating shorter-tenor agreements incorporating price reopeners. Price differentiation rests on methane intensity benchmarks and local content compliance tiers under PETRONAS Technical Standards. Cost compression in ultra-deepwater drilling is intensifying because specialized rig scarcity inflates development breakevens. Independent power producers exhibit highest price sensitivity due to renewable intermittency exposure, while petrochemical offtakers at Pengerang demonstrate lowest sensitivity through integrated margin capture.
Supply Chain Analysis
Engineering procurement construction capacity concentrates in Singapore, South Korea, and Malaysia's own fabrication yards at Pasir Gudang and Lumut. Raw material dependencies span high-grade steel plate from Japan and South Korea, subsea trees from Norway and the United States, and dynamic positioning systems from European marine electronics specialists. Single-source vulnerability runs through subsea multiphase pump manufacturers with limited qualified suppliers. Distribution runs through Petronas's integrated logistics network and Shell's contracted marine spreads serving Sarawak and Sabah production corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward independent power producers as the Energy Commission fragments single-buyer utility structures and renewable intermittency forces gas contract renegotiation. This consolidation among electricity offtakers compresses margin capture for upstream suppliers.
For Market Incumbents: Insulate margin positions through backward integration into carbon capture infrastructure at depleted Baram Delta reservoirs, countering regulatory methane intensity benchmarks. Secure subsea engineering talent through captive training partnerships with Malaysian technical universities, addressing commissioning specialist scarcity that threatens project timelines. For New Entrants and Emerging Players: Pursue marginal field aggregation opportunities in Sarawak's shallow-water blocks where tieback economics to existing Petronas hub infrastructure reduce development thresholds. Target late-life asset rejuvenation contracts where Hibiscus Petroleum's demonstrated model validates commercial viability. Lead with digital twin deployment capabilities that reduce unplanned shutdowns for aging Peninsular Malaysia platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed drilling contractors holding specialized ultra-deepwater rig fleets. Long-term viability hinges on carbon capture integration mandates and Petronas Net Zero Carbon Emissions 2050 capital reallocation. Watch methane performance standard enforcement under Department of Occupational Safety and Health protocols as the inflection signal for accelerated asset retirement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Depleted offshore reservoirs at Baram Delta align with Petronas 2050 net-zero commitments and create sequestration revenue streams. |
| Subsea Processing Deployment | Multiphase pumps at Malikai and Gumusut-Kakap defer platform upgrades and enable previously subcommercial tieback developments. |
| Digital Twin Implementation | Real-time production optimization reduces unplanned shutdowns across aging Samarang and Tapis complex infrastructure. |
| Local Content Compliance Investment | Petroleum Development Act thresholds and PETRONAS Technical Standards mandate procurement rigidities that favor established engineering networks. |
| Marginal Field Aggregation | Bundling subscale Sarawak discoveries around existing hub infrastructure offers lower-carbon pathways than greenfield standalone projects. |
Research Methodology
A standing panel of upstream project managers, subsea engineering contractors, Energy Commission regulatory officers, and Bintulu LNG offtake negotiators provided ongoing calibration throughout the study period. Primary interviews with Petronas technical standards specialists and Shell Malaysia development executives combined with secondary validation from Petroleum Development Act compliance filings, Department of Occupational Safety and Health enforcement records, and Energy Commission tariff determinations. Bottom-up field-level production economics and top-down sectoral demand modeling were triangulated against trade data from Malaysian customs records and LNG cargo tracking databases.
Scenario-bracketing around coal-to-gas transition velocity and renewable substitution pace structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology application, end-user sector, and distribution channel concentration. CAGRs were derived from production decline curve analysis, greenfield sanctioning timelines, and downstream capacity expansion schedules. Industry-specific forecast inputs incorporated ultra-deepwater rig dayrate trajectories and methane emissions cap implementation phasing.
Sensitivities concentrate around carbon pricing mechanism adoption timelines and local content threshold escalation under Petroleum Development Act revisions. Forecasts reflect assumptions regarding Petronas capital allocation priorities and Shell's deepwater portfolio commitment levels. Quarterly review of LNG spot price spreads, rig fleet utilization rates, and renewable auction clearing prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Nigeria Upstream Oil Sector Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
North America Shale Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
LNG Storage Tank Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market