
 Europe Wireline Logging Services Market | 2026-2036
Europe Wireline Logging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wireline Logging Services Market Foresight
The European wireline logging market is pivoting around a widening gap between premium technology tiers and commodity service offerings. Schlumberger Limited leverages integrated logging-while-drilling platforms to sustain premium positioning across North Sea contracts. Baker Hughes Company anchors its competitiveness through proprietary resistivity imaging systems tailored for high-pressure formations. Halliburton Company differentiates via modular toolstrings that reduce rig time for marginal field operators.
Wireline logging services deploy instrumented cables to lower measurement tools into boreholes, capturing formation properties through gamma ray, neutron porosity, and resistivity sensors at depths exceeding 6,000 meters. These measurements enable real-time decisions on hydrocarbon saturation, permeability, and completion design. Open hole logging commands the largest revenue share where exploration drilling in frontier basins demands comprehensive formation evaluation before casing. Cased hole logging grows fastest as brownfield operators prioritize through-tubing reservoir monitoring to maximize recovery from existing wells.
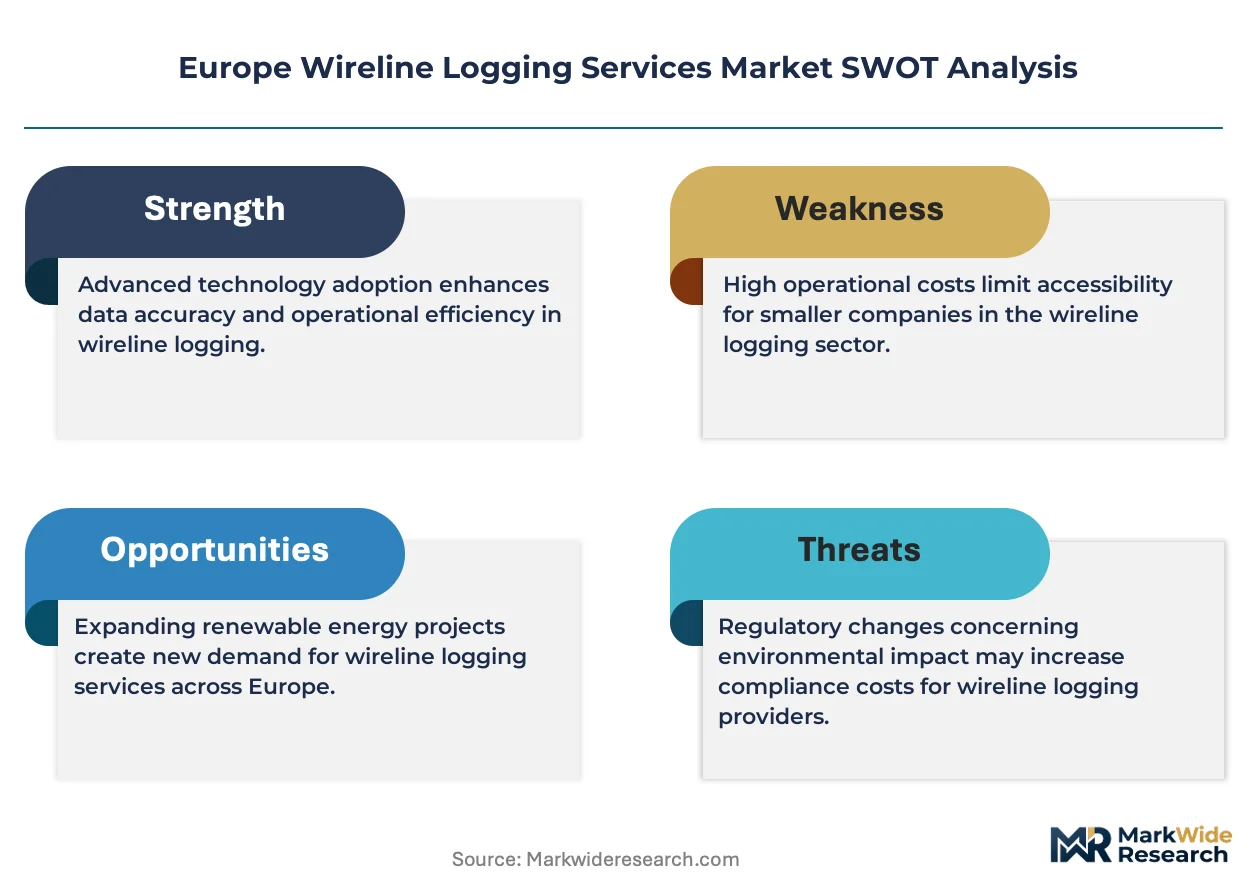
The EU Green Deal and national methane reduction frameworks enforced by environmental regulators in Norway and the UK mandate continuous leak detection, directly expanding demand for cased hole logging services. REACH compliance and CE marking requirements for downhole electronics shape equipment procurement standards across European service companies. Stakeholders must weigh technology specialization against geographic diversification as regulatory stringency tightens and operator capital discipline favors integrated service providers.
Market Dynamics
The North Sea's mature basin redevelopment is compressing service margins while elevating technical requirements, forcing wireline operators to choose between premium specialization and integrated commoditization.
Growth Catalysts
- EU Green Deal methane mandates:Norway's environmental regulator and the UK's North Sea Transition Authority enforce continuous leak detection protocols, expanding cased hole logging deployment across brownfield assets.
- High-pressure formation evaluation:Ultra-deep HPHT reservoirs in the Norwegian Continental Shelf require resistivity imaging tools rated above 200°C, pulling advanced wireline packages into frontier drilling programs.
- Netherlands geothermal repurposing:Depleted gas fields in Groningen are converting to geothermal heat extraction, creating demand for precise temperature-gradient logging through existing wellbores.
Market Restraints
- Electronics supply concentration:REACH-compliant downhole sensors depend on specialized semiconductor foundries concentrated in Germany and France, exposing service companies to 18-24 month procurement queues.
- Substitution by logging-while-drilling:LWD systems eliminate separate wireline runs in horizontal sections, compressing addressable market for conventional open hole services in shale-style developments.
- CE marking compliance costs:Downhole electronics must meet EU electromagnetic compatibility directives, adding certification overhead that disadvantages smaller regional tool manufacturers.
Strategic Opportunities
- Carbon capture site characterization:North Sea saline aquifers designated for CO2 storage require pre-injection wireline surveys to verify caprock integrity, opening a new service category in the UK and Norway.
- Modular toolstring platforms:Configurable gamma ray-resistivity combinations reduce rig time for marginal field operators in the southern North Sea, enabling service tier differentiation.
- CSRD disclosure requirements:Corporate sustainability reporting mandates from the European Commission push operators toward verifiable methane monitoring data, favoring logging providers with certified measurement traceability.
Industry Challenges
- Petrophysicist talent scarcity:Interpretation of complex lithology from image logs requires specialized expertise that European universities produce insufficiently, forcing service companies to poach from operator geoscience departments.
- Legacy wellbore access: Cased hole operations in 30-year-old North Sea wells face corroded tubing and unknown mechanical conditions, elevating operational risk and insurance costs for through-tubing logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wireline Logging Services Market |
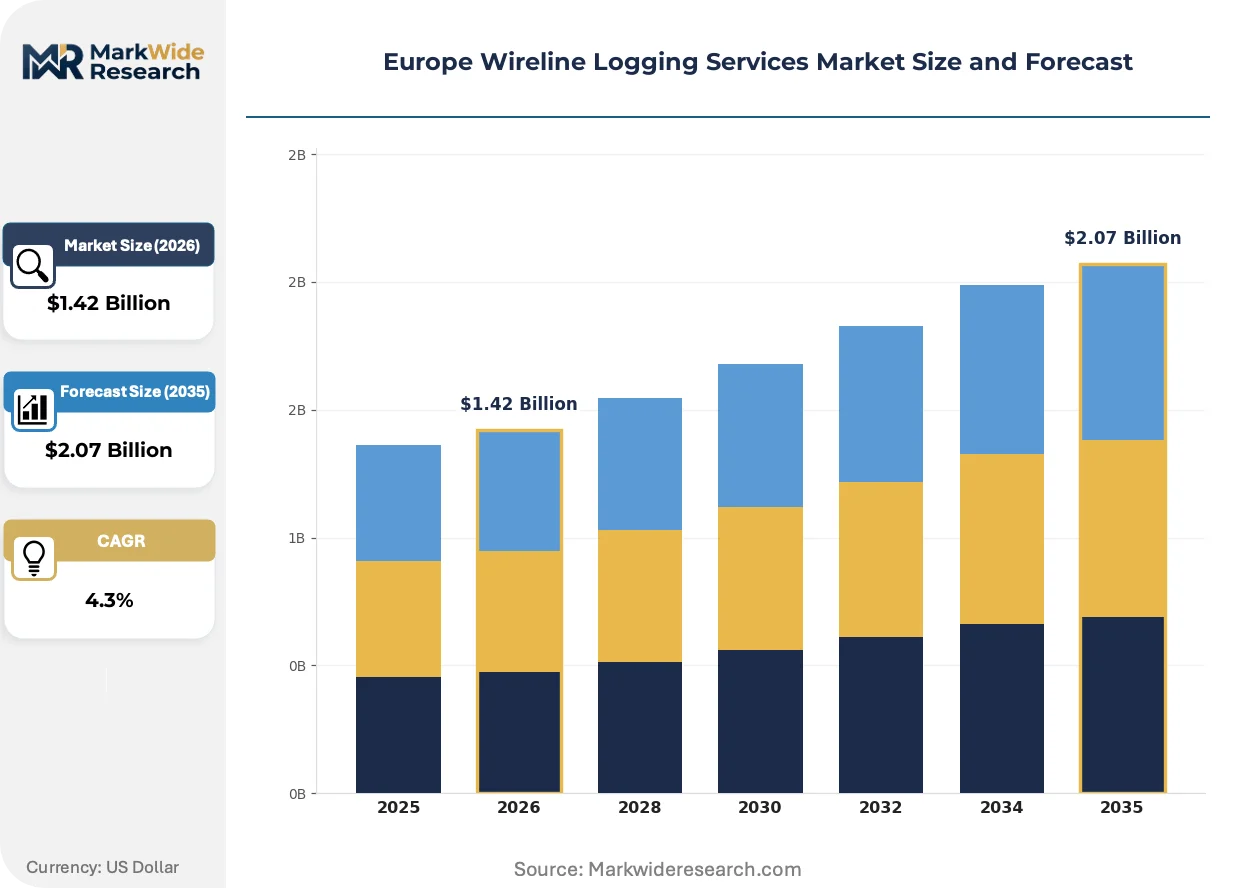
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.07 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Open Hole Logging, Cased Hole Logging, Memory Logging, Continuous Logging Technology: Electromagnetic, Acoustic, Nuclear, Resistivity End User: Oil & Gas Operators, Drilling Contractors, Service Companies, Research Institutions Application: Hydrocarbon Exploration, Reservoir Evaluation, Formation Analysis, Environmental Monitoring |
| Companies Covered | Weatherford International plc, SEMM Logging, Schlumberger Limited, Integra Group Holdings, Paradigm Group B.V., Halliburton Company, Superior Energy Services Inc, Expro International Group Ltd, Baker Hughes Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wireline Logging Services Market Shifts & Advancements
Digital telemetry and real-time formation evaluation are compressing decision cycles between downhole measurement and completion design, reshaping how North Sea operators deploy wireline assets.
High-resolution micro-resistivity imaging is expanding into fracture network characterization for tight carbonate reservoirs. Norwegian operators on the Utsira High are adopting these tools to map secondary porosity before hydraulic stimulation programs. The technology is expanding into pre-drill geological model validation, reducing exploration dry hole risk.
REACH authorization requirements for downhole chemical tracers are tightening formulation standards across European service companies. ECHA's 2023 restrictions on perfluorinated compounds forced reformulation of oil-based mud tracers used in resistivity logging. Norwegian operators now specify tracer-free formation evaluation packages to preempt regulatory delays.
Integrated logging-drilling contracts are consolidating vendor relationships among North Sea majors. BP and Equinor have shifted toward single-source agreements covering both LWD and wireline services, compressing the addressable market for standalone wireline specialists. This concentration is most visible in Norway's Johan Sverdrup phase 2 development, where one contractor provides all formation evaluation.
Europe Wireline Logging Services Market Segmentation
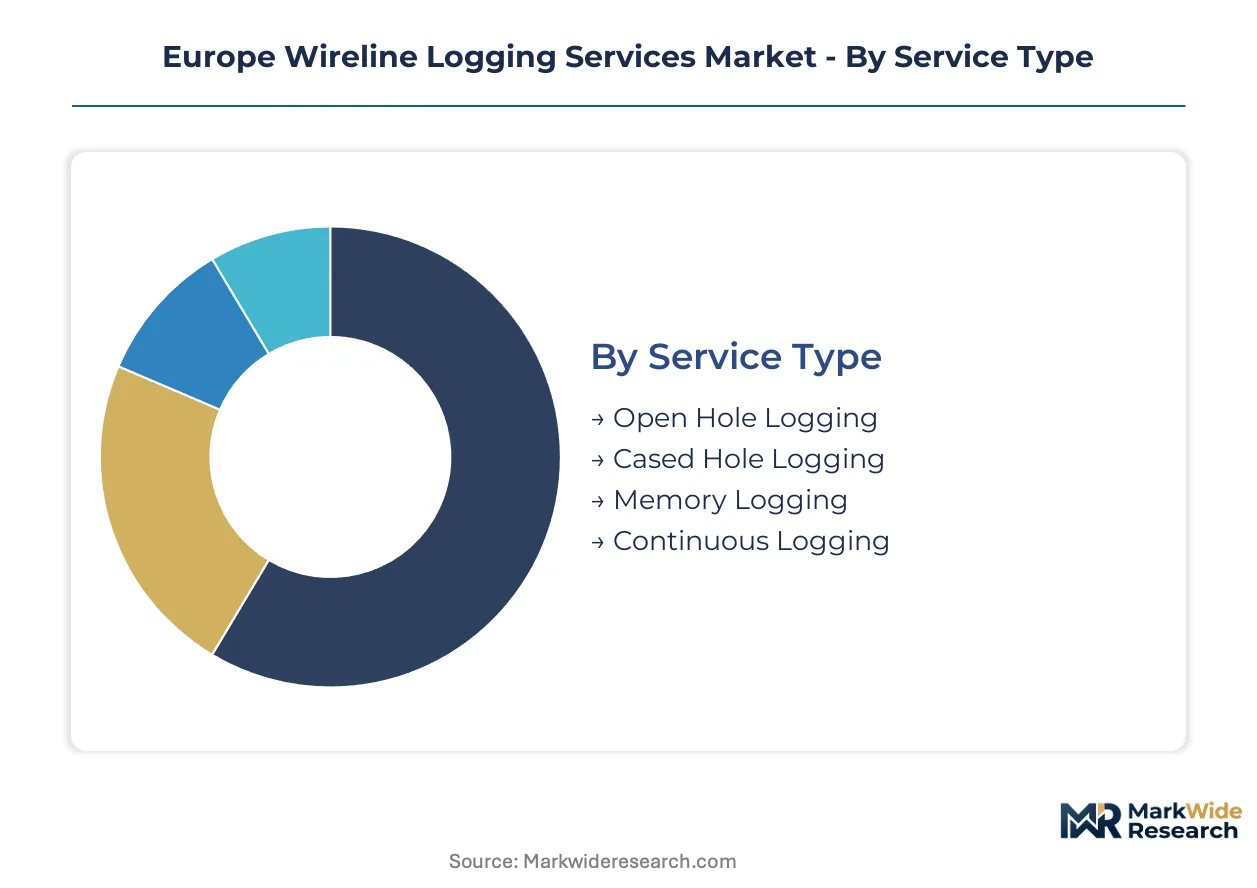
Wireline logging services fragment across four distinct dimensions that shape procurement patterns and technology requirements in the European market. Service type determines rig-time economics and operational risk profiles, while technology selection reflects formation complexity and regulatory constraints on downhole instrumentation.
Service Type:
Buyers differentiate based on wellbore condition and the trade-off between real-time data access versus operational simplicity.
- Open Hole Logging:Deploys measurement tools into uncased boreholes to capture gamma ray, neutron porosity, and resistivity profiles before cementing. Frontier exploration in the Norwegian Continental Shelf and UK West of Shetland drives demand for comprehensive formation evaluation packages that minimize dry hole risk.
- Cased Hole Logging:Conducts through-tubing measurements in completed wells for reservoir monitoring and production optimization. Norway's methane leak detection mandates under the EU Green Deal accelerate deployment across mature North Sea assets requiring continuous integrity verification.
- Memory Logging:Records downhole data without real-time telemetry, retrieving instruments for post-run analysis. High-pressure formations where electrical cable reliability degrades favor this approach.
- Continuous Logging:Maintains uninterrupted measurement during pipe-conveyed operations in highly deviated wellbores. Extended-reach drilling in the UK Central North Sea creates specialized demand.
Open hole logging leads volumes today; cased hole logging is gaining share fastest.
Technology:
Technology selection hinges on formation property targets and thermal rating requirements for high-pressure environments.
- Resistivity:Measures formation conductivity to distinguish hydrocarbon-bearing zones from water-saturated intervals. Norwegian HPHT reservoirs above 200°C require specialized imaging tools that Baker Hughes and Schlumberger deploy across the Utsira High.
- Nuclear:Utilizes neutron and gamma ray sources to determine porosity and lithology. REACH authorization constraints on radioactive sources complicate logistics for European service companies.
- Acoustic:Captures compressional and shear wave velocities for mechanical property determination. Geothermal repurposing of depleted Groningen fields in the Netherlands creates emerging demand for temperature-gradient verification.
- Electromagnetic:Induces eddy currents to assess casing thickness and corrosion in brownfield wells. Legacy wellbore integrity programs across the UK Southern North Sea utilize these measurements.
Resistivity imaging dominates revenue; nuclear logging faces regulatory headwinds.
End User:
Procurement authority concentrates with entities controlling well access and regulatory compliance obligations.
- Oil & Gas Operators:National oil companies and international majors including Equinor, BP, and Shell specify logging programs and award integrated service contracts. These buyers prioritize measurement traceability for CSRD methane disclosure requirements.
- Drilling Contractors:Noble Corporation and Transocean integrate wireline services into rig-based packages to minimize non-productive time. Their procurement favors modular toolstrings that reduce mobilization intervals.
- Service Companies:Specialist logging contractors purchase tool components and telemetry systems from technology suppliers. REACH-compliant electronics sourcing from German and French foundries constrains their procurement flexibility.
- Research Institutions:Universities and national laboratories acquire logging services for geothermal and carbon storage characterization. The British Geological Survey and Norwegian research programs drive pre-competitive data acquisition.
Oil and gas operators command the largest procurement budgets; research institutions are expanding most quickly.
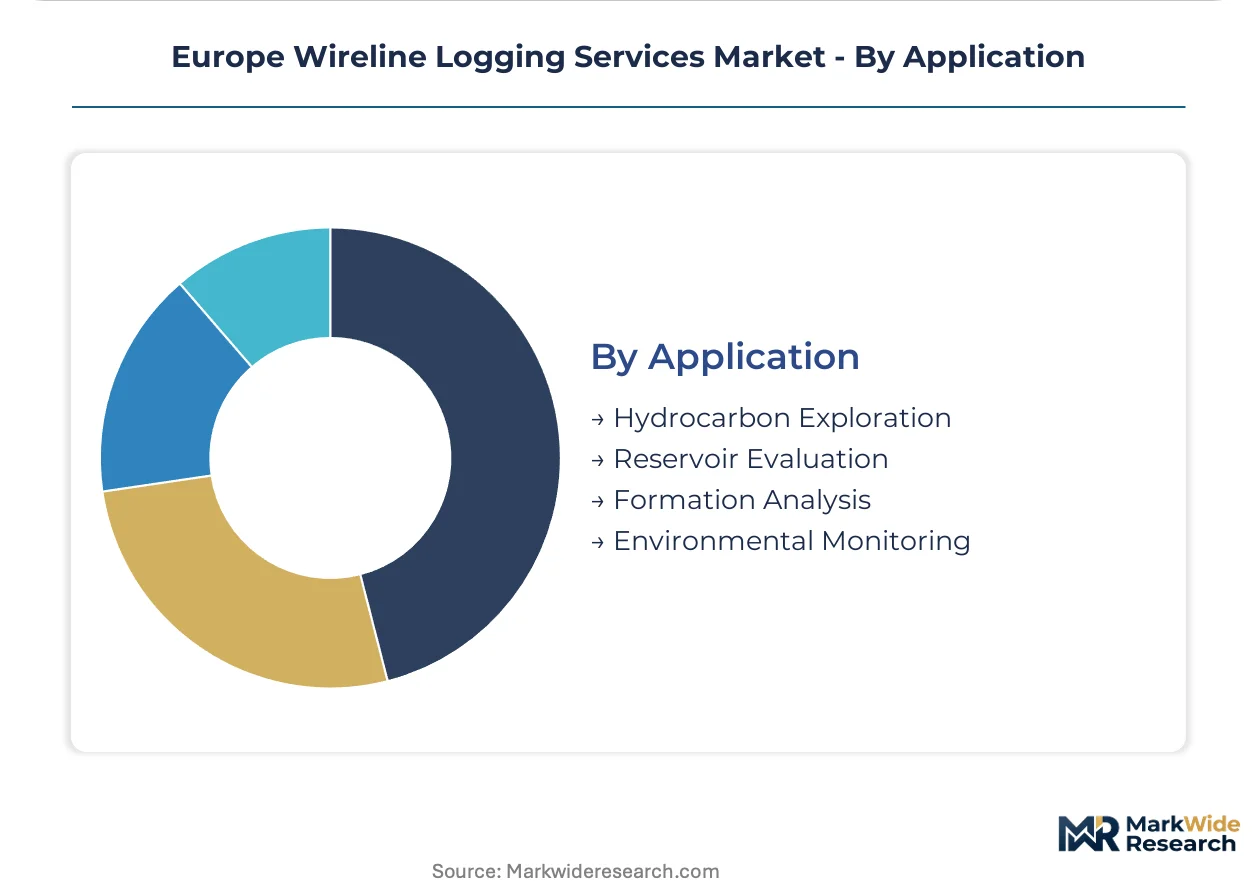
Application:
Application scope determines measurement complexity and the regulatory frameworks governing data acquisition.
- Hydrocarbon Exploration:Frontier drilling programs require comprehensive open hole evaluation to validate geological models. The UK North Sea Transition Authority mandates detailed formation assessment before field development approval.
- Reservoir Evaluation:Brownfield operators deploy time-lapse logging to track fluid movement and remaining oil saturation. Norway's Johan Sverdrup development exemplifies integrated logging programs across production phases.
- Formation Analysis:Petrophysical interpretation supports completion design and stimulation planning. Tight carbonate reservoirs on the Norwegian Continental Shelf require micro-resistivity imaging for fracture network mapping.
- Environmental Monitoring:CO2 storage site characterization and methane leak detection create emerging service categories. UK and Norwegian saline aquifer assessments for carbon capture projects drive specialized caprock integrity surveys.
Reservoir evaluation generates the most recurring revenue; environmental monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrophysicist talent concentrates in Stavanger, Aberdeen, and The Hague, anchoring wireline logging expertise across the North Sea basin. These technical clusters support mature basin redevelopment and frontier exploration programs. National regulators enforce divergent environmental standards that reshape service procurement patterns.
Norway
Equinor's Johan Sverdrup phase 2 development drives demand for integrated logging-while-drilling and wireline packages in ultra-deep HPHT reservoirs. The Norwegian Environmental Agency enforces continuous methane leak detection protocols under EU Green Deal frameworks, expanding cased hole monitoring across brownfield assets. Stavanger anchors the Utsira High exploration cluster where micro-resistivity imaging tools map fracture networks in tight carbonate formations.
United Kingdom
BP and Shell prioritize single-source formation evaluation contracts covering both LWD and wireline services to reduce rig downtime. The North Sea Transition Authority mandates comprehensive open hole assessment before field development approval, elevating technical requirements for exploration drilling. Aberdeen houses the primary service company engineering centers supporting West of Shetland frontier programs.
Netherlands
Depleted Groningen gas fields convert to geothermal heat extraction, creating demand for precise temperature-gradient logging through existing wellbores. REACH authorization constraints on radioactive sources complicate nuclear logging logistics, pushing operators toward tracer-free formation evaluation packages. The Hague concentrates regulatory compliance expertise for ECHA-aligned chemical management protocols.
Germany
Specialized semiconductor foundries in Bavaria and Baden-Württemberg produce REACH-compliant downhole sensors, exposing service companies to 18-24 month procurement queues. CE marking requirements for electromagnetic compatibility add certification overhead that disadvantages smaller regional tool manufacturers. Munich anchors electronics supply relationships critical for high-temperature resistivity imaging systems.
France
Research institutions including IFP Energies nouvelles acquire logging services for carbon storage site characterization in Paris Basin saline aquifers. ECHA's 2023 restrictions on perfluorinated compounds forced reformulation of oil-based mud tracers, reshaping chemical service procurement. Lyon concentrates geothermal exploration programs requiring acoustic velocity measurements for mechanical property determination.
Europe Wireline Logging Services Market Competitive Landscape
Capital-heavy integrated service providers compete with asset-light specialists across the European wireline logging market. Schlumberger, Baker Hughes, and Halliburton anchor the consolidated tier through bundled drilling-evaluation contracts, while regional specialists defend niche positions in cased hole monitoring and memory logging. Three archetypes dominate: integrated energy service conglomerates, independent wireline specialists, and geothermal-focused regional contractors. Competitive dynamics center on M&A consolidation of specialist tool manufacturers and strategic partnerships for REACH-compliant electronics sourcing.
Within the integrated service tier, Schlumberger Limited, Baker Hughes Company, and Halliburton Company occupy positions defined by proprietary technology platforms and multi-decade North Sea operating histories. These entities exemplify the capital-intensive archetype through captive supply chains for high-pressure formation evaluation tools. Among independent specialists, Weatherford International plc and Expro International Group Ltd represent asset-light configurations focused on modular toolstring flexibility for marginal field operators. SEMM Logging and Paradigm Group B.V. anchor the regional specialist tier with concentrated exposure to Norwegian and Dutch regulatory environments respectively.
| Leading Market Players |
|---|
| Weatherford International plc |
| SEMM Logging |
| Schlumberger Limited |
| Integra Group Holdings |
| Paradigm Group B.V. |
| Halliburton Company |
| Superior Energy Services Inc |
| Expro International Group Ltd |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
Equinor and BP's shift toward single-source formation evaluation contracts is forcing wireline specialists to absorb bundled-service pricing models or exit premium segments entirely, compressing margins for standalone providers while rewarding integrated operators with volume guarantees and multi-year rig commitments.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the European wireline logging market. Project-based contracting dominates, with integrated LWD-wireline packages commanding premium positioning against standalone open hole or cased hole offerings. Price differentiation separates operators with certified methane monitoring traceability for CSRD disclosure from commodity service tiers lacking measurement auditability. Pricing pressure stems from operator capital discipline favoring single-source agreements, eroding margins for modular specialists. Marginal field operators in the UK Southern North Sea exhibit highest price sensitivity, while Norwegian HPHT frontier programs show lowest sensitivity due to technical complexity barriers.
Supply Chain Analysis
High-temperature downhole electronics supply rests on specialized semiconductor foundries concentrated in Germany and France. REACH-compliant sensors and CE-marked telemetry systems draw from Bavarian and Baden-Württemberg manufacturing clusters, with secondary sourcing through Lyon-area electronics suppliers. Raw material dependencies include high-grade silicon carbide substrates, radiation-hardened integrated circuits, and specialized ceramic pressure housings. Single-source vulnerability pervades the 200°C-rated resistivity imaging segment, where qualified foundry capacity remains constrained. Distribution runs through rig-integrated service packages rather than standalone equipment sales, tying tool deployment to drilling contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European wireline logging operates as a geographic-arbitrage play where REACH compliance costs in Germany and France create cost disadvantages against Norwegian and UK operators able to source through less stringent regulatory pathways, rewarding positioning strategies that exploit these jurisdictional differentials.
For Market Incumbents: Extend backward integration into REACH-compliant electronics sourcing to secure sensor supply against 18-24 month procurement queues threatening contract fulfillment. Consolidate cased hole monitoring capabilities through specialist acquisitions before carbon capture site characterization demand peaks, as Schlumberger and Baker Hughes already dominate integrated logging-while-drilling platforms and will leverage this position to displace standalone wireline providers in Norwegian HPHT contracts.
For New Entrants and Emerging Players: Geothermal operators repurposing depleted Groningen fields represent an underserved buyer archetype with distinct procurement patterns and limited incumbent relationship lock-in. Carbon storage site characterization in UK and Norwegian saline aquifers offers the most penetrable application segment, with petrophysical interpretation requirements less standardized than hydrocarbon exploration. A go-to-market angle anchored in tracer-free formation evaluation packages preempts ECHA regulatory delays that constrain established players.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists holding concentrated exposure to Dutch geothermal and UK carbon capture regulatory environments. Long-term viability over a 5-10 year window favors asset-light configurations with modular toolstring flexibility rather than capital-heavy integrated platforms vulnerable to operator consolidation. Acquisition targets should demonstrate certified measurement traceability for CSRD methane disclosure requirements. The signal to watch is Johan Sverdrup phase 2 contract renewal patterns, which will indicate whether single-source integration becomes irreversible across Norwegian Continental Shelf developments.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Electronics Sourcing Partnership | Secures sensor supply from German foundries against procurement bottlenecks threatening contract delivery. |
| Tracer-Free Formation Evaluation Package Development | Preempts ECHA regulatory delays on perfluorinated compound restrictions reshaping chemical service procurement. |
| Carbon Capture Site Characterization Capability Buildout | Captures emerging demand from UK and Norwegian saline aquifer assessments for CO2 storage verification. |
| Modular Toolstring Platform Standardization | Reduces rig time for marginal field operators in the southern North Sea facing capital discipline pressures. |
| CSRD-Certified Methane Monitoring Data Service | Aligns with European Commission sustainability reporting mandates favoring verifiable measurement traceability. |
Research Methodology
Coverage spans Norway, the United Kingdom, the Netherlands, Germany, and France, with primary inputs from each market informing demand-side and supply-side assessments. The analysis combines structured interviews with petrophysicists at Equinor and Shell, procurement leads at drilling contractors including Noble Corporation and Transocean, regulatory affairs specialists at ECHA and the Norwegian Environmental Agency, and engineering directors at wireline service providers. Secondary validation draws from EU Green Deal implementation documents, REACH authorization records, North Sea Transition Authority drilling approval filings, and CE marking compliance databases. Bottom-up rig-count and well-completion data triangulates against top-down market sizing from energy service expenditure disclosures.
Granularity-level modeling distinguishes open hole versus cased hole service types, resistivity versus nuclear versus acoustic versus electromagnetic technologies, and hydrocarbon exploration versus reservoir evaluation versus environmental monitoring applications across the projection horizon. The analytical framework incorporates wellbore complexity indices, HPHT formation prevalence, and methane regulatory stringency as industry-specific forecast inputs. CAGRs derive from segment-level volume projections weighted by average service pricing tiers, with cross-validation against operator capital expenditure guidance and rig contract award patterns.
Underlying measurement precision varies by segment; cased hole logging and environmental monitoring carry tighter precision than frontier exploration given more predictable well count trajectories. Forecasts reflect assumptions regarding regulatory enforcement consistency, operator capital discipline continuity, and electronics supply chain normalization. Specific risk factors that could revise projections include accelerated LWD substitution in horizontal sections, ECHA expansion of restricted chemical categories, and Norwegian tax regime changes affecting marginal field economics. A small set of named triggers—Johan Sverdrup contract renewal timing, Groningen geothermal conversion pace, and Utsira High exploration drilling results—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
LNG Terminal Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
Intelligent Pigging Services Market