
 Iran Oil and Gas Market | 2026-2036
Iran Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Oil and Gas Market Outlook
Market Context
The divergence between premium sour crude grades and heavy residual commodity streams is repositioning how Iranian operators allocate upstream investment against downstream margin capture. National Iranian Oil Company sustains field dominance across onshore reservoirs in Ahvaz and Marun through maintained artificial lift infrastructure. Persian Gulf Petrochemical Industries Company specializes in converting associated gas into methanol and olefin chains, extending its captive feedstock advantage. Pars Oil and Gas Company anchors South Pars phase development, leveraging Qatar's adjacent North Field drilling patterns to optimize well spacing.
Technical Definition and Segments
Iran oil and gas encompasses hydrocarbon extraction, processing, and distribution operations spanning crude oil with API gravities from 26 to 38 degrees and natural gas containing 5-10 mole percent carbon dioxide, primarily serving domestic energy security, export revenue generation, and petrochemical feedstock supply. The upstream technology segment dominates capital deployment through offshore platform construction and onshore drilling campaigns, while enhanced oil recovery is accelerating as mature fields require pressure maintenance and thermal stimulation to sustain plateau production rates. Downstream refining retains entrenched margin pools around fuel oil and diesel output for domestic transportation and heating markets, though petrochemical feedstock applications are redirecting naphtha flows toward aromatic and polymer production.
Regulatory Frame
The Petroleum Ministry of Iran governs exploration licensing through Iranian Petroleum Contracts, while the National Iranian Oil Company administers buy-back terms that limit foreign equity participation but permit cost recovery through production allocations. The country's national environmental regulator enforces flaring reduction mandates at gas processing facilities, shaping investment in vapor recovery and sulfur recovery units. Stakeholders must monitor how sanctions architecture affects drilling equipment procurement and whether domestic fabrication capacity can substitute for restricted imports of subsea wellhead systems.
Market Dynamics
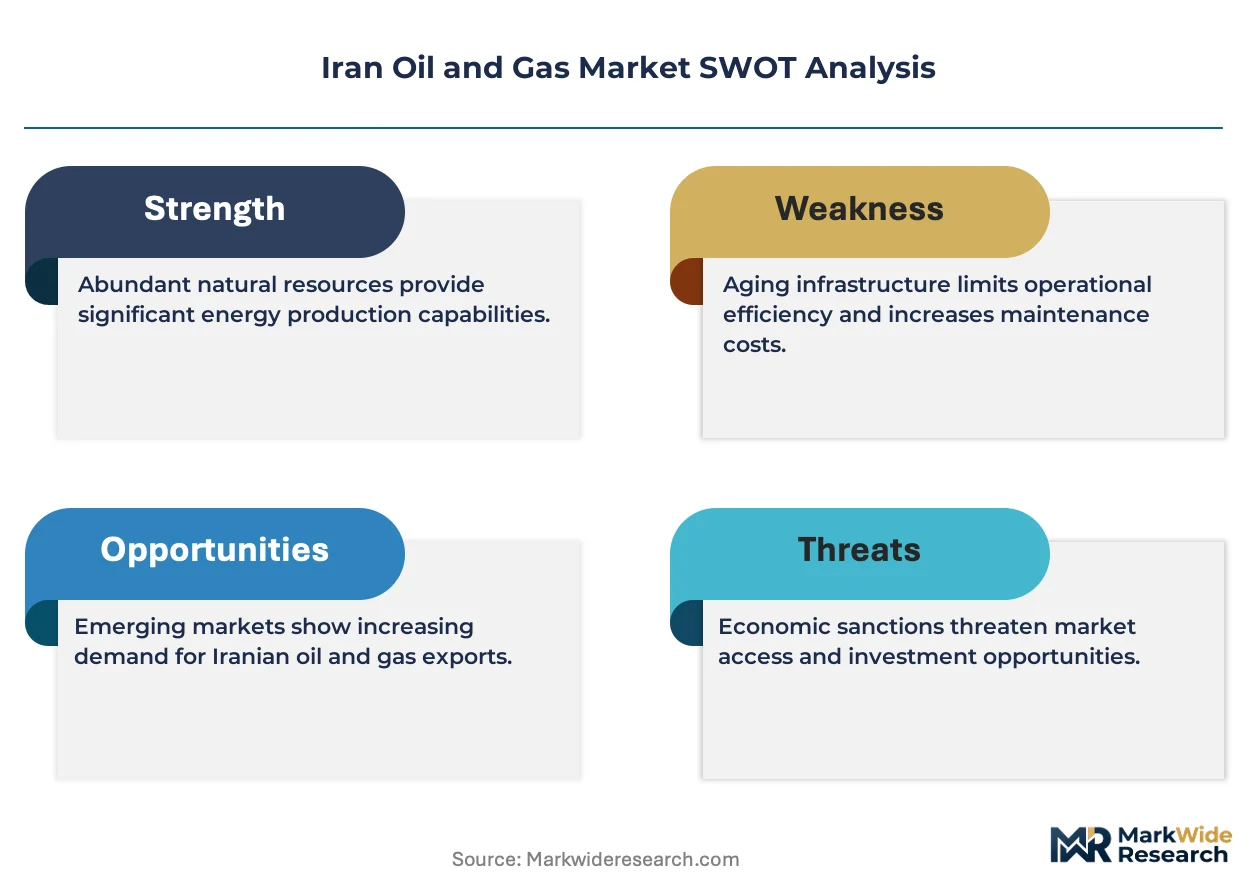
Sanctions architecture is compressing capital access and forcing Iranian operators toward domestic fabrication partnerships, fundamentally restructuring how field development contracts allocate risk between state entities and service providers.
Growth Catalysts
- South Pars reservoir optimization:Shared field management with Qatar's North Field is driving well spacing improvements and recovery factor gains through coordinated pressure maintenance strategies.
- Buy-back contract reforms:The Petroleum Ministry's revised Iranian Petroleum Contracts are expanding cost recovery mechanisms and extending contract durations to attract technical service investment.
- Flaring reduction mandates:Iran's national environmental regulator is enforcing vapor recovery unit installation at gas processing facilities, creating demand for sulfur recovery and gas monetization infrastructure.
Market Restraints
- Drilling equipment procurement constraints:Restrictions on subsea wellhead system imports are forcing reliance on limited domestic fabrication capacity, extending project timelines.
- Capital formation barriers:International banking restrictions are blocking project finance for offshore platform construction, constraining phase development in deeper South Pars segments.
- Heavy crude processing limitations:Existing refinery configurations are optimized for lighter API gravities, limiting margin capture from heavier fractions produced at mature Ahvaz and Marun fields.
Strategic Opportunities
- Petrochemical feedstock pivot:Methanol and olefin chain expansion at Asaluyeh complexes is redirecting associated gas flows from power generation to higher-value polymer production.
- Enhanced oil recovery deployment:Thermal stimulation and gas injection techniques at depleted onshore reservoirs offer production plateau extension without new exploration exposure.
- Artificial lift infrastructure modernization:Sustained investment in electric submersible pumps and gas lift systems at National Iranian Oil Company fields is opening domestic manufacturing partnerships.
Industry Challenges
- Subsea engineering skill scarcity:Specialized expertise for deepwater completion design and installation is concentrated outside Iran, complicating knowledge transfer under restricted mobility conditions.
- Legacy field data integration:Decades of reservoir characterization records held in incompatible formats are impeding digital twin deployment for real-time production optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Oil and Gas Market |
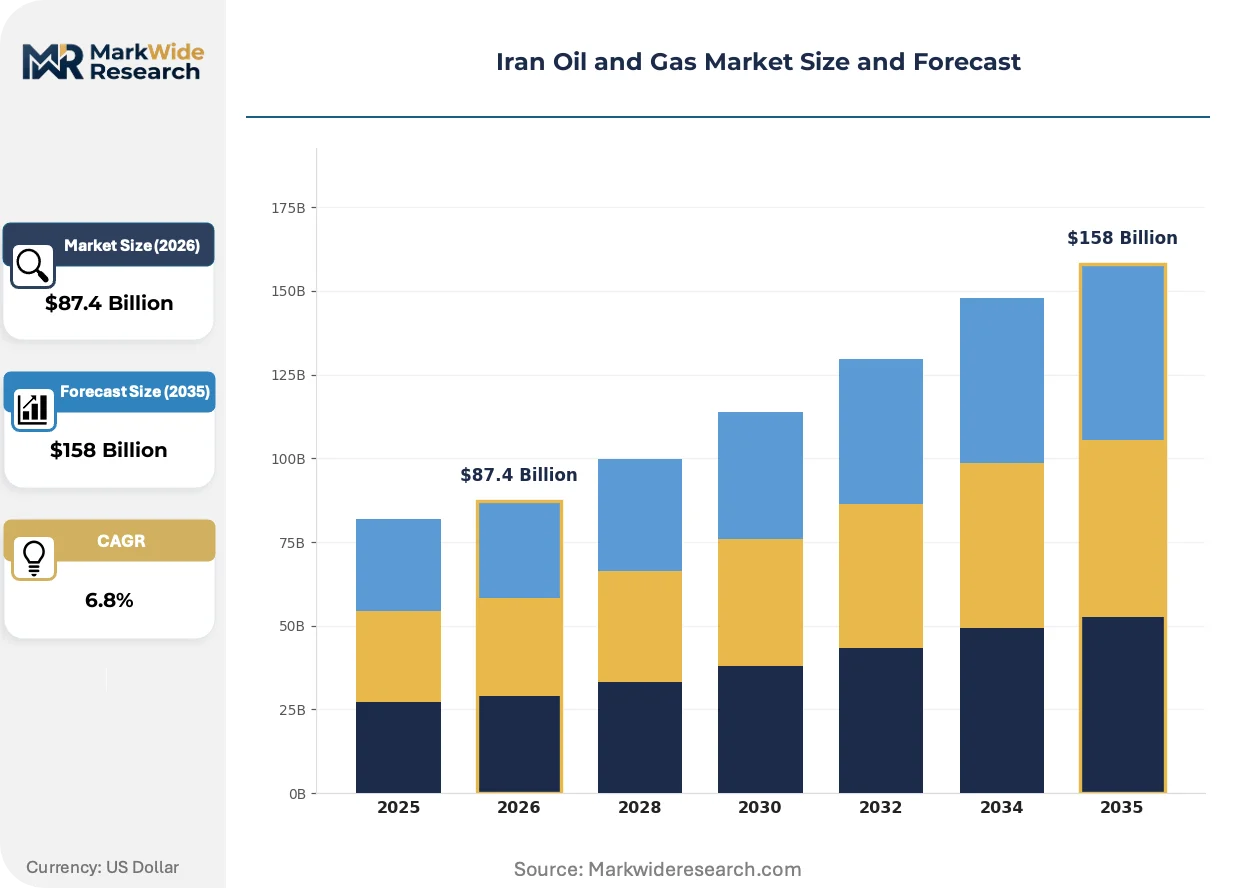
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Refining, Distribution Technology: Upstream, Midstream, Downstream, Enhanced Oil Recovery End User: Industrial, Power Generation, Petrochemical, Transportation Application: Heating, Fuel, Lubricants, Chemical Feedstock |
| Companies Covered | Petropars, Pars Oil and Gas Company, National Iranian Oil Company, Petroleum Engineering and Development Company, Iranians Offshore Oil Company, National Iranian Oil Refining and Distribution Company, Persian Gulf Petrochemical Industries Company, Naftan Company, National Iranian Gas Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Oil and Gas Market Strategic Shifts
Digital reservoir management systems are displacing conventional well testing protocols, compressing decision cycles for field development planning and enabling real-time production adjustments across Iran's mature onshore assets.
Gas-to-wire power generation technology is consolidating distributed electricity supply at remote wellpad locations, displacing diesel-fueled mobile generators that previously served artificial lift and processing equipment. Persian Gulf Petrochemical Industries Company and Pars Oil and Gas Company are deploying modular turbine packages at South Pars phases, reducing fuel logistics burden and capturing previously flared gas volumes for on-site power conversion. This distributed generation architecture is consolidating captive energy supply within production complexes, reducing grid dependency and transmission losses across the Assaluyeh industrial corridor.
Iran's Petroleum Ministry buy-back contract reforms are extending cost recovery periods and introducing production bonus structures that shift contractor risk allocation. The revised Iranian Petroleum Contract framework permits longer operational involvement for international service providers without equity participation, altering how drilling and completion risks are priced into field development economics. Upstream segments with extended plateau production profiles, particularly South Pars gas phases, are attracting modified contract terms that reward reservoir performance optimization beyond initial production targets.
After-sales service unbundling is fragmenting equipment procurement decisions from long-term maintenance contracts across Iranian oilfield service relationships. National Iranian Oil Company operating units are separating turbo-machinery and artificial lift system purchases from multi-year service agreements, enabling competitive tendering for specialized maintenance skills. This procurement model evolution is most visible at Marun and Ahvaz field operations, where electric submersible pump replacements are increasingly sourced through spot contracts rather than bundled original equipment manufacturer packages.
Iran Oil and Gas Market Segmentation
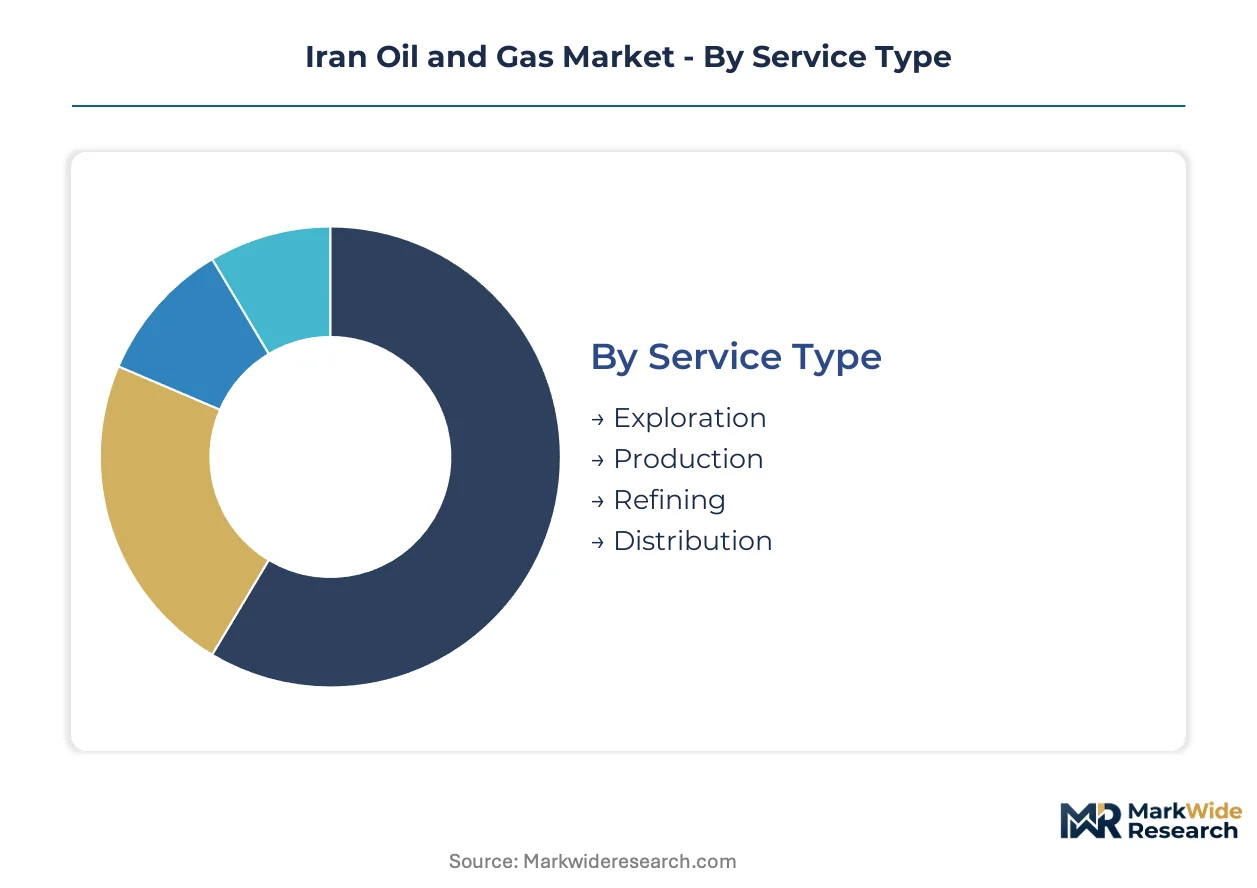
Segmentation of Iran's oil and gas market reveals how sanctions-induced supply chain fragmentation is redirecting capital toward domestically executable service categories. Each dimension exposes different pressure points where procurement constraints and technical capability gaps reshape competitive positioning.
Service Type:
Upstream service concentration in Ahvaz and Marun field districts is forcing operators to prioritize production maintenance over greenfield exploration.
- Exploration:Seismic surveying and wildcat drilling activities concentrate in the Zagros fold belt and Persian Gulf offshore blocks. The Petroleum Ministry's licensing rounds for Iranian Petroleum Contracts are attracting limited international participation due to banking restrictions, compressing exploration budgets toward state-funded programs.
- Production:Artificial lift operations and well workovers dominate capital deployment at National Iranian Oil Company mature fields. Electric submersible pump installations and gas lift system upgrades at Gachsaran and Aghajari reservoirs sustain plateau output without requiring subsea equipment imports.
- Refining:Distillation capacity expansion at Abadan and Isfahan complexes processes heavier crude fractions from onshore production. Domestic engineering firms are retrofitting atmospheric residue desulfurization units to handle declining API gravities from aging reservoirs.
- Distribution:Pipeline network integrity management and storage terminal operations span the Tehran-Isfahan product corridor. The National Iranian Oil Refining and Distribution Company maintains throughput despite sanctions-related difficulties in procuring corrosion monitoring equipment.
Today's leader: Production. Tomorrow's challenger: Distribution infrastructure modernization.
Technology:
Cost tier stratification separates capital-intensive deepwater development from deployable onshore enhancement techniques.
- Upstream:Platform construction and drilling operations at South Pars phases require specialized marine engineering capabilities. Qatar's adjacent North Field development patterns are informing well spacing optimization, though subsea completion technology remains import-dependent.
- Midstream:Gas processing and NGL extraction facilities at Asaluyeh convert associated gas into petrochemical feedstock streams. Pars Oil and Gas Company phases integrate dehydration, sweetening, and fractionation trains for methane through pentane recovery.
- Downstream:Catalytic reforming and hydrocracking units at Persian Gulf Petrochemical Industries Company complexes upgrade naphtha into aromatic and polymer precursors. Refinery-petrochemical integration captures margin pools unavailable to standalone fuel producers.
- Enhanced Oil Recovery:Thermal stimulation and miscible gas injection techniques target remaining oil saturation at depleted Asmari and Bangestan reservoirs. Carbon dioxide flooding pilots at Kirkuk-adjacent fields leverage naturally occurring CO2 from gas processing operations.
Upstream technology commands current investment. Enhanced Oil Recovery offers the steepest expansion trajectory as mature fields deplete.
End User:
Application volume concentrates in energy-intensive industrial corridors where fuel substitution options remain limited.
- Industrial:Steel, cement, and aluminum producers in Isfahan and Khuzestan provinces consume heavy fuel oil and natural gas for process heat. The Ministry of Industries, Mining and Trade enforces efficiency mandates that redirect some demand toward electricity where grid capacity permits.
- Power Generation:Combined cycle gas turbines at Shahid Rajaee and Fajr stations anchor baseload supply. Gas-to-wire installations at remote wellpads are displacing diesel generators for artificial lift power, reducing logistics burden.
- Petrochemical:Methanol, ammonia, and olefin producers at Asaluyeh and Mahshahr absorb associated gas volumes previously flared. Ethylene cracker expansions by Persian Gulf Petrochemical Industries Company redirect naphtha from gasoline blending to polymer production.
- Transportation:Compressed natural gas vehicle conversions and diesel substitution programs target urban air quality improvement. Tehran's municipal bus fleet and heavy trucking corridors along the Tehran-Bandar Abbas route represent concentrated demand nodes.
Petrochemical feedstock offtake leads volume absorption. Transportation fuel substitution presents the most policy-sensitive growth vector.
Application:
Margin maturity separates commoditized fuel markets from specialized chemical feedstock value chains.
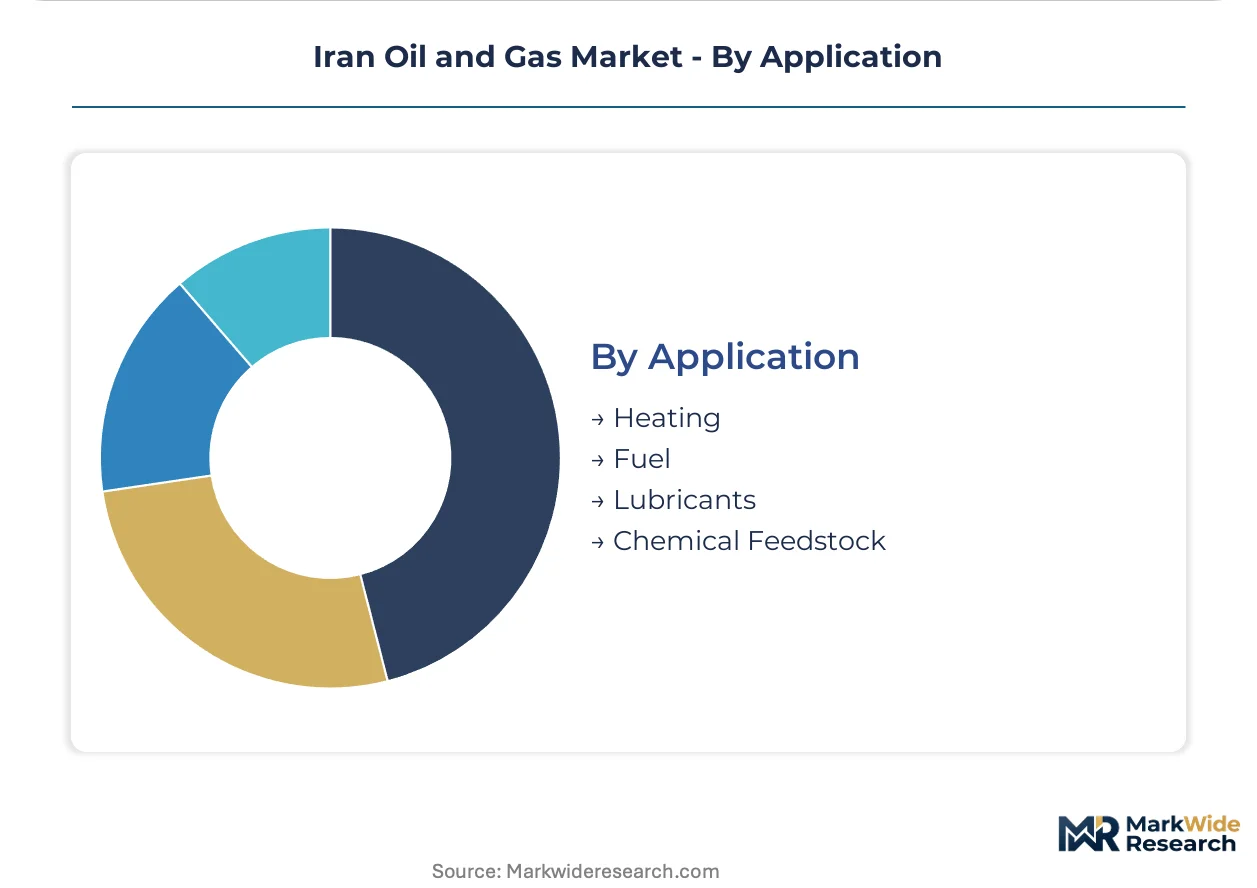
- Heating:Residential and commercial building stock in northern provinces relies on fuel oil and natural gas for winter thermal demand. Distribution infrastructure constraints in mountainous regions sustain kerosene markets despite pipeline expansion.
- Fuel:Gasoline, diesel, and fuel oil output from National Iranian Oil Refining and Distribution Company facilities serves domestic transportation and industrial energy demand. Product quality upgrades to Euro-4/5 specifications require hydrodesulfurization investments constrained by catalyst import restrictions.
- Lubricants:Base oil production at Abadan and Tehran refineries supplies blending operations for automotive and industrial applications. Group I base stock dominance reflects limited hydrocracker capacity for Group II/III upgrading.
- Chemical Feedstock:Naphtha, ethane, and propane streams feed aromatic complexes and steam crackers at Asaluyeh and Bandar Imam. Propylene and butadiene extraction from refinery off-gases supports synthetic rubber and polymer production.
Fuel applications dominate current throughput. Chemical feedstock conversion offers the fastest margin expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum engineering talent concentrates in Khuzestan province and the Asaluyeh corridor, anchoring field development capacity across Iran's hydrocarbon belt. Technical workforce migration patterns favor these zones over Tehran-based administrative centers.
Khuzestan Province
Artificial lift operations and thermal stimulation projects at Ahvaz and Marun fields absorb the majority of upstream maintenance budgets. The Petroleum Ministry's domestic content requirements under revised Iranian Petroleum Contracts mandate local fabrication partnerships for pump systems. Ahwaz city clusters house National Iranian Oil Company engineering units deploying electric submersible pumps across Asmari reservoir extensions.
Bushehr Province
South Pars gas field development phases drive specialized marine construction demand at Asaluyeh industrial port. Flaring reduction mandates from Iran's national environmental regulator enforce vapor recovery unit installation at gas processing trains. Pars Oil and Gas Company phases integrate dehydration and fractionation infrastructure along the Persian Gulf coastline.
Hormozgan Province
Refinery-petrochemical integration at Bandar Imam complexes redirects naphtha flows from fuel blending to aromatic production. The Ministry of Industries, Mining and Trade enforces efficiency mandates on steel and aluminum producers consuming heavy fuel oil. Bandar Abbas port infrastructure handles crude export logistics and catalyst import substitution challenges.
Tehran Province
Administrative control of buy-back contract negotiations and petroleum product distribution planning concentrates in the capital. National Iranian Oil Refining and Distribution Company headquarters manages the Tehran-Isfahan product corridor pipeline integrity. Research institutes in the metropolitan area coordinate enhanced oil recovery pilot designs for Kirkuk-adjacent carbon dioxide flooding projects.
Iran Oil and Gas Market Competitive Environment
Capital-heavy state producers compete with asset-light technical service specialists for field development contracts. The market structure consolidates around National Iranian Oil Company operating units and their captive engineering subsidiaries. Three archetypes dominate: integrated state operators controlling full value chains, petrochemical converters monetizing associated gas streams, and drilling service providers operating under buy-back terms. Competitive moves center on domestic fabrication partnerships and reservoir performance optimization bonuses.
Among state-integrated operators, National Iranian Oil Company and Pars Oil and Gas Company occupy positions defining upstream production benchmarks. Persian Gulf Petrochemical Industries Company exemplifies the downstream conversion archetype, anchoring methanol and olefin capacity at Asaluyeh. These entities represent the tier capturing margin through captive feedstock access and integrated infrastructure control.
| Leading Market Players |
|---|
| Petropars |
| Pars Oil and Gas Company |
| National Iranian Oil Company |
| Petroleum Engineering and Development Company |
| Iranians Offshore Oil Company |
| National Iranian Oil Refining and Distribution Company |
| Persian Gulf Petrochemical Industries Company |
| Naftan Company |
| National Iranian Gas Company |
| Others |
Value Chain & Pricing Dynamics
National Iranian Oil Company procurement officers concentrate demand for artificial lift systems and well workover services, anchoring contract-based long-term offtake agreements that bundle equipment supply with multi-year maintenance obligations under revised Iranian Petroleum Contract terms.
Pricing Analysis
Bundled original equipment manufacturer packages for electric submersible pumps and gas lift systems command premium positioning against unbundled spot-contract procurement that separates hardware purchase from specialized maintenance tendering. Price differentiation rests on domestic fabrication partnerships versus import-dependent subsea completion technology, with National Iranian Oil Company operating units showing acute sensitivity to upfront capital outlays while Pars Oil and Gas Company phases tolerate higher service premiums for reservoir performance optimization bonuses. Cost compression in standard-tier artificial lift procurement is intensifying because domestic engineering firms are expanding pump manufacturing capacity under Petroleum Ministry domestic content mandates. Margins are tightening for international service providers restricted from equity participation, forcing reliance on extended cost recovery periods through production allocations.
Supply Chain Analysis
Direct-to-field deployment channels handle artificial lift and gas processing equipment distribution from Khuzestan fabrication clusters to Ahvaz and Marun field locations, bypassing Tehran-based administrative intermediaries. Geographic supply concentration draws from China for subsea wellhead components, Germany for turbo-machinery packages, and domestic Iranian facilities for standard pump systems and pressure vessel fabrication. Raw material dependencies center on high-grade steel alloys for downhole equipment, specialized elastomers for seal assemblies, and sulfur recovery catalysts for gas processing trains. Single-source vulnerability runs through restricted subsea engineering expertise concentrated outside Iran, complicating knowledge transfer for deepwater completion design. Distribution runs through National Iranian Oil Company captive engineering subsidiaries and Pars Oil and Gas Company procurement divisions, with spot-contract tendering fragmenting aftermarket service relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Iran oil and gas market functions as a regulatory compounder where Petroleum Ministry flaring reduction mandates are accelerating vapor recovery unit installation and redirecting capital toward gas monetization infrastructure across Asaluyeh processing corridors.
For Market Incumbents: Anticipate intensifying competition from domestic fabrication partnerships as National Iranian Oil Company operating units unbundle equipment procurement from long-term service agreements. Defensive consolidation should prioritize backward integration into electric submersible pump manufacturing through joint ventures with Khuzestan-based engineering firms. Channel control over aftermarket maintenance relationships at Gachsaran and Aghajari reservoirs offers margin protection against spot-contract price erosion.
For New Entrants and Emerging Players: The premium-to-economy price gap in artificial lift services creates white-space opportunity for mid-tier domestic manufacturers offering standardized pump configurations without bundled OEM maintenance packages. Target distribution infrastructure modernization in the Tehran-Isfahan product corridor where National Iranian Oil Refining and Distribution Company faces corrosion monitoring equipment procurement constraints. Go-to-market positioning should emphasize rapid-response maintenance capabilities and domestic content compliance to qualify for Iranian Petroleum Contract eligibility.
For Investors and Strategic Acquirers: State-affiliated petrochemical conglomerates are the most active acquirer in this space, consolidating methanol and olefin capacity at Asaluyeh through captive feedstock integration. Long-term viability over a five-to-ten year window hinges on whether sanctions architecture loosens sufficiently to permit subsea equipment import substitution or domestic engineering capability closes the deepwater completion gap. Acquisition target archetypes include specialized maintenance contractors with established National Iranian Oil Company relationships and modular gas processing technology providers. The signal to watch is Qatar North Field drilling pattern coordination with South Pars phases, indicating potential for shared reservoir management technology transfer.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fabrication Partnership | Petroleum Ministry buy-back contract reforms mandate local content compliance for Iranian Petroleum Contract eligibility. |
| Enhanced Oil Recovery Deployment | Thermal stimulation and gas injection techniques at Asmari reservoirs extend plateau production without exploration exposure. |
| Flaring Reduction Infrastructure | Iran's national environmental regulator enforces vapor recovery unit installation at Asaluyeh gas processing trains. |
| Petrochemical Feedstock Pivot | Persian Gulf Petrochemical Industries Company redirects associated gas from power generation to methanol and olefin chains. |
| After-Sales Service Unbundling | National Iranian Oil Company separates turbo-machinery purchases from multi-year maintenance agreements enabling competitive tendering. |
Study Parameters
Multiple input streams — structured interviews with petroleum engineering directors, procurement leads at National Iranian Oil Company operating units, and regulatory affairs specialists at the Petroleum Ministry — were reconciled against secondary validation from customs records, Iranian Petroleum Contract disclosure filings, and gas processing facility environmental compliance reports. Bottom-up field development project inventories were triangulated with top-down hydrocarbon reserve estimates across the analysis window.
Historical production data from Ahvaz, Marun, and South Pars phases were cross-referenced against panel input from drilling contractors and artificial lift system providers to build the analytical framework. Segmentation dimensions modeled include service type, technology tier, end-use application, and regional production cluster. CAGRs were derived through regression analysis of capital deployment patterns and contract award timelines, with specific incorporation of sanctions-induced procurement delays and domestic content requirement phase-in schedules.
Caveats apply where sanctions architecture shifts, subsea equipment import restrictions, or reservoir performance variability could materially shift the outlook. Forecasts reflect assumptions regarding Qatar North Field coordination continuity and domestic fabrication capacity expansion rates. Periodic stress-testing of base assumptions is recommended against Petroleum Ministry contract reform implementation pace and environmental regulator enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Gulf of Mexico Oil and Gas Midstream Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Asia- Pacific Drilling Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
United States Wireline Logging Services Market