
 Drones for Oil & Gas Market | 2026-2036
Drones for Oil & Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Drones for Oil & Gas Market Insights
Aftermarket service revenue from drone-based inspection subscriptions is reshaping how oil and gas operators budget for asset integrity. DJI Enterprise leverages its manufacturing scale to dominate hardware supply for onshore deployments. Skydio Inc. differentiates through autonomous flight software that sustains operations in GPS-denied environments such as tank farms and processing facilities. Terra Drone Corporation anchors its position by controlling specialized pilot networks across North American shale plays.
Drones for oil and gas encompass unmanned aerial systems equipped with payloads including thermal cameras, gas analyzers, and LiDAR scanners, designed to execute remote visual and sensor-based inspection of hydrocarbon infrastructure without exposing personnel to hazardous conditions. Rotary-wing drones lead current deployments due to vertical takeoff capability and hover precision required for detailed flare stack and vessel examinations. Gas detection technology commands premium positioning as operators face tightening methane emission accountability, while pipeline inspection applications generate the most recurring flight-hour volume across major basins. Maintenance contractors represent a fast-growing end user category as outsourcing of drone operations accelerates among midstream and downstream operators seeking operational expenditure flexibility.
The FAA governs commercial drone operations through Part 107 certification and beyond-visual-line-of-sight waivers that determine where and how extensively oil and gas drones can deploy across US fields. The EPA's methane emission standards create direct regulatory pull for gas detection sensor integration, while OSHA workplace safety rules reinforce demand for remote inspection to reduce worker exposure at height and in confined spaces. Stakeholders must monitor evolving state-level privacy and airspace restrictions that could fragment operational permissions across multi-state pipeline networks.
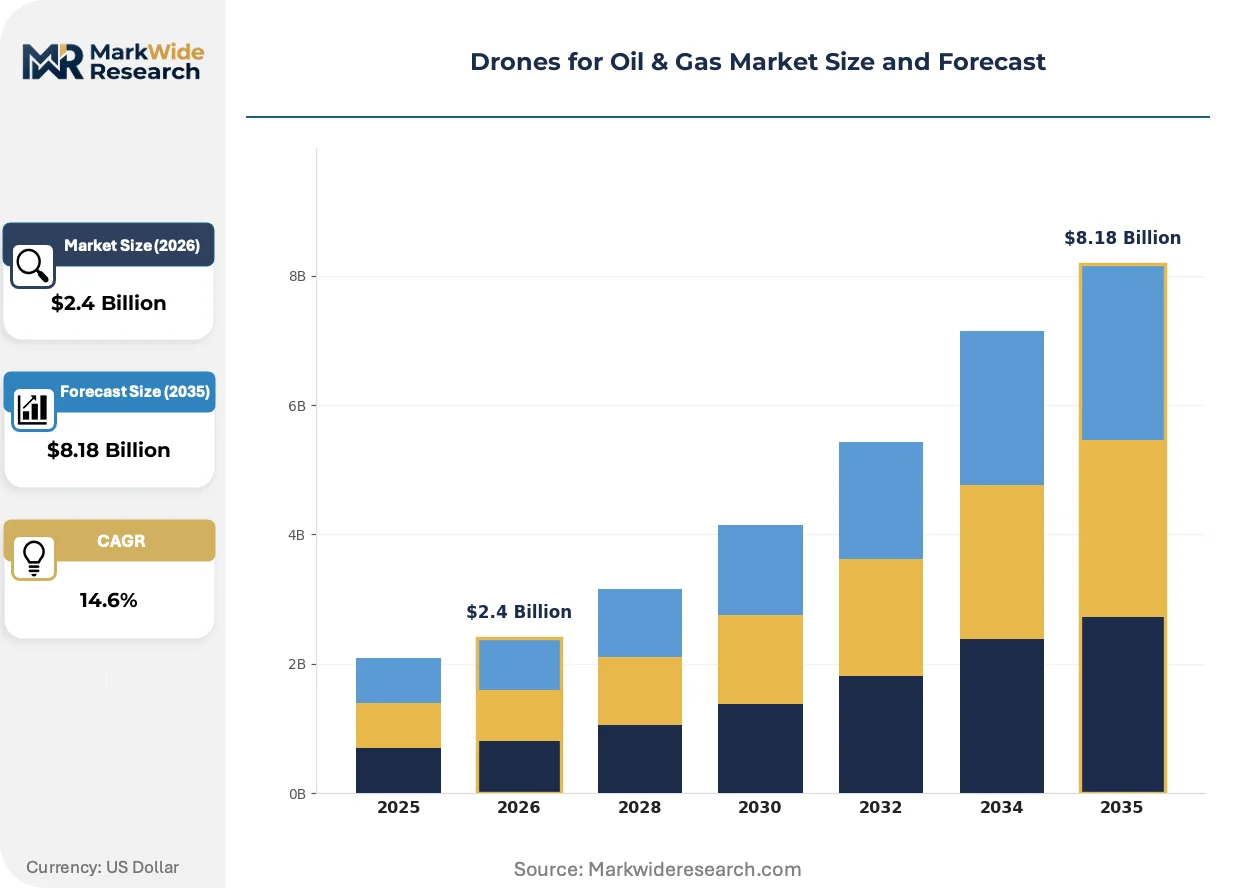
Market Dynamics
The convergence of FAA Part 107 waivers and EPA methane accountability rules is compressing procurement cycles for drone-based inspection platforms across upstream and midstream operations.
Growth Catalysts
- Beyond-visual-line-of-sight waivers:The FAA's BVLOS authorization framework expands operational range for pipeline surveillance across the Permian Basin and Appalachian shale corridors, unlocking recurring revenue models for inspection service providers.
- Methane emission standards:EPA leak detection mandates under Subpart W and OOOOb drive sensor payload upgrades, embedding gas analyzers as standard equipment on rotary-wing deployments.
- Offshore rig automation:North Sea and Gulf of Mexico operators are replacing manned helicopter inspections with autonomous drone fleets for flare stack and helideck examinations, reducing per-inspection costs and weather delays.
Market Restraints
- Sensor supply concentration:Thermal imaging and LiDAR component sourcing clusters in East Asian manufacturing hubs, exposing operators to lead-time volatility and tariff exposure.
- Airspace fragmentation:State-level privacy statutes and municipal drone ordinances create operational friction across multi-state pipeline networks, complicating route planning and pilot certification reciprocity.
- Battery energy density limits:Lithium-polymer chemistry constraints cap flight endurance at 45-60 minutes for heavy-payload missions, requiring frequent battery swaps or tethered alternatives for continuous monitoring.
Strategic Opportunities
- Digital twin integration:Convergence of photogrammetry software and asset management platforms enables predictive maintenance models that monetize inspection data beyond visual reports.
- Downstream facility penetration:Refineries and petrochemical complexes in Texas and Louisiana represent underpenetrated demand for confined-space drone entry, replacing rope-access technicians in tank and vessel inspections.
- Infrastructure Bill deployment:IRA and IIJA funding streams for methane mitigation create public-private partnership channels for drone-as-a-service vendors serving orphaned well remediation programs.
Industry Challenges
- Pilot certification bottlenecks:FAA Part 107 remote pilot throughput and specialized industrial training requirements lag fleet expansion timelines, constraining operational scaling for inspection contractors.
- Legacy SCADA integration:Proprietary data protocols in decades-old control systems complicate real-time sensor data ingestion, requiring middleware development that extends deployment timelines.
- Payload interoperability:Absence of universal mounting standards forces redundant hardware investments when operators switch between gas detection, thermal, and LiDAR configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drones for Oil & Gas Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Drones, Rotary-Wing Drones, Hybrid Drones, Micro Drones Technology: LiDAR, Thermal Imaging, Multispectral Sensors, Gas Detection, Visual Cameras Application: Pipeline Inspection, Well Monitoring, Site Surveillance, Environmental Monitoring End User: Exploration Companies, Production Facilities, Maintenance Contractors, Safety Inspection Teams |
| Companies Covered | DJI Enterprise, Skydio Inc., AeroVironment Inc., Flyability SA, Cyberhawk Innovations Limited, PrecisionHawk Inc., Terra Drone Corporation, Airobotics Ltd., Microdrones GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drones for Oil & Gas Market Trends and Innovations
Autonomous flight architectures and sensor fusion are compressing the gap between data capture and actionable intelligence, reshaping how operators budget for asset integrity programs.
Multi-sensor payload architectures are hybridizing thermal, hyperspectral, and methane-specific detection into single-flight operations. Midstream operators in the Permian Basin and Bakken formation are deploying these integrated systems at weekly intervals, collapsing what previously required three separate manned inspections into one autonomous sortie. This convergence is compressing inspection economics and accelerating subscription-based service adoption.
The EPA's supplemental methane proposal under the Clean Air Act is mandating quarterly leak surveys at compressor stations and wellheads. This regulatory compression forces upstream operators to abandon periodic manual surveys in favor of continuous or high-frequency drone monitoring. The Permian Basin and Denver-Julesburg shale plays are experiencing the fastest compliance-driven fleet expansions.
Service unbundling is fragmenting traditional inspection contracts. Midstream operators now separate hardware procurement from pilot services and data analytics, creating vendor-agnostic purchasing that privileges software platforms over airframe manufacturers. This disaggregation is most advanced among master limited partnerships in Texas and Oklahoma, where operational expenditure flexibility outweighs capital ownership preferences.
Drones for Oil & Gas Market Segmentation
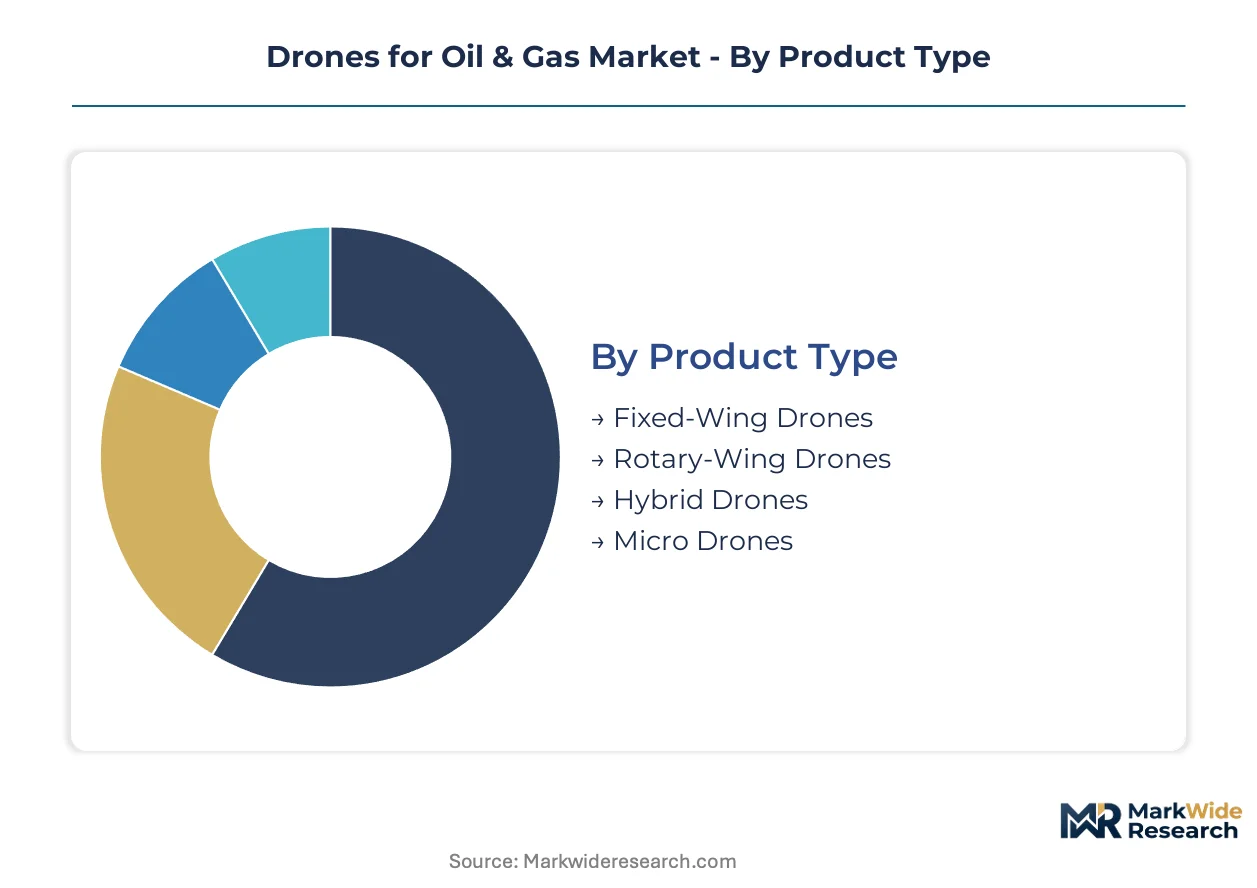
Segmentation in the Drones for Oil & Gas Market reveals how inspection economics vary sharply by flight platform, sensor payload, and contracting structure. Each dimension carries distinct aftermarket service intensity, from battery replacement cycles on rotary-wing fleets to calibration-heavy gas detection subscriptions.
Product Type:
After-sales intensity escalates with flight complexity and mission duration requirements across the four platform categories.
- Rotary-Wing Drones:Vertical takeoff and hover precision enable detailed flare stack and vessel examinations in congested facilities. Demand concentrates in the Permian Basin and Gulf Coast refineries, where OSHA height-work restrictions drive replacement of manned rope-access teams.
- Fixed-Wing Drones:Extended range and endurance suit linear pipeline surveillance across sparse terrain. Appalachian shale operators deploy these for right-of-way monitoring, though landing infrastructure requirements limit flexibility compared to rotary alternatives.
- Hybrid Drones:Combine VTOL convenience with fixed-wing efficiency for mid-range missions. North Sea offshore platforms favor these for helideck-to-stack transit routes.
- Micro Drones:Confined-space entry into storage tanks and processing vessels. Downstream operators in Texas and Louisiana use these for internal corrosion mapping where human entry poses atmospheric hazards.
By volume, Rotary-Wing Drones leads. By growth pace, Hybrid Drones is climbing the fastest as operators seek single-platform flexibility.
Technology:
Sensor payload selection directly determines recurring calibration revenue and data integration complexity for inspection service providers.
- Gas Detection:Tunable diode laser absorption spectroscopy and electrochemical arrays identify methane leaks at parts-per-million sensitivity. EPA Subpart W compliance deadlines in the Permian Basin and Bakken formation are embedding these as standard equipment on weekly inspection flights.
- Thermal Imaging:Infrared radiometry detects heat signatures indicating equipment stress, insulation failure, or flare inefficiency. Gulf of Mexico offshore operators prioritize these for 24/7 automated monitoring of unmanned platforms.
- LiDAR:Laser scanning generates centimeter-accurate digital elevation models for terrain change detection and encroachment monitoring. Midstream pipeline operators use these for volumetric analysis of ground subsidence near underground storage caverns.
- Multispectral Sensors:Vegetation stress indices reveal pipeline coating degradation and hydrocarbon soil contamination. Environmental remediation contractors deploy these for post-spill monitoring in the Denver-Julesburg shale play.
- Visual Cameras:High-resolution RGB imaging remains the baseline for general condition assessment and regulatory documentation. Maintenance contractors bundle these with other sensors or offer as standalone rapid-response service.
By installed base, Visual Cameras dominates. By expansion trajectory, Gas Detection is gaining share fastest as methane accountability tightens.
Application:
Mission type shapes procurement frequency, with recurring surveillance contracts generating steadier service revenue than episodic emergency response.
- Pipeline Inspection:Automated right-of-way surveillance detects third-party encroachment, corrosion, and leaks across thousands of linear miles. Master limited partnerships in Texas and Oklahoma are shifting from quarterly manned patrols to weekly drone subscriptions.
- Site Surveillance:Perimeter security and equipment monitoring at well pads, compressor stations, and tank farms. Bakken operators deploy these for theft deterrence and remote facility oversight where staffing costs exceed automation investment.
- Well Monitoring:Individual wellhead condition assessment and production optimization support. Smaller upstream operators use these to extend well life without dedicated field personnel.
- Environmental Monitoring:Spill detection, habitat disturbance assessment, and remediation verification. Public-private partnerships for orphaned well cleanup in Appalachia are creating demand for these specialized flight services.
By flight hours, Pipeline Inspection leads. By contract growth, Site Surveillance is expanding most quickly as midstream operators consolidate facility security spending.
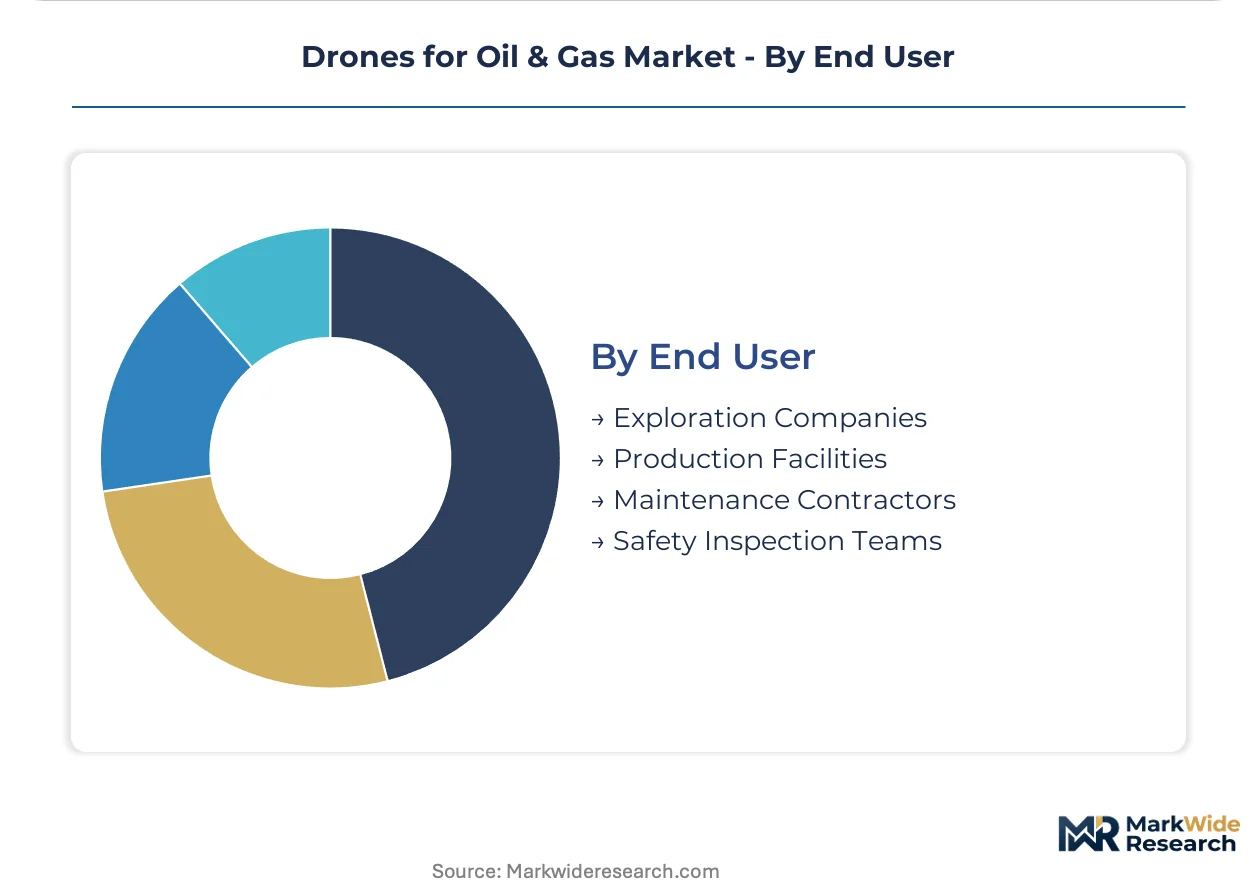
End User:
Contracting structure diverges sharply between capital-owning operators and outsourced service recipients, with implications for hardware-versus-software vendor selection.
- Maintenance Contractors:Third-party inspection specialists operating multi-client drone fleets under recurring service agreements. These vendors are capturing share fastest among midstream and downstream operators seeking operational expenditure flexibility without pilot certification burden.
- Production Facilities:Refineries, gas processing plants, and terminal operators with in-house drone programs. Texas and Louisiana petrochemical complexes are building captive capabilities for confined-space and hazardous area entry.
- Exploration Companies:Upstream operators focused on seismic survey support and greenfield site assessment. These users prioritize portability and rapid deployment over sensor sophistication.
- Safety Inspection Teams:Corporate safety departments using drones for incident response and regulatory documentation. These groups often operate under centralized procurement with standardized airframe and training requirements.
By fleet ownership, Production Facilities leads. By contract velocity, Maintenance Contractors is advancing the fastest as outsourcing accelerates across the shale patch.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: North American operators prioritize methane compliance automation, while Middle Eastern deployments emphasize offshore platform safety, and European markets stress environmental remediation integration.
United States
FAA Part 107 waivers and EPA Subpart W mandates compress procurement cycles for Permian Basin operators. The IRA's methane mitigation funding channels accelerate drone-as-a-service adoption for orphaned well remediation. Texas and New Mexico shale plays generate the densest pipeline inspection flight-hour volumes globally.
United Arab Emirates
Offshore rig automation in the Arabian Gulf drives demand for autonomous flare stack and helideck examination systems. ADNOC's digital transformation programs embed drone fleets into unmanned platform operations. Dubai-based service providers coordinate multi-rig inspection networks across Upper Zakum and Lower Zakum fields.
Norway
North Sea operators replace manned helicopter inspections with autonomous systems to reduce weather delays and carbon emissions. The Norwegian Petroleum Safety Authority's remote inspection guidelines accelerate platform certification timelines. Stavanger-clustered service vendors specialize in GPS-denied navigation for offshore jacket structures.
China
National oil companies deploy drones for pipeline surveillance across Xinjiang and Sichuan shale corridors under MEE emission monitoring directives. Domestic manufacturing scale drives cost compression for thermal and gas detection payloads. Shenzhen-based hardware suppliers anchor supply chains for onshore field operations.
Saudi Arabia
Aramco's unmanned facility initiatives expand drone fleets for critical infrastructure protection across the Eastern Province. The kingdom's dual carbon goals elevate methane leak detection to strategic priority status. Dhahran-Riyadh corridor operators integrate inspection data with predictive maintenance platforms.
Drones for Oil & Gas Market Competitive Landscape
Capability concentration sits with specialized autonomy software developers; scale advantage sits with integrated hardware manufacturers. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive drone divisions, pure-play aerial platform specialists, and inspection service operators controlling pilot networks. Dominant competitive moves include sensor payload integration partnerships and geographic expansion through pilot certification reciprocity agreements.
Among autonomy-focused developers, Skydio Inc. and Flyability SA exemplify the software-differentiated archetype, with the former representing GPS-denied navigation specialists and the latter occupying a position in confined-space entry systems. DJI Enterprise anchors the manufacturing-scale tier, while Terra Drone Corporation sits within the service-network control segment. These three patterns—software differentiation, manufacturing scale, and pilot network density—define competitive positioning across upstream and midstream procurement decisions.
| Leading Market Players |
|---|
| DJI Enterprise |
| Skydio Inc. |
| AeroVironment Inc. |
| Flyability SA |
| Cyberhawk Innovations Limited |
| PrecisionHawk Inc. |
| Terra Drone Corporation |
| Airobotics Ltd. |
| Microdrones GmbH |
| Others |
Pricing and Supply Chain Analysis
East Asian thermal imaging and LiDAR component manufacturing concentrates upstream supply for drone sensor payloads, anchoring margin pools with inspection service providers who bundle calibration subscriptions and data analytics downstream.
Pricing Analysis
Long-term subscription contracts dominate procurement for recurring pipeline surveillance, while project-based spot pricing persists for emergency response deployments. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified BVLOS operations from visual-line-of-sight flights and basic RGB documentation. Cost compression in standard-tier hardware is intensifying because Shenzhen-based manufacturers scale thermal and gas detection payload production. Maintenance contractors exhibit highest price sensitivity due to thin margins on multi-client fleet operations, whereas offshore rig operators demonstrate lowest sensitivity given helicopter replacement economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for oil and gas drone operators sourcing LiDAR scanners and lithium-polymer batteries. Component manufacturing concentrates in China, South Korea, and Japan, with final assembly drawing from Taiwan and Vietnam for certain flight controllers. Raw material dependencies span rare earth magnets for brushless motors, gallium arsenide for thermal sensors, and cobalt-nickel cathode formulations. Distribution runs through authorized dealer networks for hardware and direct SaaS platforms for flight planning and data analytics software.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
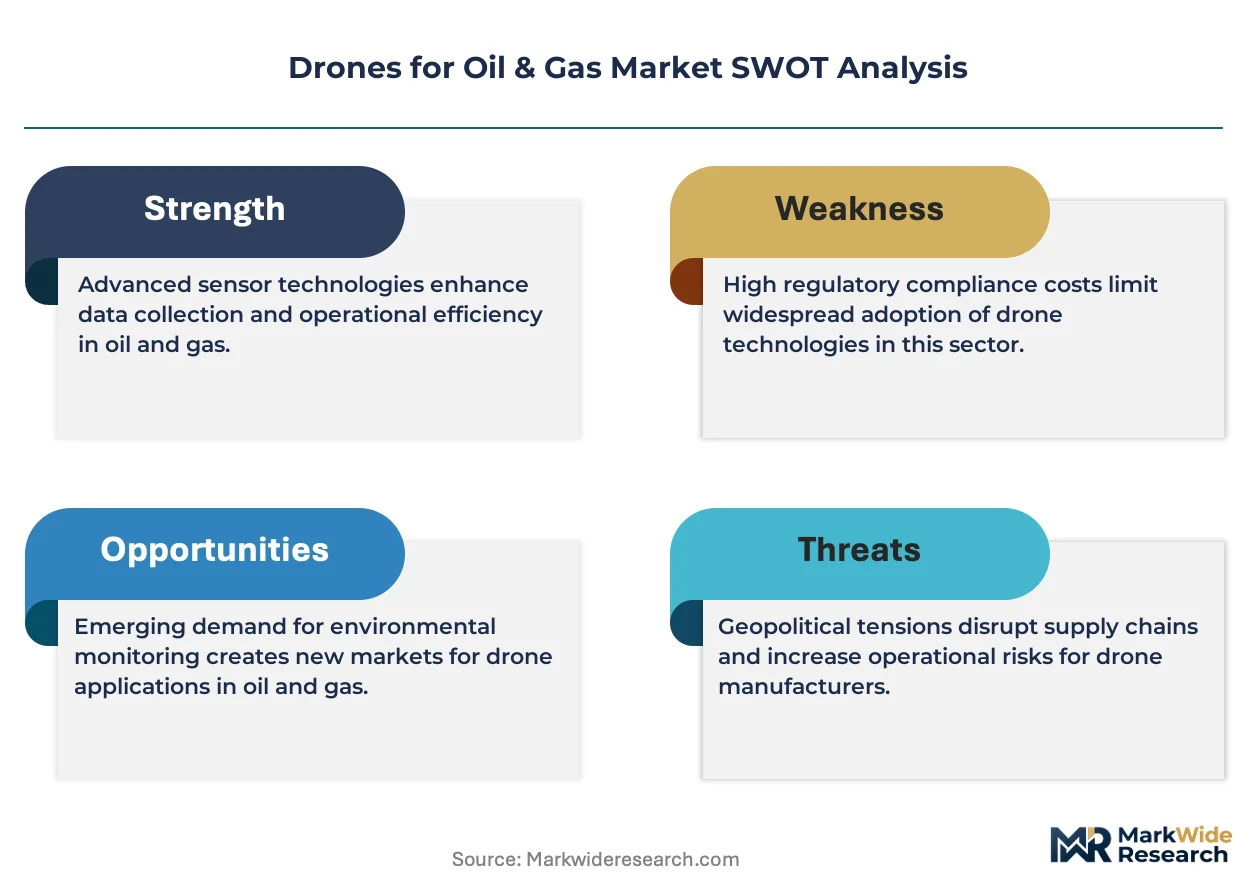
Regulatory fragmentation across FAA, EPA, and state-level airspace rules creates vendor-agnostic procurement niches, fragmenting what consolidated hardware supply chains would otherwise capture.
For Market Incumbents: Entrench position by deepening pilot certification reciprocity agreements across the Permian Basin and Appalachian shale corridors, countering emerging service-network competitors. Lock in multi-year sensor calibration subscriptions before EPA methane accountability deadlines force hardware refresh cycles. Vertical integration into predictive maintenance software platforms defends against software-differentiated entrants unbundling inspection data from flight services. For New Entrants and Emerging Players: Pursue confined-space entry contracts at Texas and Louisiana petrochemical complexes, the most penetrable segment given OSHA height-work restrictions and rope-access technician shortages. Target orphaned well remediation programs funded by IRA methane mitigation streams, where public-private partnership structures lower customer acquisition barriers. Lead with drone-as-a-service offerings that eliminate capital ownership burdens for midstream master limited partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed inspection service operators controlling dense pilot networks across North American shale plays. Five-to-ten year viability hinges on software platform stickiness transcending hardware commoditization. Watch FAA BVLOS waiver approval velocity as the inflection signal indicating scalable operational expansion for portfolio companies.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Payload Integration Partnership | Gas detection-thermal-LiDAR fusion collapses three manned inspections into single autonomous sorties for Permian operators. |
| Pilot Certification Reciprocity Expansion | Multi-state license portability reduces operational friction across Texas-New Mexico pipeline networks under FAA Part 107. |
| Predictive Maintenance Platform Development | Digital twin integration monetizes inspection data beyond visual reports for midstream asset integrity programs. |
| Orphaned Well Remediation Service Launch | IRA funding channels create public-private partnership entry points for drone-as-a-service vendors in Appalachia. |
| Confined-Space Entry System Certification | Micro-drone tank inspections replace rope-access teams at OSHA-regulated Gulf Coast refineries and processing facilities. |
Research Methodology
The analysis maps rotary-wing, fixed-wing, hybrid, and micro-drone platforms, each validated through flight operations managers at midstream operators, FAA-certified remote pilots, sensor payload engineers, and inspection service procurement leads. Primary interviews combined with secondary validation against FAA Part 107 waiver databases, EPA Subpart W compliance filings, SEC 10-K disclosures from publicly traded energy infrastructure firms, and customs records for thermal imaging component imports. Bottom-up triangulation across fleet deployment counts and top-down reconciliation against operator capital expenditure disclosures anchored volume estimates.
Assumptions held fixed include current FAA BVLOS authorization timelines and EPA methane detection regulatory stringency, while oil price volatility and lithium battery chemistry breakthroughs were treated as scenario variables. Segmentation dimensions modeled span flight platform type, sensor payload technology, application mission profile, end-user contracting structure, and regional regulatory cluster. CAGRs were derived from logistic adoption curves fitted to operator fleet expansion announcements and service provider contract win disclosures across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in North American shale drilling activity, offshore rig utilization rates, or lithium raw material pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and sensor cost decline curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Injection Well Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Coal Seam Gas Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
United States Coiled Tubing Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Oil and Gas Pipe Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
US Sand Control Systems Market