
 Middle-East Oil Country Tubular Goods (OCTG) Market | 2026-2036
Middle-East Oil Country Tubular Goods (OCTG) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East Oil Country Tubular Goods (OCTG) Market Foresight
Software-defined predictive maintenance contracts for tubular integrity is realigning how operators procure OCTG across the Middle East. Tenaris SA leverages its threading technology platform to anchor long-term service agreements with national oil companies. Vallourec SA specializes in premium connection systems that differentiate its offering in high-pressure sour gas environments. National-Oilwell Varco Inc competes through integrated supply chain control spanning inspection, repair, and redeployment services.
Oil Country Tubular Goods encompass seamless and welded steel pipes manufactured to API 5CT specifications, with wall thicknesses engineered to withstand downhole pressures exceeding 15,000 psi during drilling and hydrocarbon extraction. These tubulars form the structural backbone of wellbore architecture, isolating formation fluids and enabling controlled production flow from reservoir to surface. Casing segments dominate capital allocation across Middle Eastern fields due to deep well architectures and corrosive reservoir chemistries. Alloy steel grades represent the fastest-expanding material category as operators push into sour service conditions requiring chromium-molybdenum compositions. Oil exploration end-use commands the highest specification intensity, though gas exploration applications are gaining traction in Qatar and Saudi Arabia's unconventional shale programs.
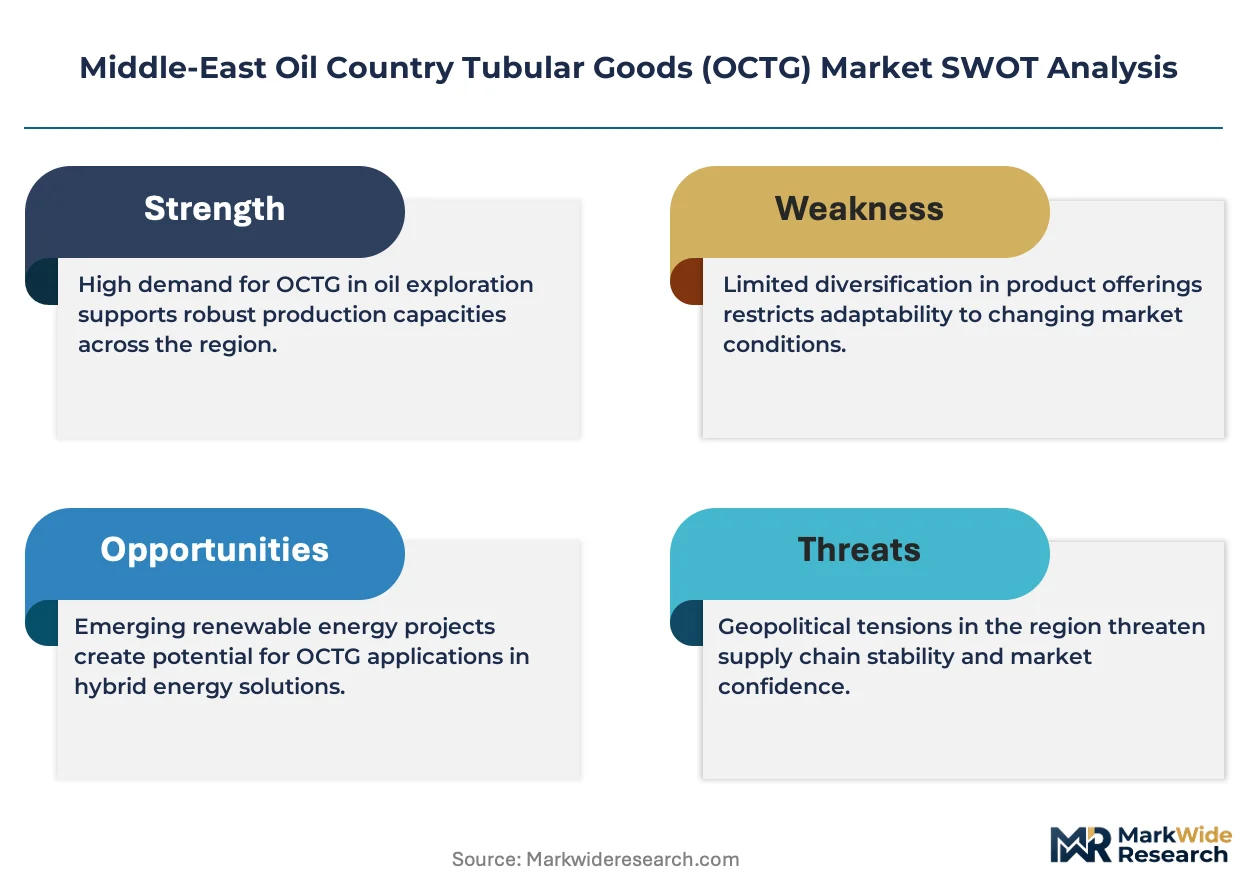
API 5CT standards enforced by Saudi Aramco's engineering specifications and ADNOC's technical integrity frameworks govern product qualification across Gulf markets. The UAE's Emirates Authority for Standardization and Metrology implements supplementary testing protocols for hydrogen-induced cracking resistance in offshore applications. SFDA and MOHAP industrial safety mandates in Saudi Arabia and the UAE respectively extend traceability requirements from mill to wellhead installation. Stakeholders must monitor how national content regulations and local manufacturing incentives reshape supplier qualification criteria across the Gulf Cooperation Council.
Market Dynamics
Deep sour-service well programs across Saudi Arabia and Qatar are compressing material qualification timelines while expanding chromium-molybdenum alloy procurement volumes beyond conventional carbon steel baselines.
Growth Catalysts
- North Field expansion phases:QatarEnergy's multi-phase gas development is generating sustained casing and tubing demand for high-pressure reservoir conditions. Procurement cycles now span decade-long horizons.
- API 5CT specification upgrades:Tighter material standards for hydrogen-induced cracking resistance are filtering supplier pools across Gulf Cooperation Council states. Qualification barriers favor integrated manufacturers.
- Unconventional shale pilots:Saudi Aramco's Jafurah basin development is introducing horizontal drilling intensity previously unseen in Middle Eastern conventional fields. Premium connection systems face expanded deployment.
Market Restraints
- Alloy feedstock concentration:Chromium and molybdenum supply chains concentrate in limited metallurgical processing jurisdictions outside the Middle East. Price volatility transmits directly to tubular manufacturing costs.
- Mill capacity bottlenecks:Seamless pipe production for sour-service grades requires specialized rolling equipment concentrated among a handful of qualified facilities. Lead times extend during demand surges.
- SFDA traceability mandates:Saudi Arabia's industrial safety authority imposes documentation requirements from raw material source through wellhead installation. Compliance overhead compresses margin structures for distributors.
Strategic Opportunities
- UAE offshore frontier:ADNOC's Upper Zakum and Lower Zakum redevelopment programs are expanding subsea tieback architectures requiring corrosion-resistant alloy tubulars. Water depth thresholds are rising.
- Predictive maintenance integration:Software-defined integrity monitoring is converging with threading technology platforms to create bundled service offerings. Equipment utilization data is becoming a contract anchor.
- Local manufacturing incentives:Gulf Cooperation Council national content regulations are creating qualification preferences for in-region finishing and inspection facilities. Joint venture structures are proliferating.
Industry Challenges
- Sour-service metallurgy expertise:Chromium-molybdenum grade selection and heat treatment protocols require specialized engineering talent scarce across regional oilfield service workforces. Training pipelines lag deployment needs.
- Multi-standard certification overlap:ADNOC technical integrity frameworks, Saudi Aramco engineering specifications, and Emirates Authority for Standardization protocols create redundant testing requirements. Approval timelines extend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East Oil Country Tubular Goods (OCTG) Market |
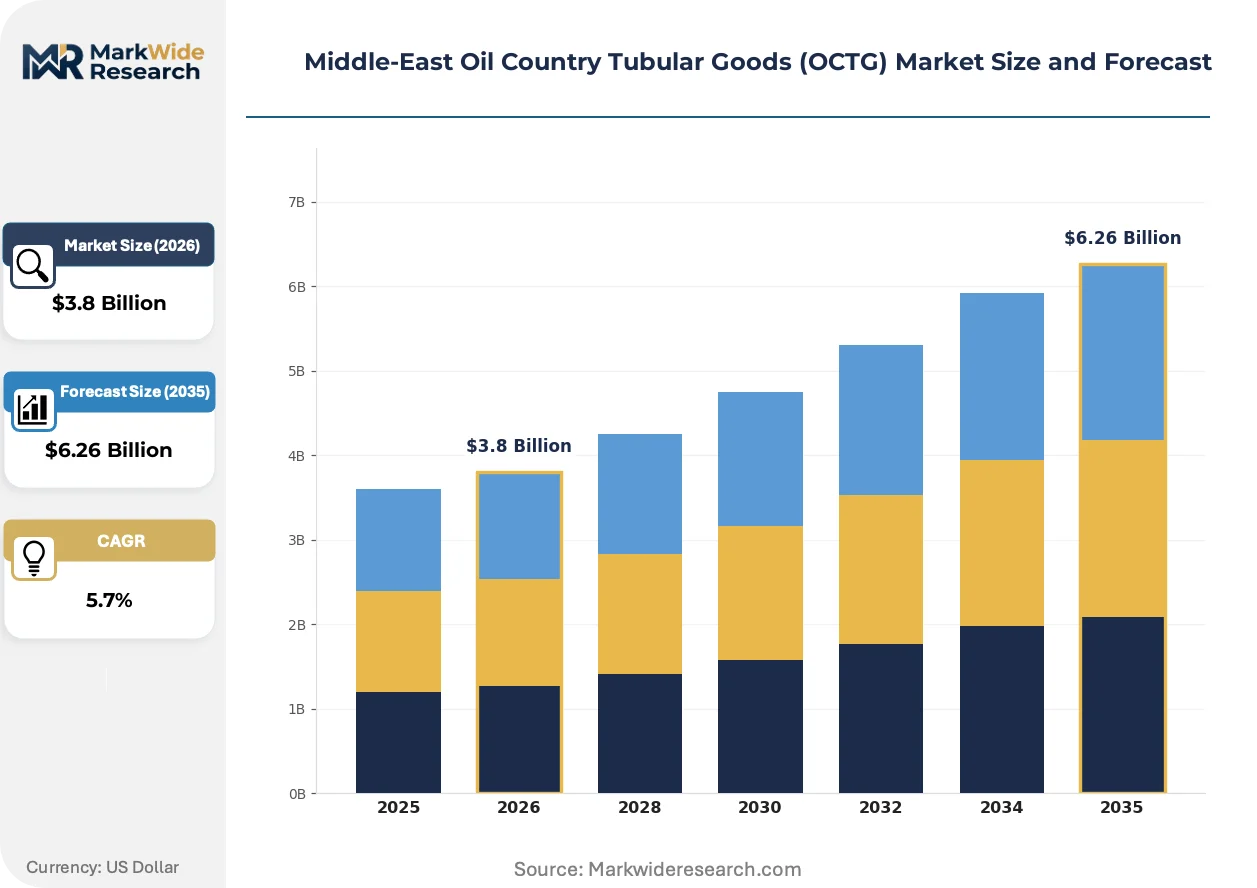
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drill Pipe, Casing, Tubing, Line Pipe Material: Carbon Steel, Alloy Steel, Stainless Steel, Others End User: Oil Exploration, Oil Production, Gas Exploration, Construction Manufacturing Stage: Raw Material, Intermediate, Finished Product, Assembly |
| Companies Covered | National-Oilwell Varco Inc, Nippon Steel Corporation, Tenaris SA, ArcelorMittal SA, Vallourec SA, ILJIN Steel Co., TPCO Enterprise Inc., U.S. Steel Tubular Products Inc., Halima Pipe Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East Oil Country Tubular Goods (OCTG) Market Shifts & Advancements
Premium connection systems and digital integrity platforms are converging to redefine how national oil companies contract for tubular lifecycle performance rather than discrete product procurement.
Chromium-molybdenum alloy compositions are consolidating market position as the baseline material for sour-service applications across Qatar's North Field and Saudi Arabia's unconventional shale programs. ADNOC and QatarEnergy procurement specifications now mandate these grades for reservoir conditions exceeding specified hydrogen sulfide thresholds. The shift is consolidating procurement volume among suppliers with captive metallurgical capabilities and integrated threading operations.
Emirates Authority for Standardization and Metrology supplementary testing protocols for hydrogen-induced cracking resistance are tightening product qualification for UAE offshore applications. Manufacturers must now demonstrate performance across extended exposure simulations before platform deployment. Premium connection specialists with established UAE technical service presence are capturing disproportionate share of subsea project awards.
Service contract unbundling is fragmenting traditional supply arrangements as operators separate tubular procurement from inspection, repair, and redeployment functions. National oil companies in Saudi Arabia and Qatar now tender integrity management independently of initial material purchase. This restructuring is compressing margins for distributors while expanding addressable market for specialized technical service providers with regional facility networks.
Middle-East Oil Country Tubular Goods (OCTG) Market Segmentation
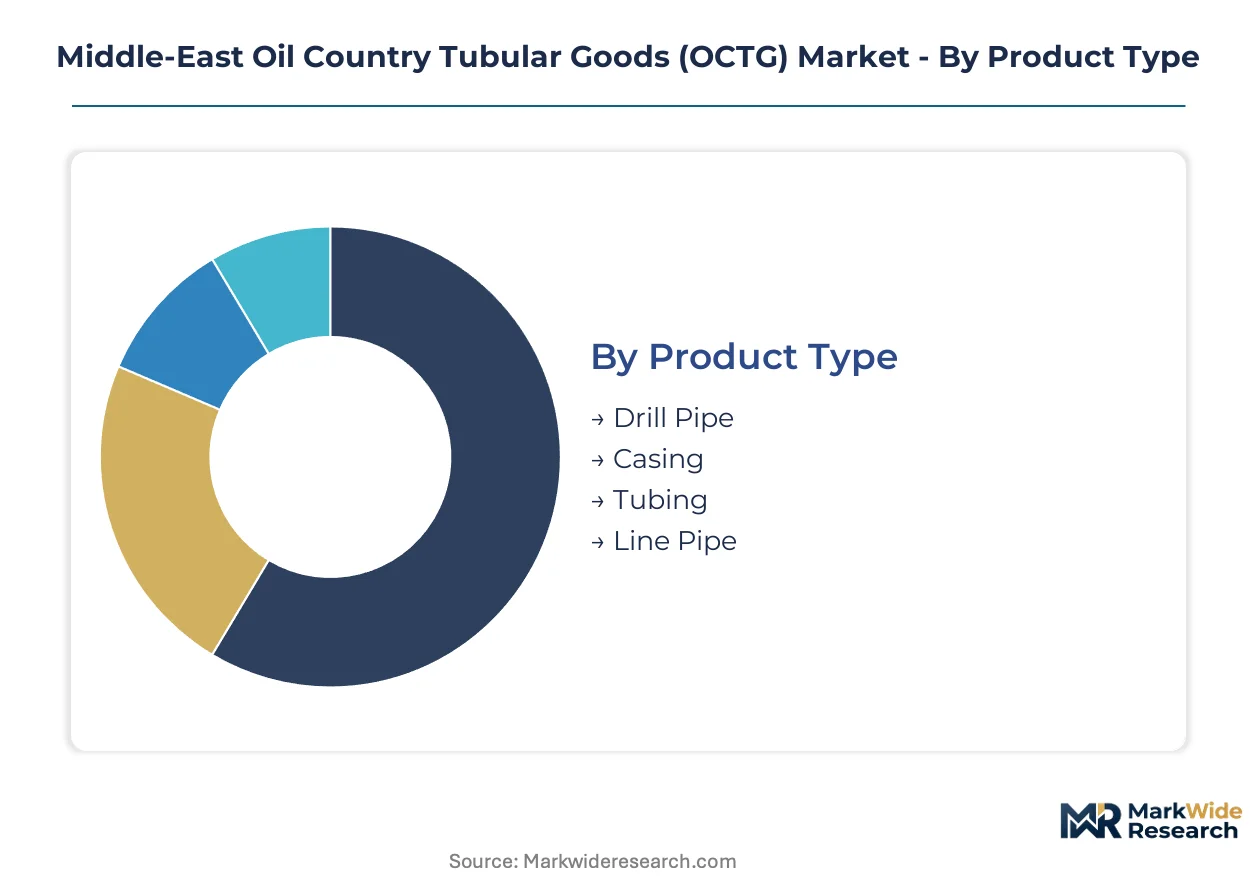
OCTG procurement patterns diverge sharply across product categories and material grades. Saudi Aramco and QatarEnergy tender specifications create tiered demand profiles that reshape supplier qualification requirements.
Product Type:
Supply concentration among seamless pipe mills favors integrated manufacturers with captive threading capacity.
- Casing:Thick-walled tubulars engineered for structural wellbore integrity withstand formation pressures exceeding 15,000 psi. Saudi Arabia's onshore megaprojects and Qatar's North Field expansion absorb the majority of regional procurement volume, driven by deep sour-service architectures requiring chromium-molybdenum compositions.
- Tubing:Production conduit installed inside casing strings enables controlled hydrocarbon flow from reservoir to surface. Horizontal drilling intensity in Saudi Aramco's Jafurah unconventional pilots is expanding premium connection deployment for tubing strings.
- Drill Pipe:Heavy-walled tubulars transmit rotational torque and drilling fluid during well construction. ADNOC's Upper Zakum redevelopment generates concentrated demand for high-torque grades.
- Line Pipe:Surface and subsea pipeline infrastructure connects wellhead facilities to processing infrastructure. UAE offshore water depth thresholds are rising for corrosion-resistant alloy specifications.
Casing absorbs the bulk of installed capacity; tubing is expanding most quickly.
Material:
Cost tier stratification separates commodity carbon grades from premium alloy specifications with metallurgical complexity premiums.
- Alloy Steel:Chromium-molybdenum compositions dominate sour-service applications across Qatar's North Field and Saudi Arabia's unconventional programs. Heat treatment protocols require specialized engineering talent scarce across regional workforces.
- Carbon Steel:API 5CT standard grades serve conventional reservoir conditions with limited hydrogen sulfide exposure. Baseline procurement for mature field workovers concentrates in Saudi Arabia's Ghawar and Safaniya complexes.
- Stainless Steel:Corrosion-resistant grades address extreme chloride environments in UAE offshore subsea tiebacks. Emirates Authority for Standardization and Metrology protocols mandate supplementary hydrogen-induced cracking testing.
- Others:Specialized metallurgical formulations including duplex and super-duplex stainless address niche high-pressure high-temperature applications.
Alloy steel commands the steepest expansion trajectory; carbon steel retains volume leadership in mature basins.
End User:
Application intensity varies by drilling program type and reservoir chemistry complexity.
- Oil Exploration:Wildcat and appraisal drilling commands the highest specification intensity for premium connection systems. Saudi Aramco's Red Sea frontier exploration drives procurement of sour-service qualified tubulars.
- Gas Exploration:QatarEnergy's North Field expansion phases generate decade-long procurement horizons for high-pressure casing strings. Hydrogen sulfide thresholds mandate chromium-molybdenum baseline specifications.
- Oil Production:Mature field workovers and infill drilling sustain steady demand for standard API grades. Artificial lift installations require specialized tubing metallurgy.
- Construction:Pipeline infrastructure and facility construction consumes line pipe volumes outside wellbore applications. UAE offshore platform fabrication generates intermittent large-diameter orders.
Oil exploration absorbs the bulk of premium alloy procurement; gas exploration is gaining share fastest.
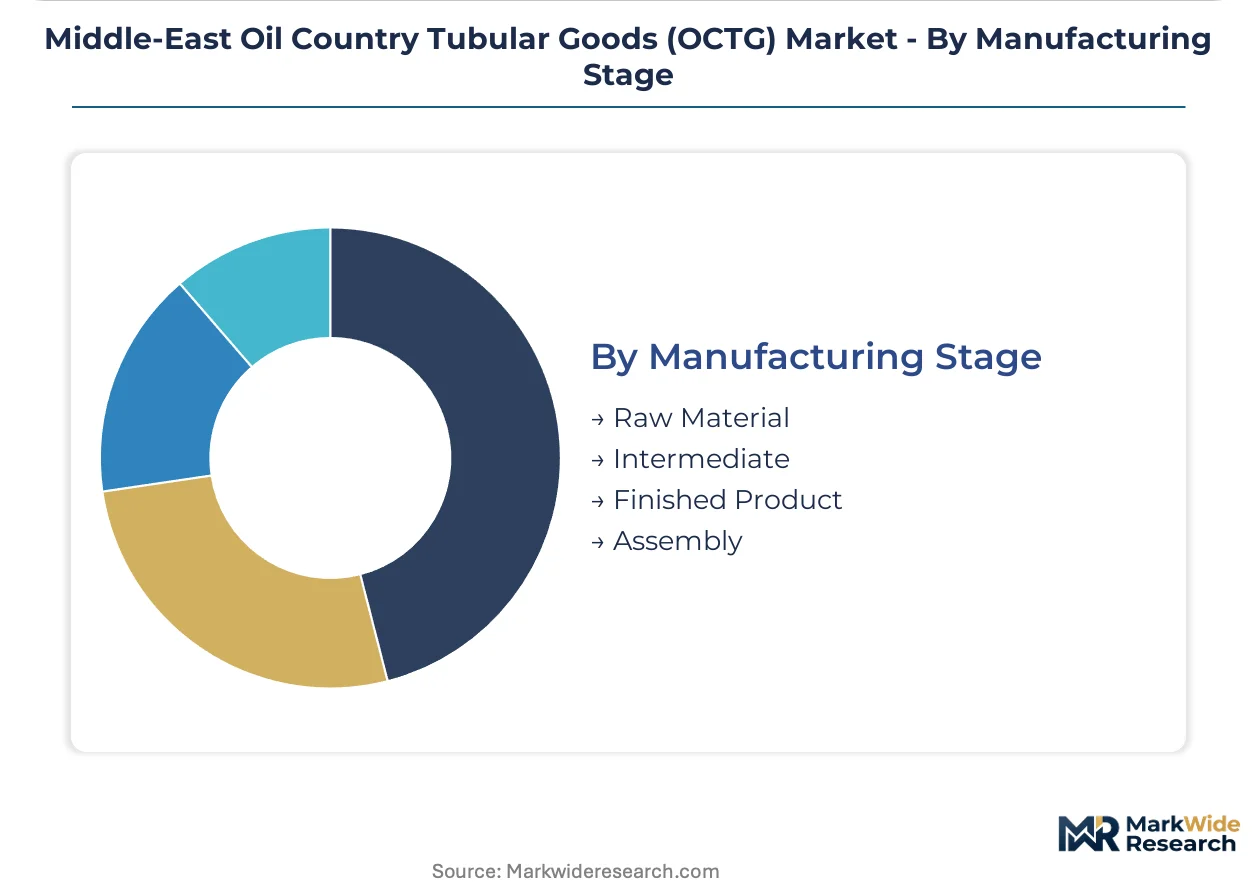
Manufacturing Stage:
Customer type separation distinguishes integrated national oil company tenders from distributor-mediated procurement.
- Finished Product:Mill-delivered threaded and inspected tubulars ready for wellhead installation. Saudi Aramco engineering specifications and ADNOC technical integrity frameworks govern qualification.
- Raw Material:Billet and slab supply to regional finishing facilities. Chromium and molybdenum feedstock concentration outside the Middle East transmits price volatility.
- Intermediate:Unthreaded seamless pipe requiring downstream heat treatment and connection machining. Mill capacity bottlenecks concentrate among qualified sour-service facilities.
- Assembly:Downhole tool integration and accessory packaging for specific well architectures. Local manufacturing incentives under Gulf Cooperation Council national content regulations reshape supplier structures.
Finished product captures the bulk of contract value; intermediate processing is expanding most quickly under localization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dammam's industrial corridor anchors Middle Eastern OCTG demand through Saudi Aramco's procurement headquarters and seamless pipe finishing facilities serving Ghawar and Jafurah basins.
Saudi Arabia
Jafurah unconventional shale pilots and Red Sea frontier exploration drive premium connection demand for horizontal drilling architectures. SFDA traceability mandates from raw material source through wellhead installation compress distributor margin structures. Dammam's King Abdulaziz Port clusters inspection and threading facilities under national content localization incentives.
United Arab Emirates
ADNOC's Upper Zakum and Lower Zakum redevelopment programs expand subsea tieback architectures requiring corrosion-resistant alloy tubulars. Emirates Authority for Standardization and Metrology protocols mandate supplementary hydrogen-induced cracking testing for offshore qualification. Abu Dhabi's industrial free zones concentrate premium connection specialists with established technical service presence.
Qatar
QatarEnergy's North Field expansion phases generate decade-long procurement horizons for high-pressure sour-service casing strings. Hydrogen sulfide thresholds in reservoir specifications mandate chromium-molybdenum baseline compositions. Ras Laffan's industrial city hosts specialized heat treatment facilities serving offshore platform fabrication.
Kuwait
Heavy oil development in northern fields sustains demand for thick-walled casing segments engineered for thermal recovery pressures. Kuwait Petroleum Corporation specifications align with API 5CT upgrades filtering regional supplier pools. Al-Ahmadi's oil sector concentration supports logistics networks for mill-to-wellhead traceability compliance.
Oman
Enhanced oil recovery programs in mature carbonate fields sustain steady tubing replacement cycles for artificial lift installations. Petroleum Development Oman technical standards emphasize sour-service qualification for deep gas exploration. Sohar's port and industrial zone facilitates intermediate processing of seamless pipe for regional redistribution.
Middle-East Oil Country Tubular Goods (OCTG) Market Competitive Landscape
Capital-heavy integrated mills compete with asset-light threading specialists and regional distributors for procurement share across Gulf national oil companies. Market structure concentrates seamless pipe supply among qualified sour-service facilities with captive metallurgical capabilities, while downstream inspection and repair functions fragment across specialized service providers. Strategic archetypes separate integrated manufacturers with full metallurgical control, premium connection specialists licensing proprietary thread designs, and regional distributors managing logistics and traceability compliance. Dominant competitive moves include joint venture structures under national content regulations and long-term service agreements bundling tubular supply with integrity monitoring platforms.
Among integrated manufacturers with established Gulf presence, Tenaris SA and Vallourec SA exemplify archetypes threading technology platforms into lifecycle service contracts, while National-Oilwell Varco Inc represents the integrated supply chain control model spanning inspection, repair, and redeployment functions. These three occupy positions where qualification barriers favor established technical service networks and captive metallurgical processing capabilities over commodity distribution models.
| Leading Market Players |
|---|
| National-Oilwell Varco Inc |
| Nippon Steel Corporation |
| Tenaris SA |
| ArcelorMittal SA |
| Vallourec SA |
| ILJIN Steel Co. |
| TPCO Enterprise Inc. |
| U.S. Steel Tubular Products Inc. |
| Halima Pipe Company |
| Others |
Supply & Pricing Matrix
Chromium-molybdenum alloy feedstock costs transmit directly through seamless pipe mill quotations to national oil company tender pricing, with Saudi Aramco and QatarEnergy procurement cycles now spanning decade-long horizons that compress spot-market volatility into contract-based long-term offtake structures.
Pricing Analysis
Lifecycle performance guarantees anchor value-based pricing for premium connection systems, with Tenaris SA and Vallourec SA bundling threading technology platforms into service contracts that tie compensation to tubular integrity outcomes. Price differentiation separates sour-service qualified chromium-molybdenum grades from standard API carbon steel specifications, with certification intensity and captive metallurgical capabilities commanding substantial premiums. Cost compression in commodity carbon steel tiers is intensifying because mill capacity bottlenecks concentrate seamless pipe supply among qualified facilities. Distributor-mediated procurement shows highest price sensitivity; integrated manufacturers with in-region finishing facilities demonstrate lowest sensitivity due to national content qualification preferences.
Supply Chain Analysis
Direct-to-national-oil-company channels handle hyperscale buyer demand from Saudi Aramco, QatarEnergy, and ADNOC, bypassing traditional distributor layers for mill-delivered threaded tubulars ready for wellhead installation. Geographic supply concentration centers on seamless pipe production in Japan, South Korea, and select European facilities with sour-service rolling equipment. Raw material dependencies draw from chromium and molybdenum metallurgical processing concentrated outside the Middle East, with billet supply chains tethered to limited qualified sources. Single-source vulnerability in alloy feedstock transmission exposes tubular manufacturing costs to commodity price volatility. Distribution runs through Dammam's King Abdulaziz Port clusters and Abu Dhabi's industrial free zones for inspection, threading, and technical service proximity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as API 5CT specification upgrades and SFDA traceability mandates filter supplier pools, forcing capital-light distributors without captive metallurgical capabilities toward exit or acquisition.
For Market Incumbents: Anchor long-term service agreements by threading predictive maintenance software into tubular supply contracts, creating switching costs that lock out commodity distributors. Deepen backward integration into heat treatment and connection machining capabilities in Dammam and Ras Laffan industrial zones to capture national content incentives. Defend against emerging technical service specialists by controlling inspection and repair facility networks across Gulf Cooperation Council states.
For New Entrants and Emerging Players: Capture white-space in UAE offshore subsea tieback architectures where Emirates Authority for Standardization and Metrology protocols favor premium connection specialists with established technical service presence. Target intermediate processing of seamless pipe for regional redistribution through Sohar's port and industrial zone, exploiting localization mandates that reshape supplier qualification criteria. Pursue joint venture structures with national oil companies to bypass qualification barriers that favor established networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light threading specialists with UAE technical service presence and established ADNOC qualification frameworks. Long-term viability across the analysis window rests on software-defined integrity monitoring capabilities converging with hardware supply. Watch QatarEnergy's North Field expansion phase transitions as inflection indicators for sour-service grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture with National Oil Company | Secures qualification preference under Gulf Cooperation Council national content regulations. |
| Captive Heat Treatment Facility Buildout | Addresses chromium-molybdenum grade scarcity and compresses lead times for sour-service orders. |
| Predictive Maintenance Platform Integration | Bundles equipment utilization data into contract anchors with Saudi Aramco and QatarEnergy. |
| Regional Inspection Network Expansion | Captures service contract unbundling as operators separate procurement from integrity management. |
| Alloy Feedstock Supply Agreement | Mitigates price volatility transmission from chromium-molybdenum concentration outside the Middle East. |
Research Methodology
Trade databases, national oil company tender disclosures, and seamless pipe mill capacity registers formed the secondary backbone, cross-referenced against primary interviews with procurement directors at Saudi Aramco and QatarEnergy, threading technology specialists at integrated manufacturers, and inspection facility operators in Dammam and Abu Dhabi. Bottom-up and top-down triangulation validated volume estimates across product categories and material grades.
Bottom-up modeling anchored forecast outputs, with top-down macro checks against hydrocarbon production trajectories and drilling program announcements. Segmentation dimensions spanned product type, material grade, end-use application, and manufacturing stage across the projection horizon. CAGRs derived from fitted growth curves incorporating tender cycle timing, qualification barrier evolution, and national content policy implementation schedules. Industry-specific inputs included ADNOC technical integrity framework revisions and SFDA traceability mandate compliance cost structures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unconventional shale program acceleration in Saudi Arabia's Jafurah basin and North Field expansion phase sequencing in Qatar. Forecasts reflect assumptions about alloy feedstock supply continuity and seamless pipe mill capacity expansion timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Well Casing Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Canada Oil and Gas Upstream Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Integrated Gas System Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
North America Oil Country Tubular Goods Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market