
 Global Mobile Offshore Drilling Units Market | 2026-2036
Global Mobile Offshore Drilling Units Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile Offshore Drilling Units Market Outlook
Independent operators and national oil companies is bifurcating the buyer landscape, with state-backed entities commanding longer-term fixtures and higher day-rate tolerance. Transocean Ltd. dominates ultra-deepwater drillship deployment through its high-specification fleet concentration. Valaris plc navigates a hybrid strategy across jackup and floater categories to sustain utilization breadth. Noble Corporation plc anchors its position in benign-environment harsh-weather dual-capability rigs.
Mobile offshore drilling units are self-propelled or towable floating platforms engineered for well drilling, completion, and workover operations in marine environments, typically rated for water depths from 30 meters to beyond 3,000 meters depending on hull form and station-keeping system. Their primary commercial purpose is to provide movable wellbore construction capacity to offshore leaseholders without permanent platform infrastructure. Drillships represent the fastest-growing product type as operators pursue pre-salt and Lower Tertiary plays requiring dynamic positioning and dual-activity derricks. Jackup rigs occupy the mature margin pool in shallow-water decommissioning and redevelopment work. Semi-submersible rigs concentrate in harsh-environment North Sea and Atlantic Canada fields where motion characteristics outweigh transit speed.
The International Maritime Organization enforces MARPOL Annex VI emission standards that constrain conventional diesel-electric propulsion in newbuild contracts, while classification societies such as DNV and ABS impose dual-fuel-ready notations that extend construction timelines and capital requirements. The US Coast Guard and Bureau of Safety and Environmental Enforcement coordinate flag-state and safety management protocols for units operating in US outer continental shelf waters. Stakeholders must monitor regulatory divergence between IMO global standards and emerging regional carbon intensity metrics that could fragment newbuild financing and resale liquidity.
Market Dynamics
The IMO MARPOL Annex VI emission standards are compressing newbuild propulsion choices toward dual-fuel-ready architectures, extending construction timelines and reshaping yard capacity allocation across major fabrication centers.
Growth Catalysts
- Pre-salt exploration:Brazil's national oil company has committed to ultra-deepwater fleet expansion in the Santos Basin. Dual-activity drillships with dynamic positioning systems command premium fixtures for these reservoirs.
- REACH-equivalent carbon intensity metrics:The EU Green Deal's maritime amendments are accelerating scrappage of conventional diesel-electric units. Classification societies are embedding dual-fuel-ready notations into newbuild specifications.
- Guyana-Suriname basin emergence:ExxonMobil-operated blocks are absorbing high-specification drillships. The Stabroek Block development is driving sequential fixture extensions for seventh-generation assets.
Market Restraints
- Steel and specialized alloy input volatility:High-strength quenched and tempered plate prices fluctuate with energy-intensive smelter economics. Korean and Chinese yard concentration amplifies cost pass-through sensitivity.
- Dual-fuel engine supply concentration:MAN Energy Solutions and Wärtsilä dominate liquefied natural gas-compatible propulsion systems. OEM bottlenecks extend delivery windows for compliant newbuilds.
- Dynamic positioning redundancy limitations:DP-3 classification requirements for ultra-deepwater operations constrain viable hull designs. Smaller fabrication yards lack certification depth for these systems.
Strategic Opportunities
- West African ultra-deepwater:Senegal-Mauritania cross-border developments and Namibe Basin licensing rounds are absorbing sixth-generation drillships. Local content requirements favor longer-term fixtures.
- Hybrid jackup electrification:Battery-hybrid power packs combined with shore-power interfaces are reducing idle fuel consumption. North Sea decommissioning campaigns are piloting these configurations.
- Carbon capture readiness:IMO guidelines on onboard CO2 handling systems are creating retrofit demand. Classification societies are developing notations for post-combustion capture integration.
Industry Challenges
- DP operator certification backlog:Dynamic positioning officer training capacity at maritime academies lags fleet expansion. Brazilian and West African operations face particular crew availability constraints.
- Dual-fuel system commissioning complexity:LNG bunkering infrastructure immaturity at Atlantic basin supply ports delays fuel system proving. First-of-class vessels require extended acceptance trials.
- Legacy BOP stack interchangeability:Subsea blowout preventer compatibility across rig generations complicates spare parts logistics. OEM consolidation has reduced alternative sourcing options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile Offshore Drilling Units Market |
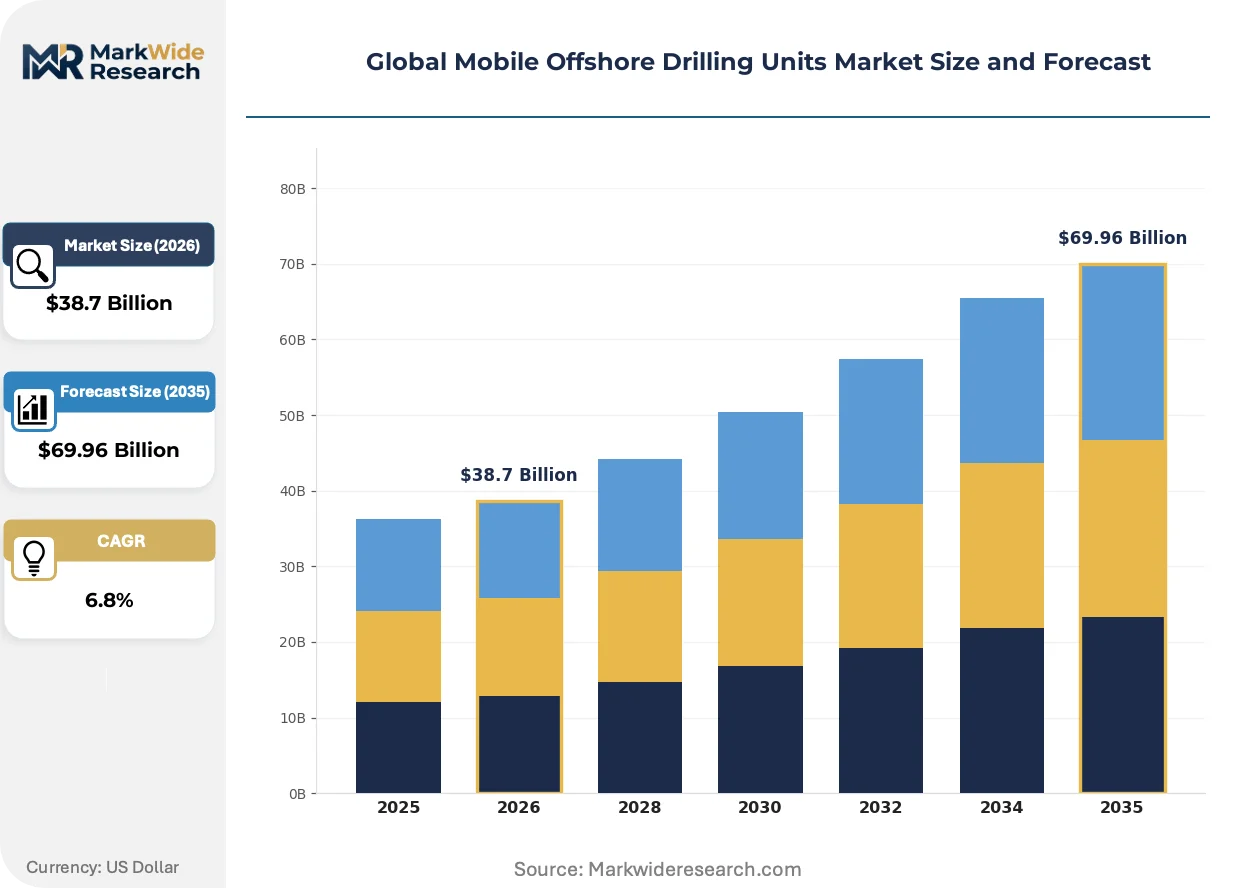
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jackup Rigs, Semi-submersible Rigs, Drillships, Tender Assisted Rigs End User: Oil & Gas Companies, Independent Operators, National Oil Companies, Service Providers Deployment: Onshore, Shallow Water, Deep Water, Ultra-deep Water Service Type: Exploration, Production, Well Intervention, Decommissioning |
| Companies Covered | Transocean Ltd., Valaris plc, Noble Corporation plc, Seadrill Limited, Keppel Corporation Limited, Daewoo Shipbuilding & Marine Engineering, Diamond Offshore Drilling, Inc., Borr Drilling Limited, Vantage Drilling International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile Offshore Drilling Units Market Strategic Shifts
Digital twin integration and predictive maintenance architectures are compressing non-productive time, while regulatory pressure on carbon intensity is forcing propulsion system reinvention across the newbuild pipeline.
Subsea robotics and autonomous inspection systems are miniaturizing. National oil companies in Brazil and Guyana are deploying remotely operated vehicle fleets with reduced surface vessel dependency. This technology is miniaturizing the topside footprint required for well intervention, enabling smaller hull forms with equivalent subsea capability.
DNV's newbuild notation for carbon-neutral-ready designs is tightening material specification requirements. Shipyards in South Korea and Singapore are redesigning power distribution architectures to accommodate future ammonia or methanol fuel cells. Ultra-deepwater drillships ordered after 2025 face the most stringent dual-fuel engine certification timelines.
Day-rate indexing mechanisms are displacing fixed-term fixtures in contractor-operator negotiations. Independent operators in the Gulf of Mexico are demanding performance-linked pricing tied to mechanical downtime thresholds. This shift is most visible in the US outer continental shelf, where Bureau of Safety and Environmental Enforcement incident metrics factor directly into rate adjustment clauses.
Global Mobile Offshore Drilling Units Market Segmentation
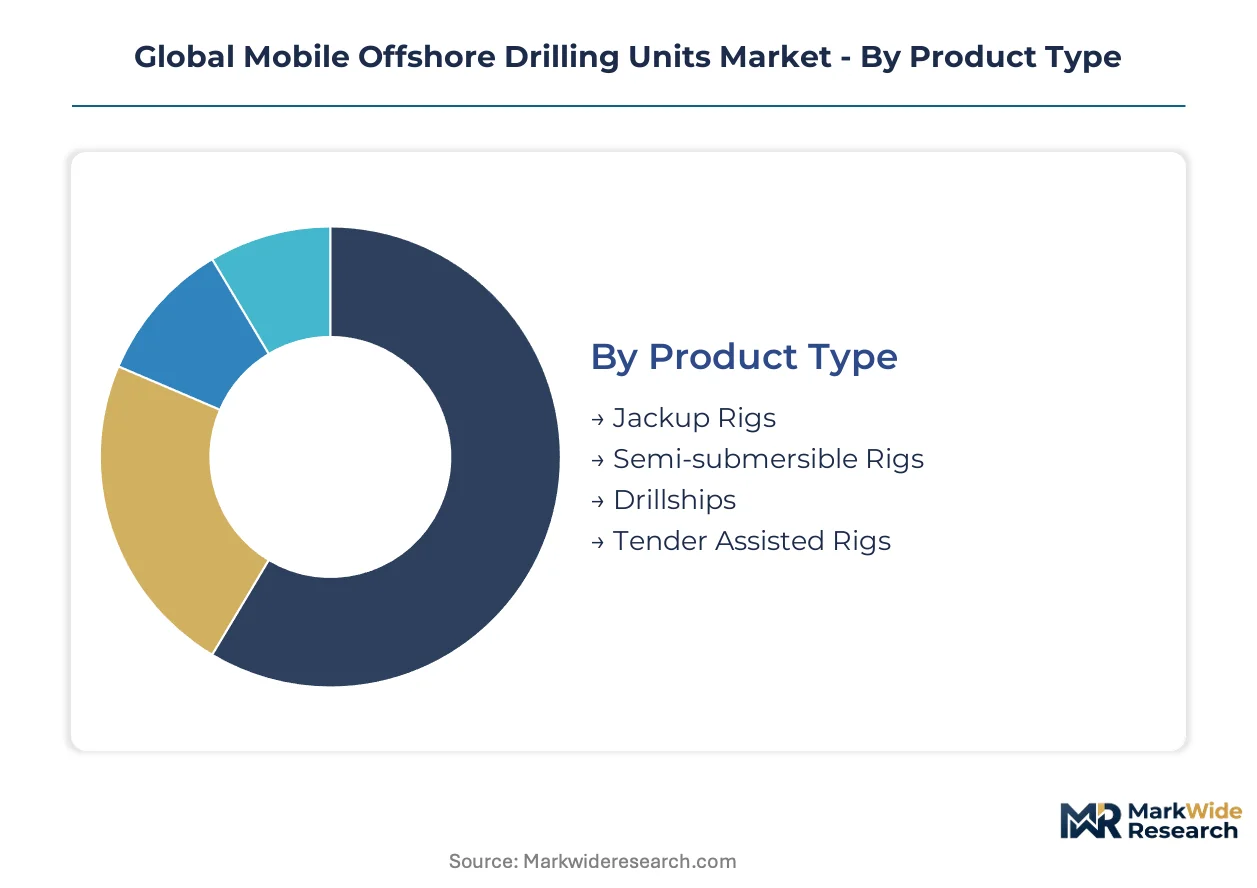
Segmentation in the Mobile Offshore Drilling Units market exposes divergent capital intensity profiles across hull architectures and water depth ratings. Product type selection dictates propulsion system specifications, crew certification requirements, and day-rate benchmarks that reshape fleet investment priorities for leaseholders.
Product Type:
Substitution pressure from platform-based solutions and well intervention vessels is strongest against shallow-water jackup categories, while ultra-deepwater drillships face limited functional alternatives.
- Drillships:Self-propelled monohull vessels equipped with dynamic positioning systems and dual-activity derricks capable of operating beyond 3,000 meters water depth. Demand concentrates in Brazil's Santos Basin pre-salt fields and Guyana's Stabroek Block, where ExxonMobil-operated developments command seventh-generation fixtures.
- Jackup Rigs:Bottom-supported platforms with retractable legs that elevate the hull above wave action in depths up to 150 meters. Operators in the North Sea decommissioning market favor these units for platform removal campaigns, though battery-hybrid retrofits are compressing idle fuel consumption.
- Semi-submersible Rigs:Twin-hull platforms with exceptional motion characteristics for harsh-environment North Sea and Atlantic Canada operations. These units sacrifice transit speed for station-keeping stability in severe wave states.
- Tender Assisted Rigs:Platform-based drilling systems reliant on adjacent support vessels for crew quarters and logistics. West African marginal field developments employ these configurations to minimize hull capital exposure.
Jackup Rigs retain volume leadership across active fleet counts; Drillships hold the steepest expansion curve as exploration migrates into deeper Atlantic basins.
End User:
Customer type segmentation reveals divergent contracting behaviors, with state-backed entities tolerating longer fixture durations and higher rate floors than risk-averse independents.
- National Oil Companies:State-controlled petroleum enterprises in Brazil, Guyana, and Saudi Arabia command multi-year fleet commitments that stabilize contractor utilization. These operators prioritize dual-fuel-ready specifications to align with IMO decarbonization mandates.
- Oil & Gas Companies:Integrated majors with balanced upstream portfolios. Their fixture strategies emphasize performance-linked pricing tied to mechanical downtime thresholds rather than fixed-term commitments.
- Independent Operators:Privately held exploration firms concentrated in Gulf of Mexico shelf redevelopment. These entities demand short-cycle fixtures with rate adjustment clauses tied to Bureau of Safety and Environmental Enforcement incident metrics.
- Service Providers:Contract drilling specialists and integrated well service firms that lease unit capacity to upstream operators. Their procurement patterns favor standardized BOP stack interchangeability to reduce spare parts logistics complexity.
National Oil Companies anchor fleet utilization stability; Independent Operators are gaining share fastest as private equity-backed entrants consolidate Gulf of Mexico shelf assets.
Deployment:
Water depth ratings determine hull form eligibility, with deeper categories commanding narrower supplier bases and extended construction timelines at Korean and Singaporean yards.
- Ultra-deep Water:Operations beyond 1,500 meters requiring dynamic positioning and subsea BOP systems. West African cross-border developments and Namibe Basin licensing rounds absorb sixth-generation drillships with DP-3 redundancy.
- Deep Water:Deployments between 400 and 1,500 meters where semi-submersible rigs retain competitive positioning. US Gulf of Mexico Lower Tertiary plays concentrate demand for these water depth ratings.
- Shallow Water:Jackup-accessible depths up to 400 meters dominated by mature field redevelopment and decommissioning work. North Sea platform removal campaigns sustain fixture demand despite limited new exploration.
- Onshore:Land-based drilling systems outside marine scope, excluded from MODU classification and IMO MARPOL Annex VI jurisdiction.
Shallow Water retains fixture volume leadership; Ultra-deep Water climbs the fastest as pre-salt and Lower Tertiary reservoirs enter development phases.
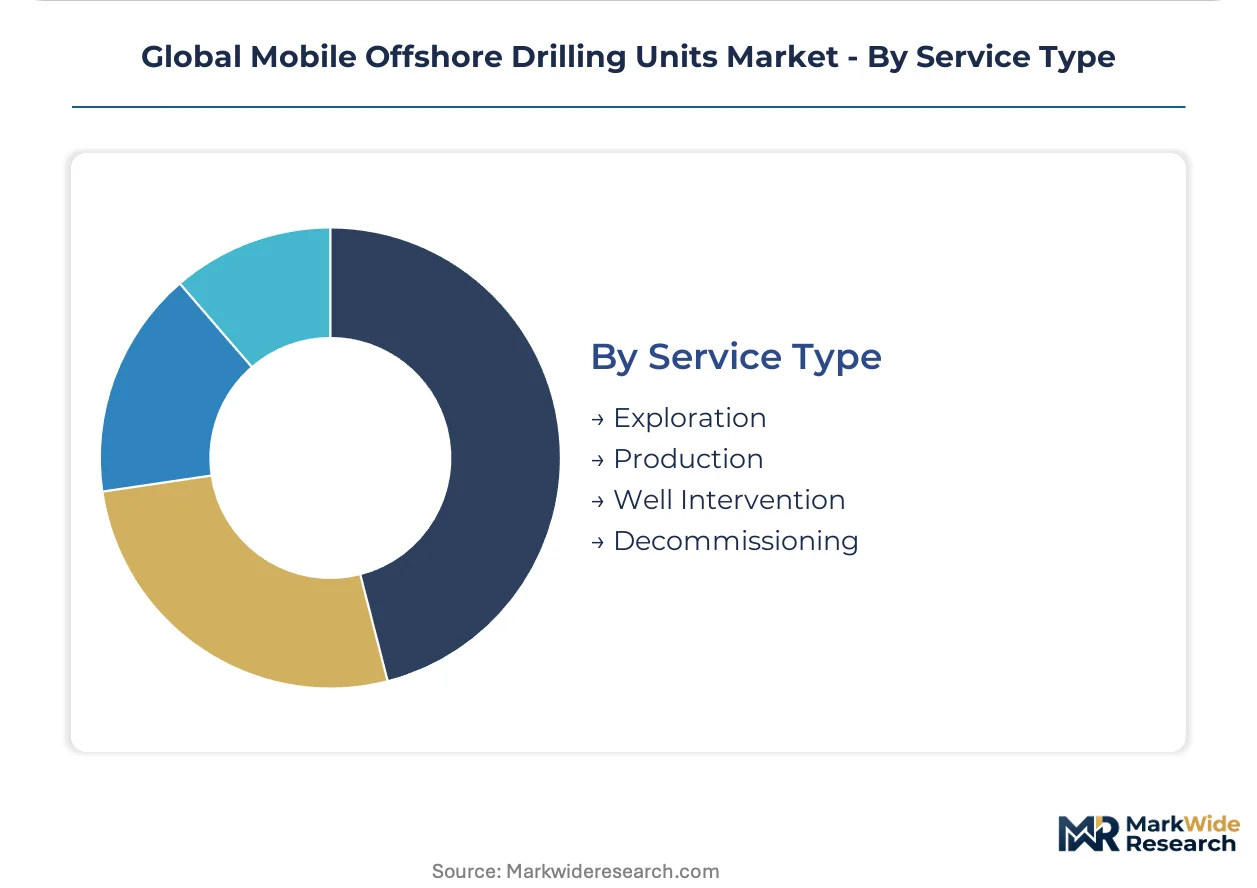
Service Type:
Activity-based segmentation tracks the well lifecycle, with exploration contracting exhibiting sharper cyclicality than production maintenance work.
- Exploration:Wildcat and appraisal drilling for unproven reserves. Brazil's national oil company has committed to ultra-deepwater fleet expansion specifically for Santos Basin exploration campaigns.
- Production:Development drilling and completion of proven reservoirs. Guyana-Suriname basin emergence is driving sequential fixture extensions for high-specification drillships in this service category.
- Well Intervention:Workover and recompletion of existing wellbores. Miniaturized subsea robotics are reducing topside footprint requirements for these operations.
- Decommissioning:Plugging and abandonment of end-of-life wells plus platform removal. North Sea regulatory deadlines are accelerating fixture demand for jackup rigs in this segment.
Production retains revenue concentration; Well Intervention is expanding most quickly as autonomous inspection systems enable smaller hull forms with equivalent subsea capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore anchors Asia-Pacific supply chain connectivity for MODU component fabrication and classification services, while Houston's offshore technology corridor concentrates engineering expertise for Gulf of Mexico deployments.
United States
Lower Tertiary plays in the Gulf of Mexico absorb sixth-generation drillships with dual-activity derricks. The US Coast Guard coordinates flag-state protocols with Bureau of Safety and Environmental Enforcement incident metrics. Houston's Energy Corridor hosts contractor headquarters managing fixtures across the outer continental shelf.
Brazil
Pre-salt reservoirs in the Santos Basin command premium fixtures for seventh-generation assets with dynamic positioning redundancy. The national petroleum regulator ANP mandates local content thresholds for fleet procurement. Macaé's offshore service base supports rig mobilization for Petrobras-operated developments.
Norway
Harsh-environment semi-submersible demand concentrates in North Sea decommissioning and redevelopment campaigns. The Norwegian Maritime Authority enforces strict station-keeping standards for winterized hull specifications. Stavanger's drilling contractor cluster coordinates jackup fixtures for platform removal work.
South Korea
Ultra-deepwater newbuild construction dominates yard capacity at Samsung Heavy Industries and DSME facilities. The Korea Register of Shipping imposes dual-fuel-ready notations extending delivery timelines. Geoje's shipbuilding complex fabricates high-specification drillships for Atlantic basin operators.
United Arab Emirates
Jackup rig refurbishment and upgrade demand flows through Dubai Maritime City facilities serving Middle East and West African markets. The Federal Transport Authority aligns with IMO MARPOL Annex VI emission standards for regional fleet compliance. Jebel Ali's port infrastructure supports heavy-lift vessel logistics for rig mobilization.
Global Mobile Offshore Drilling Units Market Competitive Environment
Listed leaders compete with private specialists across capital structure and fixture duration tolerance, creating a tiered competitive landscape where public contractors optimize for shareholder returns while private operators absorb shorter-cycle risk. The market structure concentrates around three strategic archetypes: ultra-deepwater drillship specialists commanding premium day-rates, hybrid fleet operators balancing jackup and floater exposure, and benign-environment harsh-weather dual-capability rig providers. Consolidation pressure drives M&A activity among distressed asset holders, while dual-fuel propulsion requirements force strategic partnerships with engine OEMs.
Within the ultra-deepwater specialist tier, Transocean Ltd. and Valaris plc exemplify divergent fleet concentration strategies, with the former anchoring high-specification drillship deployment and the latter maintaining hybrid category breadth. Noble Corporation plc occupies a position emphasizing dual-environment capability for harsh-weather markets. These publicly traded contractors represent archetypal responses to IMO decarbonization mandates and classification society dual-fuel-ready specifications.
| Leading Market Players |
|---|
| Transocean Ltd. |
| Valaris plc |
| Noble Corporation plc |
| Seadrill Limited |
| Keppel Corporation Limited |
| Daewoo Shipbuilding & Marine Engineering |
| Diamond Offshore Drilling, Inc. |
| Borr Drilling Limited |
| Vantage Drilling International |
| Others |
Value Chain & Pricing Dynamics
Yard capacity utilization at Korean and Singaporean fabrication centers concentrates bargaining power among a handful of hull builders, compressing price floors for ultra-deepwater drillships while elevating premiums for dual-fuel-ready specifications. This scale concentration forces contractors to accept extended delivery timelines or absorb cost pass-through from high-strength steel and specialized alloy suppliers.
Pricing Analysis
Three-tier pricing structure across seventh-generation, sixth-generation, and legacy-generation rig categories separates premium fixtures for Santos Basin pre-salt work from standard North Sea decommissioning rates and economy-tier jackup redeployment. Price differentiation rests on DP-3 classification depth and dual-fuel engine certification tier. Cost compression in legacy jackup segments is intensifying because battery-hybrid retrofits extend asset life without newbuild capital deployment. Independent operators in the Gulf of Mexico shelf exhibit highest price sensitivity, while Petrobras and ExxonMobil tolerate premium day-rates for specification compliance.
Supply Chain Analysis
Strait of Malacca transit underwrites component logistics for Samsung Heavy Industries and DSME yards, creating vulnerability to port congestion and flag-state inspection delays. Hull fabrication draws from South Korea, Singapore, and China, with high-strength quenched and tempered plate sourcing from POSCO and Baosteel. MAN Energy Solutions and Wärtsilä concentration in dual-fuel propulsion systems presents single-source vulnerability for LNG-compatible engine modules. Distribution runs through Houston's Energy Corridor for Gulf of Mexico fixtures and Macaé's offshore service base for Brazilian deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Offshore Drilling Units market functions as a defensive-moat industry where regulatory entrenchment around IMO MARPOL Annex VI compliance and classification society dual-fuel-ready notations erects steep barriers to speculative newbuild entry.
For Market Incumbents: Consolidate fleet concentration around ultra-deepwater drillship specialization or hybrid jackup-floater breadth to capture divergent fixture demand. Anchor backward integration into subsea BOP stack maintenance capabilities to offset OEM consolidation in blowout preventer sourcing. Defend against emerging battery-hybrid specialist entrants by accelerating dual-fuel-ready newbuild commitments at Geoje and Singapore yards before engine OEM bottlenecks extend delivery windows further. For New Entrants and Emerging Players: Anchor in West African ultra-deepwater fixtures where local content requirements favor longer-term contracts and Senegalese-Mauritanian cross-border developments absorb available sixth-generation capacity. Target tender-assisted rig configurations for marginal field operators seeking minimized hull capital exposure. Pursue carbon capture readiness retrofit partnerships with classification societies developing post-combustion capture notations as a differentiated service layer. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contractors with seventh-generation drillship fleets already contracted through pre-salt and Lower Tertiary development phases. Long-term viability hinges on dual-fuel propulsion compliance rather than speculative alternative fuel bets. Monitor DP operator certification backlog at Brazilian and West African maritime academies as an inflection indicator for crew-constrained fixture availability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Propulsion Retrofit | IMO MARPOL Annex VI compliance extends asset residual value in Atlantic basin fixtures. |
| DP-3 Classification Investment | Redundant dynamic positioning systems unlock ultra-deepwater fixtures off West Africa. |
| Local Content Partnership | ANP-mandated Brazilian procurement thresholds stabilize multi-year utilization for compliant contractors. |
| Battery-Hybrid Jackup Conversion | North Sea decommissioning campaigns pilot shore-power interfaces reducing idle fuel burn. |
| Carbon Capture Readiness Integration | DNV notation development creates first-mover retrofit demand ahead of IMO guidelines finalization. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of fleet utilization databases, classification society notation registries, and regulatory filing archives. Interviews with drilling contractor fleet managers, shipyard procurement directors, national oil company technical advisors, and maritime academy training officers combined with analysis of IMO circulars, ANP local content directives, and Bureau of Safety and Environmental Enforcement incident reports. Bottom-up rig-by-rig fixture tracking triangulates against top-down Atlantic basin demand projections.
Segmentation dimensions modeled span hull architecture, water depth rating, propulsion specification, and end-user contracting archetype across the projection horizon. CAGRs derive from rig delivery schedules, scrappage forecasts for conventional diesel-electric units, and fixture duration assumptions tied to pre-salt and Lower Tertiary development timelines. Forecast inputs incorporate steel price volatility indices and dual-fuel engine delivery backlogs reported by MAN Energy Solutions and Wärtsilä.
Underlying assumptions cover continued enforcement of MARPOL Annex VI emission standards, with deviation risk concentrated in regional carbon intensity metric fragmentation between EU Green Deal amendments and IMO global benchmarks. Practitioners should keep alternative scenarios live as LNG bunkering infrastructure maturity and ammonia fuel cell certification timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market