
 Deepwater Subsea Structure Integrity Acoustic Test Platforms Market | 2026-2036
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market Insights
API RP 2SIM qualification for subsea structural integrity management is collapsing the vendor landscape to firms with demonstrated deepwater certification. Sonardyne leverages its underwater positioning heritage to anchor acoustic test platform development for harsh-environment installations. Fugro sustains competitive position through integrated survey and inspection capabilities spanning multiple ocean basins. Oceaneering International dominates the contractor channel by controlling specialized deployment vessels and robotic intervention assets.
Deepwater subsea structure integrity acoustic test platforms comprise sensor-integrated systems that emit and receive acoustic signals to detect material degradation, structural deformation, or fluid leakage at depths exceeding 300 meters. These platforms typically operate at frequencies between 20 kHz and 2 MHz, with hydrophone arrays and piezoelectric transducers converting mechanical stress waves into digital signatures for real-time analysis. Fixed platforms command the largest installed base due to permanent seabed foundations requiring continuous monitoring, while fiber optic sensor deployments represent the fastest-expanding acoustic technology category as operators seek electromagnetic immunity and distributed sensing coverage across riser and pipeline networks.
The US Bureau of Safety and Environmental Enforcement mandates periodic structural integrity verification for all deepwater facilities on the Outer Continental Shelf, directly shaping procurement specifications for acoustic test platforms. Norway's Petroleum Safety Authority and Brazil's national petroleum regulator enforce comparable inspection intervals, creating harmonized demand for certified platform technologies across Atlantic basin production provinces. Stakeholders must weigh capital deployment toward autonomous underwater vehicle-integrated acoustic systems against tethered platform architectures as inspection cycle frequencies tighten and labor costs for crewed interventions escalate.
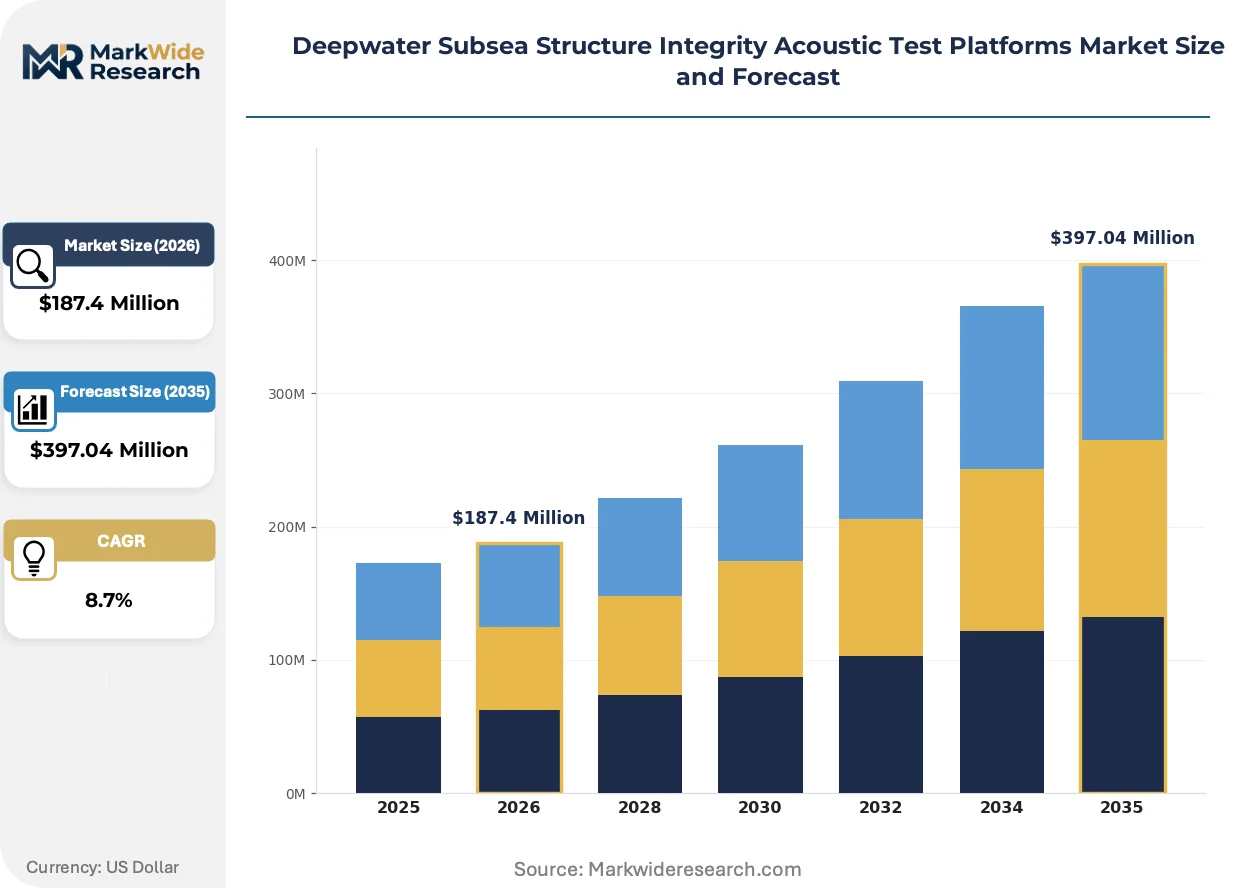
Market Dynamics
API RP 2SIM certification requirements are concentrating vendor selection around firms with demonstrated deepwater structural integrity management credentials, forcing procurement departments to disqualify uncertified suppliers regardless of price competitiveness.
Growth Catalysts
- US Bureau of Safety and Environmental Enforcement mandates:Periodic structural integrity verification requirements for Outer Continental Shelf facilities create recurring procurement cycles for certified acoustic platforms.
- Fiber optic acoustic sensing:Electromagnetic immunity and distributed coverage capabilities across riser networks drive replacement of conventional piezoelectric arrays in new installations.
- Hurricane exposure in US Gulf of Mexico:Aging infrastructure combined with extreme weather events sustains demand for continuous monitoring systems with real-time damage detection.
Market Restraints
- Piezoelectric ceramic supply concentration:Specialized transducer materials depend on limited suppliers in East Asian manufacturing clusters, creating input cost volatility and delivery risk.
- Deepwater deployment capex intensity:Installation at depths exceeding 300 meters requires specialized vessels and robotic assets that constrain inspection frequency regardless of platform capability.
- Frequency band allocation friction:Acoustic signal ranges between 20 kHz and 2 MHz face coordination requirements with maritime communication regulators in multiple offshore provinces.
Strategic Opportunities
- Brazil pre-salt basin expansion:National petroleum regulator enforcement of inspection intervals comparable to US and Norwegian standards creates certified platform demand in underpenetrated deepwater fields.
- Autonomous underwater vehicle integration:Convergence of mobile robotics with fixed sensor networks enables inspection cycle compression without crewed vessel deployment.
- Norway Petroleum Safety Authority harmonization:Alignment of Atlantic basin regulatory standards reduces certification duplication costs for multi-province operators.
Industry Challenges
- Deepwater acoustics engineering talent scarcity:Specialized expertise in hydrophone array calibration and signal processing for high-pressure environments limits platform development velocity.
- Legacy platform integration complexity:Retrofitting fiber optic sensing onto existing fixed foundations requires custom mechanical interfaces that extend deployment timelines.
- API RP 2SIM certification timeline:Demonstration of structural integrity management competency demands extended field validation periods that delay revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deepwater Subsea Structure Integrity Acoustic Test Platforms Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Platform Type: Fixed Platforms, Floating Platforms, Semi-submersible Platforms, Spar Platforms, Tension Leg Platforms Acoustic Technology: Laser Ultrasonics, Resonant Ultrasound Spectroscopy, Piezoelectric Sensors, Fiber Optic Sensors, Hydrophone Arrays Application: Corrosion Detection, Crack Identification, Fatigue Monitoring, Structural Health Assessment, Leak Detection End User: Exploration & Production Companies, Subsea Engineering Firms, Research Institutes, Offshore Service Providers, Inspection Contractors |
| Companies Covered | Sonardyne, TSC Subsea, Scanmatic, AP Sensing, MISTRAS Group, Fugro, Oceaneering International, TechnipFMC, Subsea 7, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market Trends and Innovations
Acoustic monitoring architectures are fragmenting between fixed seabed installations and mobile robotic platforms, with procurement specifications increasingly demanding interoperability between these historically separate system categories.
Fiber optic distributed acoustic sensing is decomposing the traditional boundary between point-source hydrophones and continuous coverage systems. Offshore operators in the US Gulf of Mexico are specifying fiber-based riser monitoring for new floating production installations. The technology is decomposing legacy piezoelectric array business models by enabling single-cable coverage of pipeline networks that previously required dozens of discrete sensors.
REACH chemical restrictions on piezoelectric ceramics containing lead zirconate titanate are forcing material substitutions in transducer manufacturing. European offshore contractors now face compliance verification requirements for seabed-deployed equipment. The Norway-UK North Sea corridor has become the primary testing ground for lead-free piezoelectric formulations in deepwater pressure conditions.
Integrated service contracts are compressing the traditional separation between platform procurement and inspection operations. Major offshore contractors in Brazil now bundle acoustic system deployment with annual integrity verification, displacing discrete equipment sales. This bundling is most advanced in the pre-salt basin where national operator procurement favors single-accountability arrangements over multi-vendor management.
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market Segmentation
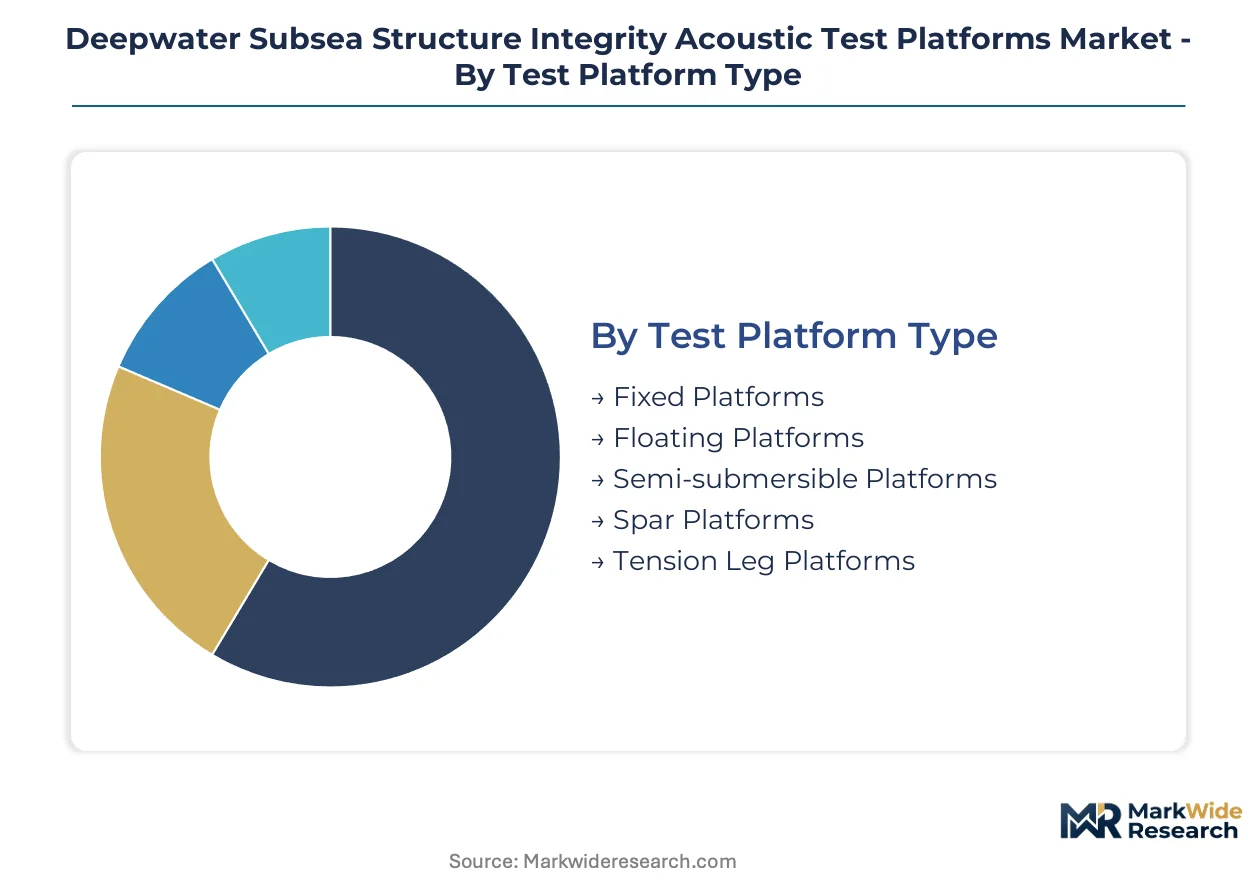
Segmentation in the deepwater acoustic test platform market reveals how procurement specifications diverge across installation architectures and sensing modalities. Platform type determines capital intensity and deployment logistics, while acoustic technology selection shapes electromagnetic compatibility and distributed coverage capabilities.
Test Platform Type:
Margin pools concentrate in permanent seabed installations where continuous monitoring commands premium pricing over campaign-based inspection.
- Fixed Platforms:Permanent seabed foundations with integrated sensor networks deliver uninterrupted structural monitoring. The US Gulf of Mexico concentrates demand as hurricane exposure and aging infrastructure drive replacement cycles for legacy systems.
- Floating Platforms:Mooring-connected production vessels require riser-focused acoustic arrays addressing dynamic loading conditions. Brazil's pre-salt basin operators specify these configurations for deepwater floating production storage and offloading units.
- Semi-submersible Platforms:Column-stabilized drilling and production units need hull-integrated sensing for fatigue crack monitoring.
- Spar Platforms:Deep-draft cylindrical hulls present unique riser access challenges for external sensor deployment.
- Tension Leg Platforms:Tendon-based mooring systems demand specialized monitoring of tension leg integrity under cyclic loading.
Fixed platforms hold installed capacity. Floating platforms are rotating up the share rankings.
Acoustic Technology:
Technology selection pivots on whether operators prioritize electromagnetic immunity or established calibration protocols.
- Fiber Optic Sensors:Distributed acoustic sensing along single cables eliminates electromagnetic interference risks while covering pipeline networks that previously required discrete sensor arrays. New floating production installations in the US Gulf of Mexico specify fiber-based riser monitoring as standard.
- Piezoelectric Sensors:Lead zirconate titanate transducers provide proven signal conversion for point-source measurements. REACH chemical restrictions are forcing material substitutions in European offshore procurement.
- Laser Ultrasonics:Non-contact generation and detection of ultrasound enables inspection of coated or corroded surfaces without mechanical coupling.
- Resonant Ultrasound Spectroscopy:Frequency-domain analysis identifies material property variations and microstructural degradation in structural components.
- Hydrophone Arrays:Underwater sound detection grids support passive acoustic monitoring for leak detection and flow characterization.
Piezoelectric sensors retain the largest installed base. Fiber optic sensors are climbing the fastest as operators specify electromagnetic immunity.
Application:
Application focus determines whether procurement prioritizes real-time alarm capability or scheduled inspection cycles.
- Corrosion Detection:Wall thickness monitoring through guided wave ultrasound identifies metal loss before structural capacity degradation. The US Bureau of Safety and Environmental Enforcement mandates periodic verification for Outer Continental Shelf facilities.
- Leak Detection:Passive acoustic monitoring of pressure waves from escaping fluids enables immediate alarm generation. Norway's Petroleum Safety Authority enforces comparable inspection intervals for subsea infrastructure.
- Crack Identification:High-frequency pulse-echo techniques locate and size fatigue cracks in welded connections and stress concentration zones.
- Fatigue Monitoring:Strain accumulation tracking supports remaining life assessment for dynamically loaded risers and tendons.
- Structural Health Assessment:Integrated evaluation of multiple degradation modes informs integrity management decisions.
Corrosion detection commands the largest procurement volume. Leak detection is gaining share fastest as real-time monitoring specifications tighten.
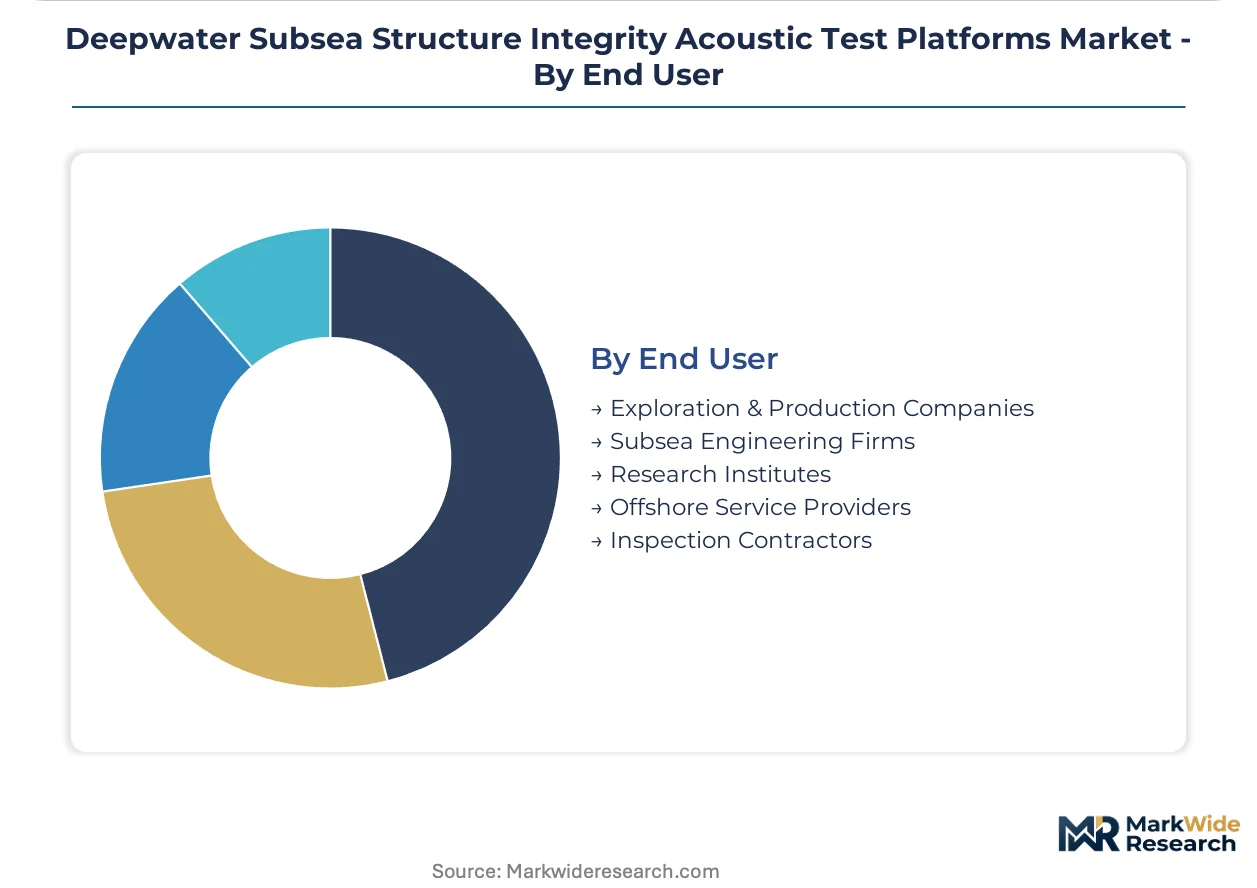
End User:
End user category shapes whether procurement flows through capital budgets or operating expenditure contracts.
- Exploration & Production Companies:National and international oil companies own structural integrity accountability and specify platform technologies for operated assets. Brazil's national operator favors bundled service contracts combining equipment with annual verification.
- Inspection Contractors:Third-party service providers procure mobile and deployable systems for campaign-based inspection services. Integrated service contracts in the pre-salt basin displace discrete equipment sales.
- Subsea Engineering Firms:Design contractors specify monitoring systems during front-end engineering for new installations.
- Offshore Service Providers:Vessel and equipment rental companies maintain acoustic platforms for spot market deployment.
- Research Institutes:Academic and government laboratories validate new sensing technologies before field qualification.
Exploration and production companies hold procurement authority. Inspection contractors are rotating up the share rankings as bundled service models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration clusters around offshore exploration and production companies with deepwater assets in hurricane-exposed basins. National petroleum regulators in the Atlantic basin enforce harmonized inspection intervals that shape procurement specifications. Demand geography tracks mature production provinces where aging infrastructure coincides with regulatory tightening.
United States
The US Gulf of Mexico concentrates the largest installed base of fixed platform monitoring systems. The Bureau of Safety and Environmental Enforcement mandates periodic structural integrity verification for all Outer Continental Shelf facilities. Houston anchors the contractor ecosystem where Sonardyne and Oceaneering International maintain operational headquarters for Atlantic basin deployment.
Brazil
Pre-salt basin expansion drives procurement for floating production storage and offloading unit monitoring. The national petroleum regulator enforces inspection intervals comparable to US and Norwegian standards. Rio de Janeiro hosts the engineering centers where bundled service contracts combine acoustic platform deployment with annual verification.
Norway
North Sea infrastructure aging sustains replacement demand for legacy piezoelectric systems. The Petroleum Safety Authority mandates continuous monitoring for dynamically loaded risers and tendons. Stavanger and Bergen anchor the subsea engineering cluster where REACH-compliant lead-free transducer formulations undergo deepwater validation.
United Kingdom
Decommissioning timelines for mature North Sea assets extend structural integrity monitoring requirements. The Health and Safety Executive enforces offshore installation safety case regulations that incorporate acoustic inspection data. Aberdeen maintains the service contractor density for campaign-based platform deployment across the UK continental shelf.
China
South China Sea deepwater development expands specification demand for autonomous underwater vehicle-integrated systems. The Ministry of Emergency Management oversees offshore facility safety standards through provincial maritime safety administrations. Shenzhen and Tianjin host the manufacturing clusters where fiber optic sensor cables undergo pressure qualification for 300-meter-plus installations.
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market Competitive Landscape
Player mix skews toward integrated service contractors with captive deployment assets and specialized sensor manufacturers with underwater positioning heritage. Market structure concentrates around firms holding API RP 2SIM certification, with procurement departments disqualifying uncertified suppliers regardless of price competitiveness. Two strategic archetypes dominate: vertically integrated offshore contractors controlling vessels and robotic intervention assets, and technology specialists with demonstrated deepwater hydrophone array calibration expertise. Competitive moves center on bundled service contract expansion and fiber optic sensing technology licensing.
Among integrated offshore contractors, Fugro and Oceaneering International occupy positions that exemplify the vessel-asset archetype, while Sonardyne represents the underwater positioning heritage specialist tier. These three firms anchor the vendor landscape where certification credentials and deployment capability determine procurement eligibility. The concentration reflects API RP 2SIM qualification requirements that collapse vendor selection to demonstrated deepwater structural integrity management competency.
| Leading Market Players |
|---|
| Sonardyne |
| TSC Subsea |
| Scanmatic |
| AP Sensing |
| MISTRAS Group |
| Fugro |
| Oceaneering International |
| TechnipFMC |
| Subsea 7 |
| Others |
Pricing and Supply Chain Analysis
API RP 2SIM qualification requirements simultaneously gate supplier eligibility and stratify pricing tiers, compressing procurement options to certified vendors while enabling premium capture for demonstrated deepwater structural integrity management competency. This regulatory entrenchment creates asymmetric pricing power where uncertified competitors face automatic disqualification regardless of cost position.
Pricing Analysis
Cost-plus contracts with Bureau of Safety and Environmental Enforcement compliance indexation dominate procurement for US Gulf of Mexico installations. Three-tier pricing structure across API RP 2SIM-certified premium, transitional standard, and uncertified economy levels separates vendors by demonstrated field validation history. Pricing pressure stems from integrated service bundling in Brazil's pre-salt basin, where national operators favor single-accountability arrangements over discrete equipment sales. Exploration and production companies exhibit lowest price sensitivity for hurricane-exposed fixed platform monitoring, while inspection contractors face margin compression from bundled contract terms.
Supply Chain Analysis
Piezoelectric ceramic feedstock chokepoints in Japanese and Chinese manufacturing clusters tether transducer production to East Asian supply corridors. Lead zirconate titanate formulations and fiber optic sensor cables draw from specialized chemical processing and submarine cable fabrication facilities concentrated in Germany, Japan, and China. Single-source vulnerability in high-pressure hydrophone array calibration equipment creates procurement risk for platform integrators. Distribution runs through integrated offshore contractors controlling specialized deployment vessels rather than discrete equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat defensive structure where API RP 2SIM certification creates switching costs that entrench incumbent positions against price-based competition.
For Market Incumbents: Compound certification advantages through fiber optic sensing technology licensing to inspection contractors facing bundled service contract demands in Brazil. Deepen captive deployment vessel networks in the US Gulf of Mexico to compress inspection cycle timelines for hurricane-exposed operators. Address emerging threat from autonomous underwater vehicle-integrated mobile platforms by controlling interoperability standards between fixed and robotic architectures. For New Entrants and Emerging Players: Anchor in China South China Sea deepwater development where autonomous underwater vehicle-integrated specifications outpace established vendor qualification timelines. Target inspection contractor procurement channels rotating up share rankings as bundled service models expand. Pursue go-to-market positioning through lead-free piezoelectric formulation partnerships with Norway-UK North Sea engineering clusters facing REACH chemical compliance deadlines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed subsea engineering specialists holding API RP 2SIM credentials but lacking integrated deployment vessel control. Long-term viability across the analysis window hinges on regulatory harmonization deepening rather than fragmenting Atlantic basin standards. Monitor Brazil national petroleum regulator enforcement intensity as inflection signal for pre-salt basin contract flow acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Optic Sensor Licensing | Enables electromagnetic immunity positioning against legacy piezoelectric arrays in US Gulf floating production specifications. |
| Autonomous Vehicle Integration Partnership | Compresses inspection cycles without crewed vessel deployment, addressing Bureau of Safety and Environmental Enforcement tightening intervals. |
| Lead-Free Transducer Certification | Secures REACH compliance positioning for Norway-UK North Sea replacement demand and European offshore procurement. |
| Bundled Service Contract Expansion | Captures Brazil pre-salt basin national operator preference for single-accountability arrangements over multi-vendor management. |
| Deepwater Deployment Vessel Acquisition | Controls specialized robotic intervention assets that constrain competitor inspection frequency regardless of platform capability. |
Research Methodology
Operator-level perspectives from offshore installation managers, subsea integrity engineers, procurement directors at national oil companies, and acoustic platform calibration specialists anchored the qualitative base for this study. Primary interview findings triangulated against Bureau of Safety and Environmental Enforcement regulatory filings, Norway Petroleum Safety Authority inspection protocols, Brazil national petroleum regulator enforcement records, and fiber optic sensor patent landscapes. Secondary validation drew from offshore contractor SEC disclosures, subsea engineering trade association technical standards, and deepwater project development databases. Bottom-up segment sizing across platform type, acoustic technology, and application categories converged with top-down market reconstruction from major end-user capital expenditure disclosures.
Sensitivity analysis around regulatory enforcement intensity, fiber optic substitution velocity, and autonomous underwater vehicle adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include platform architecture, sensing modality, inspection application, and end-user procurement channel. CAGRs derived from installation base depreciation schedules, replacement cycle compression, and new deepwater project sanctioning rates. Forecast inputs incorporated Outer Continental Shelf facility aging profiles, hurricane damage frequency assumptions, and pre-salt basin floating production unit deployment timelines.
Material uncertainties — regulatory harmonization reversals, piezoelectric ceramic supply disruptions, and autonomous platform interoperability standard fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and inspection interval enforcement consistency. Practitioners should keep alternative scenarios live as Atlantic basin regulatory alignment and REACH chemical restriction expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
United Kingdom Oil and Gas Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Enhanced Oil Recovery Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
China Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market