
 Gulf of Mexico Oil and Gas Market | 2026-2036
Gulf of Mexico Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf of Mexico Oil and Gas Market Foresight
The EPA's methane emissions standards for offshore sources is repositioning capital allocation across the Gulf shelf. Shell Plc dominates ultra-deepwater lease holdings through its Mars and Appomattox hub complexes. Chevron Corporation anchors production economics with extensive subsea tieback infrastructure at its Anchor and Ballymore developments. Oxy sustains shelf-margin competitiveness through enhanced oil recovery programs across its legacy Permian-adjacent Gulf assets.
Gulf of Mexico oil and gas encompasses hydrocarbon extraction, processing, and transport operations across federal and state waters spanning the Outer Continental Shelf, with formations typically encountered at depths from 15 feet to beyond 10,000 feet below the mudline using dynamically positioned drillships and semisubmersible rigs. Production serves refineries, petrochemical complexes, LNG export terminals, and power generation facilities concentrated along the Texas-Louisiana industrial corridor. Drilling services command premium dayrates as operators pursue Lower Tertiary and Wilcox targets beneath thick salt canopies. Subsea systems represent the fastest-growing application category as multiphase boosting and all-electric trees displace traditional platform architectures. Energy companies constitute the dominant end-user segment, though oilfield services contractors capture expanding scope through integrated service agreements.
The Bureau of Safety and Environmental Enforcement enforces blowout preventer certification and well control mandates that dictate equipment procurement specifications across all federal leases. BOEM's five-year leasing program and supplemental environmental impact statements determine tract availability and operator bidding intensity. The Coast Guard's facility response plan requirements shape spill containment inventory levels and response vessel contracting. Stakeholders must monitor how electrification of offshore platforms and carbon capture integration into existing infrastructure alter project sanctioning timelines and partnership structures.
Market Dynamics
The Bureau of Ocean Energy Management's five-year leasing program is compressing operator bidding windows while EPA methane standards force rapid capital redeployment toward detection and mitigation infrastructure across federal waters.
Growth Catalysts
- Petrochemical Feedstock Demand:Gulf Coast refineries are expanding cracking capacity for ethylene and propylene derivatives, pulling additional barrel volumes through Louisiana and Texas offshore corridors.
- BOEM Lease Stipulations:Accelerated tract release schedules under supplemental environmental impact statements are concentrating operator capital deployment into proven deepwater fairways.
- Subsea Tieback Architecture:Multiphase boosting and all-electric tree systems are unlocking stranded reserves at Lower Tertiary and Wilcox depths beneath salt canopies.
Market Restraints
- Specialized Rig Supply Concentration:Dynamically positioned drillships capable of 10,000-foot operations are concentrated among a limited contractor pool, creating dayrate volatility during sanctioning windows.
- Blowout Preventer Certification Friction:Bureau of Safety and Environmental Enforcement well control mandates extend equipment procurement timelines and compress project sanctioning flexibility.
- Electrification Capex Burden:Platform electrification requirements and carbon capture integration studies are extending front-end engineering durations before final investment decisions.
Strategic Opportunities
- Carbon Capture Integration:Existing offshore infrastructure offers injection geology for sequestered CO2, with the EPA providing Class VI permitting pathways for depleted reservoir utilization.
- LNG Export Terminal Proximity:Texas-Louisiana coastal liquefaction facilities create offtake optionality for associated gas production from ultra-deepwater developments.
- All-Electric Subsea Convergence:Integration of subsea processing with renewable power from coastal grids is reducing offshore emissions intensity and extending field economic life.
Industry Challenges
- Deepwater Geoscience Talent Scarcity:Interpretation of seismic imaging beneath salt canopies requires specialized geophysicist expertise that has not replenished through academic pipelines.
- Legacy Platform Decommissioning Liability:Shelf-margin infrastructure installed in the 1970s-1980s requires costly plug-and-abandonment execution under Coast Guard facility response plan oversight.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf of Mexico Oil and Gas Market |
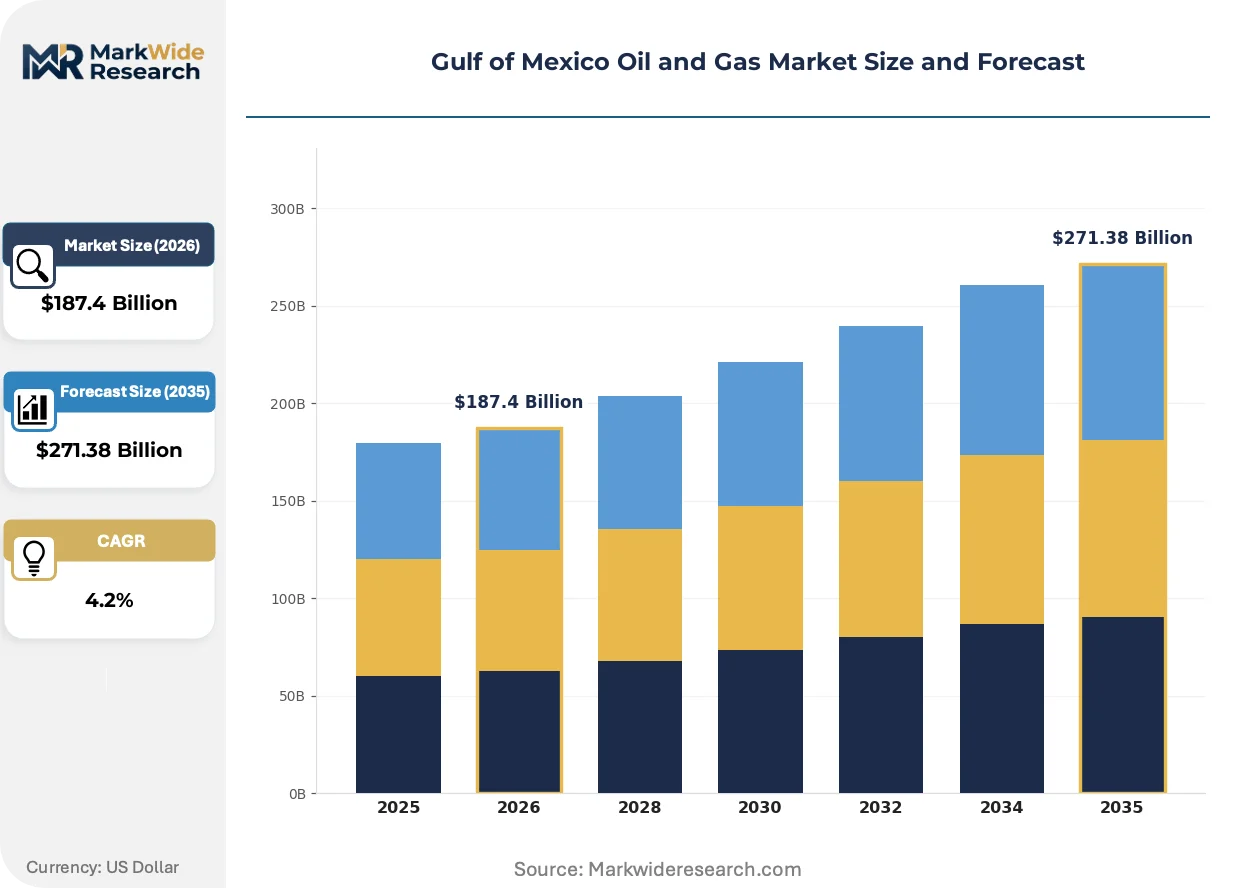
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Transportation Application: Offshore Platforms, Subsea Systems, Pipeline Infrastructure, Mobile Units End User: Energy Companies, Government Agencies, Contractors, Oilfield Services Technology: Hydraulic Fracturing, Seismic Imaging, Digital Twin, Automation Solutions |
| Companies Covered | ExxonMobil Corp., Oxy, Chevron Corporation, Enverus, Phillips 66, Shell Plc, ConocoPhillips, Entergy, BP Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf of Mexico Oil and Gas Market Shifts & Advancements
Subsea electrification and autonomous inspection systems are compressing operational expenditure structures while regulatory pressure on methane intensifies detection technology deployment across the Outer Continental Shelf.
All-electric subsea production systems are expanding into ultra-deepwater developments where hydraulic umbilical reliability degrades at extreme depths. Operators at Mars and Appomattox hub complexes are deploying these architectures to reduce topside footprint and enable longer tieback distances. The technology is expanding into previously uneconomic satellite fields by eliminating hydraulic fluid intervention requirements and reducing subsea hardware complexity.
EPA methane emissions standards for offshore sources are mandating continuous monitoring equipment across all federal lease production facilities. The regulation requires optical gas imaging and sensor networks that feed real-time data to Bureau of Safety and Environmental Enforcement reporting systems. Deepwater operators are responding by integrating drone-based inspection and satellite flare monitoring into their facility response plans to maintain compliance without manned platform visits.
Integrated service agreements are consolidating procurement scope under single-contractor accountability for drilling, completions, and subsea installation. Major operators are displacing fragmented vendor management with performance-based contracts that transfer risk to oilfield services contractors. This pattern is most visible in Louisiana offshore corridors where Shell and Chevron have compressed supplier rosters to reduce interface management overhead during project execution.
Gulf of Mexico Oil and Gas Market Segmentation
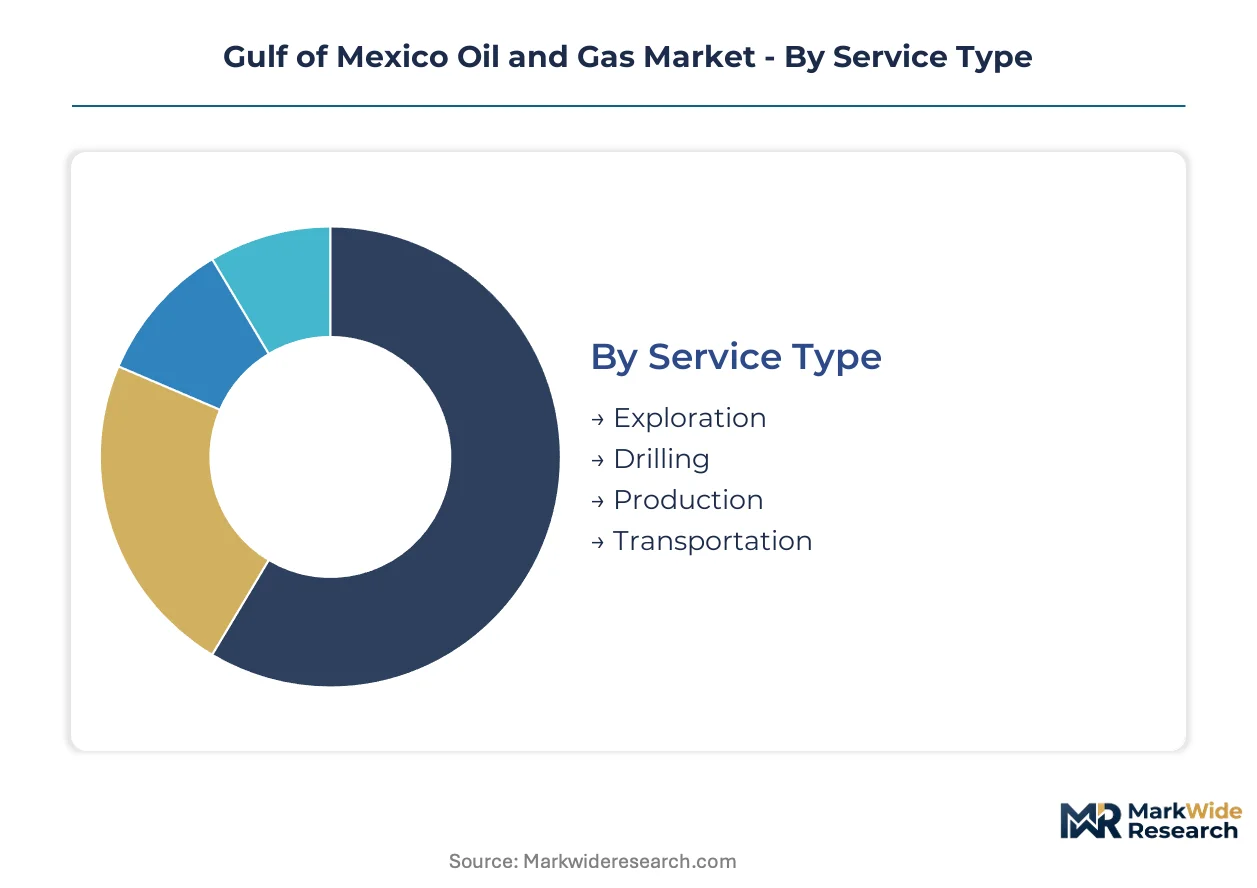
Segmentation in the Gulf of Mexico oil and gas market reveals how capital deployment, regulatory exposure, and technology adoption vary across operational layers. Each dimension carries distinct margin profiles and partnership requirements that shape operator strategy across federal waters.
Service Type:
Capital intensity escalates dramatically from surface reconnaissance through subsea completion, with drilling and production phases consuming the preponderance of deployed funds across ultra-deepwater developments.
- Exploration:Seismic acquisition and geophysical interpretation identify prospective reservoirs beneath salt canopies. Demand concentrates at Lower Tertiary and Wilcox fairways offshore Louisiana where BOEM lease stipulations compress bidding windows and accelerate appraisal timelines.
- Drilling:Dynamically positioned drillships and semisubmersible rigs execute wells to 10,000-foot depths below the mudline. Premium dayrates dominate this segment as limited contractor availability for ultra-deepwater capable units creates supply friction during sanctioning cycles.
- Production:Subsea tieback architecture and platform processing handle hydrocarbon extraction and initial separation.
- Transportation:Pipeline gathering systems and shuttle tanker operations move crude and gas to coastal refineries and LNG export terminals.
Most installed capacity flows through Production. Expansion is steepest in Drilling.
Application:
Physical infrastructure type determines regulatory jurisdiction, with fixed platforms falling under Coast Guard facility response plans while subsea installations trigger Bureau of Safety and Environmental Enforcement well control mandates.
- Offshore Platforms:Fixed and floating production facilities process hydrocarbons at the surface. Gulf Coast petrochemical feedstock demand pulls volumes through hub complexes at Mars and Appomattox where electrification requirements are extending front-end engineering durations.
- Subsea Systems:Multiphase boosting and all-electric trees handle processing at the seabed. Capital is flooding into this architecture as operators eliminate hydraulic umbilical reliability risks at extreme depths and reduce topside footprint.
- Pipeline Infrastructure:Export lines and infield gathering systems connect wells to shore.
- Mobile Units:Drillships and semisubmersibles provide exploratory and development drilling capacity.
Subsea Systems command the highest growth trajectory as salt-canopy developments multiply. Offshore Platforms retain the largest installed base.
End User:
Risk allocation patterns diverge sharply between capital-owning operators and service-executing contractors, with integrated service agreements compressing traditional procurement boundaries.
- Energy Companies:Supermajors and independents hold federal leases and sanction development projects. Shell and Chevron anchor demand through hub-and-spoke architectures that concentrate procurement scope under performance-based contracts.
- Government Agencies:BOEM and BSEE regulate leasing, environmental compliance, and safety enforcement.
- Contractors:Engineering, procurement, and construction firms execute platform and subsea installation.
- Oilfield Services:Drilling, completions, and intervention specialists provide equipment and crews.
Energy Companies direct the preponderance of capital commitment. Oilfield Services is expanding most quickly through integrated service agreements.
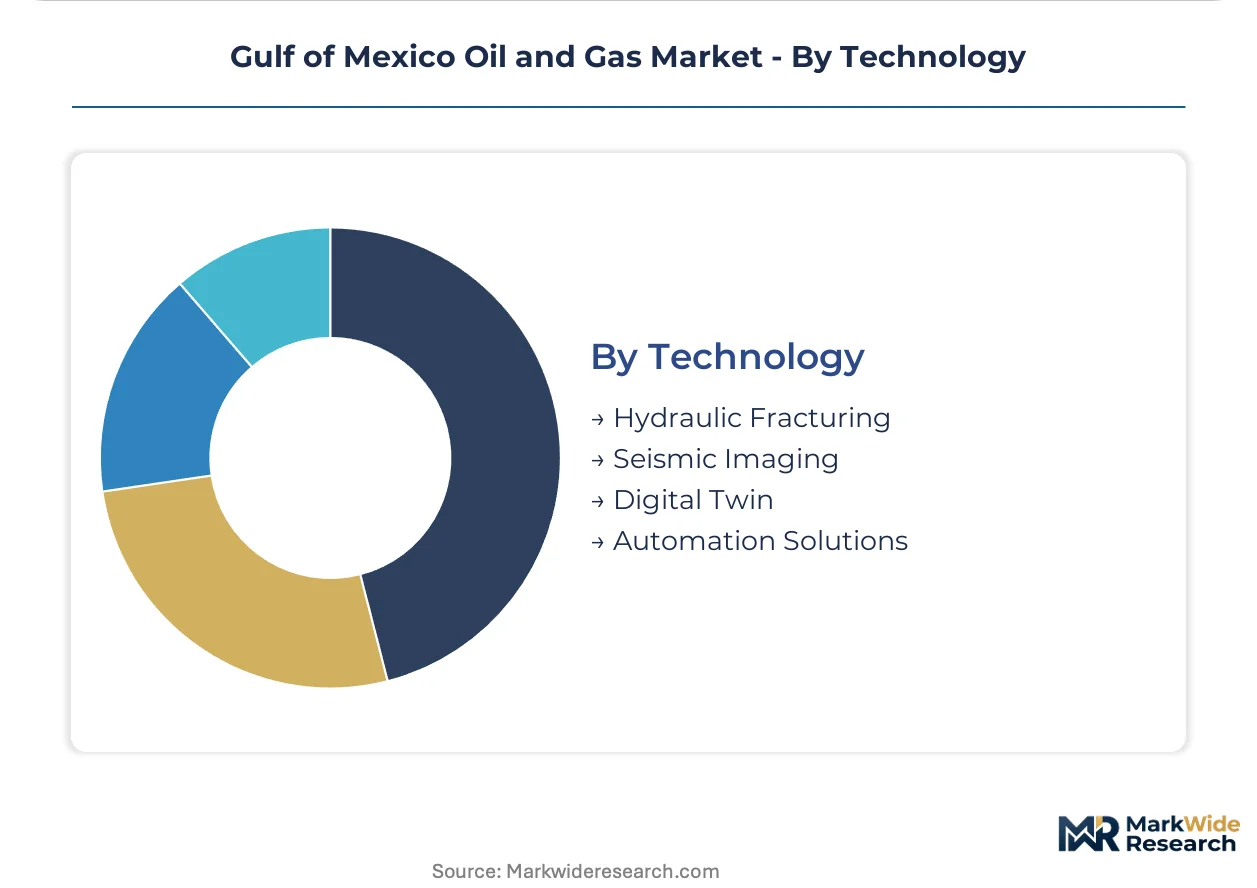
Technology:
Digital and automated solutions are displacing conventional mechanical systems as EPA methane standards and electrification mandates force detection and emissions reduction investments.
- Hydraulic Fracturing:Pressure pumping operations stimulate tight formations in shelf-margin assets. Oxy deploys this technique across legacy Permian-adjacent Gulf properties to sustain enhanced oil recovery economics.
- Seismic Imaging:Advanced processing resolves geologic structure beneath salt canopies. Talent scarcity in specialized geophysicist expertise constrains deployment velocity despite strong operator demand for Lower Tertiary targeting.
- Digital Twin:Virtual facility replicas optimize production and predict maintenance requirements.
- Automation Solutions:Remote monitoring and autonomous inspection reduce manned platform exposure.
Seismic Imaging retains dominant deployment share. Automation Solutions is climbing the fastest as continuous methane monitoring becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf of Mexico petroleum province originated from mid-20th century offshore discoveries off Louisiana, establishing the basin as the cradle of deepwater production technology. Federal leasing programs subsequently expanded operations across the Outer Continental Shelf into Texas and Mexican waters.
Louisiana Offshore
Lower Tertiary and Wilcox formations beneath salt canopies drive appraisal drilling around Mars and Appomattox hub complexes. BOEM supplemental environmental impact statements compress bidding windows for central Gulf lease sales. Port Fourchon serves as the primary logistics base for dynamically positioned drillship mobilization and subsea equipment staging.
Texas Offshore
Associated gas production from ultra-deepwater developments feeds LNG export terminals along the Sabine-Neches industrial waterway. EPA methane emissions standards mandate continuous monitoring equipment across federal lease production facilities. Corpus Christi anchors pipeline gathering systems connecting shelf-margin assets to coastal refineries and petrochemical complexes.
Federal Deepwater Corridors
Multiphase boosting and all-electric tree systems unlock stranded reserves at depths exceeding 10,000 feet below the mudline. Bureau of Safety and Environmental Enforcement blowout preventer certification requirements extend equipment procurement timelines for Lower Tertiary targets. Subsea tieback architecture from Anchor and Ballymore developments reduces topside footprint across the Alaminos Canyon and Walker Ridge protraction areas.
Mexican Waters
Reform-era energy liberalization opened deepwater blocks in the Perdido Fold Belt and Salina Basin to international operators. Mexico's National Hydrocarbons Commission regulates licensing rounds and production-sharing contract terms for Gulf prospects. Ciudad del Carmen and Tampico serve as emerging supply bases for cross-border drilling campaigns targeting Wilcox-equivalent formations.
Gulf of Mexico Oil and Gas Market Competitive Landscape
Premium-margin players sit above commodity-margin players across water depth capability and subsea technology integration. Supermajors dominate ultra-deepwater lease holdings through hub-and-spoke architectures that concentrate capital deployment. Two strategic archetypes prevail: integrated operators with proprietary subsea engineering capabilities, and independent producers leveraging enhanced oil recovery across legacy shelf-margin assets. Competitive moves center on integrated service agreements that transfer execution risk to contractors, and portfolio high-grading toward Lower Tertiary fairways with established infrastructure corridors.
Within the integrated operator tier, Shell Plc and Chevron Corporation exemplify hub-complex strategies that anchor regional production economics. Oxy occupies a position among independents sustaining shelf-margin competitiveness through enhanced recovery programs. These three entities represent distinct capital allocation philosophies across the depth spectrum from ultra-deepwater to mature shallow-water assets.
| Leading Market Players |
|---|
| ExxonMobil Corp. |
| Oxy |
| Chevron Corporation |
| Enverus |
| Phillips 66 |
| Shell Plc |
| ConocoPhillips |
| Entergy |
| BP Plc |
| Others |
Supply & Pricing Matrix
Ultra-deepwater dayrate premiums versus shelf-margin commoditization create a bifurcated cost structure that concentrates procurement power among drillship contractors while squeezing legacy platform economics. This divergence manifests in capital allocation patterns where operators pay scarcity rents for dynamically positioned units capable of 10,000-foot Lower Tertiary targets, yet face margin compression across mature assets requiring enhanced recovery investment.
Pricing Analysis
Project-based long-term offtake contracts dominate ultra-deepwater developments, with pricing stratifying across premium, standard, and economy tiers based on water depth capability and subsea technology integration. Price differentiation hinges on rig specification tier and BOEM lease tract competitiveness, with premium dayrates commanded by 10,000-foot capable drillships. Cost compression in shelf-margin drilling reflects oversupply of jack-up units and aging platform infrastructure. Independent producers exhibit highest price sensitivity due to capital constraints, while supermajors absorb premium tier costs for strategic lease retention.
Supply Chain Analysis
Domestic-content mandates under the Jones Act reshape sourcing for offshore construction and marine transport, requiring US-flagged vessels for coastwise movement of platform modules and subsea hardware. Geographic supply concentration centers on Texas and Louisiana fabrication yards, with critical component dependencies including blowout preventers from Houston-based manufacturers, subsea trees from European engineering centers, and specialty steel from domestic mills. Single-source vulnerability persists in dynamic positioning systems and subsea umbilical manufacturing. Distribution runs through Port Fourchon and Corpus Christi logistics hubs serving federal lease corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through subsea electrification capex efficiency and carbon capture integration into existing infrastructure corridors. Premium-tier shift toward all-electric tree systems and multiphase boosting architectures enables operators to extend field economic life while reducing operational expenditure burdens.
For Market Incumbents: Deploy integrated service agreements that transfer execution risk to oilfield services contractors and compress supplier rosters. Shell and Chevron's hub-and-spoke architectures demonstrate how proprietary subsea engineering capabilities defend against independent encroachment. Reinforce position through enhanced oil recovery program investment across legacy shelf-margin assets before decommissioning liabilities accelerate. Electrification mandates from EPA methane standards threaten operators lacking detection infrastructure, making early compliance capex a defensive priority.
For New Entrants and Emerging Players: Begin with carbon capture integration services targeting depleted reservoir utilization under EPA Class VI permitting pathways. Mexican waters in the Perdido Fold Belt offer the most penetrable geography given reform-era licensing rounds and underdeveloped infrastructure relative to US fairways. Target subsea inspection and autonomous monitoring technologies where drone-based optical gas imaging meets mandatory EPA continuous monitoring requirements without manned platform exposure.
For Investors and Strategic Acquirers: Consolidation pressure builds where legacy platform decommissioning liabilities exceed production economics and operators lack capital for plug-and-abandonment execution. Long-term viability favors integrated operators with proprietary subsea engineering capabilities and established Lower Tertiary infrastructure corridors. Acquisition target archetype: independents with enhanced oil recovery expertise and Permian-adjacent Gulf asset positions. Signal to watch: BOEM lease stipulation acceleration that compresses bidding windows and forces portfolio high-grading decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Electrification Deployment | All-electric tree systems reduce topside footprint and extend tieback distances at Mars and Appomattox hubs. |
| Carbon Capture Integration | Depleted reservoir utilization under EPA Class VI permits creates injection geology for sequestered CO2 streams. |
| Integrated Service Agreements | Performance-based contracts transfer execution risk to contractors across Louisiana offshore corridors. |
| Enhanced Oil Recovery Expansion | Hydraulic fracturing programs sustain shelf-margin competitiveness at Oxy's Permian-adjacent Gulf properties. |
| Autonomous Inspection Technology | Drone-based optical gas imaging maintains EPA methane compliance without manned platform visits. |
Research Methodology
Coverage spans federal waters offshore Louisiana and Texas plus Mexican deepwater blocks, with primary inputs from each jurisdiction's regulatory and operator communities. The analysis combines interviews with BOEM leasing specialists, BSEE safety enforcement officers, deepwater project sanctioning executives, and subsea engineering directors with secondary validation through BOEM lease sale records, BSEE incident databases, EPA enforcement and compliance history, and Coast Guard facility response plan filings. Bottom-up field-level production economics and top-down basin-wide capital deployment patterns undergo triangulation to reconcile segment-level estimates.
Granularity-level modeling distinguishes water depth tiers, subsea technology architecture types, and regulatory compliance cost burdens across the projection horizon. Segmentation dimensions include service type, application infrastructure, end-user risk allocation patterns, and technology adoption curves. CAGRs derive from production volume trajectories, capital deployment schedules, and dayrate elasticity assumptions. Industry-specific forecast inputs incorporate BOEM five-year leasing program tract release schedules and EPA methane detection equipment mandate implementation timelines.
Caveats apply where BOEM supplemental environmental impact statement delays, BSEE blowout preventer certification backlogs, or Jones Act vessel availability constraints could materially shift the outlook. Forecasts reflect assumptions regarding operator bidding intensity, contractor fleet utilization, and regulatory enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market