
 South Sudan Oil and Gas Downstream Market | 2026-2036
South Sudan Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
South Sudan Oil and Gas Downstream Market Analytics
South Sudan's downstream petroleum licensing regime is recalibrating capital deployment thresholds for new refinery entrants. Nile Petroleum Corporation leverages its state-backed mandate to dominate fuel importation and strategic reserve management. China National Petroleum Corporation anchors operational control through its integrated upstream-to-downstream presence in the Melut Basin corridor. Petronas competes via technical service agreements that sustain its refining advisory role despite limited direct asset ownership.
The South Sudan oil and gas downstream sector encompasses refining, storage, distribution, and marketing of petroleum products derived from crude oil processed within or imported into the country, with typical refinery operations targeting distillation capacities below 10,000 barrels per day given infrastructure constraints. Refined fuels constitute the dominant product category, absorbing the majority of import volumes and distribution capacity across wholesale and retail channels. Petrochemicals represent the fastest-growing segment as industrial users in manufacturing and commercial end-use categories seek alternatives to fully imported chemical feedstocks. The supply chain stage dimension reveals margin pools concentrating with importers and large distributors who control storage terminals in Juba and Malakal.
The Ministry of Petroleum and the country's national standards body shape product quality enforcement and import licensing timelines, while environmental directives from the central government influence storage facility siting and emissions protocols. The central bank's foreign exchange regulations directly determine fuel import financing accessibility and working capital cycles for downstream operators. Stakeholders must monitor regulatory harmonization progress between national authorities and neighboring East African Community frameworks to anticipate cross-border product flow liberalization.
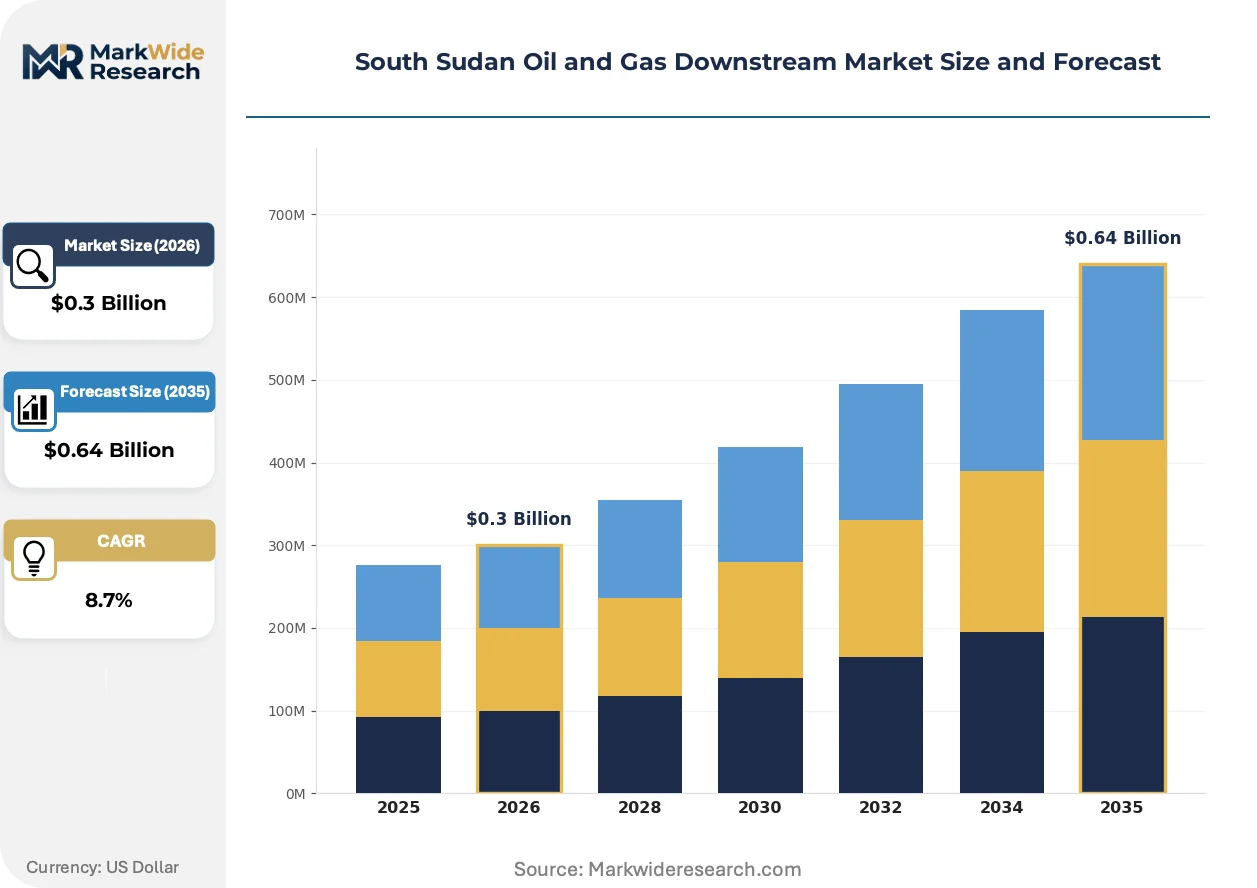
Market Dynamics
The South Sudan Ministry of Petroleum's streamlined refinery licensing framework is recalibrating capital deployment thresholds, pulling private investors toward modular processing units while Nile Petroleum Corporation maintains its grip on importation corridors.
Growth Catalysts
- Power Generation Fuel Demand:Juba's emerging distribution network is expanding offtake volumes as electricity utilities diversify from diesel-dependent generation. Central Equatoria State clustering accelerates infrastructure amortization.
- Petrochemical Feedstock Localization:Manufacturing end-users in commercial sectors seek alternatives to fully imported chemical inputs. Industrial processors are commissioning small-scale cracking units for solvent and fertilizer precursor production.
- East African Community Harmonization:Cross-border product flow liberalization talks are advancing regulatory alignment between national authorities. Border clearance protocols for refined fuels are simplifying at Nimule and Kaya entry points.
Market Restraints
- Foreign Exchange Access Bottlenecks:The Bank of South Sudan's currency rationing regime compresses working capital cycles for fuel importers. Letters of credit for petroleum product procurement face extended approval timelines.
- Upstream Supply Concentration:Melut Basin production corridors dominate crude availability for any prospective domestic refining. Pipeline disruptions at the Sudan border constrain feedstock security for downstream planners.
- Refinery Scale Economics:Sub-10,000 barrel per day distillation capacities face inherent efficiency penalties against regional mega-refinery imports. Unit operating costs remain structurally elevated versus coastal Mombasa or Port Sudan supply.
Strategic Opportunities
- Malakal Storage Hub Expansion:Strategic reserve capacity additions at Upper Nile state terminals would capture transshipment flows toward Ethiopia and eastern South Sudan. Riverine barge distribution from Sobat corridor terminals reduces road freight exposure.
- Renewable Diesel Blending Mandates:Draft biofuel integration standards under national energy transition planning create offtake certainty for agricultural waste-to-fuel processors. Juba's urban air quality directives are accelerating pilot project approvals.
- Digital Inventory Management Convergence:IoT-enabled tank monitoring and blockchain-based custody transfer systems are reducing product losses in transit. Terminal operators are piloting automated reconciliation platforms with retail network partners.
Industry Challenges
- Skilled Technician Scarcity:Refinery process engineering and pipeline maintenance expertise remains concentrated among expatriate workforces. Local vocational training pipelines for instrumentation and corrosion control are underdeveloped.
- Storage Facility Siting Compliance:Environmental impact assessments for new tank farms face prolonged review cycles under evolving emissions protocols. Groundwater protection mandates are constraining Juba periphery land availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Sudan Oil and Gas Downstream Market |
| Market Size in 2026 | $0.3 Billion |
| Market Size in 2035 | $0.64 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Lubricants, Petrochemicals, Specialty Chemicals Distribution Channel: Wholesale, Retail, Direct Sales, Online Retail End User: Transportation, Power Generation, Manufacturing, Commercial Supply Chain Stage: Importers, Distributors, Retailers, End Consumers |
| Companies Covered | Nile Petroleum Corporation, Petroliam Nasional Berhad (Petronas), China National Petroleum Corporation, Akon Refinery Company Limited, ONGC Videsh Ltd., Sinopec Group, Greater Nile Petroleum Operating Company, Lundin Energy, OMV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Sudan Oil and Gas Downstream Market Evolving Landscape
Downstream operators are reconfiguring around distributed processing architectures and digital supply chain transparency, with regulatory pressure on product quality enforcement accelerating capital redirection toward modular infrastructure.
Containerized refining skids are modularizing crude-to-product conversion for remote field operations. Mining camps and agricultural processing zones in Western Equatoria and Lakes states are deploying 500-2,000 barrel per day barge-mounted units. This technology is compressing the viable radius between production clusters and consumption centers, reducing reliance on Juba-centric distribution.
South Sudan's national standards body is tightening sulfur content specifications for imported diesel and gasoline, aligning with East African Community quality benchmarks. Refinery permit applicants must now demonstrate product testing laboratory partnerships or in-house chromatography capabilities. Importers and large distributors controlling Juba and Malakal terminals are pre-positioning lower-sulfur cargo to avoid detention risks at discharge.
Wholesale fuel buyers are consolidating procurement through volume-pooled tenders administered by cooperative associations. Construction contractors and transport fleet operators in Central Equatoria are displacing spot market purchases with quarterly framework agreements. This pattern is most visible among cement manufacturers and logistics groups operating the Juba-Nimule corridor.
South Sudan Oil and Gas Downstream Market Segmentation
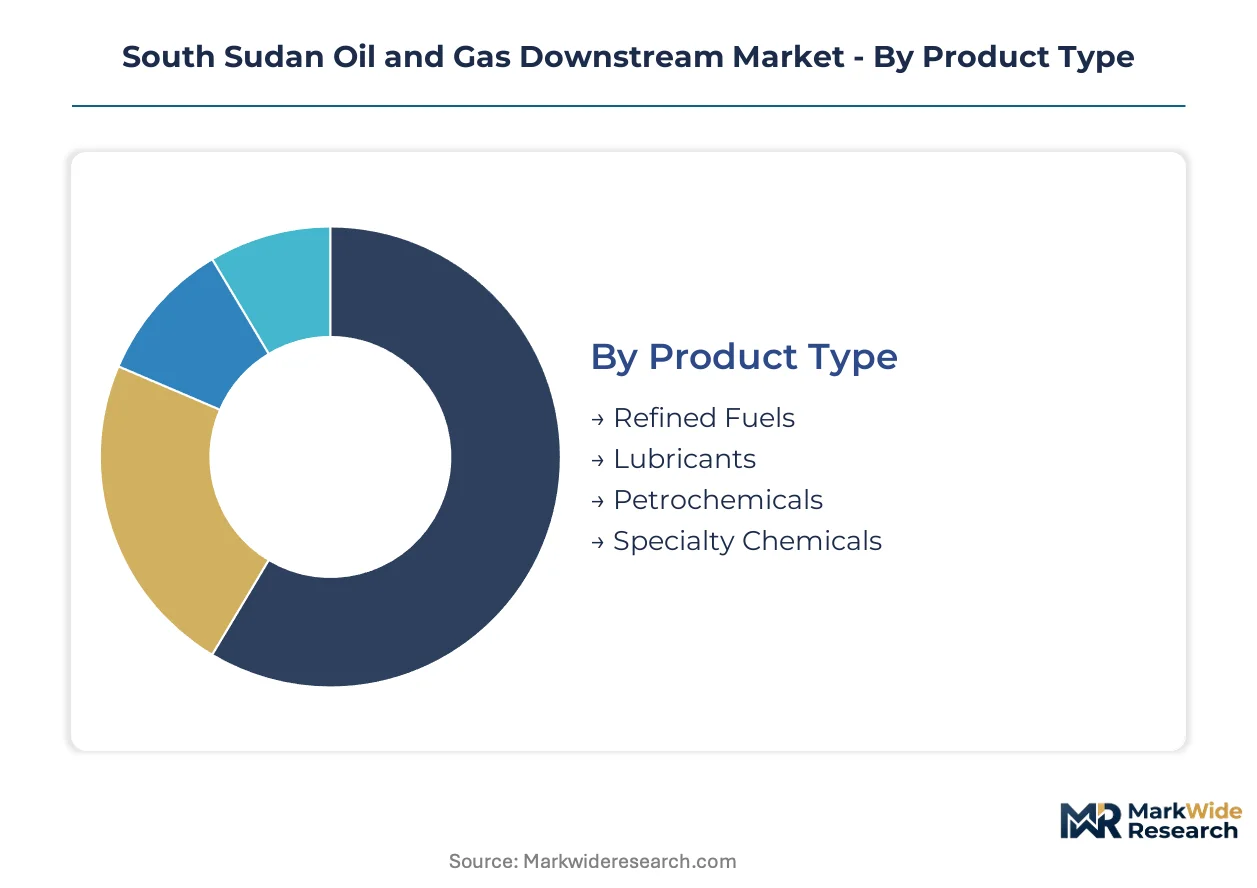
Downstream segmentation in South Sudan reflects the country's import-dependent fuel economy and nascent domestic processing capacity. Understanding product flows across channels and end-use categories exposes where margin pools concentrate and where infrastructure gaps persist.
Product Type:
Volume-heavy refined fuels absorb the majority of working capital and storage capacity, while petrochemicals command premium pricing despite thinner throughput.
- Refined Fuels:Gasoline, diesel, and kerosene constitute the bulk of import volumes and distribution infrastructure utilization. Power generation utilities in Juba and transport fleets along the Nimule corridor drive concentrated offtake, though foreign exchange rationing periodically disrupts procurement cycles.
- Petrochemicals:Solvents, fertilizers, and plastic precursors represent the steepest expansion trajectory as manufacturing end-users seek alternatives to fully imported chemical feedstocks. Small-scale cracking units in Central Equatoria are localizing production of basic industrial inputs.
- Lubricants:Engine oils and industrial greases serve mining equipment and agricultural machinery operators in Western Equatoria.
- Specialty Chemicals:Drilling fluids and refinery process additives support upstream operations in the Melut Basin corridor.
Today's leader: Refined Fuels. Tomorrow's challenger: Petrochemicals.
Distribution Channel:
Channel selection tracks customer scale and creditworthiness, with wholesale consolidation accelerating among large-volume buyers.
- Wholesale:Volume-pooled tenders administered by cooperative associations now dominate procurement for construction contractors and cement manufacturers. Quarterly framework agreements are displacing spot market purchases across Central Equatoria.
- Retail:Service stations and independent fuel depots serve fragmented transport and agricultural demand in Lakes and Jonglei states.
- Direct Sales:Mining camps and industrial processors receive bulk deliveries bypassing intermediary storage.
- Online Retail:Digital platforms for lubricant and specialty chemical ordering remain embryonic, constrained by payment infrastructure gaps.
Wholesale channels capture margin concentration. Direct sales are gaining fastest among industrial accounts.
End User:
End-use demand clusters geographically, with Central Equatoria absorbing disproportionate volumes due to infrastructure concentration.
- Transportation:Road freight operators and passenger vehicle fleets along the Juba-Nimule corridor constitute the largest diesel offtake segment.
- Power Generation:Electricity utilities diversifying from diesel-dependent generation are expanding fuel offtake from Juba's emerging distribution network.
- Manufacturing:Cement plants and food processors in Central Equatoria drive industrial fuel demand and petrochemical feedstock interest.
- Commercial:Construction equipment and agricultural machinery operators in Western Equatoria and Upper Nile states absorb lubricant and refined fuel volumes.
Transportation anchors current volumes. Power generation is climbing fastest as grid expansion proceeds.
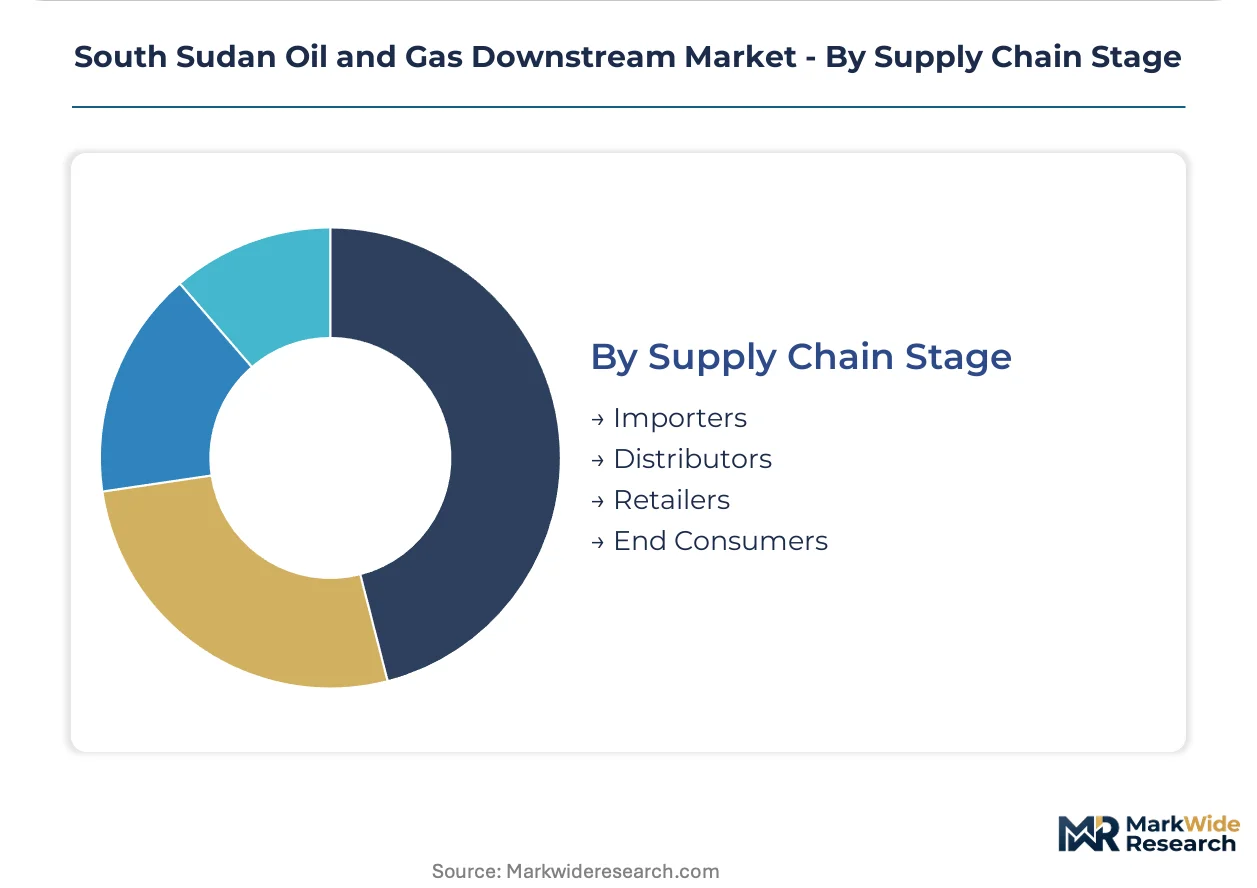
Supply Chain Stage:
Margin accumulation favors actors controlling storage terminals and import licenses, with regulatory barriers limiting downstream entry.
- Importers:Nile Petroleum Corporation dominates fuel importation and strategic reserve management through its state-backed mandate, while private operators face extended letters of credit approval timelines.
- Distributors:Large distributors controlling Juba and Malakal storage terminals capture margin pools between discharge and retail handoff.
- Retailers:Service station operators and independent depots manage last-mile delivery to fragmented end-users across state capitals.
- End Consumers:Industrial accounts and utilities with direct import relationships occasionally bypass standard distribution tiers.
Importers retain structural advantage. Distributors are consolidating fastest through terminal capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical expertise for refinery operations and pipeline maintenance concentrates among expatriate workforces in Juba and Malakal, with local vocational training pipelines for instrumentation and corrosion control still under development.
Central Equatoria State
Power generation utilities and transport fleets drive diesel offtake volumes along the Juba-Nimule corridor. The Ministry of Petroleum's streamlined refinery licensing framework is recalibrating capital deployment thresholds for private investors. Juba's emerging distribution network is expanding fuel offtake as electricity utilities diversify generation sources.
Upper Nile State
Mining camps and agricultural processors in the Sobat corridor absorb bulk fuel deliveries and lubricant volumes. The country's national standards body shapes product quality enforcement and import licensing timelines for terminal operators. Malakal storage terminals capture margin pools between discharge and retail handoff across the region.
Western Equatoria
Construction equipment and agricultural machinery operators generate concentrated demand for refined fuels and industrial greases. Environmental directives from the central government influence storage facility siting and emissions protocols in this periphery zone. Containerized refining skids are modularizing crude-to-product conversion for remote field operations near mining camps.
Lakes State
Service stations and independent fuel depots serve fragmented transport and agricultural demand across rural distribution networks. The central bank's foreign exchange regulations directly determine fuel import financing accessibility for downstream operators. Barge-mounted processing units are reducing reliance on Juba-centric distribution through riverine logistics.
Jonglei State
Road freight operators and passenger vehicle fleets constitute diesel offtake across limited paved infrastructure corridors. Cross-border product flow liberalization talks are advancing regulatory alignment with neighboring East African Community frameworks. Border clearance protocols for refined fuels are simplifying at entry points serving this eastern zone.
South Sudan Oil and Gas Downstream Market Competitive Landscape
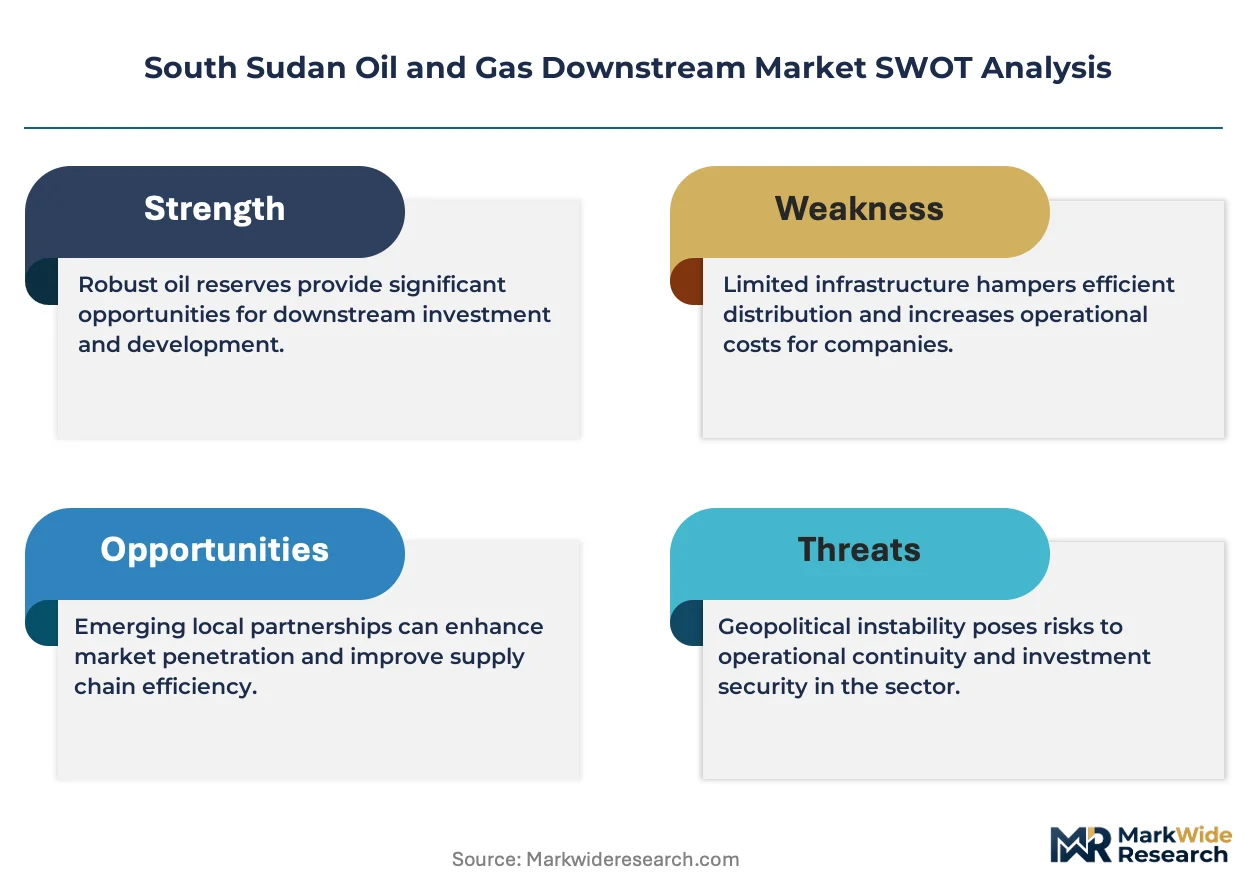
Diversified conglomerates compete with focused pure-play specialists across South Sudan's downstream petroleum sector. State-backed enterprises dominate fuel importation corridors and strategic reserve management, while private operators face extended letters of credit approval timelines. Two strategic archetypes prevail: integrated upstream-to-downstream operators leveraging basin control, and technical service providers sustaining advisory roles through contractual relationships. Competitive moves concentrate on terminal capacity expansion and modular refinery permitting.
Among state-affiliated operators, Nile Petroleum Corporation exemplifies the integrated archetype through its mandate over importation and reserve management. China National Petroleum Corporation anchors operational positioning through its presence in the Melut Basin corridor. Petronas occupies a position within the technical advisory tier, sustaining refining consultation relationships despite limited direct asset ownership.
| Leading Market Players |
|---|
| Nile Petroleum Corporation |
| Petroliam Nasional Berhad (Petronas) |
| China National Petroleum Corporation |
| Akon Refinery Company Limited |
| ONGC Videsh Ltd. |
| Sinopec Group |
| Greater Nile Petroleum Operating Company |
| Lundin Energy |
| OMV |
| Others |
Value Network & Pricing Analysis
Platts Singapore fuel oil benchmarks cascade through South Sudan's import-dependent downstream sector, compressing margin pools for distributors unable to pass through currency-driven cost spikes to end-users in Central Equatoria and Upper Nile states.
Pricing Analysis
Bundled logistics-plus-product contracts dominate wholesale procurement, while unbundled spot purchases persist among fragmented retail operators. Three-tier pricing structure across premium, standard, and economy levels reflects sulfur content specifications and delivery reliability guarantees. Cost compression in the standard tier is intensifying because Bank of South Sudan foreign exchange rationing extends letter-of-credit timelines. Transport fleet operators exhibit highest price sensitivity, while mining camps with captive generation show lowest elasticity due to operational continuity requirements.
Supply Chain Analysis
Dual-sourcing requirements from power utilities and industrial processors mandate qualification of at least two import channels, typically combining Nile Petroleum Corporation allocations with private trader volumes. Supply concentrates in Sudan, Kenya, and Uganda as overland and riverine entry points. Feedstock security rests on Melut Basin crude availability, refined product import financing, and diesel cargo quality certification. Single-source vulnerability runs through the Nimule corridor pipeline disruptions. Distribution runs through Juba and Malakal storage terminals controlled by large distributors with strategic reserve mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Sudan's downstream petroleum sector operates as a regulatory compounder, where Ministry of Petroleum licensing milestones for modular refineries are accelerating capital deployment toward domestic processing capacity.
For Market Incumbents: Cement terminal capacity control in Malakal and Juba to defend margin capture between discharge and retail handoff. Deepen backward integration into strategic reserve management through Nile Petroleum Corporation partnership structures. Invest in sulfur testing laboratory capabilities ahead of East African Community quality harmonization deadlines.
For New Entrants and Emerging Players: Launch via containerized refining skid deployment to mining camps in Western Equatoria and agricultural processing zones in Lakes State. Target petrochemical feedstock localization as the most penetrable segment, bypassing refined fuel import competition. Pursue technical service agreements with existing upstream operators to secure crude offtake commitments.
For Investors and Strategic Acquirers: Consolidation pressure builds where foreign exchange rationing compresses working capital cycles below sustainable thresholds for independent fuel importers. Long-term viability favors operators with integrated storage-terminal-distribution footprints and state-backed import licenses. Watch for regulatory harmonization completion with East African Community frameworks as the inflection signal for cross-border product flow liberalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Refinery Permitting | Streamlined licensing from Ministry of Petroleum reduces capital deployment thresholds for private investors. |
| Storage Hub Expansion | Malakal terminal capacity additions capture transshipment flows toward Ethiopia and eastern South Sudan. |
| Quality Certification Investment | In-house chromatography capabilities satisfy national standards body sulfur specification enforcement. |
| Digital Inventory Convergence | IoT-enabled tank monitoring reduces product losses for terminal operators across Juba distribution networks. |
| Riverine Logistics Integration | Barge-mounted processing units from Sobat corridor terminals reduce road freight exposure in Upper Nile. |
Research Methodology
Coverage spans Central Equatoria, Upper Nile, Western Equatoria, Lakes, and Jonglei states, with primary inputs from each region combined with secondary validation. Interviews with Ministry of Petroleum licensing officers, Nile Petroleum Corporation supply planners, terminal operators, power utility procurement managers, and mining camp logistics coordinators anchored demand-side intelligence. Secondary sources include Bank of South Sudan foreign exchange regulation circulars, East African Community trade harmonization protocols, national standards body product quality directives, and customs discharge records at Nimule and Kaya entry points. Bottom-up segment sizing triangulated against top-down macroeconomic absorption rates.
Granularity-level modeling deployed product type, distribution channel, end-user category, and supply chain stage dimensions at the state level across the projection horizon. CAGRs derived from trend extrapolation of import volume trajectories, infrastructure commissioning timelines, and regulatory milestone achievement patterns. Forecast inputs incorporated diesel substitution rates in power generation, petrochemical cracking unit commissioning schedules, and cross-border trade liberalization negotiation progress.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained foreign exchange rationing or pipeline disruption scenarios. Deviation in East African Community regulatory harmonization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Norway Oil and Gas Market
Offshore Oil and Gas
North Sea Oil and Gas Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market