
 Solid Vacuum Reclosers Market | 2026-2036
Solid Vacuum Reclosers Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Vacuum Reclosers Market Analytics
The gap between premium intelligent reclosers and commodity electromechanical units is shifting from a price spread into a capability chasm. ABB Ltd leverages embedded sensors and predictive analytics to command positions in utility smart-grid tenders. Eaton Corporation plc anchors its portfolio with arc-resistant vacuum interrupters designed for harsh climate zones. Siemens competes through integrated digital twin platforms that reduce commissioning cycles for large-scale deployments.
Solid vacuum reclosers are self-contained fault-interrupting devices that use vacuum interrupter technology—typically rated 15-38 kV with interrupting capacities up to 16 kA—to automatically isolate and restore power on overhead distribution lines after temporary faults. Their primary purpose is to minimize sustained outages by distinguishing transient disturbances from permanent faults without manual crew dispatch. Three phase configurations dominate utility procurement volumes due to their deployment on primary feeders serving mixed residential-industrial loads. Smart grid technology represents the fastest-expanding segment as utilities prioritize remote monitoring, fault location, and adaptive protection settings over conventional hydraulic control mechanisms. Pole-mounted installations retain the largest installed base but face margin compression from standardized designs, whereas pad-mounted units command premium positioning in urban underground distribution networks where space constraints and aesthetic requirements apply.
IEC 62271-111 and IEEE C37.60 establish the core performance and testing standards governing vacuum recloser design, with IEEE 1547 interconnection requirements additionally shaping product specifications for renewable energy integration scenarios. The US Federal Energy Regulatory Commission and state-level public utility commissions enforce reliability indices that directly incentivize automated switching investments, while the EU Green Deal and national grid modernization frameworks in Germany and France accelerate replacement of oil-filled reclosers with vacuum alternatives. Stakeholders must weigh the capital efficiency of conventional recloser upgrades against the operational flexibility of communications-enabled platforms as distributed energy resource penetration reshapes fault current profiles across distribution networks.
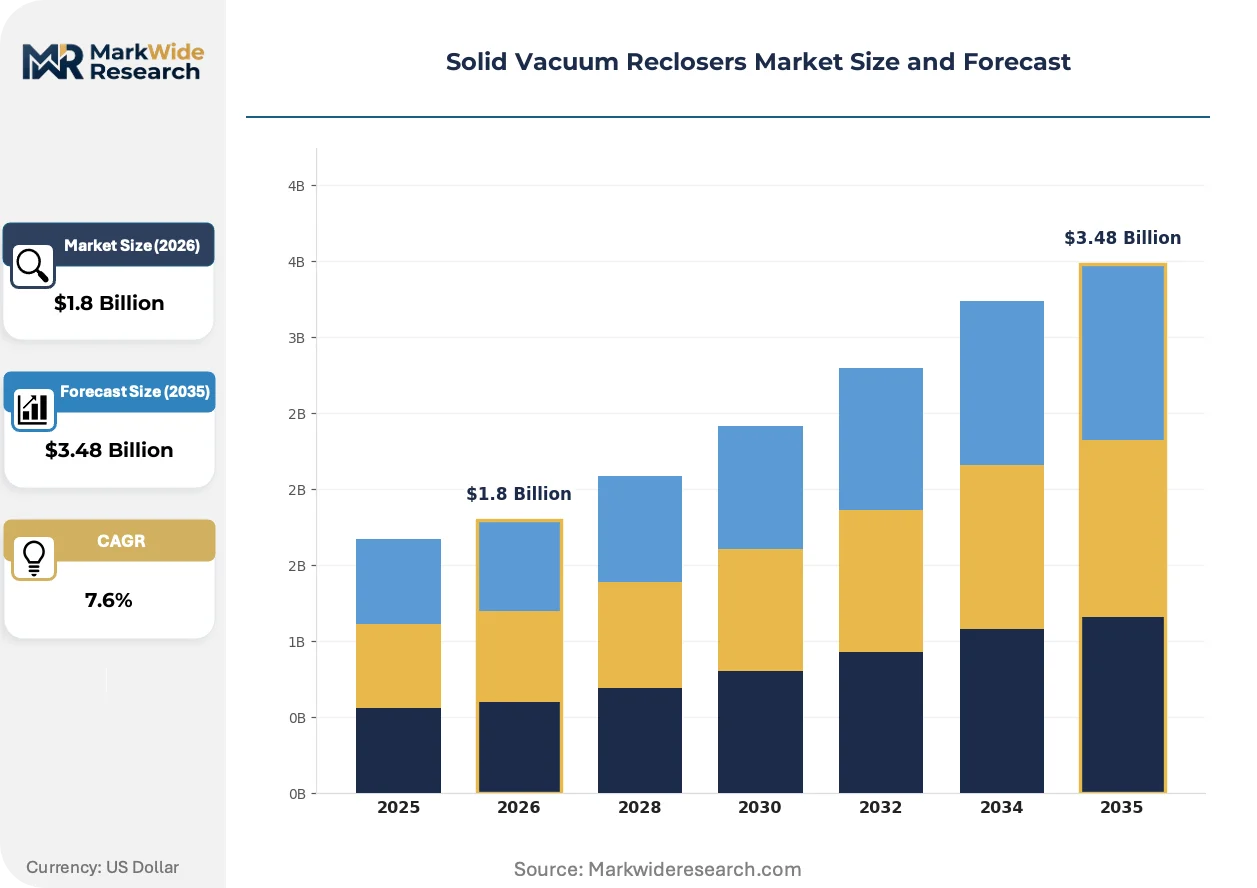
Market Dynamics
Grid modernization mandates and distributed renewable integration are forcing utilities to replace legacy electromechanical protection with intelligent vacuum reclosers capable of bidirectional fault detection and adaptive protection settings.
Growth Catalysts
- IEEE 1547 Interconnection Standards:US utilities must upgrade protection systems to accommodate solar and battery inflows, driving recloser replacements across California, Texas, and Florida distribution networks.
- Storm Hardening Programs:Electric cooperatives in hurricane-prone US states are prioritizing automated reclosers to reduce outage restoration times and avoid regulatory penalties for reliability index violations.
- Vacuum Interrupter Technology:The shift from oil-filled and SF6-based switchgear eliminates maintenance-intensive alternatives while extending equipment life cycles beyond twenty-five years.
Market Restraints
- Copper and Rare Earth Price Volatility:Vacuum interrupter assemblies depend on copper-chromium contacts and permanent magnet actuators, exposing manufacturers to commodity swings that compress margin on fixed-price utility tenders.
- Semiconductor Supply Concentration:Intelligent recloser controllers rely on industrial-grade microprocessors and communication modules sourced primarily from East Asian foundries, creating lead time vulnerability.
- Electromechanical Substitution Inertia:Budget-constrained municipal utilities in rural US districts continue specifying hydraulic reclosers despite higher lifecycle costs, delaying technology transitions.
Strategic Opportunities
- Underground Distribution Networks:Pad-mounted solid vacuum reclosers command premium positioning in urban US markets where space constraints and aesthetic requirements favor compact, low-profile installations over pole-mounted alternatives.
- Digital Twin Integration:Convergence of edge computing and physics-based simulation enables predictive maintenance models that reduce utility truck rolls and extend maintenance intervals.
- Inflation Reduction Act Grid Funding:Federal cost-sharing programs for resilience and clean energy integration create procurement acceleration opportunities across cooperative and municipal utility segments.
Industry Challenges
- IEC-IEEE Harmonization Delays:Divergent testing protocols between European and North American standards bodies complicate product certification for suppliers serving both markets.
- Cybersecurity Compliance Burden:NERC CIP requirements for critical cyber assets impose documentation and audit costs on communications-enabled recloser deployments that exceed those for conventional units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Vacuum Reclosers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Phase, Three Phase, Pole-Mounted, Pad-Mounted Technology: Smart Grid, Conventional, Hybrid, Remote Monitoring Application: Utilities, Industrial, Commercial, Renewable Energy End User: Electric Utilities, Municipalities, Independent Power Producers, Others |
| Companies Covered | ABB Ltd, Eaton Corporation plc, Siemens, Schneider Electric, Tavrida Electric AG, NOJA Power Switchgear Pty Ltd, Mitsubishi Electric, Arteche Lantegi Elkartea SA, ESTECO SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Vacuum Reclosers Market Evolving Landscape
Intelligent protection platforms are displacing conventional control mechanisms as utilities prioritize fault location accuracy and remote operability over basic automatic reclosing functions.
Self-powered microprocessor-based controllers with integrated voltage and current sensing are expanding into medium-voltage distribution feeders previously served by hydraulic mechanisms. Rural electric cooperatives in the US Midwest are adopting these units fastest, drawn by elimination of external power sources and reduced commissioning complexity. The technology is expanding into territories where line crews previously maintained electromechanical devices, compressing supplier margins on simpler product tiers.
The EU Green Deal's phase-out of fluorinated greenhouse gases is accelerating SF6 recloser retirement schedules across German and French distribution networks. Utilities must now specify vacuum alternatives for new installations and replacement cycles, tightening supplier qualification requirements. Medium-voltage switchgear procurement in Northern Europe now prioritizes sealed vacuum interrupter designs with certified leak-free performance over conventional gas-insulated options.
Performance-based reliability contracting is displacing traditional equipment-only purchasing among large US investor-owned utilities. Duke Energy and Southern California Edison now bundle recloser procurement with outage reduction guarantees and predictive analytics subscriptions. This shift concentrates purchasing authority at corporate engineering centers rather than regional districts, favoring suppliers with integrated software and service capabilities over component vendors.
Solid Vacuum Reclosers Market Segmentation
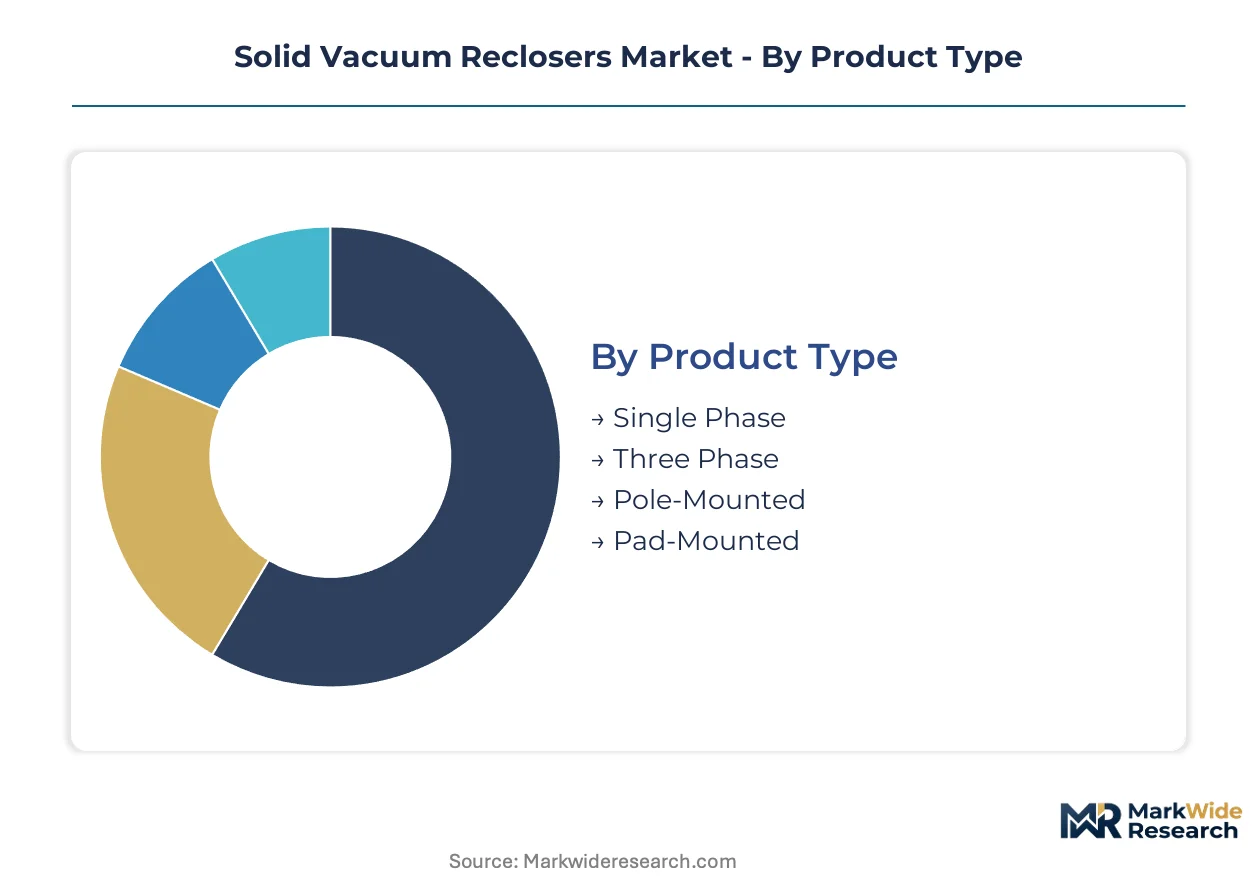
Solid vacuum reclosers serve distinct operational profiles across distribution networks, with procurement specifications diverging sharply between rural overhead feeders and dense urban underground circuits. Technology tiers separate utilities seeking basic fault interruption from those requiring adaptive protection and bidirectional power flow management.
Product Type:
Buyers in this category prioritize installation geometry and load configuration over unit cost, with terrain constraints and aesthetic requirements driving specification divergence.
- Three Phase:These configurations handle primary feeders serving mixed residential-industrial loads with interrupting capacities up to 16 kA across 15-38 kV ratings. US electric utilities concentrate procurement here for mainline hardening programs in storm-prone regions, where simultaneous three-pole operation reduces sustained outage frequency. IEEE C37.60 compliance requirements dominate tender specifications.
- Pole-Mounted:Overhead installations retain the largest installed base through standardized designs that minimize capital expenditure for rural cooperatives. Margin compression intensifies as hydraulic control mechanisms face displacement by microprocessor-based alternatives in the US Midwest.
- Single Phase:Lateral tap protection and single-phase laterals in sparsely populated territories.
- Pad-Mounted:Compact enclosures for urban underground distribution where space constraints and aesthetic requirements apply.
Pole-mounted units lead volumes today; pad-mounted configurations are gaining share fastest in metropolitan underground networks.
Technology:
Investment thresholds separate utilities pursuing operational flexibility through communications-enabled platforms from those optimizing capital efficiency with proven electromechanical designs.
- Smart Grid:Embedded sensors and predictive analytics enable remote monitoring, fault location, and adaptive protection settings that accommodate distributed renewable inflows. Duke Energy and Southern California Edison bundle these capabilities with outage reduction guarantees, concentrating purchasing authority at corporate engineering centers.
- Remote Monitoring:Self-powered microprocessor-based controllers with integrated voltage and current sensing eliminate external power sources. US rural electric cooperatives adopt these fastest where line crew availability constrains maintenance schedules.
- Conventional:Hydraulic control mechanisms specified by budget-constrained municipal utilities despite higher lifecycle costs.
- Hybrid:Transitional architectures blending electromechanical reliability with limited digital functionality.
Conventional technology still dominates installed base; smart grid platforms are expanding most quickly through performance-based reliability contracting.
Application:
Load characteristics and regulatory exposure determine whether buyers prioritize basic fault interruption or advanced grid integration capabilities.
- Utilities:Investor-owned and cooperative entities deploying automated reclosers to reduce SAIDI/SAIFI indices and avoid regulatory penalties. Storm hardening mandates across hurricane-prone US states accelerate procurement cycles here.
- Renewable Energy:Solar and battery interconnection requirements under IEEE 1547 force protection upgrades across California, Texas, and Florida distribution networks. Bidirectional fault detection becomes essential as distributed generation reshapes current profiles.
- Industrial:Manufacturing facilities and critical load centers requiring premium arc-resistant vacuum interrupters.
- Commercial:Shopping centers, hospitals, and data centers seeking selective coordination with upstream protection.
Utility applications command the largest revenue share; renewable energy integration is climbing the fastest as interconnection queues lengthen.
End User:
Ownership structure and funding access create procurement segmentation between federally subsidized cooperatives and municipally financed operators.
- Electric Utilities:Investor-owned entities with access to Inflation Reduction Act grid resilience funding. These buyers specify integrated digital twin platforms that reduce commissioning cycles for large-scale deployments.
- Municipalities:City-owned systems balancing ratepayer pressure against reliability mandates, often specifying conventional hydraulic reclosers despite lifecycle cost disadvantages.
- Independent Power Producers:Renewable developers requiring IEEE 1547-compliant protection for solar and battery interconnection.
- Others:Campus microgrids, military installations, and industrial self-generation facilities.
Electric utilities anchor procurement volume today; independent power producers are expanding most quickly behind interconnection-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in utility automation hubs anchor procurement intensity across major economies. Distribution network operators in storm-prone and renewable-rich territories drive specification divergence between intelligent and conventional recloser platforms.
United States
Electric cooperatives in hurricane-exposed southeastern states deploy automated reclosers to compress SAIDI metrics and evade FERC reliability penalties. The Inflation Reduction Act channels cost-sharing funds toward grid resilience investments across cooperative and municipal segments. Texas utilities concentrate procurement in the ERCOT interconnection zone where solar and battery queues force IEEE 1547 protection upgrades.
Germany
Distribution system operators accelerate vacuum recloser adoption to meet EU F-Gas Regulation phase-out deadlines for SF6 switchgear. The national grid modernization framework prioritizes sealed vacuum interrupter designs with certified leak-free performance. Industrial automation clusters in Bavaria supply control systems for smart-grid recloser deployments across Northern European networks.
China
State Grid Corporation specifications drive volume procurement for rural electrification hardening and urban underground distribution expansion. MIIT industrial standards for medium-voltage switchgear tighten supplier qualification requirements. Manufacturing concentration in the Yangtze River Delta produces vacuum interrupter assemblies for domestic utility tenders and export markets.
Japan
Tokyo Electric Power and regional utilities specify compact pole-mounted reclosers for seismic resilience and space-constrained urban feeders. METI energy efficiency mandates favor maintenance-free vacuum technology over legacy oil-filled alternatives. Nagoya-area industrial clusters manufacture precision vacuum interrupter contacts for utility and railway electrification applications.
India
Power Grid Corporation and state distribution companies deploy single-phase reclosers for rural lateral protection under the national rural electrification program. CEA technical standards for distribution automation guide procurement specifications. Manufacturing activity in Gujarat and Maharashtra supplies electromechanical and microprocessor-based units for price-sensitive state utility tenders.
Solid Vacuum Reclosers Market Competitive Landscape
Top-tier vendors anchor premium intelligent recloser positions, while regional fabricators compete on conventional electromechanical specifications. The vendor base stratifies across three capability tiers: integrated platform providers with digital twin and predictive analytics offerings; vacuum interrupter specialists with arc-resistant designs for harsh climate zones; and commodity producers of standardized pole-mounted units. Strategic moves concentrate on M&A to acquire edge computing and sensor capabilities, plus capacity expansion in vacuum interrupter contact manufacturing to secure supply against copper-chromium price volatility.
Within the integrated platform tier, ABB Ltd and Siemens exemplify archetypes combining embedded sensing with utility smart-grid tender positioning. Eaton Corporation plc occupies a position among arc-resistant vacuum interrupter specialists serving storm-hardening programs. These three anchors represent divergent competitive vectors: predictive analytics bundling, climate-zone engineering specialization, and digital twin commissioning acceleration.
| Leading Market Players |
|---|
| ABB Ltd |
| Eaton Corporation plc |
| Siemens |
| Schneider Electric |
| Tavrida Electric AG |
| NOJA Power Switchgear Pty Ltd |
| Mitsubishi Electric |
| Arteche Lantegi Elkartea SA |
| ESTECO SpA |
| Others |
Value Network & Pricing Analysis
Precision vacuum interrupter engineering talent clusters in Bavaria and the Yangtze River Delta anchor labor-cost differentials that widen pricing-tier spreads between premium intelligent reclosers and commodity pole-mounted units. German and Chinese manufacturing wage gaps translate directly into three-tier pricing structures that separate predictive analytics-bundled platforms from basic hydraulic alternatives.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the Solid Vacuum Reclosers Market. Equipment-only transactions dominate municipal utility procurement, while investor-owned utilities increasingly subscribe to outage-reduction-guarantee packages with embedded predictive maintenance. Price differentiation hinges on IEEE C37.60 certification tier and after-sales service bundling. Cost compression in conventional hydraulic tiers intensifies as microprocessor-based alternatives capture rural cooperative demand. Municipal utilities exhibit highest price sensitivity; large IOUs with IRA funding access show lowest.
Supply Chain Analysis
Certification and qualification gating by IEEE and IEC standards concentrates supplier viability among vacuum interrupter specialists with proven arc-resistant designs. Manufacturing gravity centers on Germany, China, and Japan, with copper-chromium contact fabrication and permanent magnet actuator assembly feeding final recloser production. Raw material dependencies include copper-chromium alloys, rare earth elements for actuators, and industrial-grade semiconductors for controllers. Single-source vulnerability in East Asian foundry supply creates lead time exposure. Distribution runs through direct utility tender channels and specialized electrical equipment distributors serving cooperative segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Solid Vacuum Reclosers Market functions as a stable compounder, with grid reliability mandates and storm-hardening programs providing durable procurement visibility regardless of macroeconomic cycles.
For Market Incumbents: Lock in long-term vacuum interrupter supply agreements to hedge copper-chromium price volatility and secure margin positions against commodity-tender pressure. Deepen backward integration into contact manufacturing in Germany or Japan to reduce exposure to Yangtze River Delta logistics disruptions. Prioritize IEC-IEEE dual certification investments to capture cross-border utility tenders as harmonization delays persist. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and France opens a window for vacuum recloser specialists to displace retiring SF6 switchgear installations. Target German distribution system operators accelerating phase-out schedules under national grid modernization frameworks. Lead with sealed vacuum interrupter designs certified leak-free to bypass incumbent qualification barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among conventional electromechanical recloser producers facing technology displacement, offering platform-acquisition entry points. Five-to-ten-year viability hinges on successful digital-twin and edge-computing capability integration. Watch NERC CIP cybersecurity compliance cost escalation as the signal indicating communications-enabled recloser deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Manufacturing | Captive copper-chromium contact supply secures margin against commodity swings in utility tenders. |
| Dual Certification Investment (IEEE C37.60 + IEC 62271-111) | Cross-border qualification unlocks procurement from US cooperatives and German DSOs simultaneously. |
| Predictive Analytics Platform Development | Performance-based contracting with Duke Energy and Southern California Edison concentrates purchasing authority. |
| SF6 Switchgear Retirement Program Targeting | EU F-Gas Regulation deadlines in Germany and France accelerate replacement cycle capture. |
| Edge Computing Controller Acquisition | Self-powered microprocessor capabilities compress commissioning cycles for Midwest rural cooperative adoption. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build convergent validity across demand and supply perspectives. Primary discussions included utility planning officers at investor-owned and cooperative entities, recloser procurement managers at electrical equipment distributors, and vacuum interrupter engineering leads at component manufacturers. Secondary validation drew from FERC reliability index filings, IEEE standards documentation, EU F-Gas Regulation implementation reports, and EIA distribution automation investment disclosures. Bottom-up utility tender aggregation and top-down grid modernization budget allocation analysis were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through verified installed base records and replacement cycle documentation. The analytical framework modeled segmentation across product type (three-phase, single-phase, pole-mounted, pad-mounted), technology tier (conventional, remote monitoring, smart grid), application (utilities, renewable energy, industrial, commercial), and end-user ownership structure (investor-owned, municipal, independent power producer). CAGRs were derived from utility capital expenditure trajectory analysis and interconnection queue growth patterns. Forecast inputs included IEEE 1547 upgrade cycle timing and IRA grid resilience funding disbursement velocity.
Revisions become necessary when copper or rare earth price volatility exceeds historical bands, when semiconductor foundry lead times extend beyond standard utility procurement windows, or when IEC-IEEE harmonization accelerates unexpectedly. Forecasts reflect documented assumptions regarding distributed generation penetration rates and storm-hardening program continuity. A model refresh is warranted upon material change in FERC reliability penalty structures or EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Latin America Hazardous Location Motor Starters Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Alternator Regulator Market