
 HVDC Converter Station Market | 2026-2036
HVDC Converter Station Market Size, Share, and Industry Trends Forecast 2026-2036
HVDC Converter Station Market Analysis
Project finance structures with long-term offtake agreements is tilting the competitive landscape toward firms capable of underwriting decade-long performance contracts. Siemens Energy leverages its manufacturing scale across European fabrication sites to secure utility-scale bids. Hitachi Energy anchors its position through technology leadership in voltage source converter architectures. Mitsubishi Electric competes aggressively in Asia-Pacific markets with localized supply chains and after-service networks.
An HVDC converter station is a high-voltage direct current facility that transforms alternating current to direct current for efficient long-distance transmission, typically operating at voltage levels from 150 kV to 800 kV and above, using thyristor or IGBT-based valve halls to minimize resistive losses across submarine cables and continental interconnectors. Modular multilevel converter technology now dominates new installations due to its superior harmonic performance and black-start capability, while voltage source converter configurations are capturing the fastest growth in offshore wind integration projects where compact footprint and reactive power control prove critical. Line commutated converter systems retain relevance in ultra-high-capacity bulk power transfers above 5 GW, particularly in brownfield expansions where existing thyristor infrastructure reduces capital outlay.
FERC Order 2023 in the United States and the EU's TEN-E regulation framework are reshaping permitting timelines and cross-border cost allocation for interconnector investments, directly influencing developer return thresholds and technology selection criteria. China's GB standards for ultra-high voltage DC, administered by SAMR, dictate insulation coordination and valve testing protocols that equipment suppliers must satisfy for market access. Stakeholders must monitor how evolving grid codes in multiple jurisdictions treat fault ride-through requirements for converter stations, as these specifications determine R&D allocation and product platform compatibility across regions.
Market Dynamics
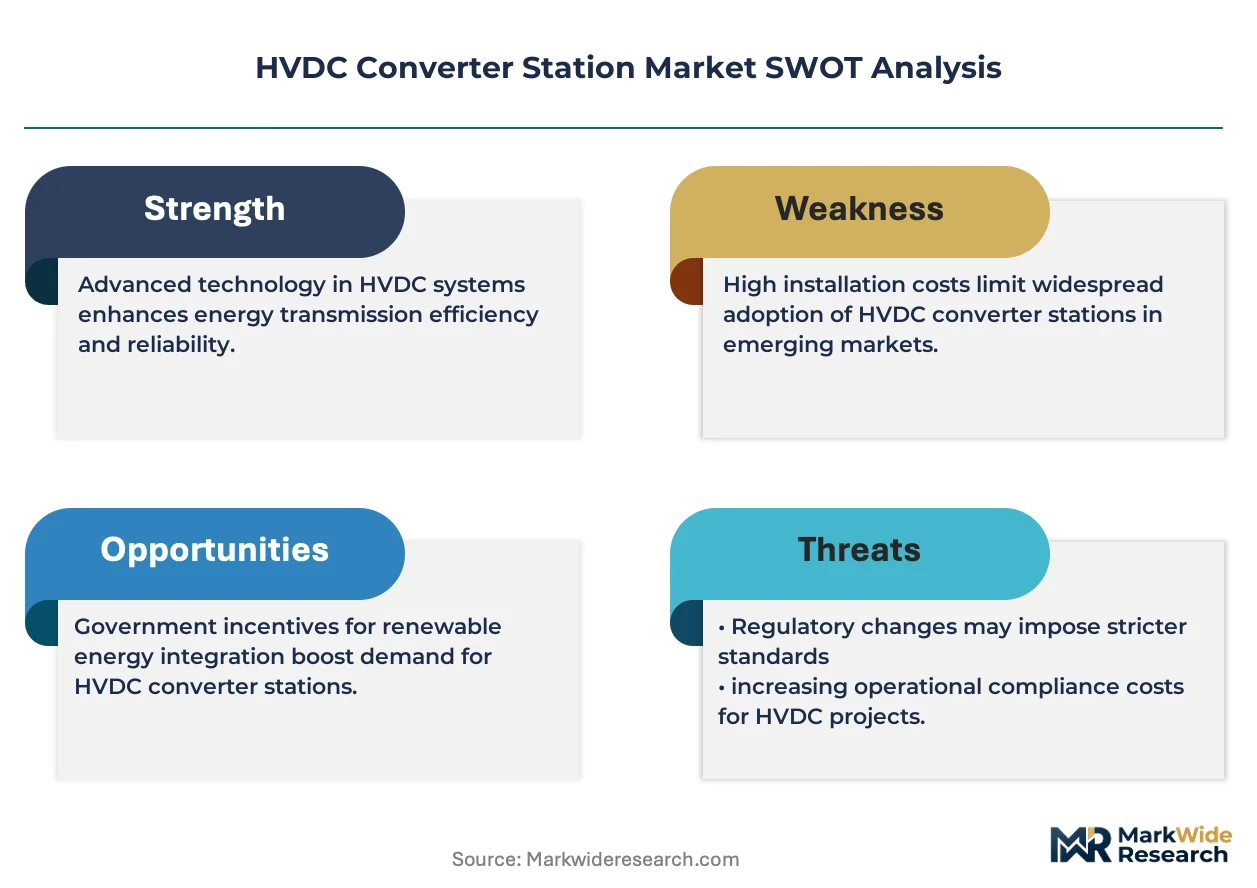
The transition from gas-insulated to dry-type converter transformers is compressing supplier margins while opening new equipment categories as Europe's F-Gas Regulation tightens phase-out timelines for sulfur hexafluoride.
Growth Catalysts
- Offshore wind scaling:Floating wind projects in deeper waters require compact, lightweight converter stations that voltage source converter architectures deliver.
- TEN-E regulation:The EU's framework for trans-European energy networks accelerates permitting for cross-border interconnectors, reducing developer uncertainty.
- Modular multilevel converters:This technology's black-start capability and harmonic performance are pulling replacements of aging line commutated converter halls.
Market Restraints
- Specialized copper and rare earth supply:Concentration of magnet wire and neodymium processing in China creates input cost volatility and geopolitical exposure.
- Ultra-high-voltage testing infrastructure:Limited global availability of 800 kV+ test bays extends lead times for valve qualification.
- Thyristor equipment lock-in:Existing line commutated converter installations above 5 GW create substitution friction against full MMC retrofits.
Strategic Opportunities
- Desert solar export corridors:Green hydrogen-linked HVDC links from North Africa to Southern Europe remain underpenetrated despite resource abundance.
- Grid-forming converter integration:Convergence of battery energy storage and voltage source converter controls enables synthetic inertia services.
- US IRA manufacturing credits:Domestic content bonuses for electrical equipment create localized fabrication incentives for converter valve assembly.
Industry Challenges
- HVDC control systems engineering:Scarce expertise in real-time digital simulators and electromagnetic transient modeling extends commissioning timelines.
- Multi-jurisdiction grid code compliance:Divergent fault ride-through specifications across Germany, the United Kingdom, and China force redundant platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVDC Converter Station Market |
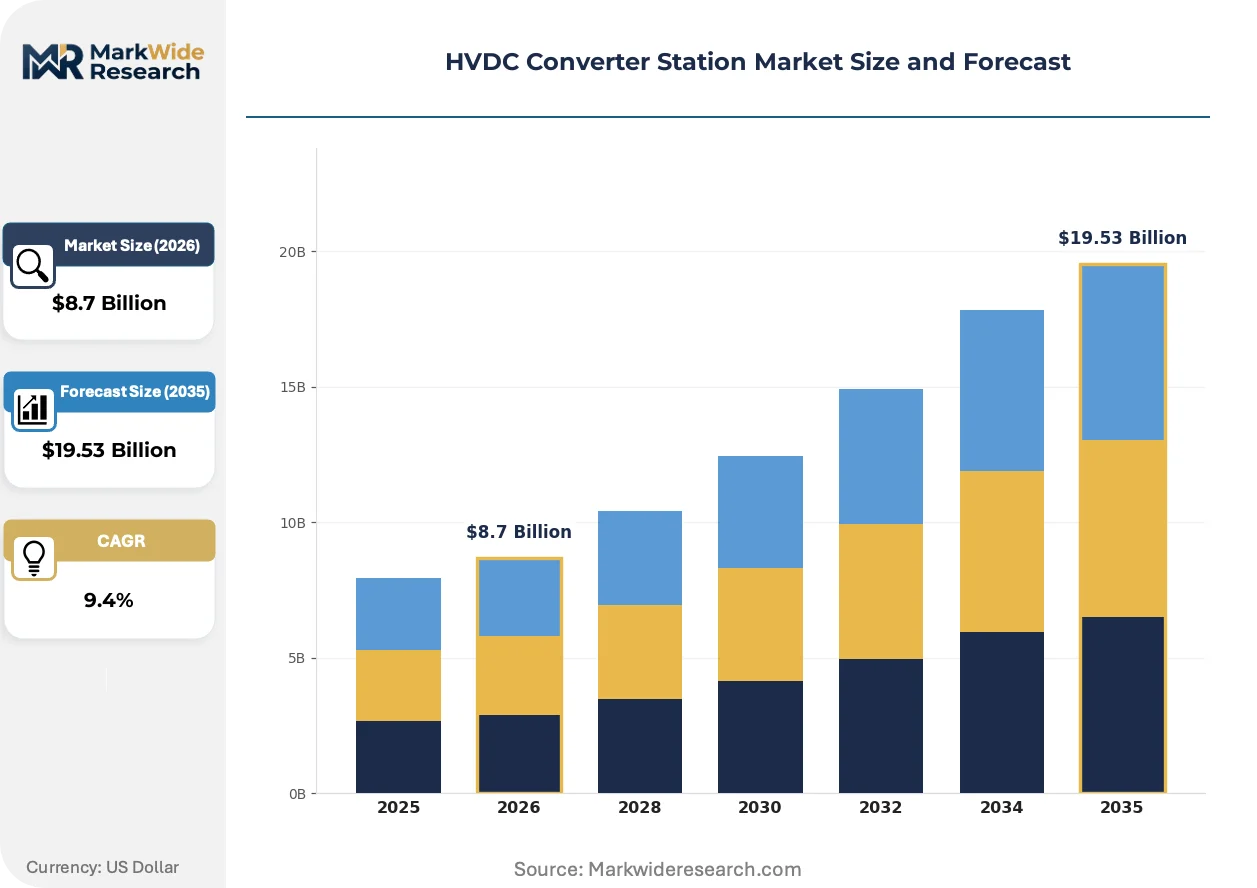
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Line Commutated Converter, Voltage Source Converter, Modular Multilevel Converter, Hybrid Converter Technology: DC Transmission, AC Transmission, Wind Integration, Solar Integration End User: Utilities, Industrial Sector, Renewable Energy Providers, Offshore Wind Farms Installation: Onshore, Offshore, Greenfield, Brownfield |
| Companies Covered | Mitsubishi Electric, NR Electric, Hitachi Energy, Schneider Electric, Prysmian Group, Siemens Energy, Toshiba Energy Systems & Solutions, Alstom Grid, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVDC Converter Station Market Emerging Trajectories
Converter station architecture is bifurcating between ultra-compact offshore platforms and land-based bulk power hubs, with equipment specifications diverging sharply between these deployment modes.
Silicon carbide power semiconductors are entering pilot installations in medium-voltage valve halls, offering switching frequencies that reduce filter bank volumes by half. Offshore wind developers in the North Sea are trialing these modules for 66 kV collection platforms. Conventional silicon IGBT-based designs are rendering obsolete for floating wind applications where every ton of topside weight carries through to mooring and vessel charter costs.
Europe's F-Gas Regulation mandates an 80% cut in sulfur hexafluoride emissions by 2030 from 2014 baselines, forcing immediate redesign of gas-insulated switchgear and transformer bushings. Manufacturers are accelerating dry-type and vacuum interrupter alternatives. German transmission system operators face the tightest compliance deadlines, compressing their technology refresh cycles relative to Southern European counterparts.
Long-term availability contracts now dominate procurement for interconnector projects, with developers seeking 15-year performance warranties that bundle equipment supply, installation, and predictive maintenance. Engineering-procurement-construction firms are absorbing this risk and subcontracting to valve suppliers on back-to-back terms. This model is most advanced in the United Kingdom, where OFGEM's cap-and-floor regime for interconnectors shapes return calculations and contractor selection criteria.
HVDC Converter Station Market Segmentation
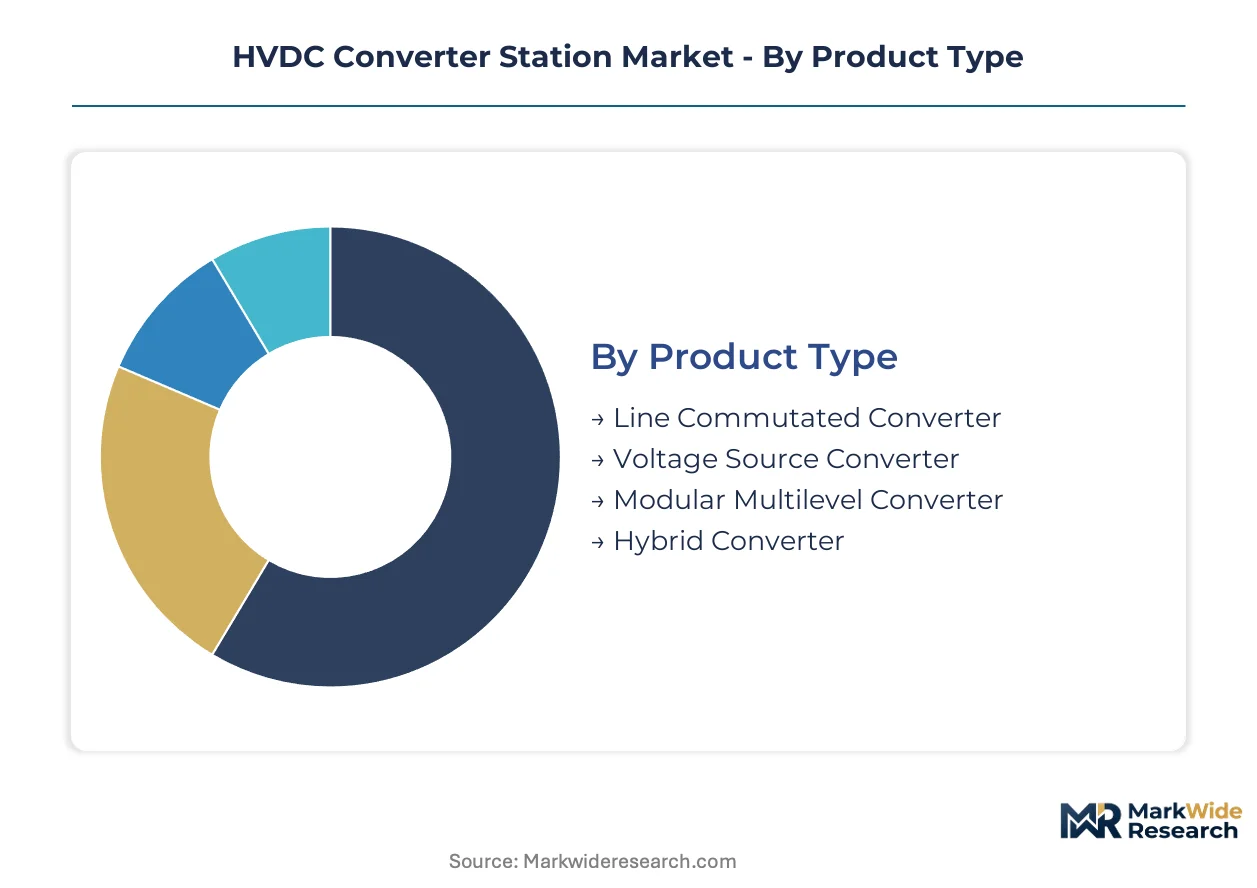
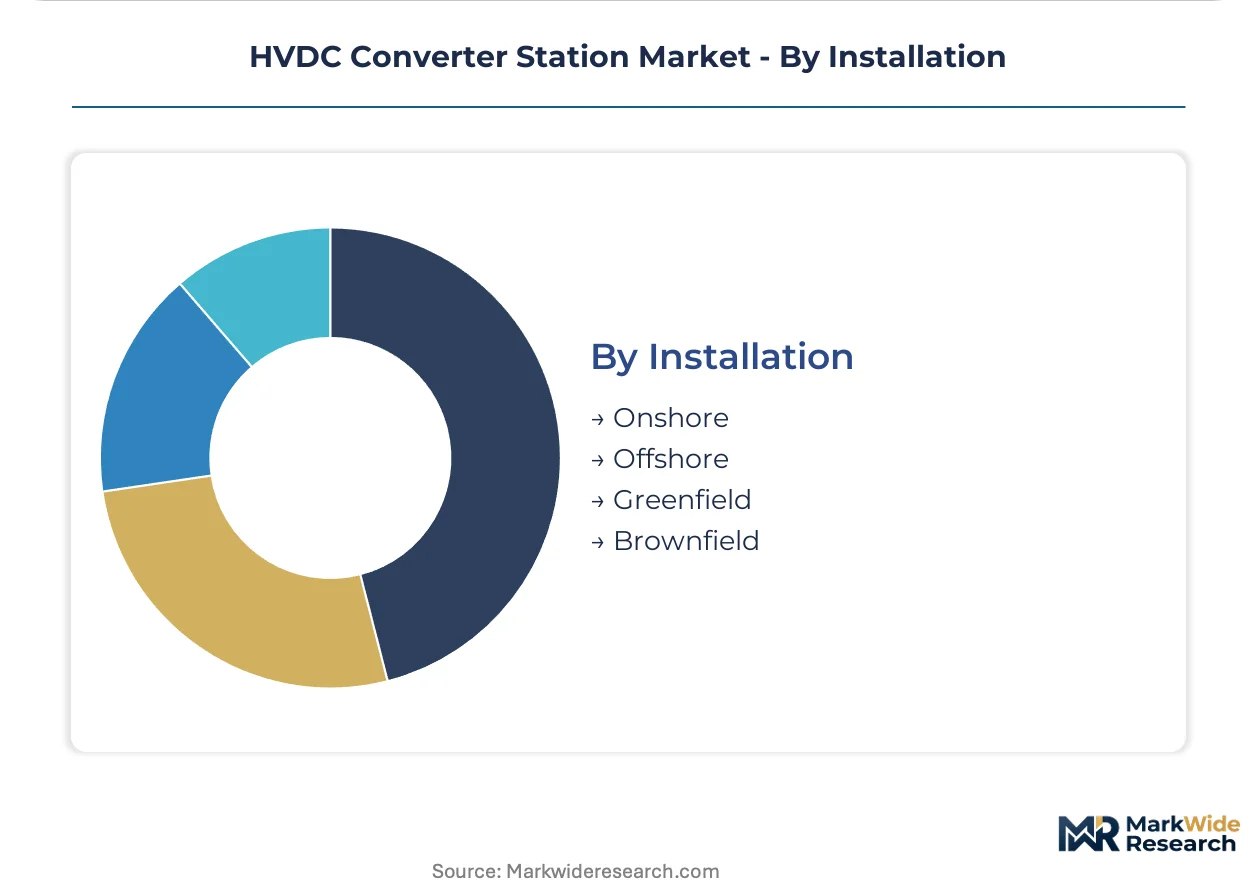
HVDC converter station procurement cycles vary dramatically by segment, with offshore platforms turning over every 12-15 years versus 25-30 year lifecycles for onshore bulk power hubs. Technology selection and installation mode drive these divergent replacement rhythms, directly shaping supplier revenue predictability and aftermarket service attach rates.
Product Type:
Replacement cycles compress most sharply where floating wind economics demand lighter, more compact architectures, while legacy bulk power corridors extend equipment life through phased retrofits.
- Line Commutated Converter:Thyristor-based valve halls dominate existing installations above 5 GW capacity, with mercury-arc heritage designs still operational in select European corridors. Brownfield expansions in China and India preserve this technology where existing infrastructure amortization outweighs efficiency gains from full replacement.
- Voltage Source Converter:IGBT-based architectures enable independent active and reactive power control, making them indispensable for offshore wind integration where grid-forming capability proves essential. North Sea developers specify these systems for floating platforms where weight reduction directly reduces mooring and dynamic cable costs.
- Modular Multilevel Converter:Expanding most quickly across new interconnector projects, this topology eliminates harmonic filters through cascaded cell structures while delivering black-start capability that system operators increasingly mandate.
- Hybrid Converter:Combines LCC bulk power handling with VSC grid support functions, finding niche application in corridor upgrades where partial retrofit preserves existing thyristor investments while adding reactive power services.
Line Commutated Converter anchors the volume base while Modular Multilevel Converter gains share at the steepest rate.
Technology:
Cost tiers separate transmission-centric deployments from renewable integration projects, with the latter commanding 40-60% capital premiums for specialized control systems and environmental hardening.
- DC Transmission:Point-to-point bulk power corridors exceeding 1000 km leverage low resistive losses, with Saharan solar export links and Siberian hydropower connections representing the highest-capacity deployments.
- AC Transmission:Back-to-back asynchronous interconnections resolve grid stability conflicts between unsynchronized networks, particularly at borders between 50 Hz and 60 Hz systems.
- Wind Integration:Offshore collection platforms at 66 kV and 220 kV require compact converter footprints where every ton of topside equipment amplifies foundation and installation vessel costs.
- Solar Integration:Desert solar clusters in Morocco, Saudi Arabia, and Australia demand extreme temperature cycling resilience, with ambient specifications reaching 55°C continuous operation.
DC Transmission anchors the volume base while Wind Integration climbs the fastest as floating projects proliferate.
End User:
Customer procurement sophistication ranges from standardized utility frameworks to bespoke offshore engineering specifications, with contract structures diverging sharply across these institutional contexts.
- Utilities:National transmission system operators in Germany, the United Kingdom, and China dominate interconnector procurement, with OFGEM's cap-and-floor regime and China's GB standards dictating divergent technical specifications.
- Industrial Sector:Mining and aluminum smelting operations in remote locations purchase dedicated HVDC links where grid extension proves uneconomical, with Mongolian copper deposits and Icelandic smelters representing established demand pockets.
- Renewable Energy Providers:Independent power producers negotiate long-term offtake agreements that bundle converter station availability into generation revenue streams, compressing supplier margins through performance guarantees.
- Offshore Wind Farms:Floating wind developers in the Celtic Sea and Pacific Northwest specify weight-optimized platforms where silicon carbide semiconductors reduce filter bank volumes by half relative to conventional IGBT designs.
Utilities anchor the volume base while Offshore Wind Farms expand most quickly as water depths exceed fixed-foundation limits.
Installation:
Site preparation intensity and regulatory pathway duration create four distinct project archetypes, with environmental permitting timelines spanning 18 months to 7 years across these categories.
- Onshore:Land-based converter halls face community opposition and visual impact assessments, with German and French projects encountering the most protracted permitting due to agricultural land use conflicts.
- Offshore:Platform-based installations eliminate terrestrial constraints but introduce marine logistics complexity, with jack-up vessel availability and weather windows determining construction schedules in the North Sea and Baltic.
- Greenfield:New corridor development requires full environmental impact assessment and greenfield land acquisition, with TEN-E regulation in the European Union accelerating cross-border projects while domestic transmission builds lag.
- Brownfield:Existing substation expansions leverage permitted footprints and operational infrastructure, with China's ultra-high-voltage network and the US Eastern Interconnection representing the largest brownfield opportunity pools.
Onshore anchors the volume base while Offshore gains share at the steepest rate as floating wind moves into deeper waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export corridors from resource-rich peripheries to demand centers in Germany, the United Kingdom, and China are driving converter station procurement, while import-dependent regions in Southern Europe and Southeast Asia accelerate interconnector deployment to diversify supply.
Germany
North Sea offshore wind clusters and cross-border interconnectors to Norway and Denmark dominate converter station demand. The country's F-Gas Regulation compliance deadlines force rapid gas-insulated switchgear replacement in converter halls. Hamburg and the northern coastal states concentrate fabrication yards where dry-type transformer assembly lines are expanding.
United Kingdom
OFGEM's cap-and-floor regime for interconnectors shapes developer return calculations and contractor selection for subsea cable projects. Floating wind developments in the Celtic Sea require compact voltage source converter platforms. Scottish and English North Sea ports host installation vessel fleets mobilizing for platform deployment.
China
Ultra-high-voltage DC corridors from western hydropower and desert solar to eastern load centers sustain bulk power converter demand. SAMR-administered GB standards dictate insulation coordination and valve testing protocols for market access. The Yangtze River Delta and Pearl River Delta house valve manufacturing clusters serving domestic and export markets.
United States
FERC Order 2023 streamlines interconnection permitting timelines for cross-regional transmission investments. Offshore wind lease areas off the Atlantic coast require converter platforms with grid-forming capabilities. The Pacific Northwest and Texas ERCOT interconnections represent brownfield expansion opportunities for asynchronous ties.
Saudi Arabia
Green hydrogen export corridors to Southern Europe drive planning for desert solar-linked HVDC links. The kingdom's dual carbon goals align with high-capacity DC transmission for renewable energy integration. NEOM and the Eastern Province concentrate early-phase engineering studies for multi-gigawatt converter stations.
HVDC Converter Station Market Vendor Landscape
On the supply side, the industry is consolidating around integrated energy technology conglomerates capable of underwriting decade-long performance contracts. Three strategic archetypes dominate: full-system EPC providers, specialized valve technology licensors, and cable-integrated solution vendors. Competitive intensity centers on manufacturing scale leverage and geographic proximity to North Sea offshore clusters.
Among European-integrated energy suppliers, Siemens Energy and Hitachi Energy exemplify the full-system archetype with manufacturing footprints across continental fabrication sites. NR Electric represents the specialized technology tier with focused valve and control system capabilities. These anchors reflect the market's bifurcation between scale-driven utility bids and technology-differentiated offshore wind specifications.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| NR Electric |
| Hitachi Energy |
| Schneider Electric |
| Prysmian Group |
| Siemens Energy |
| Toshiba Energy Systems & Solutions |
| Alstom Grid |
| GE Vernova |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet supply concentration in China determines both pricing tier spreads and supply chain shape for HVDC converter stations, as neodymium processing bottlenecks force European and North American buyers into long-term offtake premiums while dry-type transformer transitions compress margins across equipment categories.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing with 15-year performance warranties bundling equipment supply and predictive maintenance. Three-tier pricing structure across premium, standard, and economy levels separates black-start capable modular multilevel converter systems from basic line commutated retrofits and weight-optimized offshore platforms. Cost compression in standard-tier valve halls is intensifying because F-Gas Regulation compliance deadlines force accelerated gas-insulated switchgear replacement. Renewable energy providers exhibit highest price sensitivity due to long-term offtake agreement structures, while utility transmission system operators demonstrate lowest sensitivity given regulated cost recovery mechanisms.
Supply Chain Analysis
Export controls on wide-bandgap semiconductor manufacturing equipment limit silicon carbide substrate flows from United States and Japanese suppliers to Chinese valve assemblers. Magnet wire drawing concentrates in China and Germany, with thyristor and IGBT module packaging anchored in Japan and South Korea. Supply chains draw from Chilean copper cathodes, Australian rare earth concentrates, and Malaysian semiconductor packaging facilities. Single-source vulnerability in 800 kV+ test bay availability extends valve qualification timelines. Distribution runs through engineering-procurement-construction firms that absorb performance risk and subcontract to specialized valve suppliers on back-to-back terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC converter station markets exhibit durable defensive moats rooted in regulatory entrenchment, where F-Gas compliance deadlines and grid code certification requirements create structural barriers that protect incumbent positions against new challenger entry.
For Market Incumbents: Insulate market position by accelerating dry-type transformer manufacturing scale-up in Hamburg and northern German coastal states ahead of F-Gas Regulation phase-out deadlines. Secure captive supply of neodymium magnet wire through backward integration into rare earth processing partnerships. Prioritize real-time digital simulator expertise acquisition to address HVDC control systems engineering scarcity that extends commissioning timelines. For New Entrants and Emerging Players: Floating wind platform retrofits in the Celtic Sea and Pacific Northwest represent the most penetrable entry point, as weight-optimized voltage source converter specifications diverge from established utility-scale procurement frameworks. Green hydrogen-linked desert solar export corridors from North Africa to Southern Europe offer second-mover advantage in underpenetrated corridor development. Pursue technology licensing partnerships with established valve technology licensors to bypass decade-long performance contract underwriting requirements. For Investors and Strategic Acquirers: Specialized valve technology licensors with focused modular multilevel converter control system capabilities present the most attractive acquisition archetype for portfolio exposure to offshore wind integration growth. Monitor silicon carbide pilot installation conversion rates at 66 kV collection platforms as inflection indicator for next-generation semiconductor substrate adoption timelines. Material shifts in multi-jurisdiction grid code harmonization would force updated calibration of technology platform compatibility assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Dry-Type Transformer Manufacturing Scale-Up | F-Gas Regulation compliance deadlines in Germany force accelerated gas-insulated switchgear replacement cycles. |
| Silicon Carbide Valve Hall Pilot Expansion | Switching frequency advantages reduce filter bank volumes for floating wind weight constraints. |
| Long-Term Rare Earth Supply Agreement | Neodymium processing concentration in China creates geopolitical exposure for magnet wire inputs. |
| Grid-Forming Converter Control Integration | Synthetic inertia services from battery energy storage convergence meet evolving system operator mandates. |
| Real-Time Digital Simulator Capability Buildout | Scarce electromagnetic transient modeling expertise extends commissioning timelines across projects. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FERC interconnection filings, IEA transmission investment databases, EU TEN-E project registries, and SAMR GB standards documentation. Utility planning officers, offshore wind project developers, EPC contractors, and grid operators provided structured input on procurement frameworks and technology selection criteria. Bottom-up project pipeline aggregation triangulates against top-down market sizing from equipment supplier manufacturing disclosures.
Forecast inputs include voltage source converter adoption rates in floating wind applications, modular multilevel converter replacement cycles for aging line commutated converter halls, and F-Gas Regulation compliance investment schedules across European transmission system operators. Segmentation dimensions encompass converter topology, transmission technology, end-user procurement sophistication, and installation mode regulatory pathway duration. CAGRs were derived from equipment order book analysis and interconnector project development timelines.
Practitioners should monitor silicon carbide substrate export control enforcement, multi-jurisdiction grid code harmonization progress, and jack-up vessel fleet availability for early signals of supply constraint or demand acceleration. Forecasts reflect assumptions regarding TEN-E regulation permitting acceleration, OFGEM cap-and-floor regime stability, and China's ultra-high-voltage corridor buildout continuity. Material shifts in rare earth processing geographic concentration or wide-bandgap semiconductor manufacturing equipment access restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Substation Testing Equipment Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Power Line Filters Market