
 North America Alternating Current (AC) Drive Market | 2026-2036
North America Alternating Current (AC) Drive Market Size, Share, and Industry Trends Forecast 2026-2036
North America Alternating Current (AC) Drive Market Analytics
Modular drive configurations paired with pre-integrated power electronics and communication modules is expanding buyer flexibility across retrofit and greenfield projects. ABB Ltd leverages its broad voltage-range portfolio to anchor large industrial accounts across the Great Lakes manufacturing belt. Rockwell Automation, Inc. competes through tight integration with its programmable automation controller ecosystem. Danfoss specializes in compact, decentralized drive architectures for food and beverage conveyor systems.
Alternating current drives are power conversion systems that vary motor speed and torque by adjusting input frequency and voltage, typically operating across 208V to 690V three-phase supply with switching frequencies between 2–16 kHz to optimize thermal performance and motor compatibility. Their primary purpose is reducing energy consumption in centrifugal load applications where throttling valves or dampers previously wasted mechanical power. Variable Speed Drive units command the largest installed base due to decades of proven payback in fan and pump duty, while Servo Drive segments attract premium positioning from precision motion requirements in packaging machinery and CNC tooling. VFD technology retains dominant share across water treatment and HVAC end users, though Sensorless Vector Control is gaining ground in mid-range positioning tasks where encoder cost elimination improves project economics.
US Department of Energy motor efficiency rules and NEMA MG 1 standards mandate minimum full-load efficiency curves that effectively exclude single-speed motor operation in many new installations, directly stimulating variable speed drive attachment rates. Canada's Natural Resources CANMET program and provincial utility rebate structures in Ontario and Quebec further reduce payback periods for industrial efficiency upgrades. Stakeholders must monitor harmonized IEEE 519 and CSA C22.2 power quality enforcement, as tightening total harmonic distortion limits will force filter investments or multilevel topology transitions in large drive deployments.
Market Dynamics
US Department of Energy motor efficiency mandates are compressing payback periods for variable frequency drive retrofits while simultaneously elevating minimum performance thresholds that legacy fixed-speed installations cannot satisfy.
Growth Catalysts
- NEMA MG 1 Standards:Minimum full-load efficiency curves now exclude single-speed motor operation in many new installations across Texas and California industrial corridors.
- Water Treatment Utilities:Municipal pump stations throughout the Great Lakes region are deploying variable frequency drives to cut centrifugal load energy consumption.
- Sensorless Vector Control:Encoder elimination in mid-range positioning tasks improves project economics for packaging machinery retrofits.
Market Restraints
- Power Quality Compliance Costs:Harmonized IEEE 519 and CSA C22.2 total harmonic distortion limits force filter investments or multilevel topology transitions in large drive deployments.
- Input Cost Volatility:Insulated-gate bipolar transistor and silicon carbide power module pricing fluctuates with semiconductor foundry capacity constraints.
- Technical Limitation:Electromagnetic interference mitigation in 690V three-phase supply environments demands shielded cabling and isolated control architectures that inflate installation complexity.
Strategic Opportunities
- Canadian Provincial Rebates:Ontario and Quebec utility efficiency programs reduce capital outlay for industrial drive upgrades in food processing clusters.
- Semiconductor Manufacturing:Cleanroom HVAC and ultrapure water pump applications in Arizona and New Mexico fabs require precision torque control that variable frequency drives uniquely deliver.
- Decentralized Drive Architectures:Compact motor-mounted units eliminate cabinet space requirements in conveyor-intensive beverage bottling operations.
Industry Challenges
- Power Electronics Expertise Gap:Field service engineers fluent in pulse-width modulation tuning and thermal management are scarce across the Midwest manufacturing belt.
- Legacy Integration Complexity:Retrofitting 208V systems with modern communication protocols demands gateway hardware that fragments control architecture uniformity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Alternating Current (AC) Drive Market |
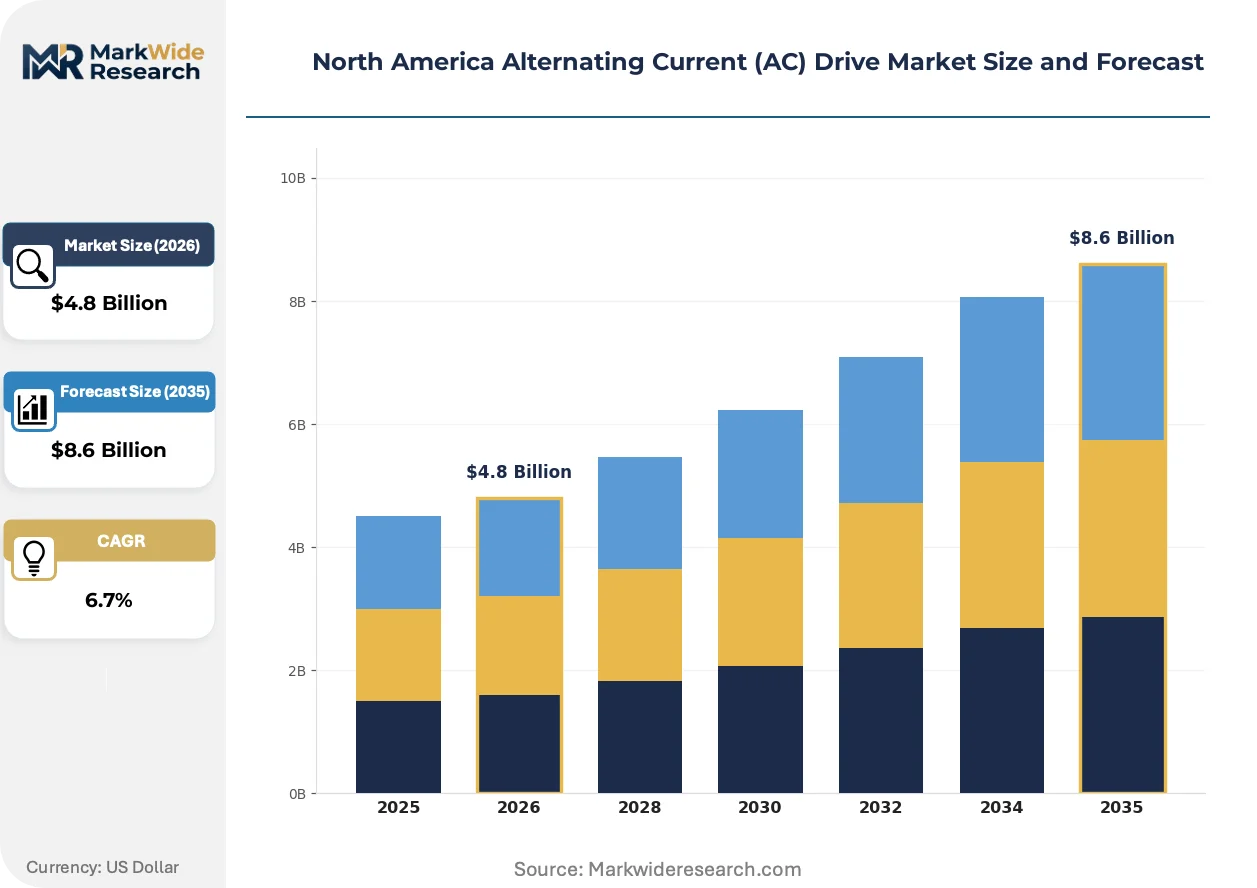
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Speed Drive, Servo Drive, Direct Torque Control, Soft Starter End User: Manufacturing, Oil & Gas, Mining, Water Treatment Technology: VFD, Sensorless Vector Control, Closed Loop Control, Open Loop Control Installation: Wall-Mounted, Rack-Mounted, Integrated, Modular |
| Companies Covered | ABB Ltd, Rockwell Automation, Inc., Danfoss, Siemens, Yaskawa Electric Corporation, WEG Industries, Schneider Electric SE, Eaton, Emerson Electric Co, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Alternating Current (AC) Drive Market Evolving Landscape
Silicon carbide power semiconductors and predictive maintenance algorithms are compressing drive footprint and extending service intervals simultaneously.
Multilevel topologies utilizing cascaded H-bridge or neutral-point-clamped architectures is absorbing harmonic distortion mitigation costs that previously required external passive filters. Water treatment utilities in the Colorado River basin are specifying these configurations for 480V pump stations. The technology is absorbing what were separate engineering line items into the drive enclosure itself.
The US Department of Energy's motor efficiency regulations tighten minimum full-load efficiency curves on a rolling schedule that effectively mandates variable speed attachment. Industrial facility managers in petrochemical corridors now treat NEMA Premium compliance as a baseline procurement filter. Canadian Natural Resources CANMET program harmonization accelerates parallel adoption across Ontario manufacturing.
After-sales service unbundling allows end users to separate hardware procurement from commissioning and preventive maintenance contracts. Large industrial accounts in the Texas Permian Basin are negotiating drive-only purchases while sourcing startup tuning from specialized system integrators. This bifurcation is most visible in oilfield pumpjack retrofits where operational technology vendors now compete directly with original equipment manufacturer service arms.
North America Alternating Current (AC) Drive Market Segmentation
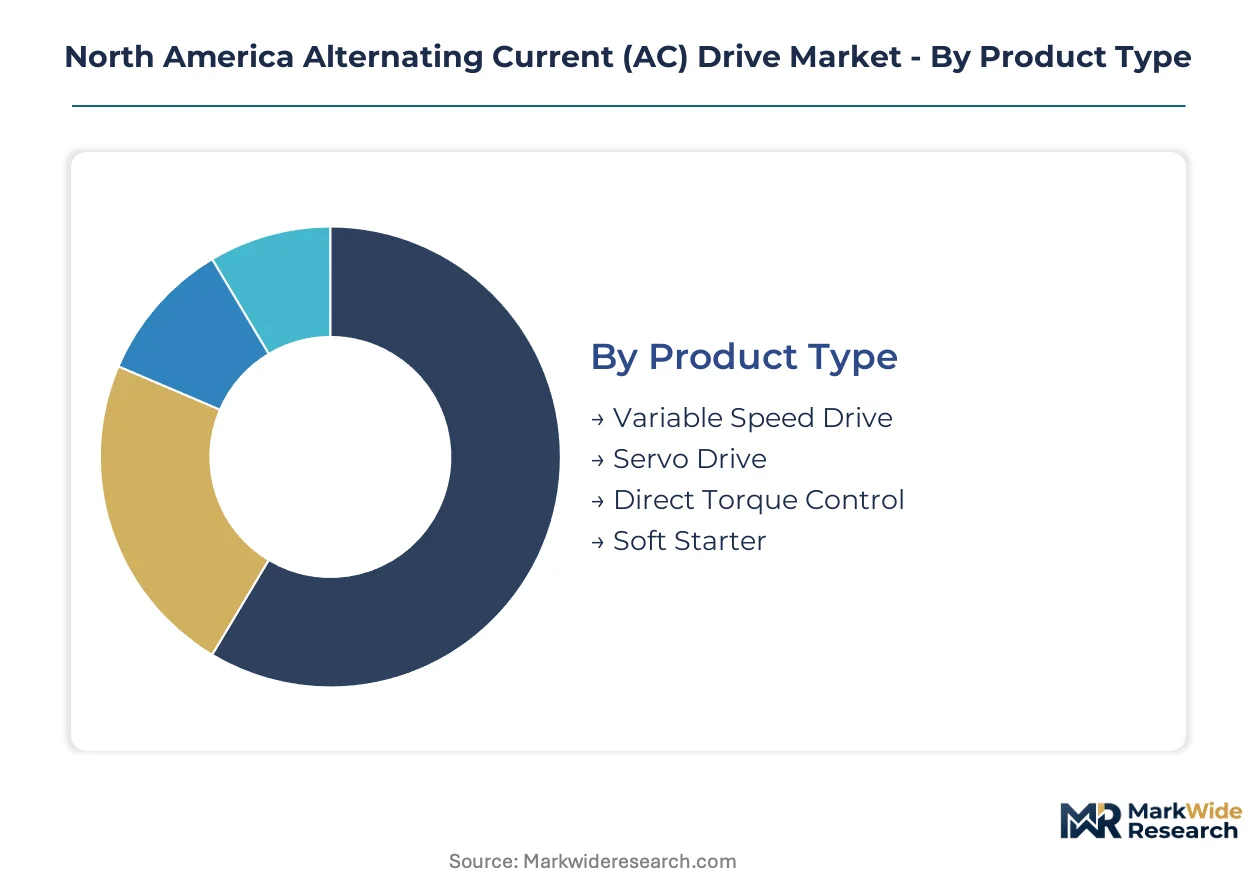
AC drive segmentation in North America reflects divergent engineering requirements across voltage classes, control precision needs, and retrofit constraints. Procurement patterns cluster around specific end-use verticals where regulatory efficiency mandates and operational criticality shape technology selection.
Product Type:
Supply concentration in power electronics manufacturing favors vendors with broad voltage-range portfolios capable of spanning 208V to 690V applications.
- Variable Speed Drive:These units modulate motor speed through frequency and voltage adjustment, typically operating at 2–16 kHz switching frequencies. Texas and California industrial corridors deploy these extensively in petrochemical pump stations where NEMA MG 1 efficiency mandates exclude fixed-speed alternatives. The technology commands the largest installed base due to decades of proven payback in centrifugal fan and pump duty.
- Servo Drive:Precision motion control systems delivering closed-loop position and torque regulation for high-dynamic applications. Arizona and New Mexico semiconductor fabs specify these for cleanroom HVAC and ultrapure water pump control where torque accuracy prevents process contamination. Encoder-based feedback architectures attract premium positioning against sensorless alternatives.
- Direct Torque Control:Advanced algorithmic approach eliminating modulator stages for faster torque response in heavy-industry motor control.
- Soft Starter:Reduced-voltage starting equipment limiting inrush current in fixed-speed applications where full variable speed remains economically unjustified.
Variable Speed Drive absorbs the bulk of installed capacity; Servo Drive is expanding most quickly in precision manufacturing clusters.
End User:
Application intensity varies sharply across customer types, with energy-intensive process industries driving attachment rates above commercial building averages.
- Manufacturing:Encompasses discrete and process operations from automotive stamping to food packaging. The Great Lakes manufacturing belt generates concentrated demand for modular drive configurations in retrofit scenarios where cabinet space constraints limit integrated solutions. Sensorless Vector Control penetration is highest here among mid-range positioning tasks.
- Oil & Gas:Upstream pumpjack operations and downstream refining processes. Texas Permian Basin operators are unbundling after-sales service, negotiating drive-only purchases while sourcing commissioning from specialized system integrators.
- Mining:Harsh-environment conveyance and crushing applications requiring ruggedized enclosures and extended temperature specifications.
- Water Treatment:Municipal pump stations throughout the Colorado River basin and Great Lakes region. Utilities specify multilevel topologies for 480V installations to absorb harmonic mitigation costs internally.
Manufacturing claims the deepest installed base; Water Treatment is climbing the fastest on utility efficiency program support.
Technology:
Control architecture selection hinges on encoder cost economics versus precision requirements, with algorithmic advances narrowing performance gaps.
- VFD:Scalar control methodology maintaining constant volts-per-hertz ratio for general-purpose pump and fan applications. Dominates water treatment and HVAC end uses where dynamic performance requirements remain modest.
- Sensorless Vector Control:Flux estimation algorithms eliminating physical encoders for mid-range positioning tasks. Packaging machinery retrofits across the Midwest manufacturing belt favor this technology where encoder elimination improves project economics.
- Closed Loop Control:Feedback-dependent architectures mandatory for sub-micron positioning in CNC tooling and semiconductor handling equipment.
- Open Loop Control:Basic voltage-frequency control for undemanding constant-torque loads where cost minimization overrides precision.
VFD retains the largest operational footprint; Sensorless Vector Control is gaining share fastest through encoder cost elimination.
Installation:
Physical mounting configuration directly impacts cooling architecture, electromagnetic compatibility, and maintenance accessibility in both greenfield and retrofit contexts.
- Wall-Mounted:Individual drive enclosures affixed to facility structures, prevalent in smaller horsepower ranges where distributed motor control suffices. Food and beverage conveyor systems in Ontario and Quebec processing clusters favor compact decentralized units mounted directly at motor locations.
- Rack-Mounted:Standardized 19-inch or proprietary chassis integration for centralized control rooms. Semiconductor fabs in the Southwest specify these for cleanroom compatibility and coordinated environmental control.
- Integrated:Motor-drive combinations from single vendors reducing installation complexity.
- Modular:Pre-integrated power electronics and communication modules expanding buyer flexibility across project types. Large industrial accounts value the configuration agility for phased retrofit deployments.
Wall-Mounted carries the majority of legacy installations; Modular is expanding most quickly on greenfield project flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in established industrial corridors while consumption spreads across municipal infrastructure and precision manufacturing clusters. The United States dominates installed capacity, though Canadian utility programs accelerate cross-border technology transfer. Mexico's manufacturing expansion absorbs mid-range drive volumes for automotive and electronics assembly.
United States
Petrochemical pump stations across the Texas Gulf Coast and semiconductor fabs in Arizona drive demand for high-precision torque control. The US Department of Energy's motor efficiency regulations mandate NEMA Premium compliance that excludes fixed-speed alternatives in new installations. California's industrial corridors from San Jose to Los Angeles anchor cleanroom HVAC and ultrapure water pump applications requiring variable frequency drive deployment.
Canada
Natural Resources Canada's CANMET program harmonizes federal efficiency standards with provincial utility rebate structures. Ontario and Quebec food processing clusters leverage these incentives for conveyor system upgrades using compact decentralized architectures. Municipal pump stations throughout the Great Lakes region specify multilevel topologies to internalize harmonic mitigation costs under CSA C22.2 enforcement.
Mexico
Automotive assembly plants in Nuevo León and electronics manufacturing in Baja California generate demand for modular drive configurations in greenfield deployments. The country's national energy regulator promotes industrial efficiency standards that align with US NEMA frameworks. Querétaro's aerospace cluster and Guanajuato's automotive corridor absorb mid-range variable speed drives for precision motion applications.
North America Alternating Current (AC) Drive Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with broad voltage-range portfolios spanning 208V to 690V applications. European and Japanese multinationals anchor large industrial accounts through integrated power electronics and communication modules. Three archetypes dominate: full-range system integrators, precision motion specialists, and compact decentralized architects. Capacity expansion in silicon carbide power modules and strategic partnerships for predictive maintenance algorithms represent the dominant competitive vectors.
Among diversified European-based conglomerates, ABB Ltd and Siemens occupy positions exemplifying full-range portfolio coverage across industrial voltage classes. Rockwell Automation, Inc. anchors the integrated automation ecosystem archetype through tight programmable automation controller compatibility. Danfoss represents the compact decentralized specialist tier with motor-mounted architectures for space-constrained food and beverage operations.
| Leading Market Players |
|---|
| ABB Ltd |
| Rockwell Automation, Inc. |
| Danfoss |
| Siemens |
| Yaskawa Electric Corporation |
| WEG Industries |
| Schneider Electric SE |
| Eaton |
| Emerson Electric Co |
| Others |
Value Network & Pricing Analysis
NEMA Premium certification tiers bifurcate the AC drive landscape into compliant and non-compliant supply pools, with certified manufacturers commanding pricing power through US Department of Energy gatekeeping while uncertified competitors retreat to aftermarket refurbishment channels. This tier divergence concentrates procurement authority among vendors with in-house power electronics fabrication, as third-party module sourcing triggers compliance documentation gaps that disqualify bids from Texas petrochemical and California semiconductor accounts.
Pricing Analysis
Margin tightening in standard-tier variable speed drives traces to silicon carbide power module cost volatility and foundry capacity constraints that compress assembler economics. Three-tier pricing structure across premium NEMA Premium-certified, standard IEEE 519-compliant, and economy non-certified levels differentiates on harmonic performance and efficiency curves. Pricing pressure accelerates in the standard tier as Chinese module suppliers expand 690V three-phase offerings. Municipal water treatment utilities exhibit highest price sensitivity due to capital budget cycles, while semiconductor fabs prioritize torque precision over unit cost.
Supply Chain Analysis
Domestic-content mandates under US Buy American provisions and Canada's equivalent federal procurement rules are reshaping sourcing patterns for publicly funded infrastructure projects. Manufacturing concentrates in Germany, Japan, and the United States for insulated-gate bipolar transistor modules and drive assemblies. Raw material dependencies include rare earth elements for permanent magnet motors, copper for windings, and epoxy resins for encapsulation. Single-source vulnerability in silicon carbide wafer supply from Wolfspeed and II-VI facilities threatens multilevel topology expansion. Distribution runs through authorized industrial distributors and direct OEM relationships for large account engineering support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America AC drive market functions as a cost-of-compliance arena where US Department of Energy motor efficiency regulations erect regulatory moats that reward early certification investment and punish laggards with exclusion from new installation specifications.
For Market Incumbents: Extend NEMA Premium certification coverage into compact decentralized architectures to preempt Danfoss specialization in food and beverage conveyor applications. Backward integration into silicon carbide module sourcing reduces exposure to foundry capacity constraints that threaten margin stability. Channel control through exclusive distribution agreements with Great Lakes industrial distributors defends against Rockwell Automation's programmable automation controller ecosystem bundling. For New Entrants and Emerging Players: System integrators represent the most accessible channel for aftermarket service unbundling, particularly in Texas Permian Basin pumpjack retrofits where operators separate hardware procurement from commissioning. Target Ontario and Quebec food processing clusters leveraging provincial utility rebate structures that compress customer payback periods and accelerate purchase decisions. White-space exists in predictive maintenance algorithm development for water treatment utilities seeking to extend pump station service intervals. For Investors and Strategic Acquirers: Re-rating potential sits with sensorless vector control specialists given encoder elimination economics that improve packaging machinery retrofit project returns. Long-term viability favors vendors with multilevel topology intellectual property as IEEE 519 harmonic limits tighten across the analysis window. Acquisition target archetype: compact drive architects with motor-mounted form factors and Canadian provincial rebate program relationships. Watch silicon carbide power module pricing inflection as a signal for margin expansion or compression across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Multilevel Topology Development | Absorbs IEEE 519 harmonic mitigation costs into drive enclosures for Colorado River basin utilities. |
| Silicon Carbide Module Integration | Compresses thermal footprint and switching losses for 690V three-phase industrial applications. |
| Predictive Maintenance Algorithm Licensing | Extends service intervals for water treatment pump stations through vibration and thermal monitoring. |
| Provincial Rebate Program Alignment | Accelerates Ontario and Quebec food processing adoption through Natural Resources Canada harmonization. |
| After-Sales Service Unbundling | Captures Texas oilfield pumpjack retrofit demand through specialized commissioning partnerships. |
Research Methodology
Independent corroboration across plant engineers at Texas petrochemical facilities, procurement leads at Arizona semiconductor fabs, and aftermarket service heads at Midwest distribution channels underwrites the qualitative findings. Primary interviews with water treatment utility maintenance directors, OEM motor control specialists, and power electronics R&D directors combined with secondary validation from US Department of Energy efficiency rulemakings, NEMA MG 1 standard documentation, and IEEE 519 harmonic compliance databases. Bottom-up unit deployment estimates triangulate against top-down industrial motor stock assessments.
The forecast window anchors to historical retrofit penetration rates and greenfield attachment patterns across prior regulatory phase-in periods. Segmentation dimensions span voltage class, control technology, end-use vertical, and installation configuration throughout the projection horizon. CAGRs derive from regression analysis against industrial electricity price trajectories and efficiency mandate enforcement calendars. Industry-specific inputs include semiconductor fab construction pipelines and Great Lakes municipal infrastructure bond issuances for pump station modernization.
Caveats apply where silicon carbide foundry capacity constraints or harmonized IEEE 519-CSA C22.2 enforcement delays could materially shift the outlook. Forecasts embed assumptions regarding NEMA Premium compliance deadlines and provincial rebate program continuity that regulatory revision would invalidate. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Power Line Carrier System Market