
 Aluminium Ion Battery Market | 2026-2036
Aluminium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Ion Battery Market Outlook
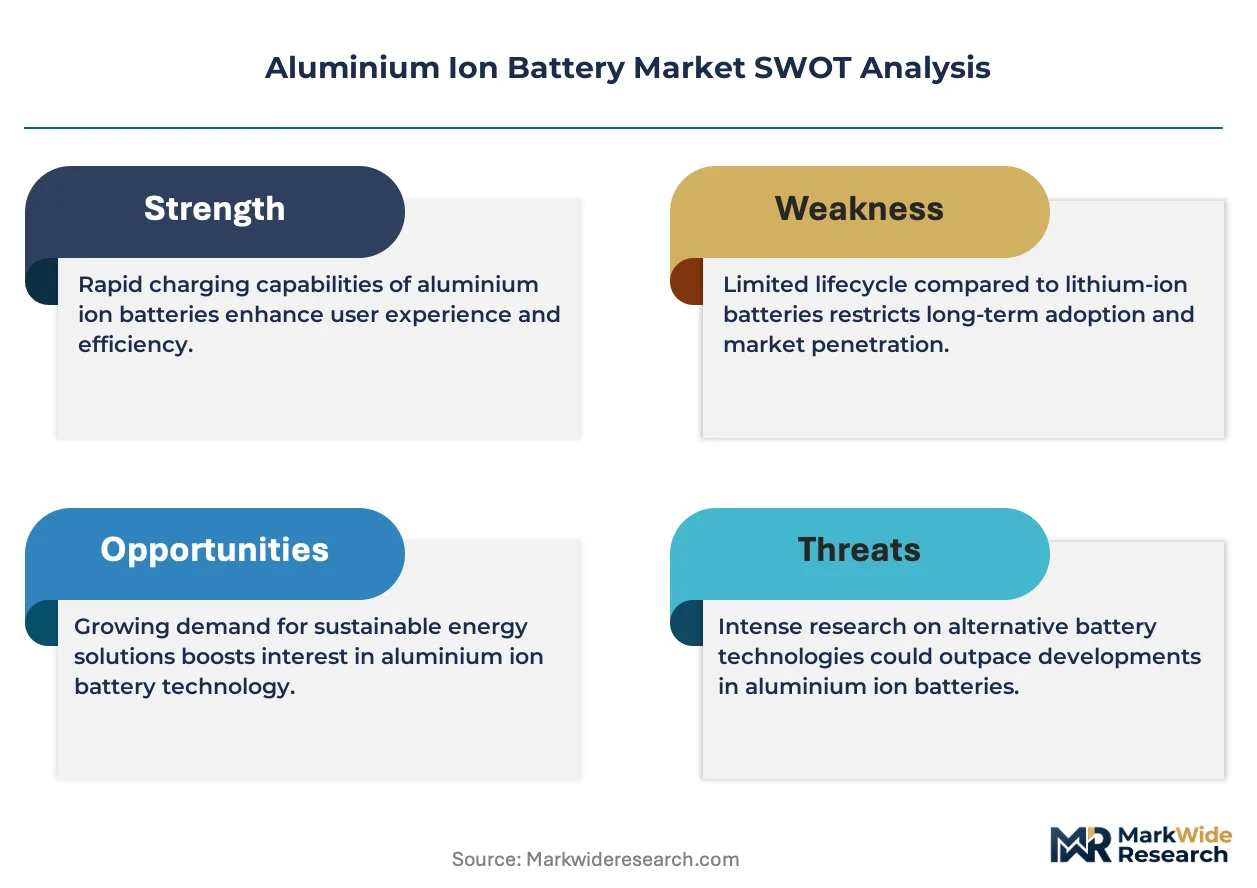
Aluminium is recalibrating cost structures across electrochemical storage as electrode material substitution gathers pace. Graphene Manufacturing Group Ltd. leverages its graphene-aluminium composite cathode expertise to anchor pilot production in Brisbane. Phinergy Ltd. differentiates through its air-aluminium hybrid architecture, while Saturnose sustains R&D intensity on proprietary electrolyte formulations.
An aluminium ion battery stores energy through reversible electrochemical insertion of Al³⁺ ions into host materials, typically operating at 1.5–2.0 V with aqueous or ionic liquid electrolytes that suppress dendrite formation. Secondary batteries command the deepest R&D investment pools as cycle stability improvements unlock automotive qualification pathways. Grid Storage applications attract the fastest policy-driven procurement commitments, while Portable Electronics segments remain margin-constrained by incumbent lithium-ion scale. Energy Density metrics govern competitive positioning, with manufacturers targeting above 150 Wh per kilogram to displace lithium iron phosphate in stationary applications.
The US EPA and NHTSA coordinate tailpipe-emission and battery-safety standards that indirectly channel automotive R&D toward non-lithium chemistries. China's SAMR enforces GB standards for electrochemical storage safety, while the EU Green Deal and REACH frameworks restrict hazardous substances in battery supply chains. Stakeholders must monitor electrolyte formulation patents and cathode host material licensing as gatekeepers to commercial scale.
Market Dynamics
Aluminium-ion chemistry is absorbing capital flows from stranded lithium supply commitments as automakers diversify electrochemical sourcing. China's dual carbon mandate and Australia's raw material proximity are compressing development timelines for pilot-scale manufacturing.
Growth Catalysts
- NMPA Battery Safety Standards:China's GB standards for electrochemical storage are accelerating domestic R&D investment pools and pilot production qualification timelines.
- Graphene-Aluminium Composites:Brisbane's materials cluster combines bauxite access with cathode host material expertise, concentrating engineering talent and pilot infrastructure.
- Grid Storage Procurement:Policy-driven utility commitments for stationary storage are creating anchor demand for aluminium-ion systems above 150 Wh per kilogram.
Market Restraints
- Electrolyte Cost Volatility:Ionic liquid electrolyte precursors face supply concentration from specialty chemical producers, compressing margin structures at pilot scale.
- Cathode Host Limitations:Reversible Al³⁺ insertion kinetics remain slower than lithium-ion equivalents, constraining power density in automotive duty cycles.
- Incumbent Scale Economics:Lithium iron phosphate gigafactory depreciation schedules create pricing floors that aluminium-ion must undercut through material cost advantage.
Strategic Opportunities
- India Stationary Storage:CEA grid modernization mandates and PLI scheme incentives for non-lithium chemistries create first-mover positioning for aluminium-ion developers.
- Air-Aluminium Hybrids:Convergence of metal-air architectures with aluminium-ion electrolytes enables energy density above 400 Wh per kilogram for long-haul aviation.
- Direct Utility Procurement:Bypassing distributor networks through FERC-regulated interconnection agreements accelerates revenue recognition for grid-scale deployments.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Al³⁺ ion transport modeling and dendrite suppression expertise concentrates within academic labs, constraining manufacturing scale-up.
- Automotive Qualification Timelines:UN ECE R100 certification and OEM cell validation protocols demand 24-36 month test cycles before platform integration.
- Patent Thicket Navigation:Electrolyte formulation and cathode host material licensing from university spinouts creates IP transaction costs for commercial entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Ion Battery Market |
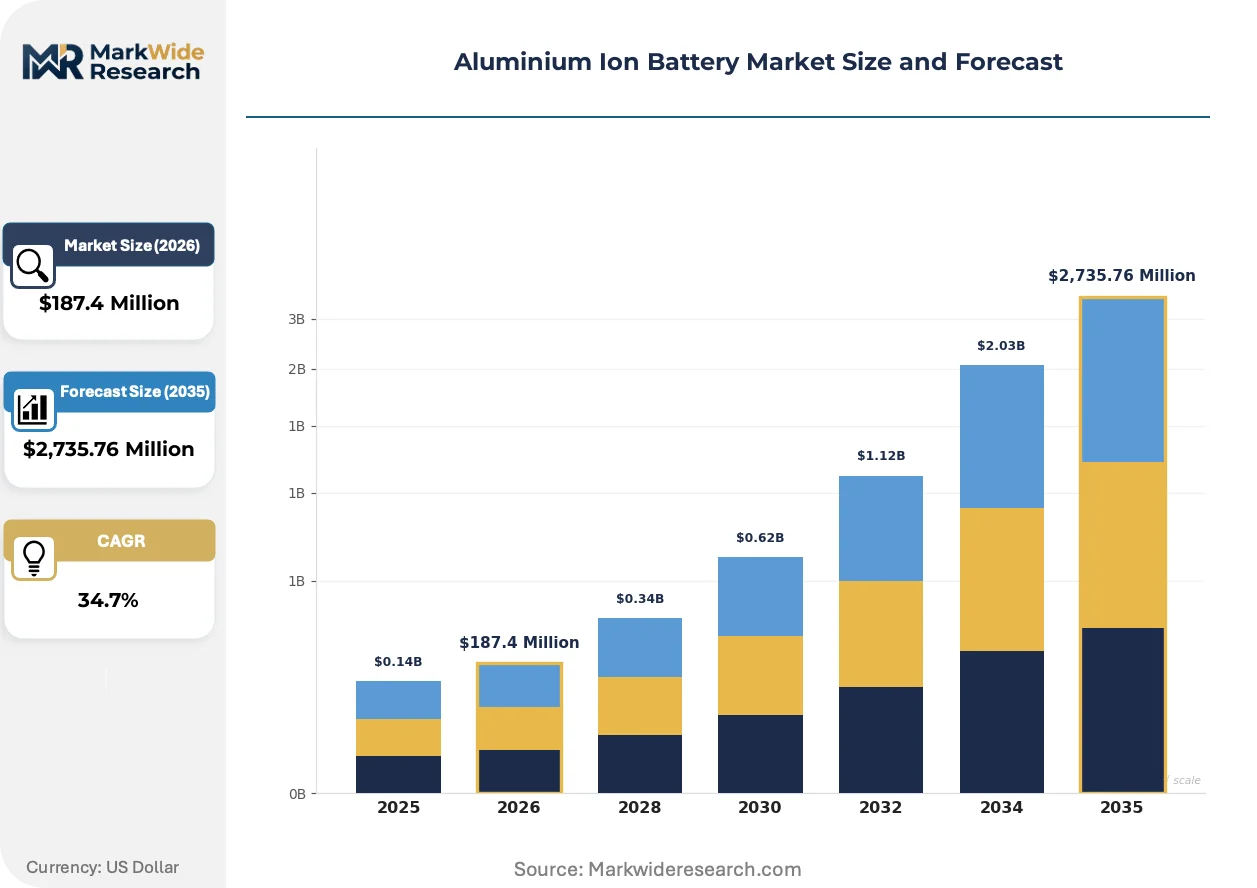
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Batteries, Secondary Batteries, Hybrid Batteries, Supercapacitors Application: Electric Vehicles, Portable Electronics, Grid Storage, Aerospace End User: Automobile Manufacturers, Consumer Electronics, Energy Providers, Military Technology: Energy Density, Cycle Life, Charging Speed, Thermal Stability |
| Companies Covered | Graphene Manufacturing Group Ltd., Saturnose, Ionix Technology, Inc., Phinergy Ltd., Albufera Energy Storage, TasmanIon, Fuji Pigment Co., Ltd., Xinjiang Joinworld Co., Ltd., ACTXE Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Ion Battery Market Strategic Shifts
Graphene-aluminium composite cathodes are compressing development cycles as manufacturers target automotive qualification pathways. Regulatory frameworks across three continents are rewriting electrochemical storage compliance requirements.
Graphene Manufacturing Group's cathode architecture is absorbing engineering resources from conventional graphite anode development. Australian mining integrators are adopting the composite for pilot lines serving Brisbane-based grid storage projects. The technology is absorbing capital that would otherwise flow to solid-state lithium R&D, redirecting materials science talent toward aqueous electrolyte systems.
REACH substance restrictions and EU Green Deal battery passport requirements are forcing electrolyte reformulation away from fluorinated compounds. German automotive OEMs are accelerating compliance timelines for non-lithium supply chains. Stationary storage integrators in the Netherlands are responding by pre-qualifying aluminium-ion systems for circularity certification.
Electric vehicle manufacturers are unbundling cell procurement from pack integration contracts, compressing supplier qualification cycles. Tier-1 battery integrators are losing exclusivity on cathode material sourcing as OEMs pursue direct offtake agreements. This pattern is most visible in China's NEV procurement, where SAMR disclosure rules expose supply chain concentration risks.
Aluminium Ion Battery Market Segmentation
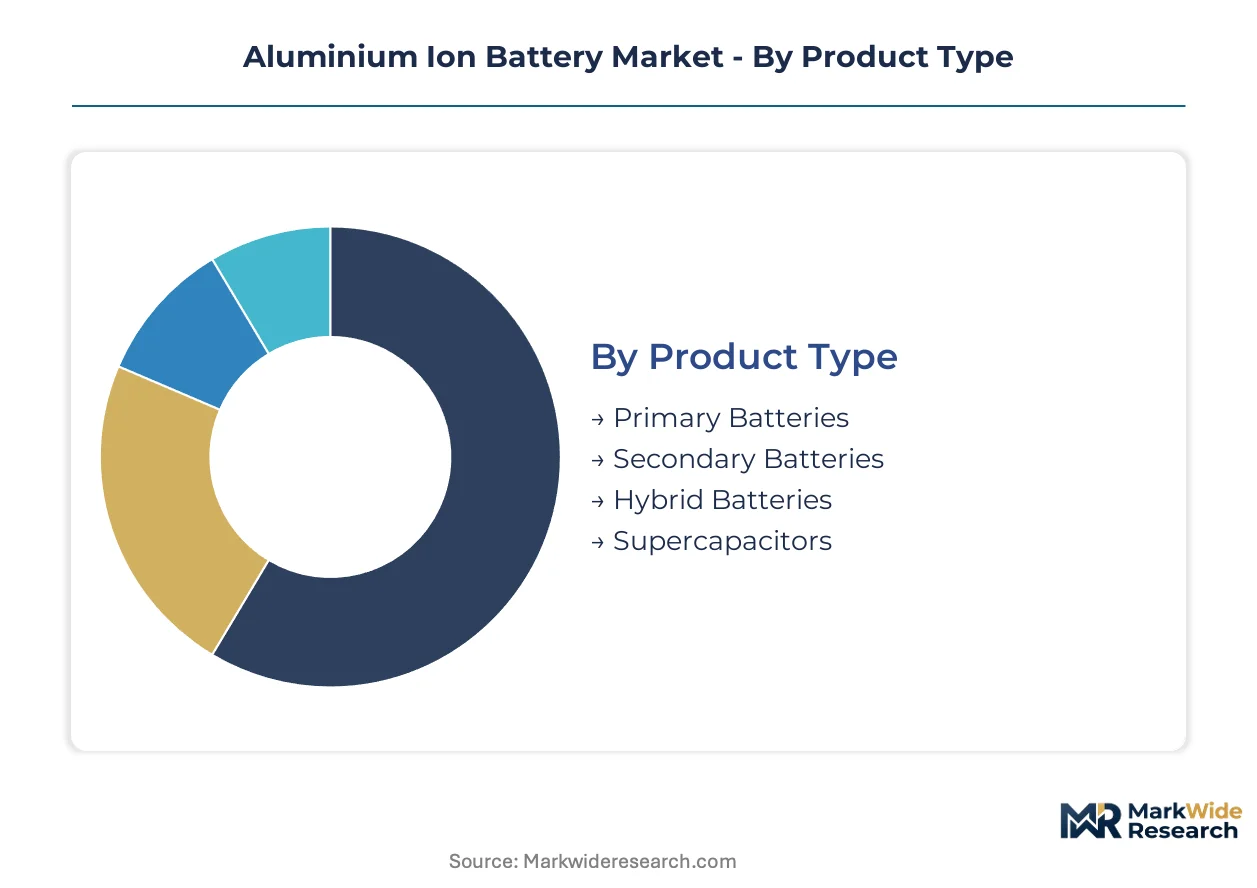
Aluminium-ion battery segmentation reveals how electrochemical performance trade-offs map to distinct procurement budgets and qualification timelines. Product architecture choices determine whether systems target automotive platform integration or stationary storage deployment cycles.
Product Type:
Standardized primary cell formats compete against customized secondary architectures across this category, with customization intensity rising with cycle life requirements.
- Primary Batteries:Single-use aluminium-anode systems deliver immediate energy discharge without recharge infrastructure. Military field operations in remote theaters drive procurement for disposable power units where resupply logistics dominate total cost.
- Secondary Batteries:Reversible Al³⁺ insertion enables 500+ cycle operation with aqueous electrolyte safety profiles. Electric vehicle manufacturers concentrate qualification resources here as UN ECE R100 certification pathways mature for automotive duty cycles.
- Hybrid Batteries:Dual-chemistry architectures combine aluminium-ion base capacity with lithium-ion peak power output. Consumer electronics OEMs evaluate these for device categories requiring both energy density and burst discharge.
- Supercapacitors:Aluminium-graphene electric double-layer configurations deliver sub-second charge acceptance. Grid storage integrators deploy these for frequency regulation services where cycle depth remains shallow.
Leading the category by volume: Secondary Batteries. Expanding most quickly: Hybrid Batteries.
Application:
Cost tier stratification separates premium aerospace qualification from mass-market portable electronics, with grid storage occupying the middle tier.
- Electric Vehicles:Platform-integrated battery packs demand 150 Wh/kg minimum energy density with 10-year calendar life. China's SAMR disclosure rules and NEV procurement mandates are compressing supplier qualification timelines for domestic OEMs.
- Portable Electronics:Smartphone and laptop power budgets prioritize volumetric energy density over absolute cost. Incumbent lithium-ion scale economics constrain aluminium-ion penetration to ruggedized device niches requiring thermal runaway immunity.
- Grid Storage:Utility-scale installations above 100 MWh target levelized cost thresholds through aluminium abundance. India's CEA modernization mandates and PLI scheme incentives are redirecting developer capital toward non-lithium chemistries.
- Aerospace:Crewed aviation applications impose 400 Wh/kg effective density requirements through air-aluminium hybrid architectures. Long-haul electric aircraft developers evaluate these for routes exceeding current lithium-ion range envelopes.
Dominant by procurement value: Grid Storage. Steepest expansion trajectory: Aerospace.
End User:
Customer type determines whether procurement flows through centralized integrator contracts or direct OEM offtake agreements.
- Automobile Manufacturers:Tier-1 battery integrators face disintermediation as OEMs pursue direct cathode material sourcing. This pattern concentrates in China's NEV sector where NMPA safety standards accelerate vertical supply chain restructuring.
- Consumer Electronics:Brand owners specify cell chemistry through pack integration contracts rather than cell-level procurement. Margin compression from incumbent lithium-ion scale limits aluminium-ion design wins to premium ruggedized product lines.
- Energy Providers:Utility procurement departments evaluate 20-year asset life against upfront capital expenditure. FERC-regulated interconnection agreements enable direct revenue recognition bypassing distributor network markups.
- Military:Defense procurement offices prioritize supply chain security and thermal safety over unit cost. Australia's defence materiel organization evaluates Brisbane-sourced graphene-aluminium systems for forward operating base deployment.
Controlling procurement volume: Energy Providers. Gaining share fastest: Military.
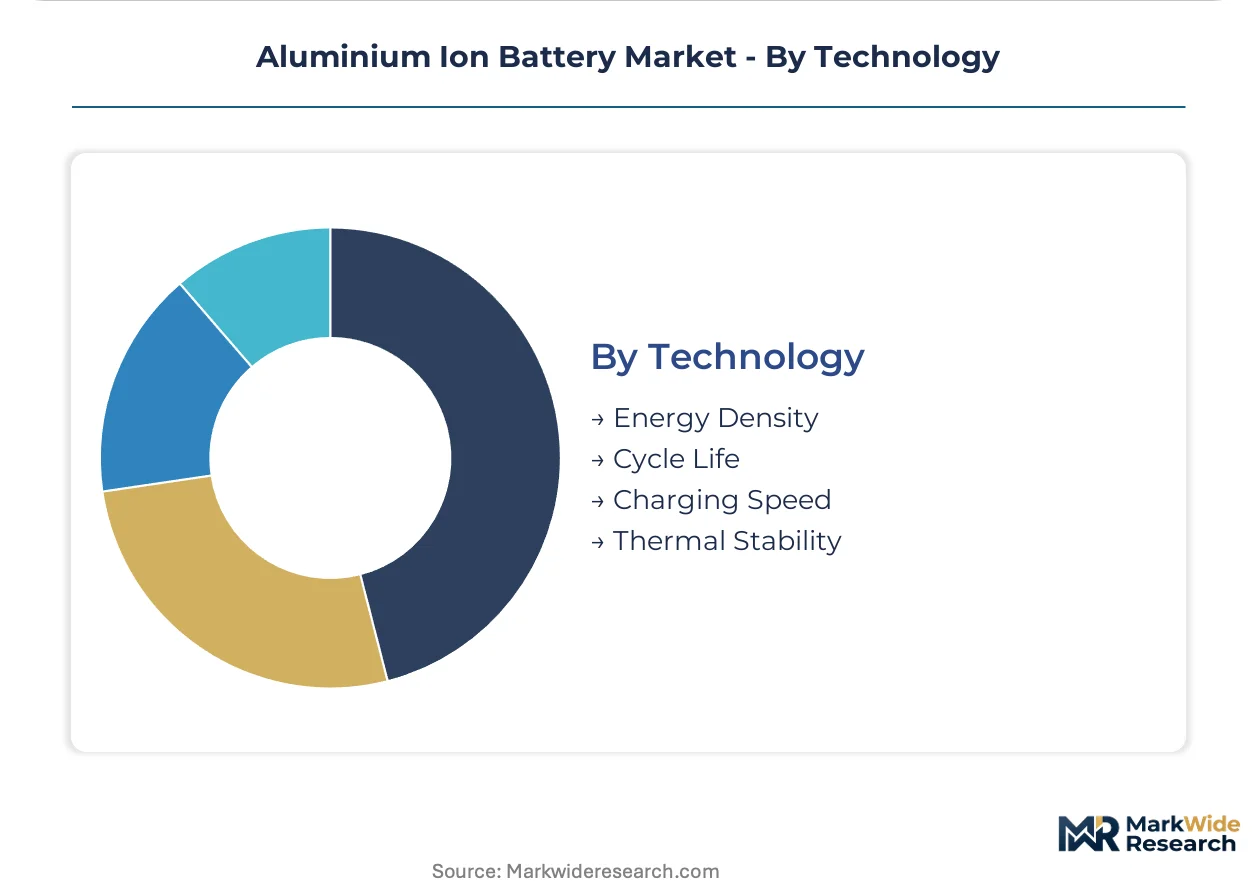
Technology:
Maturity gradients separate commercialized energy density metrics from emerging thermal stability specifications still in validation.
- Energy Density:Gravimetric performance above 150 Wh/kg unlocks stationary storage displacement of lithium iron phosphate. Graphene Manufacturing Group's composite cathode expertise anchors pilot production targeting this threshold.
- Cycle Life:Calendar degradation rates below 2% annually determine automotive platform acceptance. Slower Al³⁺ insertion kinetics relative to lithium-ion constrain power density in high-duty-cycle applications.
- Charging Speed:Ionic liquid electrolyte conductivity governs C-rate performance without dendrite nucleation. Specialty chemical precursor supply concentration from limited producers creates input cost volatility.
- Thermal Stability:Aqueous electrolyte systems eliminate thermal runaway propagation risks. EU REACH substance restrictions and battery passport requirements are accelerating reformulation away from fluorinated compounds.
Primary competitive battleground: Energy Density. Advancing most rapidly: Thermal Stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon mandate and Australia's raw material proximity are compressing development timelines for pilot-scale manufacturing. Electric vehicle manufacturers in Germany and the United States are expanding procurement of aluminium-ion cells as lithium supply constraints persist. India's grid modernization programs are redirecting developer capital toward non-lithium chemistries.
China
SAMR disclosure rules and NMPA battery safety standards are accelerating domestic R&D investment pools. The country's dual carbon goals compress qualification timelines for domestic OEMs seeking non-lithium supply chains. Pilot production facilities in Shenzhen and Shanghai concentrate engineering talent for graphene-aluminium composite cathode development.
Australia
Brisbane's materials cluster combines bauxite access with cathode host material expertise. The country's defence materiel organization evaluates graphene-aluminium systems for forward operating base deployment. Queensland's mining integrators adopt composite cathodes for grid storage projects serving utility-scale installations.
Germany
Automotive OEMs accelerate compliance timelines for non-lithium supply chains under EU Green Deal battery passport requirements. REACH substance restrictions force electrolyte reformulation away from fluorinated compounds. Stationary storage integrators in the Netherlands pre-qualify aluminium-ion systems for circularity certification.
United States
EPA and NHTSA coordinate tailpipe-emission and battery-safety standards that channel automotive R&D toward non-lithium chemistries. FERC-regulated interconnection agreements enable direct revenue recognition bypassing distributor networks. California-based grid developers evaluate aqueous electrolyte systems for thermal runaway immunity.
India
CEA grid modernization mandates and PLI scheme incentives for non-lithium chemistries create first-mover positioning for aluminium-ion developers. Policy-driven utility commitments for stationary storage above 100 MWh redirect capital from lithium iron phosphate. Tamil Nadu and Gujarat concentrate manufacturing scale-up efforts for automotive qualification pathways.
Aluminium Ion Battery Market Competitive Environment
Capacity expansion dominates the current landscape as developers race to secure pilot production qualification before automotive OEMs finalize platform decisions. The vendor base clusters around three strategic archetypes: graphene-aluminium composite specialists, air-aluminium hybrid architects, and aqueous electrolyte formulators. Geographic concentration in Australia and China reflects raw material proximity and regulatory acceleration. Competitive moves center on cathode host material licensing and direct utility offtake agreements that bypass traditional integrator networks.
Within the composite cathode tier, Graphene Manufacturing Group Ltd. and Phinergy Ltd. exemplify divergent technical approaches to energy density optimization. Saturnose occupies a position among electrolyte formulation specialists pursuing proprietary aqueous systems. Fuji Pigment Co., Ltd. and Xinjiang Joinworld Co., Ltd. represent materials-integrated players with upstream access to precursor supply chains. TasmanIon and Albufera Energy Storage sit within the European development cluster, anchoring regional qualification efforts under REACH and EU Green Deal compliance frameworks. Ionix Technology, Inc. and ACTXE Limited exemplify venture-stage entrants targeting niche stationary storage deployments.
| Leading Market Players |
|---|
| Graphene Manufacturing Group Ltd. |
| Saturnose |
| Ionix Technology, Inc. |
| Phinergy Ltd. |
| Albufera Energy Storage |
| TasmanIon |
| Fuji Pigment Co., Ltd. |
| Xinjiang Joinworld Co., Ltd. |
| ACTXE Limited |
| Others |
Value Chain & Pricing Dynamics
Ionic liquid electrolyte precursors flow from specialty chemical producers through contract manufacturers to cell assemblers, with concentration in German and Japanese suppliers creating tiered pricing power across automotive qualification batches versus grid storage volume offtake.
Pricing Analysis
Volume-margins split sharply between automotive qualification batches commanding certification premiums and grid storage volume contracts compressing unit economics. Three-tier pricing structure across automotive-grade, industrial-standard, and pilot-economy levels separates UN ECE R100 certified cells from CEA-prequalified stationary systems. Pricing pressure stems from lithium iron phosphate gigafactory depreciation schedules forcing aluminium-ion to undercut through material cost advantage. Energy providers exhibit highest price sensitivity through 20-year asset life evaluation, while military procurement prioritizes thermal safety over unit cost.
Supply Chain Analysis
China's GB standards and India's PLI scheme domestic-content mandates are reshaping sourcing patterns for cathode host materials and electrolyte precursors. Bauxite extraction concentrates in Australia and Guinea, while graphene-aluminium composite processing anchors in Brisbane and Shenzhen. Specialty ionic liquid production draws from German and Japanese chemical producers, creating single-source vulnerability for automotive qualification timelines. Distribution runs through direct utility offtake agreements bypassing traditional Tier-1 integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty chemical precursor capacity constraints prop pricing premiums for automotive-grade electrolyte formulations, sustaining margin pools for qualified suppliers through the supply-constrained window.
For Market Incumbents: Lock in cathode host material licensing from university spinouts before patent thicket thickening raises IP transaction costs. Secure captive supply of bauxite feedstock through Queensland mining integrator partnerships to defend against graphene-aluminium composite cost volatility. Accelerate UN ECE R100 certification completion ahead of OEM platform finalization deadlines.
For New Entrants and Emerging Players: Launch via FERC-regulated interconnection agreements targeting California and Texas grid developers seeking thermal runaway immunity. Penetrate India's CEA-mandated stationary storage procurement where PLI incentives reduce incumbent lithium-ion scale advantage. Pursue direct utility offtake models bypassing distributor markups to compress customer acquisition costs.
For Investors and Strategic Acquirers: First automotive OEM platform integration announcement is the leading indicator that aluminium-ion has crossed the commercial threshold. Five-to-ten year viability rests on electrolyte formulation specialists achieving aqueous system scale. Target acquisition archetype: graphene-aluminium composite developers with pilot production qualification and Brisbane materials cluster proximity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyte Formulation Scale-Up | Aqueous system commercialization unlocks automotive qualification pathways under NMPA standards. |
| Graphene-Aluminium Cathode Licensing | Composite expertise from Brisbane cluster anchors grid storage procurement above 150 Wh per kilogram. |
| Direct Utility Offtake Agreements | FERC-regulated interconnection bypasses distributor networks for revenue recognition acceleration. |
| Automotive OEM Platform Integration | UN ECE R100 certification completion signals crossover to mass-market electric vehicle supply chains. |
| India PLI Scheme Qualification | CEA modernization mandates redirect developer capital toward non-lithium chemistry first-movers. |
Study Parameters
Multi-period observation of pilot production qualification timelines, electrolyte precursor pricing indices, and automotive OEM sourcing announcements anchored the trend analysis, supplemented by interviews with cell engineering directors, utility procurement officers, mining integrator supply planners, and NMPA regulatory affairs specialists. Secondary validation drew from SAMR disclosure filings, CEA grid modernization mandates, FERC interconnection databases, and GB standards documentation. Bottom-up cell cost modeling triangulated against top-down utility procurement budget forecasts.
Input-output matrices mapped cathode host material throughput, electrolyte formulation batch yields, and pack integration labor content across product type, application, and technology segmentation dimensions. CAGRs were derived from slope analysis of pilot-to-commercial transition curves and policy-driven procurement commitment trajectories. Forecast inputs incorporated bauxite feedstock availability projections and graphene manufacturing yield improvements.
Patent litigation acceleration, automotive platform cancellation decisions, and ionic liquid precursor supply disruptions are the dominant revision risks to commercialization timelines. Forecasts reflect documented assumptions on qualification cycle durations and policy incentive continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Li Metal Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Automotive Cylindrical Lithium Batteries Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium-Ion Stationary Battery Storage Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
Lithium-Sulfur Battery Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
France SLI Battery Market