
 Mobile Hydraulic Valves Market | 2026-2036
Mobile Hydraulic Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Hydraulic Valves Market Foresight
The EU Green Deal is expanding compliance obligations for off-road mobile equipment across European member states. Bosch Rexroth leverages its integrated drivetrain expertise to anchor electrohydraulic valve portfolios for construction OEMs. Danfoss AS competes through advanced proportional technology platforms optimized for precision agriculture implements. Parker Hannifin Corp sustains manufacturing scale advantages across North American and Asian distribution networks.
Mobile hydraulic valves regulate fluid direction, pressure, and flow rate in dynamic off-road equipment through spool-and-sleeve architectures rated for pressures exceeding 350 bar. These components translate operator or electronic inputs into precise actuator movement, enabling load-holding and motion control in harsh vibration environments. Directional control valves occupy the largest product category due to universal deployment across loader and excavator circuits. Electrohydraulic technology leads growth trajectories as CAN-bus integration replaces mechanical linkages in next-generation machinery. Agricultural machinery applications command premium positioning where GPS-coordinated implements demand sub-second response accuracy.
The US EPA Tier 4 Final and EU Stage V frameworks mandate particulate and NOx reductions that force engine compartment packaging density, squeezing hydraulic component envelope dimensions and thermal tolerance requirements. ISO 4413 and IEC 61508 standards govern fluid power system safety and functional safety integrity for electrohydraulic controls in autonomous equipment. Japan's METI promotes carbon-neutral construction machinery roadmaps that accelerate electric-hybrid hydraulic system development. Stakeholders must monitor regulatory divergence between emission-focused engine standards and emerging safety-critical electronics protocols when allocating R&D resources across product architectures.
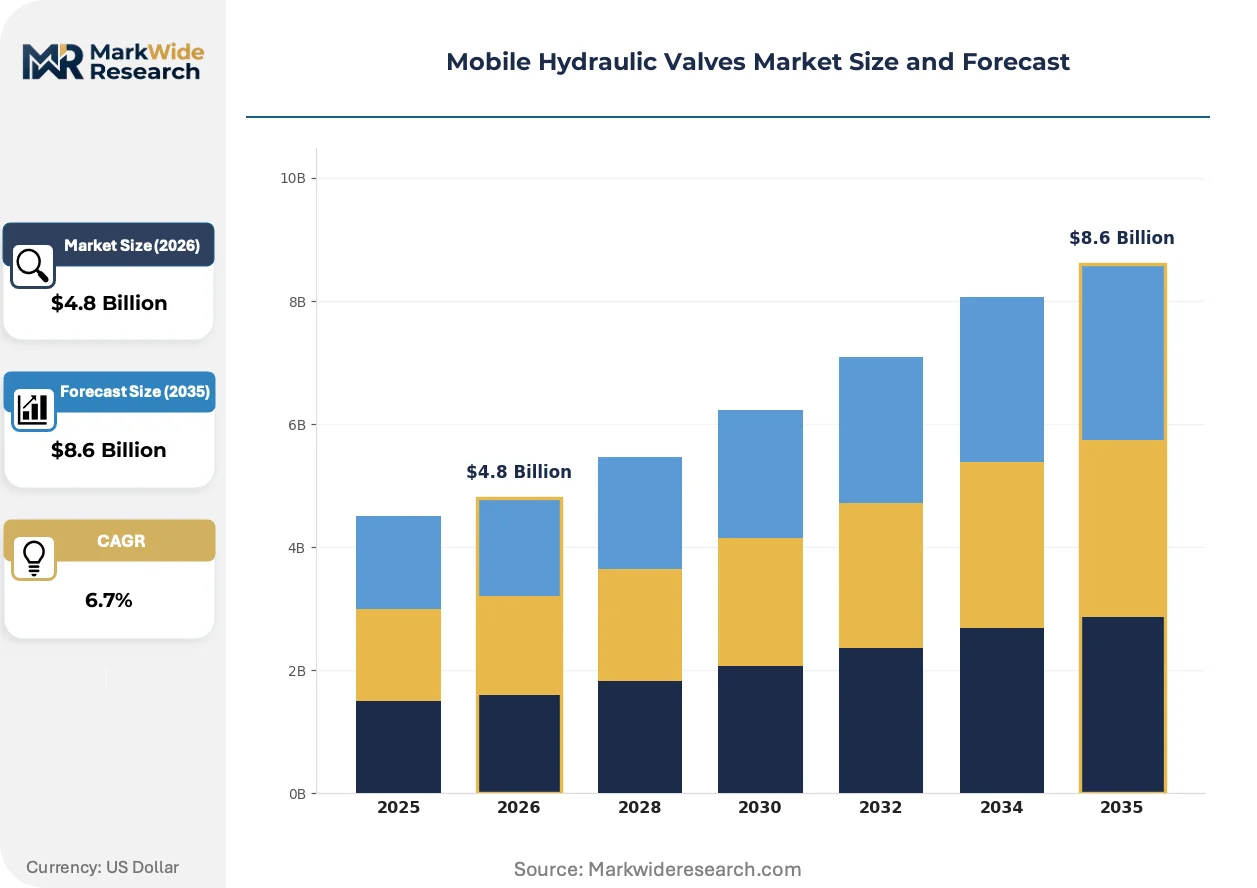
Market Dynamics
Electrohydraulic valve architectures are displacing mechanical spool systems as construction and agriculture OEMs pursue CAN-bus integration for autonomous machine control, compressing supplier lead times and forcing component miniaturization to meet tighter engine compartment packaging.
Growth Catalysts
- EU Stage V mandates:German and Italian construction equipment manufacturers accelerate procurement of compact electrohydraulic directional valves to satisfy particulate and NOx reduction requirements.
- Precision agriculture:GPS-guided hydraulic implements across Brazil's Mato Grosso region demand proportional flow control valves with sub-second response accuracy.
- Japan's carbon-neutral roadmaps:METI-promoted electric-hybrid hydraulic systems expand addressable market for integrated valve-drivetrain packages in excavator and loader segments.
Market Restraints
- Specialized casting alloys:Spool-and-sleeve architectures require high-grade ductile iron with limited qualified foundry capacity concentrated in Germany and Japan.
- Functional safety certification costs:IEC 61508 compliance for autonomous electrohydraulic controls extends development timelines and raises barrier to entry for mid-tier suppliers.
- Electromechanical actuation:All-electric linear actuators threaten proportional valve demand in light-duty agricultural implements below 150 bar operating pressure.
Strategic Opportunities
- Indian construction equipment:Domestic infrastructure investment and quarrying expansion create unmet demand for cost-optimized directional control valves with simplified maintenance protocols.
- Telematics integration:Convergence of hydraulic valve position sensors with IoT platforms enables predictive maintenance service models for rental fleet operators.
- US Midwest precision farming:Variable-rate seeding and spraying implements drive specification of multi-section proportional valves with independent flow zones.
Industry Challenges
- Mechatronics engineering scarcity:Valve manufacturers compete for talent capable of bridging fluid power physics with embedded software development for CAN-bus valve controllers.
- Legacy system integration:Electrohydraulic retrofits into existing excavator and loader fleets require custom manifold adaptations that fragment production volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Hydraulic Valves Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Directional Control Valves, Pressure Relief Valves, Flow Control Valves, Check Valves Technology: Electrohydraulic, Proportional, Pneumatic, Manual Application: Agricultural Machinery, Construction Equipment, Material Handling, Mobile Equipment End User: OEMs, Aftermarket Suppliers, Contractors, Service Providers |
| Companies Covered | Parker Hannifin Corp, Danfoss AS, Eaton Corporation PLC, Bosch Rexroth, OMAX Hydraulics Industrial, Poclain Hydraulics, Bucher Hydraulics, Moog Inc, Sun Hydraulics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Hydraulic Valves Market Shifts & Advancements
Digital valve control architectures are compressing the traditional separation between hydraulic hardware and machine electronics, enabling closed-loop automation that reduces operator skill requirements while demanding new supplier competencies in firmware and sensor fusion.
Proportional valve technology with integrated load-sensing electronics is expanding into mid-size excavator and wheel loader platforms previously served by pure mechanical systems. Korean and Chinese construction OEMs now specify these valves for 20-ton class machines. This expansion is compressing price premiums for electronic control functionality and forcing mechanical valve specialists to develop partnership strategies or cede volume.
The EU Green Deal's extended compliance obligations for off-road mobile equipment are mandating tighter envelope constraints that favor compact cartridge valve configurations over traditional stack-mounted directional controls. Engine compartment thermal management requirements now specify valve materials rated beyond 120°C ambient. Agricultural machinery manufacturers in France and Germany are responding with sealed electronic valve packages that isolate circuitry from hydraulic fluid contamination.
Rental fleet operators and large agricultural contractors are consolidating procurement authority into centralized technical purchasing functions that bypass traditional distribution channels. These buyers now demand valve performance data transparency and direct manufacturer technical support. The shift is most visible in North American construction equipment leasing, where national fleet managers negotiate frame agreements with valve suppliers for standardized maintenance protocols across mixed-brand equipment pools.
Mobile Hydraulic Valves Market Segmentation
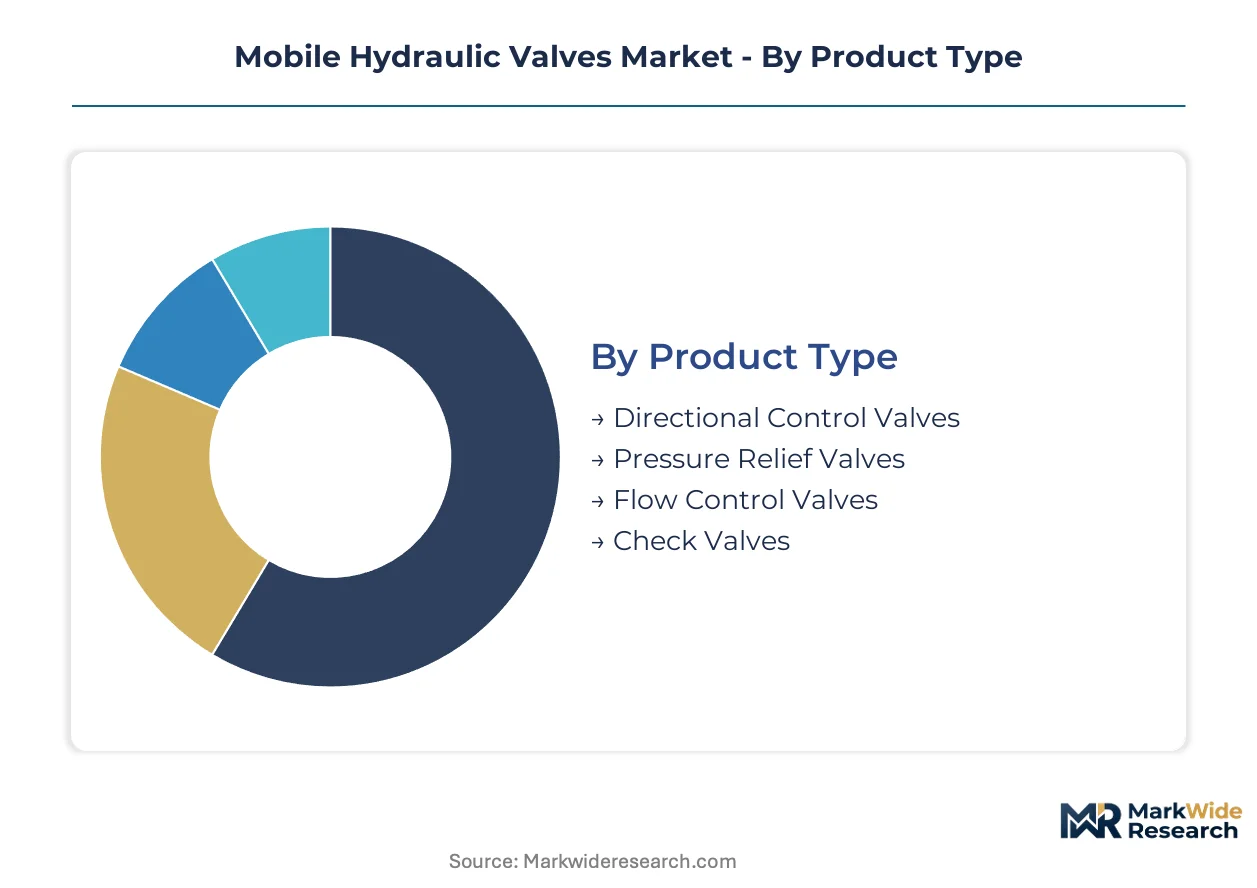
Mobile hydraulic valve manufacturers engineer distinct product architectures for each application tier. Specification requirements diverge sharply between precision agriculture and heavy construction, forcing portfolio diversification across pressure ratings, response speeds, and electronic integration levels.
Product Type:
Pressure tolerance and flow dynamics separate these architectures, with each configuration optimized for specific circuit functions and duty cycles.
- Directional Control Valves:Spool-and-sleeve mechanisms route fluid between actuator ports through precisely machined lands and grooves. German construction OEMs specify these for excavator boom and bucket circuits where load-holding reliability is critical. Thermal tolerance requirements now exceed 120°C ambient due to Stage V engine compartment density.
- Pressure Relief Valves:Spring-loaded or pilot-operated designs limit maximum system pressure to protect pump and actuator integrity. Brazilian sugarcane harvester manufacturers deploy these in high-shock lifting circuits where pressure spikes from sudden load drops would damage downstream components.
- Flow Control Valves:Orifice-based regulation manages actuator speed independent of load variations.
- Check Valves:Ball or poppet configurations permit unidirectional flow to prevent cylinder drift and maintain load position.
Mature deployment sits with directional control valves. Newer deployment is concentrated in integrated pressure relief assemblies with electronic sensing.
Technology:
Control interface architecture determines competitive positioning, with electronic integration now commanding premium specification across mid-size equipment platforms.
- Electrohydraulic:CAN-bus integrated solenoid actuation replaces mechanical linkages, enabling closed-loop position feedback and autonomous machine control. Japanese excavator OEMs specify these for 20-ton class machines under METI carbon-neutral roadmaps. IEC 61508 functional safety certification extends development timelines but locks in supplier relationships.
- Proportional:Continuous spool positioning delivers variable flow rates proportional to electrical input signal. US Midwest precision farming operations demand sub-second response accuracy for GPS-coordinated variable-rate implements. Price premiums are compressing as Korean and Chinese OEMs adopt these for wheel loaders.
- Pneumatic:Compressed air pilot control suits explosive atmosphere applications and simplified maintenance protocols.
- Manual:Direct mechanical linkage persists in cost-optimized markets and legacy fleet replacement.
Volume concentration remains with manual systems. Value expansion is climbing the fastest in electrohydraulic platforms with integrated sensor fusion.
Application:
Operating environment severity and precision requirements create distinct specification clusters across mobile equipment categories.
- Agricultural Machinery:GPS-guided implements require multi-section proportional valves with independent flow zones for seeding and spraying accuracy. France and Germany lead sealed electronic package adoption to isolate circuitry from chemical contamination and hydraulic fluid exposure.
- Construction Equipment:Harsh vibration and shock loading demand ductile iron castings rated beyond 350 bar with fatigue-resistant spool geometries. Indian quarrying expansion drives specification of simplified maintenance protocols for dust-intensive operating conditions.
- Material Handling:Forklift and telehandler circuits prioritize compact cartridge configurations for tight mast and boom envelope constraints.
- Mobile Equipment:Specialty vehicle applications span aerial work platforms, mining trucks, and forestry harvesters with customized manifold adaptations.
Revenue scale favors construction equipment. Specification innovation is concentrating most intensely in agricultural machinery with autonomous implement coordination.
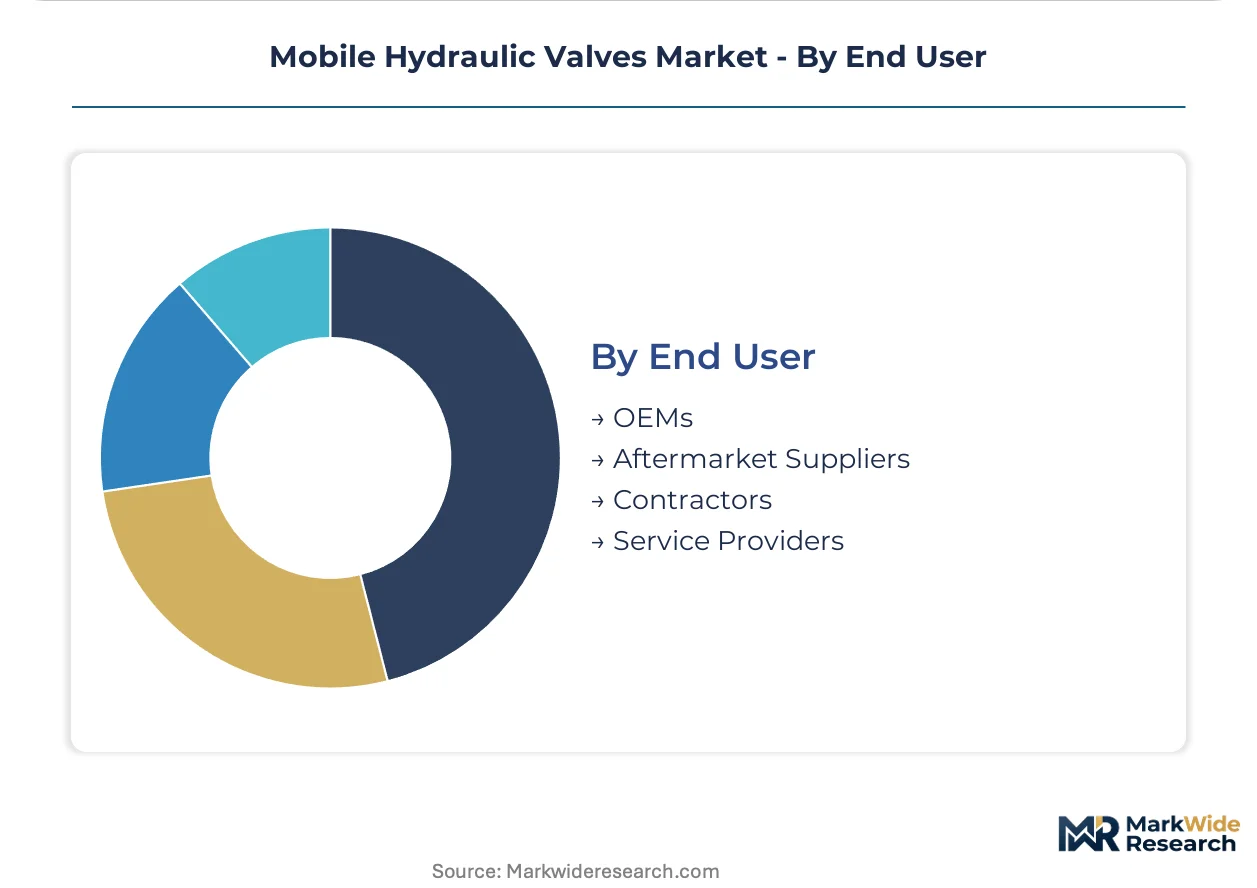
End User:
Procurement authority consolidation is restructuring channel relationships, with technical purchasing functions bypassing traditional distribution networks.
- OEMs:Frame agreements with integrated drivetrain suppliers secure volume pricing and direct engineering support. North American construction equipment manufacturers negotiate standardized maintenance protocols across mixed-brand equipment pools.
- Aftermarket Suppliers:Independent distributors and remanufacturers serve legacy fleet replacement demand with cost-optimized alternatives.
- Contractors:Large agricultural operators in Brazil's Mato Grosso region consolidate specification authority for GPS-coordinated implement fleets.
- Service Providers:Rental fleet operators demand valve performance data transparency and predictive maintenance integration through telematics platforms.
Direct procurement dominates among OEMs. Telematics-enabled service models are expanding fastest among rental fleet operators with national equipment pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for electrohydraulic valve systems serving German construction OEMs under Stage V emission mandates. Regional procurement patterns concentrate around precision agriculture clusters in North America and carbon-neutral machinery roadmaps in Japan.
United States
Midwest precision farming operations drive specification of GPS-coordinated hydraulic implements across Iowa and Illinois. EPA Tier 4 Final mandates compress engine compartment packaging, forcing valve miniaturization. Chicago-area distributors consolidate procurement authority for multi-section proportional valves serving variable-rate seeding equipment.
Germany
Construction equipment manufacturers in Bavaria and Baden-Württemberg accelerate adoption of compact electrohydraulic directional valves. EU Green Deal obligations extend compliance timelines for off-road machinery through 2035. Stuttgart-based engineering clusters integrate valve-drivetrain packages for excavator OEMs targeting emission-reduction benchmarks.
Japan
Excavator producers in the Chubu region around Nagoya specify electrohydraulic valves for 20-ton class machines under METI carbon-neutral roadmaps. METI promotes electric-hybrid hydraulic system development through 2030 targets. Osaka-area component suppliers scale manufacturing of integrated valve packages for loader and excavator segments.
Brazil
Sugarcane and soybean operations in Mato Grosso demand proportional flow control valves with sub-second response accuracy for GPS-guided implements. ANVISA regulates agricultural chemical exposure, driving sealed electronic valve adoption. São Paulo-based machinery distributors negotiate frame agreements for precision agriculture fleets across the Cerrado biome.
India
Domestic infrastructure investment and quarrying expansion in Maharashtra and Gujarat create demand for cost-optimized directional control valves. BIS standards govern hydraulic component safety in construction equipment. Pune-area manufacturers develop simplified maintenance protocols for dust-intensive operating conditions in mining and road-building applications.
Mobile Hydraulic Valves Market Competitive Landscape
Premium-margin players sit above commodity-margin players across electrohydraulic integration depth and functional safety certification. The vendor base stratifies between integrated drivetrain specialists, standalone valve manufacturers, and regional fabrication houses. Three archetypes dominate: diversified fluid power conglomerates with construction OEM frame agreements; precision agriculture specialists with GPS-coordination expertise; and emerging Asian fabricators serving cost-optimized markets. Competitive moves concentrate on strategic partnerships for CAN-bus integration and geographic expansion into Indian and Southeast Asian construction equipment markets.
Within the diversified fluid power tier, Parker Hannifin Corp and Danfoss AS exemplify scale-driven positions across North American and European distribution networks. Bosch Rexroth anchors the integrated drivetrain archetype through electrohydraulic valve portfolios developed for German construction OEMs. These three entities represent distinct competitive vectors: manufacturing scale, proportional technology platforms, and system-level integration expertise respectively.
| Leading Market Players |
|---|
| Parker Hannifin Corp |
| Danfoss AS |
| Eaton Corporation PLC |
| Bosch Rexroth |
| OMAX Hydraulics Industrial |
| Poclain Hydraulics |
| Bucher Hydraulics |
| Moog Inc |
| Sun Hydraulics Corporation |
| Others |
Supply & Pricing Matrix
Ductile iron spot indices in Germany and Japan cascade through foundry tolling arrangements into three-tier pricing structures across premium, standard, and economy levels. OEM frame agreements with Bosch Rexroth and Parker Hannifin compress spot-market premiums for electrohydraulic platforms while Indian quarrying demand sustains cost-optimized mechanical valve tiers.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for rental fleet operators demanding predictive maintenance integration. Price differentiation separates IEC 61508-certified electrohydraulic systems from uncertified proportional alternatives, with brand premiums concentrated in German and Japanese construction OEM procurement. Cost compression in mid-tier proportional valves is intensifying because Korean and Chinese OEM adoption erodes legacy price premiums. Aftermarket suppliers exhibit highest price sensitivity, while OEM frame agreement holders prioritize technical support bundling over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German construction equipment manufacturers and Brazilian agricultural machinery distributors. Manufacturing concentrates in Germany, Japan, and China, with high-grade ductile iron casting capacity anchored in Stuttgart and Nagoya industrial clusters. Raw material dependencies include nickel-alloyed ductile iron, precision-machined spool blanks, and sealed electronic sensor packages. Single-source vulnerability sits with qualified foundry capacity for 350 bar-rated spool-and-sleeve architectures. Distribution runs through integrated drivetrain suppliers for OEM tier-one procurement and specialized hydraulics distributors for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile hydraulic valves market functions as a vertical-integration race where captive control over foundry capacity and firmware development determines margin capture. Players are pursuing downstream service integration through telematics-enabled predictive maintenance platforms to lock in rental fleet relationships.
For Market Incumbents: Anticipate margin compression in 20-ton excavator proportional valves as Korean OEMs localize supply chains. Defensive consolidation should prioritize backward integration into ductile iron foundry capacity in Germany and Japan to secure alloy supply against qualified-supplier bottlenecks. IEC 61508 certification investment locks in autonomous equipment partnerships before mid-tier competitors close functional safety gaps. For New Entrants and Emerging Players: E-commerce aftermarket platforms offer lowest channel friction for penetrating Indian quarrying and construction equipment maintenance markets. White-space targets include cost-optimized directional control valves with simplified maintenance protocols for dust-intensive operating conditions in Maharashtra and Gujarat. Telematics-agnostic valve position sensors for legacy fleet retrofits represent the most penetrable application tier. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision agriculture specialists with GPS-coordination firmware expertise in the US Midwest. Long-term viability over the next decade hinges on CAN-bus integration depth and sensor fusion capabilities rather than pure hydraulic hardware scale. Monitor METI carbon-neutral roadmap implementation velocity as the inflection signal for electric-hybrid hydraulic system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive ductile iron supply in Germany secures Stage V thermal tolerance specifications. |
| CAN-Bus Firmware Development | Embedded software integration differentiates electrohydraulic platforms for autonomous excavator OEMs. |
| Telematics Sensor Partnership | Valve position data convergence with IoT platforms enables predictive maintenance revenue streams. |
| Precision Agriculture Specialist Acquisition | GPS-coordination expertise accelerates penetration of variable-rate implement markets in Brazil. |
| Indian Distribution Channel Buildout | Direct technical support infrastructure captures quarrying expansion demand in Maharashtra. |
Research Methodology
Document review covered EU Stage V regulatory filings, METI carbon-neutral machinery roadmaps, and ISO 4413 fluid power safety standards, complemented by interviews with hydraulic systems engineers at German construction OEMs, procurement directors at Brazilian agricultural machinery distributors, maintenance directors at North American rental fleet operators, and foundry operations managers in Stuttgart and Nagoya. Secondary validation drew from customs trade data for ductile iron alloy shipments, SEC 10-K disclosures from diversified fluid power conglomerates, and patent filings for electrohydraulic control architectures. Bottom-up equipment production forecasts and top-down OEM procurement spend estimates were triangulated against regional infrastructure investment databases.
Historical shipment volumes from excavator and loader production databases were cross-referenced against panel input from OEM procurement teams to establish baseline market sizing. The analytical framework modeled segmentation across product type, technology architecture, application severity, and end-user procurement channel throughout the forecast period. CAGRs were derived from regression analysis of equipment production growth correlated with hydraulic content per machine trends. Industry-specific forecast inputs included GPS-guided implement adoption rates in precision agriculture and Stage V compliance timelines for European construction equipment.
The model holds under sustained infrastructure investment in India and Brazil and stable foundry capacity utilization in Germany and Japan; deviation in nickel alloy price volatility or METI subsidy acceleration would shift volume projections. Forecasts reflect base-case assumptions regarding electrohydraulic displacement rates and functional safety certification adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Pipeline Pigging Equipment Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Pulsation Dampeners Market
Valves
China Explosion-Proof Equipment Market
Valves
Explosion Vents Market
Valves
Air Vent Heads Market
Valves
Manual Control Valve Market
Valves
Safety Valve Market
Valves
United States Valves Market
Valves
Servo Valves Market
Valves
Pipeline Integrity Management (PIM) Market
Valves
Hydraulic Diaphragm Valve Market
Valves
HVAC Valves Market
Valves
Steam Trap Valve Market