
 Float Traps Market | 2026-2036
Float Traps Market Size, Share, and Industry Trends Forecast 2026-2036
Float Traps Market Analytics
The EU Green Deal is repositioning float trap specifications across European process industries toward higher thermal efficiency thresholds. Spirax-Sarco Engineering leverages its steam specialties heritage to anchor premium positioning in retrofit-intensive markets. Armstrong International competes through extensive distributor networks covering North American industrial corridors. TLV Corporation dominates precision manufacturing for high-pressure float mechanisms serving Asian boiler OEMs.
Float traps are mechanical steam conditioning devices that utilize a buoyant sealed float to modulate condensate discharge while blocking live steam loss, typically rated for pressures from 0 to 250 bar and temperatures exceeding 300°C depending on seal and body material selection. Their primary industrial purpose centers on protecting downstream equipment, recovering thermal energy, and maintaining process steam quality across continuous and batch operations. Stainless steel body configurations lead material selection due to corrosion resistance in aggressive condensate chemistries, while tank-mounted installations capture margin pools in compact skid-based systems where space constraints override pipeline integration preferences. The automatic product category sustains volume leadership as plants prioritize reduced operator intervention, though manual variants retain niche positions in isolated or hazardous access locations.
The US EPA enforces steam efficiency benchmarks through industrial boiler MACT standards that directly specify condensate recovery equipment performance, while India's BIS mandates pressure equipment certification that shapes import eligibility for foreign float trap manufacturers. Japan's METI maintains JIS standards for steam trap thermal efficiency testing that influence product development cycles across Asian supply chains. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading requirements for documented steam system energy recovery rates.
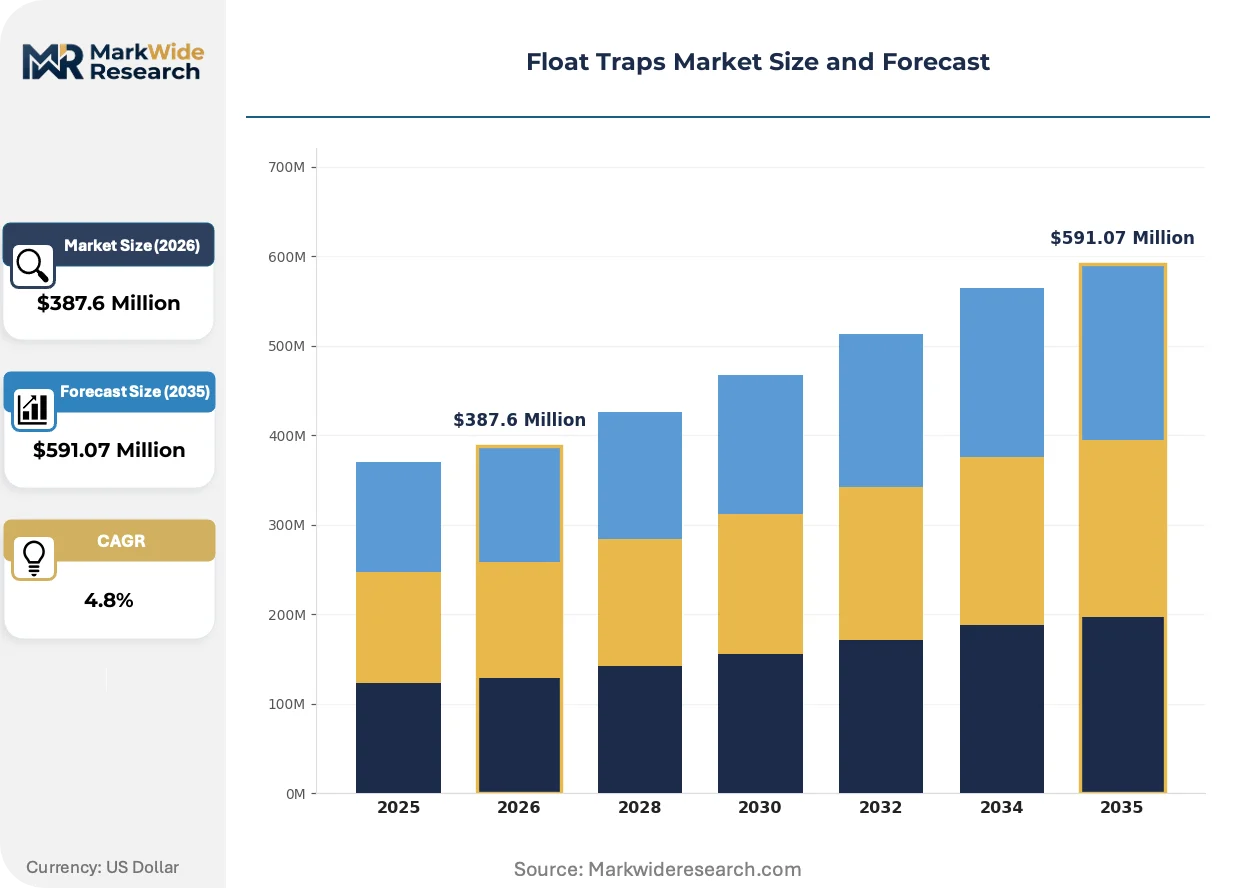
Market Dynamics
Asia-Pacific power generation buildouts and EU industrial decarbonization mandates are compressing procurement cycles for high-efficiency steam conditioning equipment, forcing manufacturers to recalibrate thermal performance specifications and regional certification pipelines simultaneously.
Growth Catalysts
- EU Green Deal efficiency mandates:The EU Green Deal tightens industrial energy recovery thresholds, compelling process plants to replace legacy mechanical traps with higher-performance float mechanisms.
- India's refinery corridor expansion:Petrochemical processing clusters along India's western coast are scaling steam system investments, creating concentrated demand for corrosion-resistant stainless steel body configurations.
- Condensate recovery technology:Advances in seal metallurgy extend float trap service intervals above 300°C operating temperatures, reducing maintenance downtime in continuous boiler operations.
Market Restraints
- Stainless steel input volatility:Austenitic steel alloy price swings compress margin stability for body casting operations, particularly affecting mid-tier manufacturers without captive foundry capacity.
- Supply concentration in precision machining:High-pressure float mechanism production clusters in East Asian manufacturing basins, exposing procurement timelines to regional logistics disruptions.
- Thermodynamic substitution:Thermostatic and thermodynamic trap alternatives capture share in low-pressure HVAC applications where float mechanism precision offers limited operational advantage.
Strategic Opportunities
- Carbon border adjustment documentation:EU CBAM implementation creates premium positioning for manufacturers supplying verified steam system energy recovery rate data to process industry exporters.
- Skid-based system integration:Compact tank-mounted float trap configurations penetrate modular process equipment builds where space constraints override traditional pipeline mounting preferences.
- Japan METI efficiency standards:JIS thermal efficiency testing protocols are propagating across Asian supply chains, enabling certification harmonization for manufacturers targeting multiple national markets.
Industry Challenges
- Multi-jurisdiction certification pipelines:Simultaneous compliance with US EPA boiler MACT specifications, India's BIS pressure equipment mandates, and Japan's JIS testing protocols extends product launch timelines.
- Legacy system integration friction:Retrofit installations in established process plants require custom flange adaptations and condensate line reconfiguration, complicating standardized product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Float Traps Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Float Type, Level Control, Automatic, Manual End User: Industrial Sector, Power Generation, Petrochemical, Commercial Buildings Installation Type: In-Line, Vertical, Horizontal, Tank Mounted Material: Stainless Steel, Plastic, Bronze, Carbon Steel |
| Companies Covered | Spirax-Sarco Engineering, Armstrong International, TLV Corporation, Emerson Electric, Watts Water Technologies, Velan Inc., Forbes Marshall, Thermax Limited, Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Float Traps Market Evolving Landscape
Steam system digitization and predictive maintenance integration are redefining how float trap performance is monitored, shifting value capture from hardware sales toward thermal efficiency assurance services.
Smart float trap sensors with embedded pressure-temperature telemetry are overtaking purely mechanical installations in critical process applications. Refinery operators in the US Gulf Coast and Rotterdam-Antwerp corridor are adopting these configurations fastest. The technology is overtaking traditional inspection-based maintenance schedules by enabling real-time condensate discharge monitoring and automated steam loss alerts.
The EU F-Gas Regulation and associated industrial emissions frameworks are tightening documentation requirements for steam system energy performance. Process plants must now maintain auditable records of condensate recovery equipment efficiency across reporting periods. Food and pharmaceutical processing facilities in Germany and France face the steepest compliance ramps, driving preference for traps with certified thermal efficiency ratings.
Buyer procurement patterns are consolidating toward integrated steam system suppliers capable of delivering trap specification, installation, and efficiency verification as unified contracts. This unbundles traditional component distribution channels in favor of direct OEM-to-plant relationships. The shift is most pronounced in India's chemical processing corridors, where project engineers prioritize single-source accountability over multi-vendor assembly.
Float Traps Market Segmentation
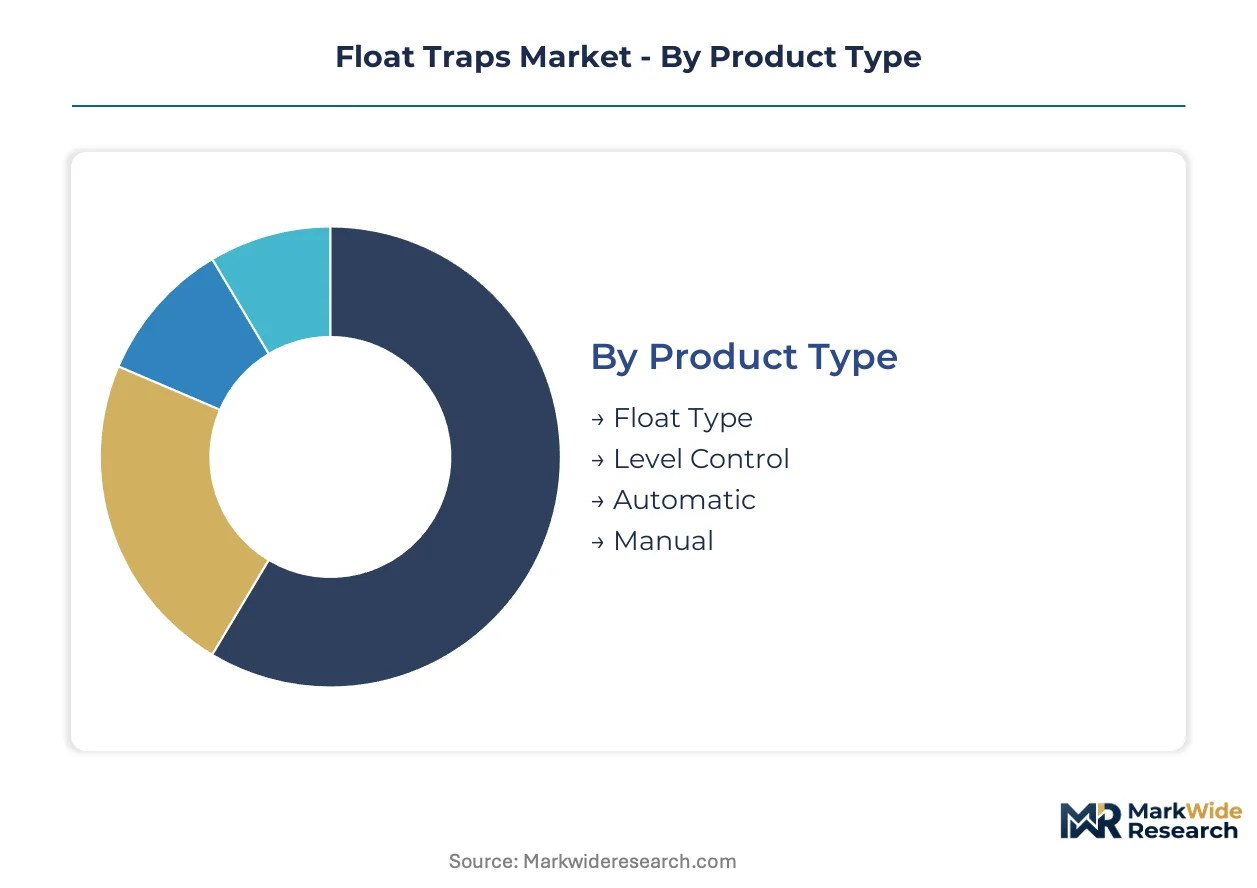
Float trap segmentation reflects divergent engineering requirements across pressure ratings, thermal envelopes, and maintenance accessibility. Specification choices cascade through procurement decisions in power generation and petrochemical corridors where failure modes carry significant operational cost.
Product Type:
Technology sophistication determines operator intervention levels and condensate discharge precision across continuous and batch operations.
- Automatic:Self-actuating float mechanisms modulate discharge without manual adjustment, reducing labor exposure in hazardous access locations. Demand concentrates in India's refinery corridors where continuous boiler operations prioritize reduced maintenance intervals.
- Float Type:Buoyant sealed floats provide direct mechanical actuation with pressure ratings spanning 0 to 250 bar. Power generation facilities in Asia-Pacific specify these configurations for thermal efficiency assurance in high-pressure steam headers.
- Level Control:Integrated sensing enables precise condensate pool management in tank-mounted installations.
- Manual:Operator-dependent discharge suits isolated maintenance access points with infrequent condensate loads.
Mature deployment sits with Float Type mechanisms in legacy industrial infrastructure. Newer deployment is concentrated in Automatic configurations driven by labor reduction mandates.
End User:
Application intensity shapes corrosion resistance requirements and thermal cycling specifications across sector-specific procurement.
- Power Generation:High-pressure boiler feed systems demand float traps rated above 300°C with extended service intervals. Asia-Pacific capacity buildouts specify stainless steel body configurations for aggressive condensate chemistry.
- Petrochemical:Process steam networks require corrosion-resistant seals and rapid maintenance turnaround. India's western coast processing clusters drive concentrated procurement of tank-mounted configurations for compact skid integration.
- Industrial Sector:General manufacturing applications span diverse pressure and temperature envelopes.
- Commercial Buildings:Low-pressure HVAC systems tolerate thermodynamic alternatives where float precision offers limited advantage.
Procurement volume concentrates in Power Generation. Margin expansion is climbing the fastest in Petrochemical applications requiring specialized metallurgy.
Installation Type:
Spatial constraints and pipeline geometry dictate mounting orientation preferences across greenfield and retrofit project types.
- Tank Mounted:Compact configurations capture margin pools in skid-based systems where space constraints override traditional pipeline integration. Modular process equipment builds in India's chemical corridors specify these for single-source accountability.
- In-Line:Direct pipeline integration suits standard horizontal or vertical steam headers with accessible maintenance clearance.
- Vertical:Orientation-specific mounting addresses condensate collection points in vertical risers.
- Horizontal:Standard pipeline alignment accommodates the majority of process steam distribution networks.
Retrofit friction is highest with In-Line replacements requiring flange adaptation. Greenfield specification is expanding most quickly in Tank Mounted configurations for modular system integration.
Material:
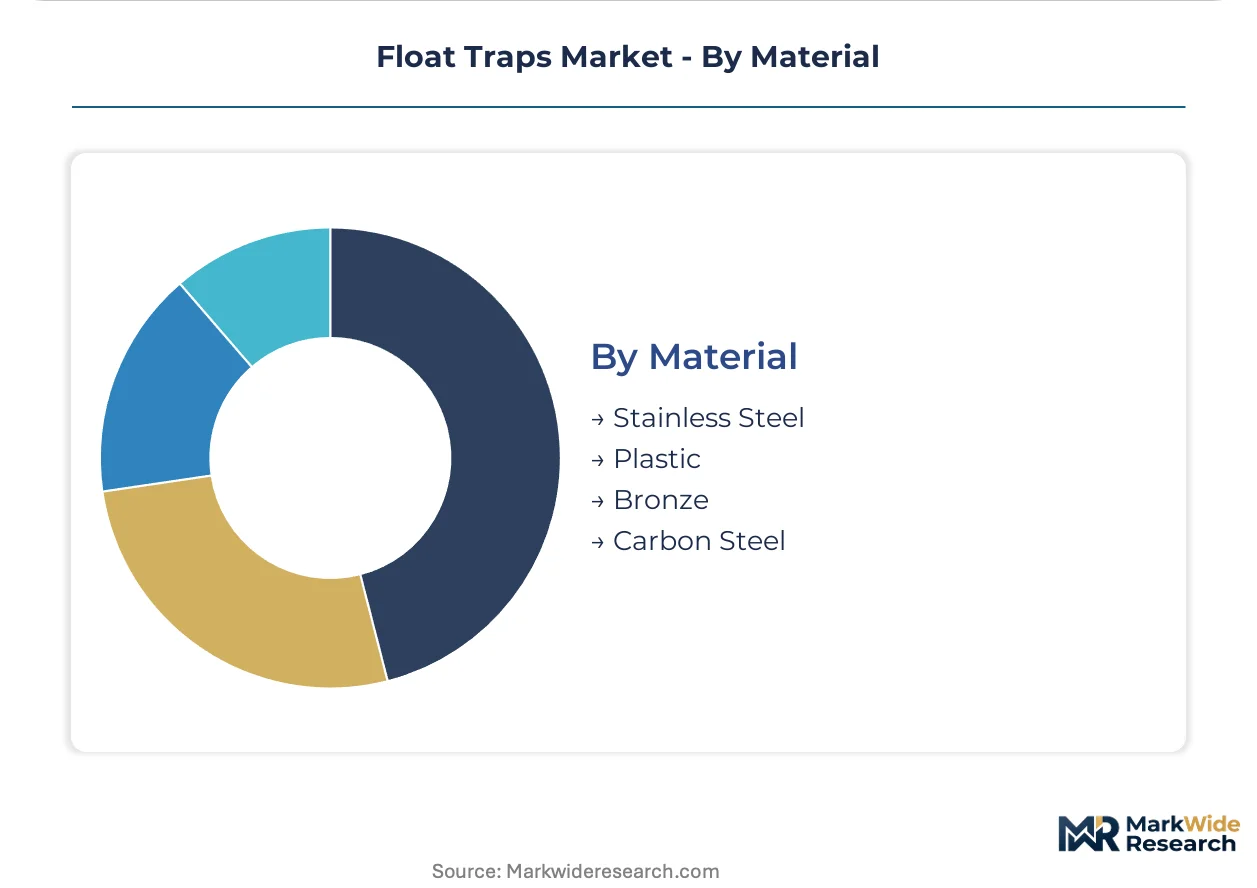
Corrosion resistance and thermal conductivity properties determine body and seal selection for specific condensate chemistries.
- Stainless Steel:Austenitic alloys dominate aggressive condensate environments with superior corrosion resistance. EU Green Deal efficiency mandates accelerate replacement cycles toward premium material specifications.
- Carbon Steel:Cost-sensitive applications in lower-corrosion environments tolerate reduced material investment.
- Bronze:Marine and specific chemical resistance applications leverage copper alloy properties.
- Plastic:Low-pressure, low-temperature installations accept polymer construction for cost minimization.
Specification gravity centers on Stainless Steel for process industry reliability. Procurement experimentation is gaining share fastest in specialized Bronze applications for niche chemical resistance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jamnagar-Dahej industrial corridor anchors float trap procurement intensity. India's western coast refineries drive stainless steel body specifications. EU decarbonization mandates compress European replacement cycles.
United States
Gulf Coast petrochemical clusters and power generation retrofits sustain demand for high-pressure float mechanisms. EPA boiler MACT standards enforce condensate recovery equipment performance thresholds. Houston-Baytown processing facilities specify smart sensor configurations for real-time steam loss monitoring.
Germany
Food and pharmaceutical processing facilities face steep EU F-Gas Regulation compliance ramps. JIS thermal efficiency testing protocols from Japan METI propagate through German OEM supply chains. Rhine-Ruhr industrial belt plants prioritize certified thermal efficiency ratings for audit documentation.
India
Refinery corridor expansion along the western coast scales steam system investments. BIS pressure equipment certification shapes import eligibility for foreign manufacturers. Gujarat's Dahej petrochemical zone concentrates tank-mounted configuration demand for modular skid integration.
Japan
Boiler OEM partnerships drive precision manufacturing requirements for high-pressure float mechanisms. METI maintains JIS standards for steam trap thermal efficiency testing that cascade through Asian supply chains. Kansai region process industries adopt predictive maintenance integration fastest.
China
Power generation capacity buildouts specify corrosion-resistant stainless steel configurations for aggressive condensate chemistry. Dual carbon goals tighten industrial energy efficiency thresholds. Yangtze River Delta manufacturing basins cluster precision machining capacity for float mechanism production.
Float Traps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal efficiency certification and metallurgy specialization. The vendor base stratifies between integrated steam system suppliers and component specialists. Three archetypes dominate: heritage steam engineering houses, diversified industrial conglomerates, and regional precision fabricators. Consolidation pressure favors integrated suppliers capable of delivering specification, installation, and efficiency verification as unified contracts.
Within the heritage engineering tier, Spirax-Sarco Engineering and Armstrong International exemplify premium positioning through steam specialties lineage. TLV Corporation occupies a precision manufacturing position serving Asian boiler OEMs with high-pressure mechanism expertise. These three anchors represent divergent geographic and technical positioning strategies without overlapping core market footprints.
| Leading Market Players |
|---|
| Spirax-Sarco Engineering |
| Armstrong International |
| TLV Corporation |
| Emerson Electric |
| Watts Water Technologies |
| Velan Inc. |
| Forbes Marshall |
| Thermax Limited |
| Xylem Inc. |
| Others |
Value Network & Pricing Analysis
Heritage steam engineering houses with multi-generational family ownership anchor pricing discipline through captive foundry capacity and direct OEM relationships. Their control over precision machining assets in East Asian manufacturing basins lets them buffer stainless steel alloy volatility while mid-tier competitors absorb margin compression.
Pricing Analysis
Value-based pricing anchored to thermal efficiency outcomes and documented energy recovery rates commands premium positioning in EU compliance-driven procurement. Three-tier pricing structure across premium certified, standard industrial, and economy unbranded levels stratifies the vendor base. Cost compression in economy tiers intensifies as Indian refinery projects consolidate procurement toward integrated steam system suppliers. Power generation buyers exhibit lowest price sensitivity due to failure-mode cost exposure, while commercial building HVAC contractors drive aggressive economy-tier negotiation.
Supply Chain Analysis
Single-source vulnerability sits with precision float mechanism machining concentrated in China's Yangtze River Delta and Japan's Kansai industrial belt. Raw material flows draw from South Korean stainless steel slab producers, German specialty seal metallurgy suppliers, and Indian domestic austenitic alloy processors. Tariff exposure on precision-machined components threatens procurement timelines for European and North American trap assemblers. Distribution runs through direct OEM-to-plant contracting that is displacing traditional multi-tier distribution channels in India's chemical processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Float trap manufacturing is consolidating toward integrated steam system suppliers as EU carbon border adjustment documentation requirements force out component-only vendors lacking efficiency verification capabilities.
For Market Incumbents: Lock in captive foundry capacity for stainless steel body casting to insulate margin stability from alloy price volatility. Secure JIS thermal efficiency certification harmonization across Asian supply chains before competitors complete multi-jurisdiction compliance pipelines. Thermodynamic trap substitution in low-pressure HVAC applications threatens legacy float mechanism volume; counter through smart sensor integration for predictive maintenance contracts. For New Entrants and Emerging Players: Capture tank-mounted configuration demand in India's modular skid-based system builds where space constraints override traditional pipeline mounting. Target corrosion-resistant bronze seal applications for niche chemical resistance requirements underserved by stainless steel incumbents. Lead with single-source accountability contracts that bundle trap specification, installation, and efficiency verification. For Investors and Strategic Acquirers: EU CBAM implementation timeline acceleration is the leading indicator that verified steam system energy recovery documentation capabilities will separate viable acquisition targets from stranded component vendors. Five-to-ten-year viability favors precision fabricators with backward integration into seal metallurgy and captive high-pressure machining capacity. Watch for Japanese METI efficiency standard adoption rates across Southeast Asian boiler OEM supply chains as the signal for certification-harmonization investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seal Metallurgy | Captive specialty alloy production insulates margin stability from South Korean stainless steel slab price volatility. |
| Smart Sensor Configuration Launch | Embedded pressure-temperature telemetry captures predictive maintenance contracts from US Gulf Coast refinery operators. |
| JIS Certification Harmonization | Unified thermal efficiency testing protocols unlock procurement access across Japan, India, and Southeast Asian boiler OEMs. |
| Modular Skid System Partnership | Tank-mounted float trap integration secures sole-source positioning in India's Dahej petrochemical zone project builds. |
| EU CBAM Documentation Service | Verified energy recovery rate data packages command premium positioning with German and French process industry exporters. |
Research Methodology
Trade flow databases, national pressure equipment certification registries, and boiler MACT compliance filings formed the secondary backbone for demand quantification. Primary interviews with maintenance directors at US Gulf Coast petrochemical facilities, procurement leads at Indian refinery operators, steam system OEM technical directors, and aftermarket service heads validated specification trends and replacement cycle timing. Bottom-up installation data triangulated against top-down industrial steam system investment forecasts.
Historical trendline analysis of stainless steel body shipment volumes and thermal efficiency certification issuance rates established baseline growth parameters across the projection horizon. Segmentation modeling captured product type, end-use intensity, installation geometry, and material grade tier dimensions. CAGR derivation incorporated EU Green Deal mandate implementation pacing, India's BIS certification pipeline expansion, and Japan METI efficiency standard propagation through Asian supply chains.
The model holds under stable industrial energy efficiency regulatory enforcement; deviation in carbon border adjustment mechanism scope expansion or precision machining logistics disruptions would shift trajectory. Forecasts reflect documented assumptions on replacement cycle compression and certification harmonization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
HVAC Valves Market
Valves
Tubing Heads Market
Valves
Steam Trap Market
Valves
Steel Cylinder Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Compressor Valves Market
Valves
Supply Stop Valves Market
Valves
North America Irrigation Valves Market
Valves
Insulation Flanges Market
Valves
Stainless Steel Valve Tag Market
Valves
North America Butterfly Valve Market
Valves
Fin Tube Market
Valves
Global Valves Market
Valves
Total Containment Vessels Market
Valves
Hydraulic Diaphragm Valve Market
Valves
Emergency Shut Down Valves (ESDV) Market