
 Off-Road Vehicle Market | 2026-2036
Off-Road Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Off-Road Vehicle Market Intelligence
EPA Phase 3 emission standards for nonroad spark-ignition engines is pivoting the cost-of-entry calculus for gasoline-powered off-road manufacturers. Polaris Inc. leverages its vertically integrated Minnesota production campus to sustain domestic compliance without sourcing disruption. Deere & Company anchors the agricultural utility segment through its entrenched dealer network across North American farming regions.
Off-road vehicles are motorized machines designed for unpaved terrain, typically featuring reinforced suspensions with travel exceeding 25 centimeters, knobby tires, and sealed drivetrain components against mud and debris ingress; they serve commercial, military, and recreational users requiring mobility beyond paved infrastructure. The utility-task vehicle category dominates professional and agricultural end-use, while electric fuel types represent the fastest-expanding segment as lithium-ion powertrains penetrate closed-course and low-range commercial applications. Dirt bikes retain concentrated margin pools in professional racing, where specialized suspension tuning and lightweight frame alloys command sustained premium positioning.
The EPA, NHTSA, and California Air Resources Board collectively shape product standards through tailpipe limits, rollover protection mandates, and state-level zero-emission vehicle pathways that filter into manufacturer platform planning. The EU F-Gas Regulation and REACH chemical restrictions further complicate material selection for seals, coolants, and coatings in globally distributed supply chains. Stakeholders must monitor how battery-electric range specifications evolve against the torque and runtime benchmarks that agricultural and construction buyers currently enforce.
Market Dynamics
EPA Phase 3 emission standards for nonroad spark-ignition engines is compressing the gasoline-powered product lifecycle while accelerating electric powertrain development across the United States, Brazil, and European Union manufacturing bases.
Growth Catalysts
- Utility-Task Vehicle Fleet Expansion:Agricultural operators in Brazil are scaling UTV purchases for precision crop management and livestock monitoring across expansive ranching properties.
- REACH Chemical Compliance:The EU's chemical restrictions are forcing material innovation in seals and coolants, opening supplier diversification opportunities for compliant compound manufacturers.
- Lithium-Ion Powertrain Penetration:Electric drivetrains are capturing closed-course recreational and low-range commercial applications where runtime requirements align with battery specifications.
Market Restraints
- EPA Certification Cost Burden:Gasoline engine manufacturers face escalating compliance expenditure as tailpipe limits tighten for nonroad spark-ignition categories.
- Semiconductor Supply Concentration:Electronic control module sourcing remains concentrated in East Asian foundries, exposing production schedules to geopolitical disruption.
- Steel and Aluminum Input Volatility:Frame and suspension component costs fluctuate with commodity pricing, compressing margin predictability for mid-tier assemblers.
Strategic Opportunities
- Midwest United States Ranching-Recreation Overlap:Demand concentration across Texas, Oklahoma, and Kansas creates bundled fleet opportunities serving both agricultural work and trail access.
- California ZEV Pathway Alignment:The state's zero-emission vehicle mandates provide regulatory runway for electric UTV and side-by-side platform launches ahead of federal requirements.
- Telematics-Enabled Fleet Management:GPS tracking and usage analytics are converging with electric powertrains to offer subscription-based operational intelligence for commercial buyers.
Industry Challenges
- Power Electronics Engineering Scarcity:Battery management system and motor control expertise remains concentrated among automotive suppliers, creating recruitment competition for off-road specialists.
- Dual-Certification Timeline Compression:Manufacturers must synchronize EPA tailpipe approval with NHTSA rollover protection validation, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Off-Road Vehicle Market |
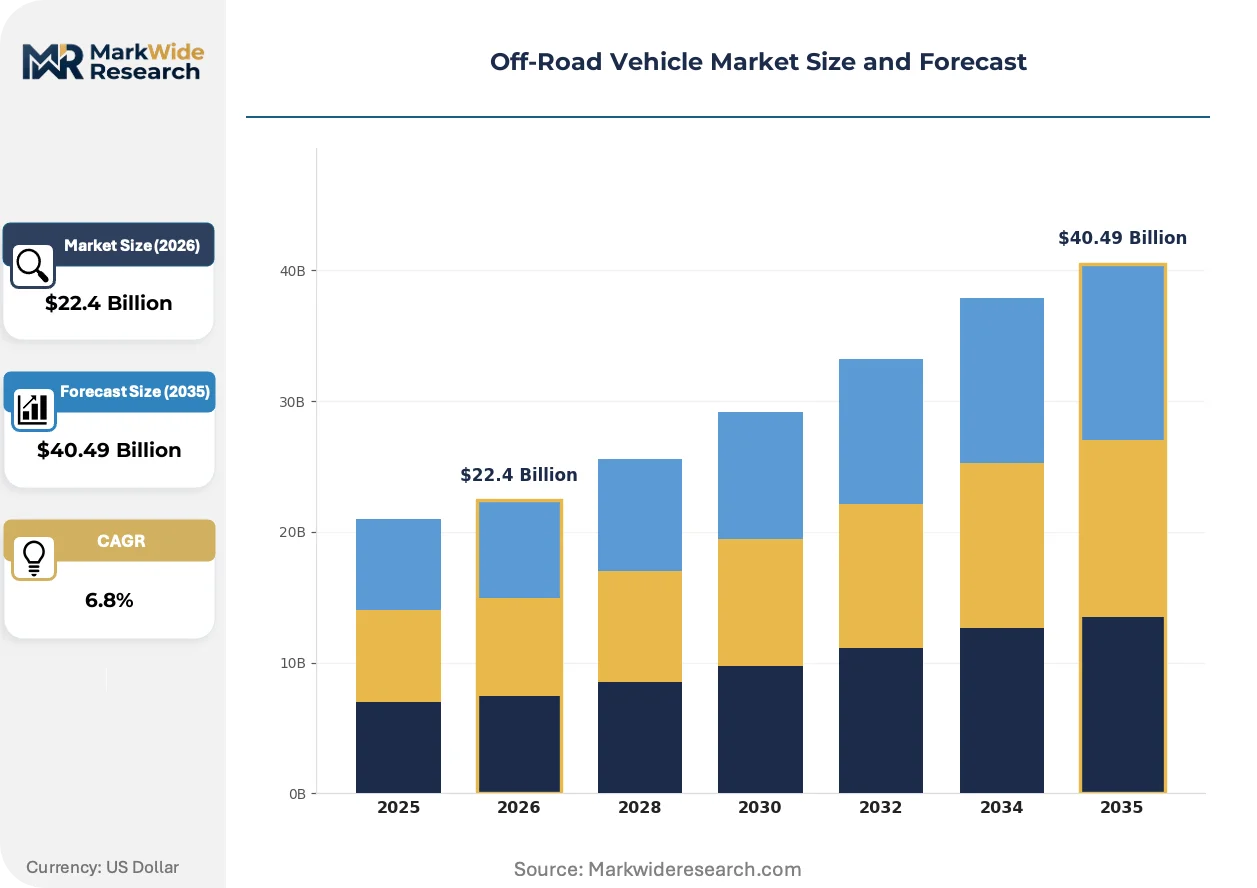
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: ATVs, UTVs, Dirt Bikes, Trucks Fuel Type: Gasoline, Diesel, Electric, Hybrid End User: Recreational Users, Military, Agricultural, Construction Market Segment: Professional Racing, Leisure Riding, Utility Applications, Commercial Use |
| Companies Covered | Yamaha Motor Co. Ltd, Kawasaki Heavy Industries Ltd., Polaris Inc., Deere & Company, CFMOTO Powersports Inc., Bombardier Recreational Products Inc., Arctic Cat Inc., Suzuki Motor Corp., Honda Motor Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Off-Road Vehicle Market Strategic Shifts & Innovations
Powertrain electrification is rewriting competitive boundaries between recreational and commercial segments while regulatory fragmentation across the United States, European Union, and Brazil forces platform architecture decisions.
Solid-state battery prototyping is rewriting range and thermal management assumptions for electric off-road vehicles. Agricultural fleet buyers in California and the European Union are piloting pre-production units for vineyard and greenhouse applications where charging infrastructure exists. This chemistry transition is compressing the performance gap between electric and gasoline torque curves in low-speed, high-load operating conditions.
The EU F-Gas Regulation is eliminating hydrofluorocarbon refrigerants from HVAC-equipped UTV cabins, forcing compressor redesigns and alternative coolant adoption. Manufacturers serving European agricultural and municipal buyers must revalidate thermal systems under new global warming potential thresholds. Product planners in Germany and France are prioritizing CO2-based climate systems for 2027 model year compliance.
Subscription-based ownership models are displacing traditional retail financing for recreational trail riders in the United States Southwest. Younger buyers in Arizona and Utah are accessing side-by-sides through monthly plans bundling insurance, maintenance, and trail network access. This consumption-pattern shift is pressuring dealer networks to restructure compensation around recurring revenue rather than unit throughput.
Off-Road Vehicle Market Segmentation
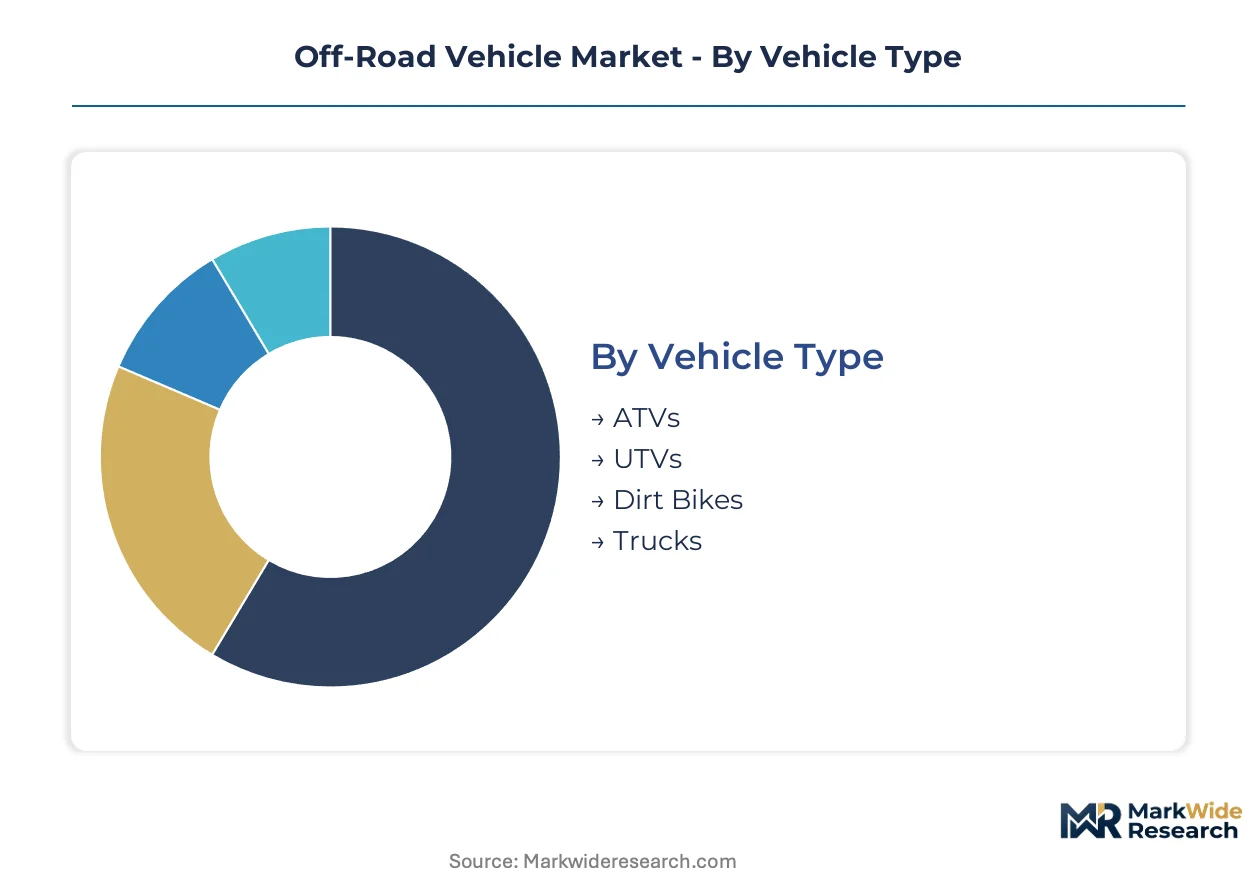
Off-road vehicle segmentation reveals divergent engineering priorities across recreational and commercial applications. Vehicle architecture, powertrain selection, and durability specifications vary sharply between weekend trail riders and agricultural fleet operators.
Vehicle Type:
Volume production concentrates in utility platforms, while premium engineering resources flow toward specialized racing derivatives.
- ATVs:Single-rider quad bikes with straddle seating and handlebar steering dominate entry-level recreational sales. Demand clusters in the United States Southwest where desert trail systems and ranching properties overlap, though EPA Phase 3 certification costs are compressing gasoline model profitability.
- UTVs:Side-by-side configurations with bench seating and cargo beds anchor agricultural and commercial fleets. Brazilian crop operators are scaling fleet purchases for precision agriculture applications across expansive soybean and cattle operations.
- Dirt Bikes:Lightweight motorcycles with long-travel suspension serve closed-course racing and backcountry trail access. Professional racing circuits command sustained premium pricing for specialized frame alloys and tunable suspension.
- Trucks:Heavy-duty off-highway vehicles with reinforced frames and multi-axle configurations serve mining and construction logistics. Underground mining operations in Canada and Australia specify explosion-proof electrical systems and rollover protection cages.
Mature deployment sits with ATVs. Newer deployment is concentrated in UTVs.
Fuel Type:
Application range dictates powertrain selection, with runtime requirements and charging infrastructure availability determining electric viability.
- Gasoline:Spark-ignition engines with carburetor or fuel injection systems deliver power-to-weight ratios suited to high-performance recreational use. EPA Phase 3 tailpipe limits are extending certification timelines and forcing exhaust after-treatment integration.
- Diesel:Compression-ignition powertrains with high torque at low RPM serve agricultural towing and construction haulage. European Union Stage V emission standards are requiring selective catalytic reduction and diesel particulate filters for nonroad mobile machinery.
- Electric:Lithium-ion battery packs with permanent magnet motors are penetrating closed-course racing and greenhouse agriculture where charging infrastructure exists. Vineyard operators in California are piloting solid-state battery prototypes for silent, zero-emission crop management.
- Hybrid:Combined internal combustion and electric drivetrains optimize fuel consumption in variable-load commercial applications. Municipal maintenance fleets in Germany are evaluating mild-hybrid architectures for stop-start urban utility work.
Gasoline retains the largest installed base. Electric platforms are climbing the fastest as battery energy density improves and regulatory pressure intensifies.
End User:
Procurement patterns diverge between individual discretionary purchase and fleet-based capital allocation with telematics integration requirements.
- Recreational Users:Individual buyers seeking trail access, hunting transport, and desert dune riding. Subscription ownership models are displacing traditional retail financing in Arizona and Utah, bundling insurance and maintenance into monthly payments.
- Military:Defense procurement specifications require electromagnetic hardening, air-transportability, and multi-fuel compatibility. Special operations forces prioritize silent-running electric platforms for reconnaissance insertion.
- Agricultural:Crop and livestock operators requiring spray application, fencing maintenance, and herd monitoring across large properties. Brazilian ranching cooperatives are standardizing UTV fleets for GPS-guided precision agriculture.
- Construction:Site logistics and materials transport in unpaved conditions with rollover protection mandates. NHTSA certification requirements for occupant protection are extending product development cycles for this segment.
Agricultural deployment shows the deepest fleet integration. Recreational purchase patterns are shifting fastest toward subscription and shared-access models.
Market Segment:
Margin structure inverts between volume-driven utility applications and low-volume, high-specification racing derivatives.
- Professional Racing:Homologated competition vehicles with FIM or AMA certification for sanctioned events. Suspension tuners and chassis specialists command sustained premium pricing for championship-proven component packages.
- Leisure Riding:Weekend trail access and family recreation with moderate durability requirements. Trail network expansion across Texas, Oklahoma, and Kansas is creating bundled fleet opportunities serving both work and recreation.
- Utility Applications:Work-focused platforms with cargo capacity, towing ratings, and attachment compatibility. REACH chemical compliance is forcing material innovation in seals and coolants for European agricultural buyers.
- Commercial Use:Fleet-deployed vehicles with telematics integration and usage-based maintenance scheduling. GPS tracking and operational analytics are converging with electric powertrains to offer subscription-based intelligence packages.
Utility Applications anchor production volume. Professional Racing captures the steepest margin premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minnesota's off-road manufacturing corridor anchors North American production concentration, with tax-advantaged zones drawing assemblers seeking EPA compliance proximity. Brazilian agricultural cooperatives are scaling fleet procurement for precision crop management. European Union F-Gas Regulation is forcing thermal system redesigns for vineyard and greenhouse operators.
United States
Midwest ranching operations across Texas, Oklahoma, and Kansas are converging with recreational trail demand, creating bundled fleet procurement opportunities. EPA Phase 3 tailpipe standards are compressing gasoline model certification timelines and forcing exhaust after-treatment integration. Minnesota's vertically integrated production campus sustains domestic compliance without cross-border sourcing exposure.
Brazil
Soybean and cattle ranching cooperatives are standardizing UTV fleets for GPS-guided precision agriculture across expansive properties. ANVISA chemical registration requirements intersect with agricultural equipment specifications for spray application systems. São Paulo state anchors distributor networks serving the Central-West crop belt expansion.
Germany
Municipal maintenance fleets are evaluating mild-hybrid architectures for stop-start urban utility work under EU Stage V nonroad mobile machinery standards. KBA type-approval processes govern rollover protection validation for construction site deployment. Baden-Württemberg engineering clusters supply power electronics for electric powertrain conversion programs.
China
Domestic lithium-ion cell capacity is penetrating closed-course recreational and low-range commercial applications where charging infrastructure exists. MIIT new energy vehicle mandates are filtering into off-road platform planning through battery management system specifications. Chongqing manufacturing bases serve ASEAN export markets with cost-optimized utility configurations.
Australia
Underground mining operations in Western Australia specify explosion-proof electrical systems and rollover protection cages for subterranean logistics. State-level workplace safety regulations mandate operator protection beyond federal minimums. Perth engineering consultancies validate autonomous haulage integration for remote site deployment.
Off-Road Vehicle Market Key Industry Players
North American producers anchor one tier; Asian specialists hold manufacturing scale advantages in powertrain components. The vendor base stratifies across diversified powersports conglomerates, agricultural equipment incumbents, and emerging electric-focused entrants. Three archetypes dominate: vertically integrated recreational vehicle assemblers, dealer-network-anchored agricultural equipment suppliers, and battery-electric platform specialists. Competitive moves concentrate on EPA compliance synchronization and solid-state battery prototyping partnerships.
Within the diversified powersports tier, Yamaha Motor Co. Ltd and Kawasaki Heavy Industries Ltd represent Japanese engineering heritage with established distribution density. Polaris Inc. anchors North American production integration, while Deere & Company exemplifies agricultural equipment incumbency through entrenched dealer relationships. CFMOTO Powersports Inc. occupies a position as a Chinese scale entrant accessing cost-optimized manufacturing bases.
| Leading Market Players |
|---|
| Yamaha Motor Co. Ltd |
| Kawasaki Heavy Industries Ltd. |
| Polaris Inc. |
| Deere & Company |
| CFMOTO Powersports Inc. |
| Bombardier Recreational Products Inc. |
| Arctic Cat Inc. |
| Suzuki Motor Corp. |
| Honda Motor Co. Ltd |
| Others |
Cost & Logistics Intelligence
Steel and aluminum price indices cascade through frame and suspension component costs, compressing margin predictability for mid-tier assemblers while reinforcing pricing power among vertically integrated producers with captive metalworking capacity.
Pricing Analysis
Lead-time premiums compress as EPA Phase 3 certification timelines extend, forcing gasoline-powered manufacturers to discount spot inventory while electric powertrain specialists command premiums for short-lead battery pack availability. Three-tier pricing structure across premium racing-grade, standard utility, and economy recreational levels separates FIM-certified competition machines from fleet-deployed agricultural workhorses. Cost compression in gasoline models is intensifying because exhaust after-treatment integration extends engineering cycles. Agricultural fleet buyers exhibit lowest price sensitivity due to telematics-enabled total cost of ownership calculations, while recreational subscription customers demonstrate highest elasticity to monthly payment adjustments.
Supply Chain Analysis
EPA tailpipe certification and NHTSA rollover protection validation gate component sourcing, with only qualified suppliers able to support dual-certification timelines. Electronic control module production concentrates in Taiwan, South Korea, and Japan, while lithium-ion cell supply anchors in China. Frame-grade steel, forged aluminum suspension components, and semiconductor-based power electronics constitute critical input dependencies. Single-source vulnerability in battery management system chipsets exposes production schedules to geopolitical disruption. Distribution runs through manufacturer-owned dealer networks for agricultural and commercial segments, with direct-to-consumer channels penetrating recreational subscription markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The off-road vehicle market functions as a vertical-integration race where control over battery cell supply and power electronics engineering determines platform economics and compliance timing.
For Market Incumbents: Anchor compliance advantage through backward integration into EPA-certified engine production and captive battery pack assembly in Minnesota manufacturing corridors. Defend against electric-focused entrants by locking exclusive solid-state battery prototyping partnerships before chemistry transitions mature. Prioritize certification investment in dual EPA-NHTSA approval pathways to compress launch cycles relative to competitors dependent on external engineering houses. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting Arizona and Utah recreational riders displaced from traditional dealer financing. White-space concentration sits with telematics-enabled electric UTV fleets for California vineyard operators ahead of state ZEV mandate expansion. Penetrate Brazilian agricultural cooperatives through GPS-guided precision agriculture bundling with established spray equipment distributors. For Investors and Strategic Acquirers: Distressed-cycle entries favor power electronics engineering specialists in Baden-Württemberg clusters where automotive supplier expertise is transferable to off-road motor control applications. Long-term viability hinges on platform architectures capable of spanning both EPA Phase 3 gasoline compliance and zero-emission regulatory trajectories without complete redesign. Watch solid-state battery pilot program conversion rates from California greenhouse operators as inflection signal for chemistry transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium-ion production insulates against East Asian foundry concentration and semiconductor sourcing disruption. |
| Dual-Certification Platform Architecture | Simultaneous EPA tailpipe and NHTSA rollover validation compresses product launch cycles versus sequential approval pathways. |
| Telematics-Enabled Fleet Management Launch | GPS tracking convergence with electric powertrains creates recurring revenue streams from California agricultural buyers. |
| Solid-State Battery Prototyping Partnership | Early chemistry access rewrites range assumptions for vineyard operators under EU F-Gas thermal system mandates. |
| Subscription Ownership Model Expansion | Monthly payment bundling displaces traditional dealer compensation structures across Southwest United States trail networks. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across OEM platform engineers, agricultural fleet procurement managers, aftermarket service heads, and power electronics R&D directors. EPA certification databases, NHTSA rollover test reports, ANVISA chemical registrations, and EU F-Gas compliance disclosures supplied regulatory validation. Bottom-up production estimates triangulated against top-down demand aggregation across recreational, agricultural, and commercial end-use segments.
Vehicle type, fuel architecture, and end-user procurement patterns were modeled at country-level granularity across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by regional regulatory phase-in schedules and commodity input cost assumptions. Solid-state battery pilot deployment rates, EPA certification timeline extensions, and Brazilian agricultural credit availability served as industry-specific forecast inputs.
Regulatory delay, commodity price volatility, and battery chemistry transition failure are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding emission standard enforcement timing and charging infrastructure buildout pacing. A model refresh is warranted upon material change in EPA Phase 3 implementation schedules or solid-state battery commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Off Road Vehicles
All-Terrain Vehicle Market
Off Road Vehicles
Amphibious ATV Market
Off Road Vehicles
Small Off-Road Engines Market
Off Road Vehicles
Europe Off-Highway Vehicle HVAC Market
Off Road Vehicles
Global Automotive Off Highway Engine Market
Off Road Vehicles
Snowmobile Market
Off Road Vehicles
Off-Road Equipment Market
Off Road Vehicles
Off-Highway Electric Vehicle Market
Off Road Vehicles
Off Highway Vehicle Lighting Market
Off Road Vehicles
Utility Terrain Vehicles (UTV) Market
Off Road Vehicles
Off Road Motorcycles Market
Off Road Vehicles
Automotive and Off-Road Vehicle Hoses Market
Off Road Vehicles
Off-Highway Wheels Market
Off Road Vehicles
Off-Road High Performance Vehicle Market
Off Road Vehicles
Off-Road Vehicles Cooling Fan Market
Off Road Vehicles
US Off-Road Vehicles Market