
 Floating Solar System Market | 2026-2036
Floating Solar System Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Solar System Market Insights
Utility-scale procurement is hardening as the dominant demand channel for floating solar deployments. Ciel & Terre International leverages its proprietary Hydrelio platform to anchor project pipelines across Europe and Asia. Sungrow Power Supply sustains technology leadership through integrated floating inverter and energy storage solutions. Trina Solar competes aggressively on module efficiency tailored for bifacial floating configurations.
Floating solar systems deploy photovoltaic arrays on buoyant platforms anchored to water bodies, typically achieving 10-15% higher energy yield than ground-mounted equivalents due to the evaporative cooling effect. The primary commercial purpose centers on unlocking electricity generation from reservoirs, quarry lakes, and coastal lagoons without competing for terrestrial land use. Photovoltaic technology dominates current installed capacity while bifacial modules capture expanding margin pools from enhanced rear-side albedo gain on water surfaces. The utility end-user segment leads absolute deployment volumes, though commercial and industrial off-takers are gaining traction behind corporate renewable energy targets.
China's MEE enforces environmental impact assessments for water-body installations, while Japan's METI administers feed-in tariff qualification for floating PV systems on agricultural reservoirs. The EU Green Deal and F-Gas Regulation collectively shape module import standards and platform material specifications across European project pipelines. Stakeholders must monitor evolving anchoring standards and cable routing protocols as offshore floating solar advances into deeper water environments.
Market Dynamics
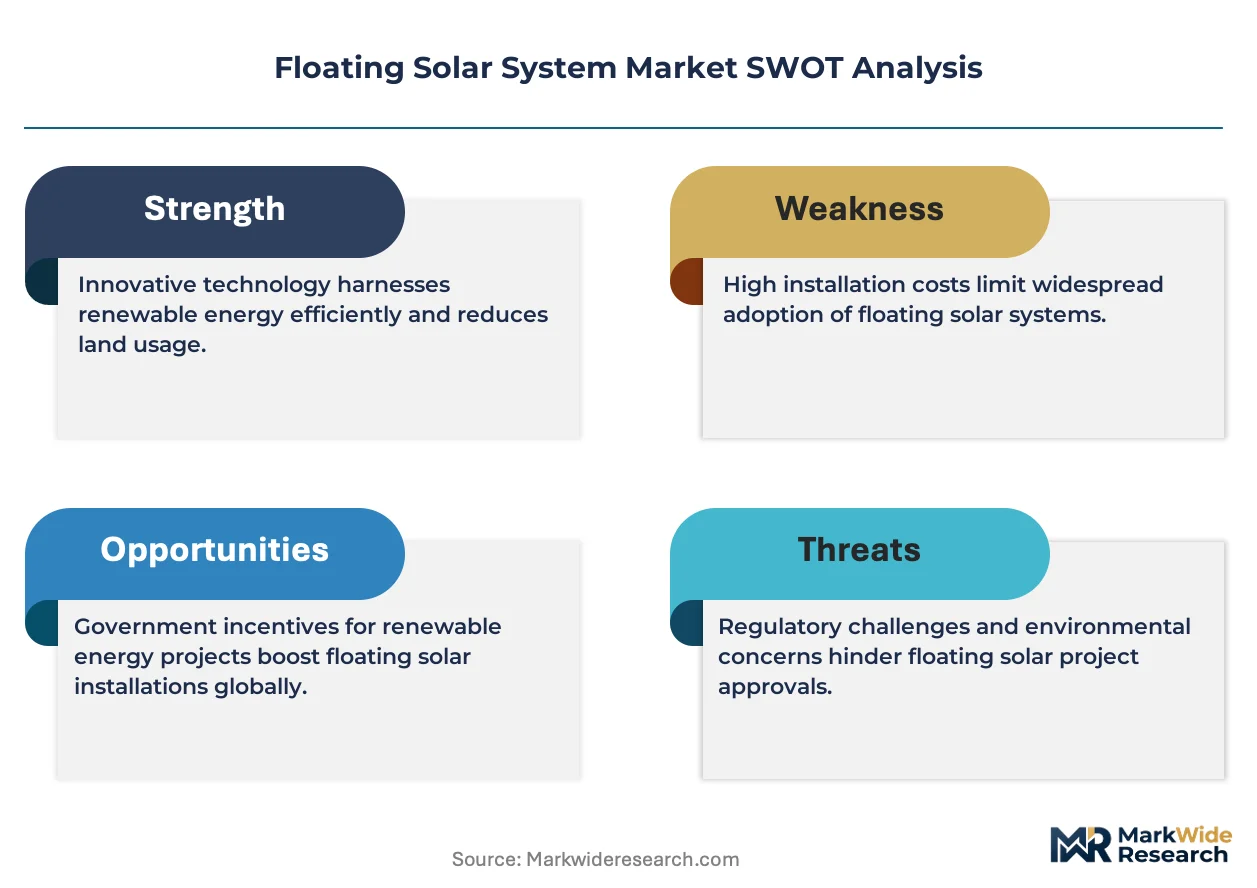
Utility-scale power purchase agreements are hardening as the dominant procurement channel, compressing project development cycles and favoring developers with integrated platform-inverter capabilities over pure component suppliers.
Growth Catalysts
- Japan's METI feed-in tariff:Agricultural reservoir installations qualify for premium rates, accelerating deployment on ponds in Hyogo and Chiba prefectures where land scarcity blocks ground-mounted alternatives.
- Evaporative cooling physics:Water-mounted photovoltaic arrays achieve sustained thermal advantage over terrestrial equivalents, improving module efficiency margins without active cooling infrastructure.
- China's dual carbon framework:Updated renewable energy quotas and provincial compliance deadlines are forcing state-owned utilities to fast-track reservoir-based projects on existing hydropower assets.
Market Restraints
- High-density polyethylene supply concentration:Platform buoyancy systems depend on specialized polymer grades where Asian petrochemical clusters control upstream resin production, exposing project budgets to feedstock volatility.
- Offshore anchoring technical limits:Current mooring engineering fails beyond 50-meter water depths, excluding deep coastal lagoons and open-sea environments from addressable site inventory.
- EU F-Gas Regulation compliance friction:Module import standards and platform material specifications add certification layers that extend European project timelines relative to Asian counterparts.
Strategic Opportunities
- India's CEA renewable purchase obligations:State electricity regulators are incorporating floating solar carve-outs into distribution company mandates, creating first-mover advantages on dam reservoirs in Maharashtra and Tamil Nadu.
- Bifacial-albedo convergence:Rear-side energy capture from water surface reflectance is expanding addressable yield per hectare, repositioning module selection criteria for new project pipelines.
- Corporate renewable energy procurement:Industrial off-takers with net-zero commitments are bypassing utility intermediaries to contract directly with floating solar developers for dedicated offtake.
Industry Challenges
- Marine electrical engineering talent scarcity:Submerged cable routing and corrosion-resistant junction design require specialized skills concentrated in offshore wind and oil-gas sectors, creating recruitment bottlenecks.
- Multi-stakeholder site access complexity:Reservoir installations require coordination between water resource authorities, agricultural irrigation boards, and grid operators, fragmenting permitting timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Solar System Market |
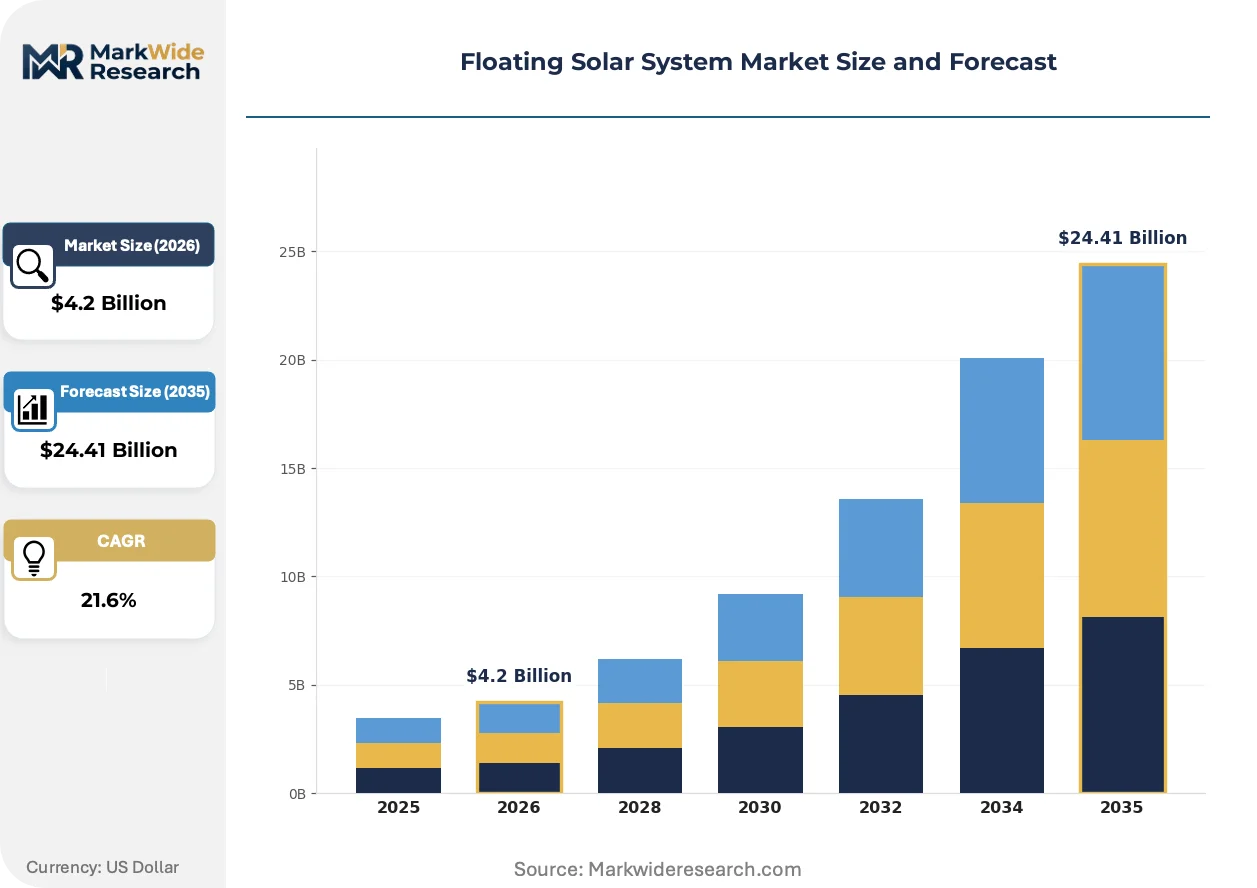
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $24.41 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photovoltaic, Concentrated Solar Power, Bifacial Modules, Floating Platforms End User: Utilities, Commercial, Industrial, Residential Installation Type: Onshore, Offshore, Hybrid, Fixed Component: Inverters, Mounting Structures, Cables, Monitoring Systems |
| Companies Covered | Ciel & Terre International, Sungrow Power Supply, Trina Solar, LONGi Solar, JA Solar Technology, KYOCERA Corporation, Sharp Corporation, Ocean Sun, Vikram Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Solar System Market Trends and Innovations
Technology convergence between floating platform engineering and bifacial module architecture is reshaping system design priorities, while regulatory frameworks in major economies are formalizing environmental safeguards that favor established developers with compliance infrastructure.
High-efficiency bifacial modules with dual-glass construction are expanding into floating configurations as the dominant technology choice for new utility-scale tenders. European and Japanese developers are specifying these modules for agricultural reservoir projects where rear-side albedo gain from water surfaces compounds energy yield advantages. This technology shift is expanding into deeper water environments as platform engineering advances, compressing the performance gap between coastal and inland installations.
The EU Green Deal in combination with F-Gas Regulation is tightening material specifications for imported photovoltaic modules and synthetic platform components. Industrial consequence includes mandatory supply chain documentation and restricted substance thresholds that disqualify non-compliant Asian manufacturers from European project pipelines. Utility-scale developers with European pipelines are responding by qualifying alternative module suppliers and accelerating in-country platform fabrication partnerships.
Direct corporate power purchase agreements are displacing traditional utility-mediated procurement for commercial and industrial floating solar offtake. Large energy consumers with Scope 2 reduction targets are contracting directly with project developers for dedicated reservoir-based generation, bypassing regulated tariff structures. This pattern is most visible in Japan's manufacturing belt and South Korea's industrial zones where land-constrained facilities seek renewable supply without terrestrial footprint competition.
Floating Solar System Market Segmentation
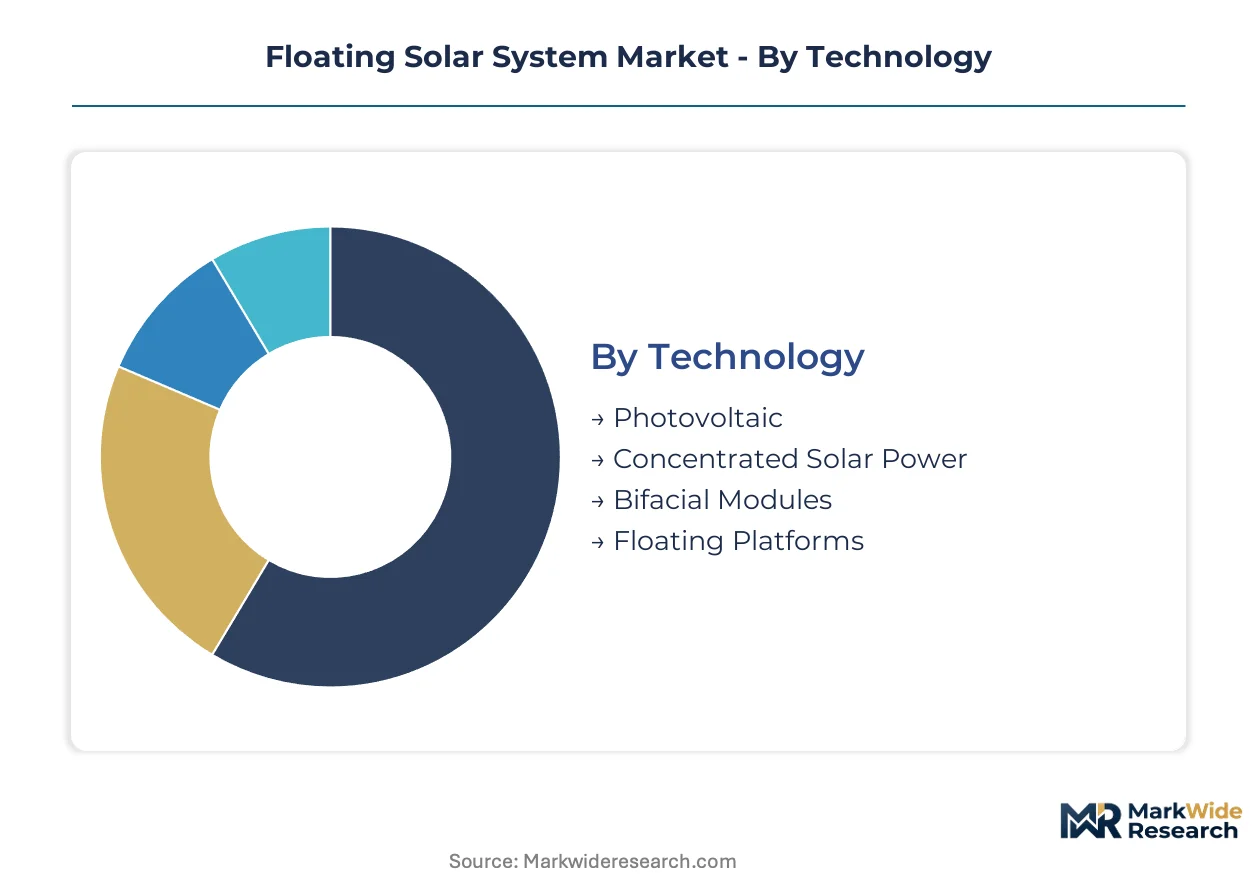
Floating solar systems require precise technology matching to water body characteristics and grid connection requirements. Segmentation reveals which configurations deliver standalone generation versus hybrid integration with existing infrastructure.
Technology:
Photovoltaic dominates as standalone generation technology while concentrated solar power remains embedded within hybrid thermal-solar configurations.
- Photovoltaic:Crystalline silicon cells mounted on buoyant platforms constitute the baseline technology for reservoir and quarry lake installations. Demand concentrates in China's provincial utility procurements where state-owned developers fast-track projects on existing hydropower reservoirs to meet dual carbon compliance deadlines.
- Bifacial Modules:Dual-glass construction captures rear-side irradiance reflected from water surfaces, yielding 10-15% energy gains over monofacial equivalents. Japanese agricultural reservoir projects in Hyogo and Chiba prefectures specify these modules to maximize feed-in tariff returns on constrained pond surfaces.
- Concentrated Solar Power:Parabolic trough and tower configurations integrate with thermal storage for dispatchable output on large inland water bodies.
- Floating Platforms:High-density polyethylene and composite pontoon systems provide structural buoyancy and anchoring interfaces for module arrays.
Photovoltaic leads volumes today; bifacial modules are gaining share fastest.
End User:
Utility procurement operates at scale through power purchase agreements while commercial and industrial offtake pursues direct contracting for Scope 2 reduction targets.
- Utilities:State-owned and independent power producers deploy multi-megawatt arrays on reservoirs and coastal lagoons under long-term offtake contracts. China's provincial grid companies dominate procurement volumes as renewable energy quota enforcement tightens project timelines.
- Industrial:Manufacturing facilities with net-zero commitments contract directly with developers for dedicated floating solar supply. South Korea's industrial zones in Gyeonggi and Ulsan show accelerating corporate procurement as land constraints block ground-mounted alternatives.
- Commercial:Retail and office complexes source smaller-scale installations on ornamental water features and cooling ponds.
- Residential:Individual property owners deploy kilowatt-scale systems on private ponds and small water bodies.
Utilities anchor current deployment; industrial direct procurement shows the steepest expansion trajectory.
Installation Type:
Onshore reservoir installations deliver proven economics while offshore configurations push engineering boundaries into deeper water environments.
- Onshore:Inland reservoirs, quarry lakes, and irrigation ponds provide sheltered conditions with established anchoring methodologies. India's dam reservoirs in Maharashtra and Tamil Nadu concentrate development activity under CEA renewable purchase obligation carve-outs.
- Offshore:Coastal and open-water installations face 50-meter depth limits and marine corrosion challenges that constrain addressable inventory. Japan's coastal industrial zones drive pilot projects as land scarcity intensifies.
- Hybrid:Co-located floating solar and hydropower assets share transmission infrastructure and water management systems.
- Fixed:Permanently anchored platforms on small water bodies with minimal wave action and stable water levels.
Onshore installations dominate current capacity; offshore configurations are expanding most quickly as platform engineering advances.
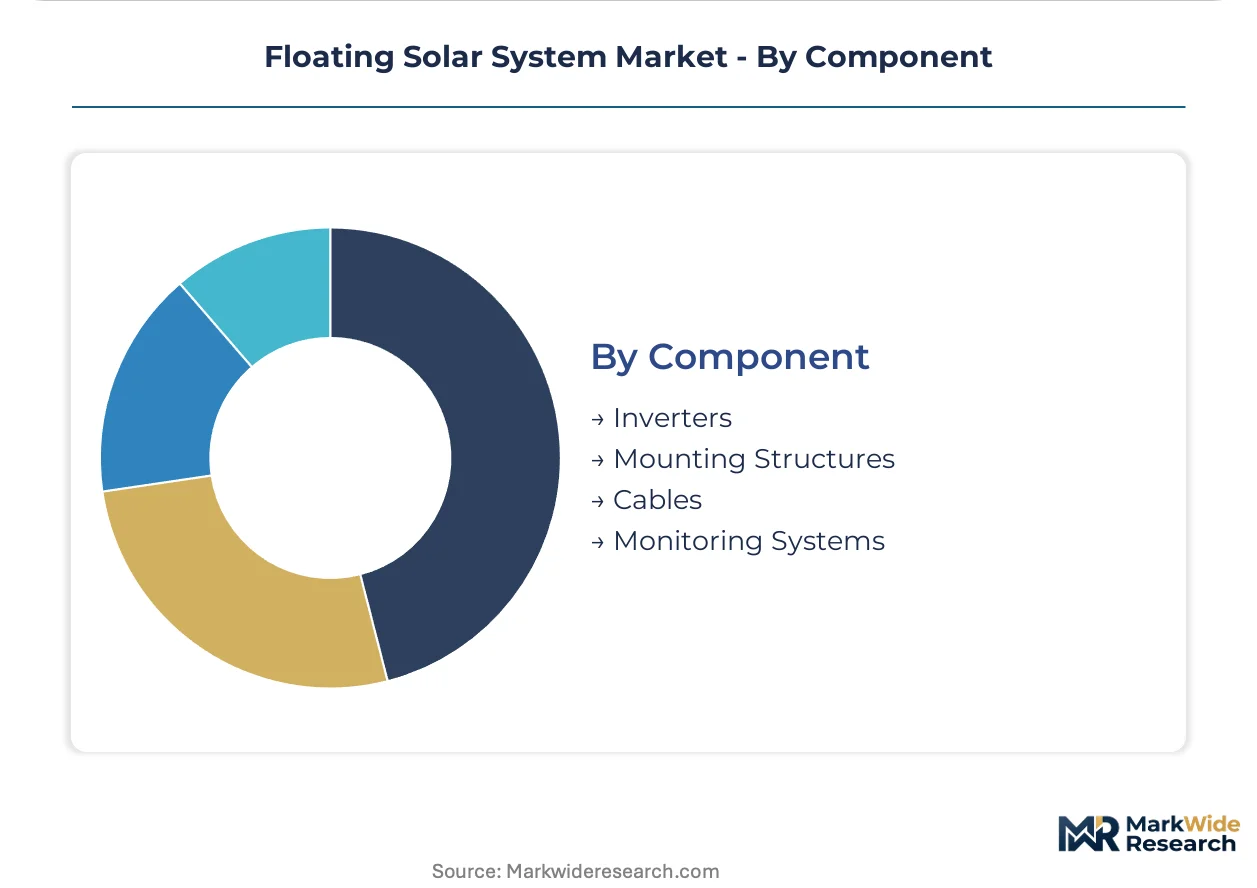
Component:
System reliability depends on corrosion-resistant electrical infrastructure and real-time performance monitoring adapted to aquatic environments.
- Inverters:IP68-rated string and central inverters with salt-mist resistance protect against humidity and water ingress. Integrated floating inverter solutions from technology leaders reduce balance-of-system complexity for utility-scale developers.
- Mounting Structures:Aluminum and composite racking systems secure modules to pontoon platforms while accommodating wave-induced flexure. European project pipelines specify EU Green Deal compliant materials to satisfy F-Gas Regulation import standards.
- Cables:Submerged and floating cable routing with marine-grade insulation and junction protection.
- Monitoring Systems:Remote sensing and drone-based inspection platforms track performance and detect mooring degradation.
Inverters represent the highest-value component category; monitoring systems are climbing the fastest as predictive maintenance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's provincial utility procurements anchor regional deployment volumes as state-owned developers fast-track reservoir-based installations to meet dual carbon compliance deadlines. Japan's agricultural pond conversions and India's dam reservoir carve-outs concentrate secondary demand clusters. European project pipelines face extended timelines from F-Gas Regulation compliance layers.
China
State-owned grid companies dominate procurement through renewable energy quota enforcement on existing hydropower reservoirs. MEE environmental impact assessments compress development timelines for water-body installations. Sichuan and Yunnan provinces concentrate activity where reservoir co-location with transmission infrastructure accelerates project execution.
Japan
Land scarcity and high population density drive adoption on agricultural ponds and industrial water bodies in manufacturing belts. METI feed-in tariff qualification for agricultural reservoir installations qualifies projects for premium rates. Hyogo and Chiba prefectures concentrate deployment where pond surfaces substitute for unavailable terrestrial sites.
India
State electricity regulators incorporate floating solar carve-outs into distribution company mandates under CEA renewable purchase obligations. Maharashtra and Tamil Nadu dam reservoirs concentrate first-mover development activity. Distribution companies in these states face compliance pressure to procure reservoir-based generation.
South Korea
Industrial zones in Gyeonggi and Ulsan accelerate corporate procurement as land constraints block ground-mounted alternatives for manufacturing facilities with net-zero commitments. Direct power purchase agreements bypass regulated tariff structures. Coastal industrial water bodies host pilot projects pushing offshore engineering boundaries.
Germany
Quarry lake installations and inland water bodies attract utility-scale developers seeking sites without terrestrial land use competition. EU Green Deal and F-Gas Regulation compliance layers extend project timelines relative to Asian counterparts. Bavaria and North Rhine-Westphalia concentrate permitting activity where water authorities coordinate with grid operators.
Floating Solar System Market Competitive Landscape
Capacity expansion dominates the current landscape as developers race to secure reservoir site inventory ahead of regulatory deadlines. The vendor base stratifies across integrated platform-inverter providers, pure module suppliers, and specialized marine engineering firms. Three archetypes define competitive positioning: technology-integrated developers with proprietary floating platforms, component specialists supplying standardized buoyancy systems, and hybrid solution providers combining solar generation with energy storage. M&A activity and strategic partnerships concentrate around offshore engineering capabilities and European compliance infrastructure.
Among technology-integrated developers, Ciel & Terre International and Sungrow Power Supply exemplify the platform-inverter convergence archetype. Trina Solar occupies a position within the module efficiency tier, competing on bifacial configurations tailored for floating deployment. These three companies represent distinct strategic vectors: proprietary anchoring systems, integrated power electronics, and high-efficiency module architecture.
| Leading Market Players |
|---|
| Ciel & Terre International |
| Sungrow Power Supply |
| Trina Solar |
| LONGi Solar |
| JA Solar Technology |
| KYOCERA Corporation |
| Sharp Corporation |
| Ocean Sun |
| Vikram Solar |
| Others |
Pricing and Supply Chain Analysis
Utility-scale procurement consolidation in China and Japan is forcing platform-inverter suppliers to absorb polyethylene resin volatility while maintaining fixed-price EPC contracts, compressing margins for non-integrated component vendors.
Pricing Analysis
Input-cost pass-through from high-density polyethylene resin markets dominates floating solar pricing dynamics. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant European fabricators from Asian mass producers and non-certified regional assemblers. Price differentiation stems from F-Gas Regulation certification tier and vertical integration depth in inverter-platform bundling. Pricing pressure stems from state-owned utility procurement consolidation in China, which squeezes EPC margins through volume-driven reverse auctions. Industrial offtakers in South Korea show lowest price sensitivity due to net-zero compliance premiums, while Indian distribution companies under CEA mandates exhibit highest sensitivity to upfront capital costs.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Chinese petrochemical clusters for specialized HDPE resin grades used in pontoon buoyancy systems. Upstream polymer production concentrates in China, South Korea, and Japan, with compounding and platform fabrication following downstream. Raw material dependencies span naphtha-derived polyethylene, marine-grade aluminum for racking, and IP68-rated power electronics. Supply chain risk centers on tariff exposure from EU F-Gas Regulation import restrictions that disqualify non-compliant Asian module suppliers. Distribution runs through EPC contractors and direct utility procurement channels, with emerging corporate PPA routes bypassing traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating solar development functions as a geographic-arbitrage play where developers exploit the gap between China's compressed provincial utility timelines and Europe's extended compliance-driven project cycles to optimize capital deployment.
For Market Incumbents: Acquire offshore mooring engineering capabilities to defend against pure-play marine specialists entering from wind and oil-gas sectors. State-owned utility procurement consolidation in China threatens pure component suppliers; backward integration into HDPE compounding or captive inverter production secures margin control. EU F-Gas Regulation compliance infrastructure represents a defendable moat against Asian cost competitors. For New Entrants and Emerging Players: Bifacial module optimization for water-albedo environments offers technology-first entry without competing on platform manufacturing scale. India's CEA renewable purchase obligation carve-outs in Maharashtra and Tamil Nadu present the most penetrable geography for first-mover reservoir site access. Direct corporate PPA origination with industrial offtakers in South Korea bypasses utility procurement barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with platform-inverter integrated developers holding European compliance infrastructure and Asian cost bases. Long-term viability over the coming decade hinges on offshore engineering capabilities as water-depth limits expand. Acquisition targets should combine marine electrical engineering talent with qualified module supply chains. The signal to watch is METI feed-in tariff rate revisions for agricultural reservoir installations in Japan.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Mooring Engineering Acquisition | Marine engineering capabilities from offshore wind unlock 50-meter-plus water depths for coastal installations. |
| EU Green Deal Compliance Certification | F-Gas Regulation qualification excludes non-compliant Asian competitors from European project pipelines. |
| Bifacial Module Platform Integration | Dual-glass construction optimized for water-albedo gain captures 10-15% yield premiums in Japanese agricultural reservoirs. |
| Corporate PPA Origination Capability | Direct contracting with South Korean industrial offtakers bypasses regulated utility tariffs and accelerates offtake closure. |
| HDPE Compounding Backward Integration | Captive resin processing insulates margins from Asian petrochemical feedstock volatility in platform manufacturing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, EPC contractors, floating platform engineers, and corporate renewable energy procurement leads with secondary validation. Secondary sources included EIA project databases, IEA renewable energy reports, FERC interconnection filings, and national regulator submissions from METI, MEE, and CEA. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume estimates across technology and end-user segments.
Comparable-period anchoring linked forward projections to historical deployment trajectories from reservoir commissioning records and PPA execution timelines. The analytical framework modeled technology type, installation depth tier, end-user procurement channel, and regional regulatory cluster across the projection horizon. CAGRs derived from segmented growth rate blending weighted by addressable site inventory. Forecast inputs incorporated hydropower reservoir co-location potential and bifacial module yield assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to offshore anchoring engineering breakthroughs and EU F-Gas Regulation enforcement intensity. Forecasts reflect documented assumptions about resin supply stability and utility procurement consolidation trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Fixed Tilt Solar PV Market
Solar Power Systems
Solar Tracker for Power Generation Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Tubular Solar Collector Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Global Airport Solar Power Market