
 Global Cardiac Tamponade Market | 2026-2036
Global Cardiac Tamponade Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Tamponade Market Foresight
Germany is rewriting supply dynamics for pericardiocentesis devices through expanded catheter production near Frankfurt's medical technology corridor. Medtronic leverages integrated manufacturing networks across Bavaria to sustain European distribution. Abbott anchors diagnostic catheter supply through specialized facilities serving Western European cardiology clinics.
Cardiac tamponade denotes acute pericardial fluid accumulation compressing the heart chambers, requiring immediate pericardiocentesis intervention using 16–18 gauge needles with echocardiographic guidance to restore ventricular filling pressure. Catheters and drainage sets constitute the primary revenue pool, with monitoring devices representing the fastest-expanding segment as remote hemodynamic tracking integrates into post-procedural care. Emergency care applications dominate volume, while surgical procedures command premium pricing due to integrated operating room deployment requirements.
FDA premarket notification pathways and EU MDR conformity assessments govern device commercialization, with notified bodies in Germany and the Netherlands extending review timelines for novel drainage materials. The WHO's emergency surgical care guidelines increasingly reference pericardiocentesis protocols, expanding addressable demand in health systems building trauma capacity. Stakeholders must monitor reimbursement shifts toward outpatient pericardiocentesis as ambulatory deployment models mature.
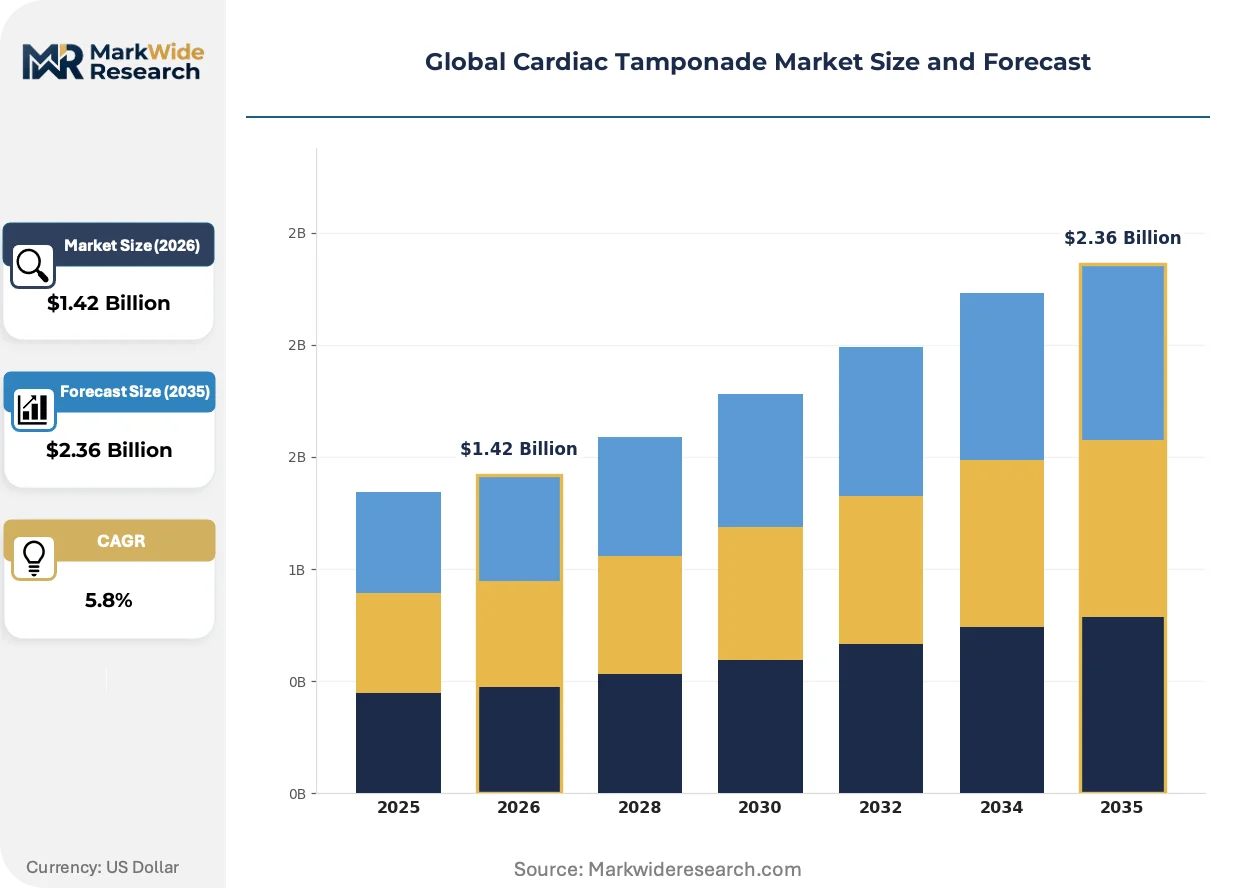
Market Dynamics
Emergency care units in tertiary hospitals are consolidating purchasing power around integrated drainage systems, compressing procurement cycles for standalone pericardiocentesis kits while elevating technical specifications for catheter materials and hemodynamic monitoring compatibility.
Growth Catalysts
- Emergency surgical care guidelines:The WHO's trauma capacity protocols now embed pericardiocentesis as a core intervention, expanding device deployment in health systems across Southeast Asia and sub-Saharan Africa building acute cardiac response infrastructure.
- EU MDR conformity pathways:Notified bodies in Germany and the Netherlands have streamlined technical documentation reviews for established drainage materials, accelerating market access for manufacturers with existing CE certificates.
- Ambulatory deployment models:Outpatient pericardiocentesis reimbursement frameworks in the United States are maturing, shifting procedure volume from inpatient surgical suites to specialized cardiac intervention centers.
Market Restraints
- Silicone polymer feedstock volatility:Catheter-grade silicone supply concentrates among three specialty chemical producers in Germany and Japan, exposing device manufacturers to input cost swings and allocation constraints.
- FDA premarket notification timelines:Class II cardiovascular device reviews now average fourteen months for novel drainage materials, extending capital recovery periods and deterring incremental innovation in catheter coatings.
- Echocardiography skill scarcity:Real-time ultrasound guidance requires specialized training that cardiology fellowship programs in Brazil and India have not scaled proportionally to device availability.
Strategic Opportunities
- Remote hemodynamic tracking integration:Post-procedural monitoring devices represent the fastest-expanding segment as telemetry systems converge with drainage catheters, enabling early discharge protocols.
- Frankfurt medical technology corridor expansion:Catheter production capacity near Rhine-Main logistics hubs is scaling to serve Central and Eastern European cardiac centers underserved by current distribution networks.
- Japanese PMDA priority review vouchers:Breakthrough device designation for integrated drainage-monitoring systems offers accelerated approval pathways for manufacturers targeting the Asia-Pacific acute care market.
Industry Challenges
- EU MDR technical documentation recertification:Legacy device portfolios require substantial clinical evidence supplementation, straining regulatory affairs teams and compressing R&D bandwidth for next-generation platforms.
- Interoperability with legacy hospital IT:Smart drainage systems transmitting hemodynamic data face integration friction with proprietary electronic health record architectures predominant in German university hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Tamponade Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pericardiocentesis Needles, Catheters, Drainage Sets, Monitoring Devices Application: Emergency Care, Critical Care, Surgical Procedures, Diagnostic Assessment End User: Cardiology Clinics, Intensive Care Units, Surgical Centers, Diagnostic Laboratories Deployment: Hospital-Based, Ambulatory Care, Home Healthcare, Emergency Medical Services |
| Companies Covered | Johnson & Johnson, Koninklijke Philips N.V., Medtronic, Edwards Lifesciences Corporation, Hitachi, Ltd., Boston Scientific Corporation, General Electric Company, Teleflex Incorporated, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Tamponade Market Shifts & Advancements
Digital twin technology is virtualizing pre-procedural planning and post-intervention monitoring, collapsing the traditional separation between diagnostic imaging and therapeutic device deployment in acute cardiac care workflows.
Sensor-embedded drainage catheters equipped with pressure transducers and wireless telemetry are virtualizing continuous hemodynamic assessment, enabling tertiary hospital emergency departments to monitor pericardial pressure remotely rather than retaining patients in intensive care solely for observation. Cardiac surgery divisions in Bavaria and North Rhine-Westphalia have piloted these systems since early adoption programs began, with procurement committees now specifying integrated monitoring as a mandatory evaluation criterion.
The FDA's evolving enforcement posture on cybersecurity in networked medical devices is compelling manufacturers to embed hardware-based encryption and automated vulnerability patching into drainage system firmware. Device firms with Class II cardiovascular portfolios are reallocating engineering resources to meet the October 2023 guidance deadline, with catheter-electronics integration projects receiving priority funding over material science initiatives. German notified bodies have begun parallel assessments of cybersecurity documentation, extending review timelines but reducing duplicate submission burdens for dual-market products.
Hospital purchasing cooperatives in the United States are consolidating pericardiocentesis device contracts under broader cardiovascular intervention bundles, displacing standalone kit negotiations. Integrated delivery networks in Texas and California have led this transition, awarding multi-year agreements to suppliers offering drainage sets, monitoring hardware, and training support as unified packages. European group purchasing organizations have begun analogous consolidation, though national procurement regulations in France and Italy fragment implementation speed.
Global Cardiac Tamponade Market Segmentation
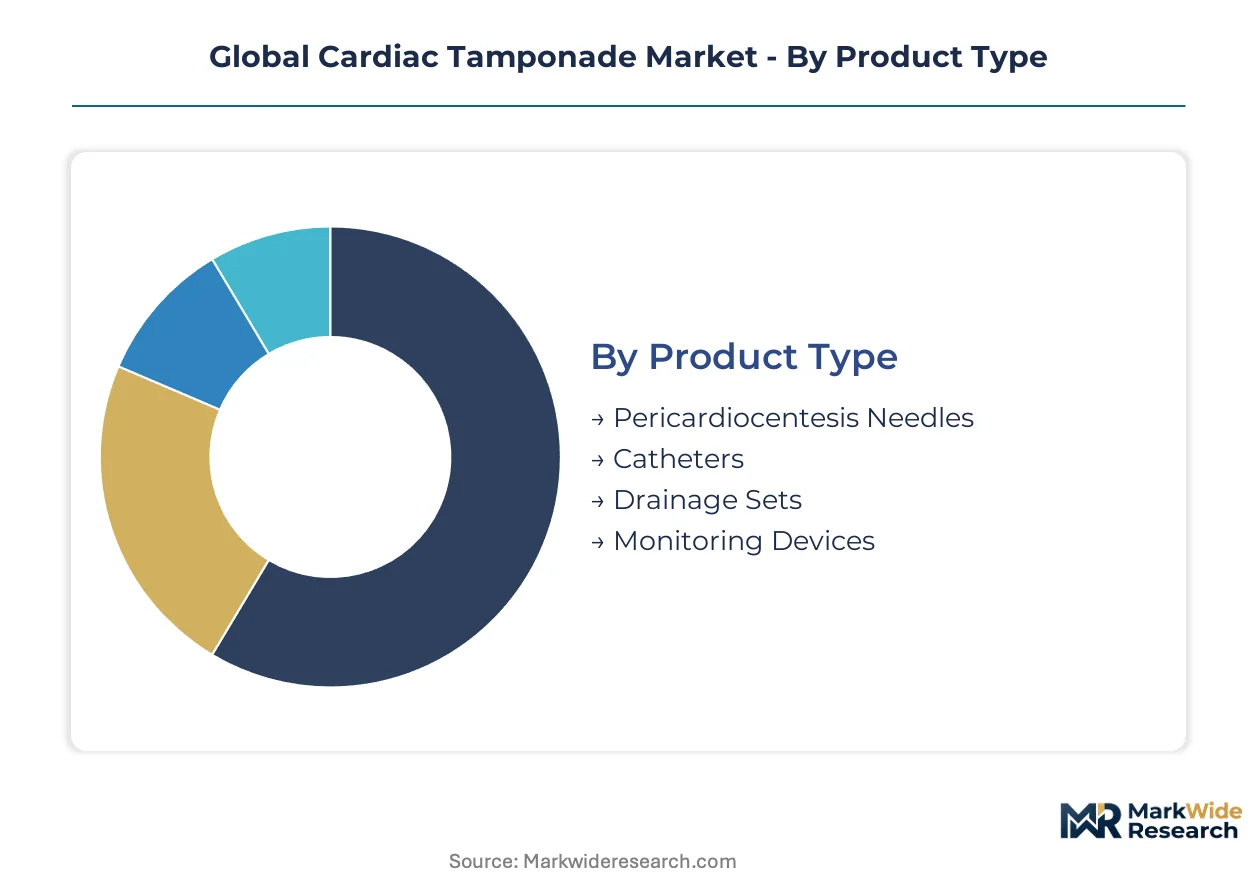
Product configurations in cardiac tamponade intervention span emergency drainage hardware through connected monitoring platforms. Segment boundaries reflect divergent reimbursement pathways and clinical workflow integration requirements across acute care settings.
Product Type:
Use cases range from immediate pericardial decompression to extended hemodynamic surveillance post-intervention.
- Pericardiocentesis Needles:16–18 gauge stainless steel or coated variants designed for echocardiographic-guided entry into the pericardial space. Emergency departments in tertiary German hospitals specify needle gauge and length combinations optimized for subxiphoid approaches.
- Catheters:Silicone or polyurethane multi-lumen designs enabling sustained pericardial drainage with pressure monitoring ports. Demand concentrates in cardiology clinics across Bavaria and North Rhine-Westphalia where ambulatory pericardiocentesis protocols are expanding.
- Drainage Sets:Integrated kits combining needle, catheter, collection bag, and connection tubing for sterile field deployment.
- Monitoring Devices:Sensor-embedded systems transmitting pericardial pressure data to telemetry stations.
Established volume favors Catheters; emerging adoption favors Monitoring Devices.
Application:
Clinical settings impose distinct device specifications based on urgency, patient stability, and procedural complexity.
- Emergency Care:Rapid-deployment configurations prioritizing speed of pericardial decompression in hemodynamically unstable patients. Volume concentrates in United States trauma centers where emergency medicine residency programs emphasize pericardiocentesis competency.
- Critical Care:Extended drainage with continuous pressure monitoring for patients requiring hemodynamic stabilization post-intervention. Adoption is accelerating fastest in Japanese intensive care units integrating drainage systems with centralized monitoring architectures.
- Surgical Procedures:Operating room-compatible sets with enhanced sterility assurance and integration with cardiopulmonary bypass circuits.
- Diagnostic Assessment:Low-volume fluid sampling for etiological analysis without therapeutic drainage.
Revenue concentration sits with Emergency Care; Critical Care is climbing the fastest.
End User:
Facility type determines procurement scale, training infrastructure, and reimbursement capture mechanisms.
- Cardiology Clinics:Outpatient-focused sites performing elective and urgent pericardiocentesis under local anesthesia. Procurement in United States cardiology clinics is shifting toward bundled payment models incorporating device and professional fees.
- Intensive Care Units:High-acuity environments managing post-procedural monitoring and complications. German university hospital ICUs specify integrated drainage-monitoring systems with EHR interoperability.
- Surgical Centers:Ambulatory facilities performing pericardiocentesis as adjunct to cardiac surgery.
- Diagnostic Laboratories:Reference sites handling pericardial fluid analysis for tertiary diagnosis.
Procurement scale favors Intensive Care Units; outpatient migration favors Cardiology Clinics.
Deployment:
Care setting location shapes device portability requirements, connectivity specifications, and supply chain logistics.
- Hospital-Based:Fixed-installation systems with full monitoring integration and sterile processing support. Volume concentrates in United States integrated delivery networks consolidating cardiovascular service lines.
- Ambulatory Care:Portable configurations enabling same-day discharge protocols. Expansion is steepest in German cardiac intervention centers near Frankfurt's medical technology corridor.
- Home Healthcare:Simplified drainage management for chronic pericardial effusion patients.
- Emergency Medical Services:Pre-hospital kits for field pericardiocentesis in penetrating chest trauma.
Installed base favors Hospital-Based; reimbursement reform favors Ambulatory Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main logistics corridor underwrites Germany's dominance in catheter manufacturing, while the Port of Rotterdam anchors distribution throughput for Western European cardiac centers. These infrastructure assets position Central Europe as the critical node for device supply chains serving acute cardiac care networks.
United States
Emergency medicine residency programs at trauma centers in Texas and California drive procedural volume and device specification standards. The FDA's premarket notification pathway for Class II cardiovascular devices shapes product development timelines, with review cycles averaging fourteen months for novel drainage materials. Integrated delivery networks in the Southwest consolidate procurement under bundled cardiovascular intervention contracts.
Germany
Specialized cardiac centers clustering around university hospital networks in Bavaria and North Rhine-Westphalia concentrate demand for integrated drainage-monitoring systems. The EU MDR conformity assessment process through German notified bodies streamlines technical documentation reviews for established catheter materials. The Frankfurt medical technology corridor scales production capacity to serve Central and Eastern European markets previously underserved by distribution networks.
Japan
Intensive care units in Tokyo and Osaka integrate drainage systems with centralized monitoring architectures, accelerating adoption of sensor-embedded catheters. The PMDA's priority review voucher program for breakthrough device designation offers accelerated approval pathways for integrated drainage-monitoring platforms. The Kanto region anchors manufacturing partnerships between domestic device firms and specialty chemical suppliers.
India
Cardiology fellowship programs in Maharashtra and Karnataka have not scaled echocardiography training proportionally to device availability, creating a capability gap. The Central Drugs Standard Control Organization governs medical device registration, with recent regulatory harmonization efforts streamlining import pathways for drainage sets. Metro hospital networks in Delhi-NCR and Chennai build trauma capacity referencing WHO emergency surgical care guidelines.
Global Cardiac Tamponade Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying catheter materials and sensor modules. The vendor base stratifies across three tiers: diversified cardiovascular conglomerates with integrated drainage portfolios, mid-cap device firms focused on pericardiocentesis kits, and specialty chemical suppliers providing silicone polymer feedstock. Competitive moves concentrate on M&A to secure monitoring technology capabilities and capacity expansion near Rhine-Main logistics hubs to reduce lead times for Central European delivery.
Among diversified cardiovascular conglomerates, Medtronic, Abbott, and Boston Scientific Corporation exemplify the platform-integrator archetype. These firms occupy positions spanning drainage hardware through connected monitoring ecosystems, leveraging integrated manufacturing networks across multiple geographies to sustain distribution scale. Their market presence anchors the competitive structure, with procurement committees at German university hospitals and United States integrated delivery networks specifying their platforms as mandatory evaluation benchmarks for bundled contract awards.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Koninklijke Philips N.V. |
| Medtronic |
| Edwards Lifesciences Corporation |
| Hitachi, Ltd. |
| Boston Scientific Corporation |
| General Electric Company |
| Teleflex Incorporated |
| Abbott |
| Others |
Supply & Pricing Matrix
Catheter-grade silicone feedstock concentrates among specialty chemical producers in Germany and Japan, anchoring margin pools in drainage set assembly and integrated monitoring platforms rather than raw polymer supply. Device manufacturers face asymmetric pricing power where three upstream suppliers dictate allocation terms to downstream kit assemblers.
Pricing Analysis
FDA premarket notification pathways and EU MDR conformity assessments dictate the pricing tier structure across drainage device portfolios. Three-tier pricing structure across premium, standard, and economy levels separates integrated monitoring systems from standalone kits from basic needle configurations. Price differentiation rests on CE marking tier and hemodynamic telemetry compatibility. Pricing pressure stems from hospital purchasing cooperative consolidation in Texas and California demanding bundled cardiovascular intervention contracts. Emergency care units in United States trauma centers exhibit highest price sensitivity; surgical suites in German university hospitals show lowest.
Supply Chain Analysis
Contract manufacturing capacity for sensor-embedded catheters concentrates with EMS providers in the Kanto region and Rhine-Main corridor. Geographic supply concentration spans Germany, Japan, and United States for finished devices; China and India for sterile packaging components. Raw material dependencies include medical-grade silicone polymers, pressure transducer modules, and wireless telemetry chipsets. Single-source vulnerability sits with Japanese specialty chemical producers for catheter-grade polyurethane formulations. Distribution runs through hospital purchasing cooperatives in United States integrated delivery networks and group purchasing organizations in Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
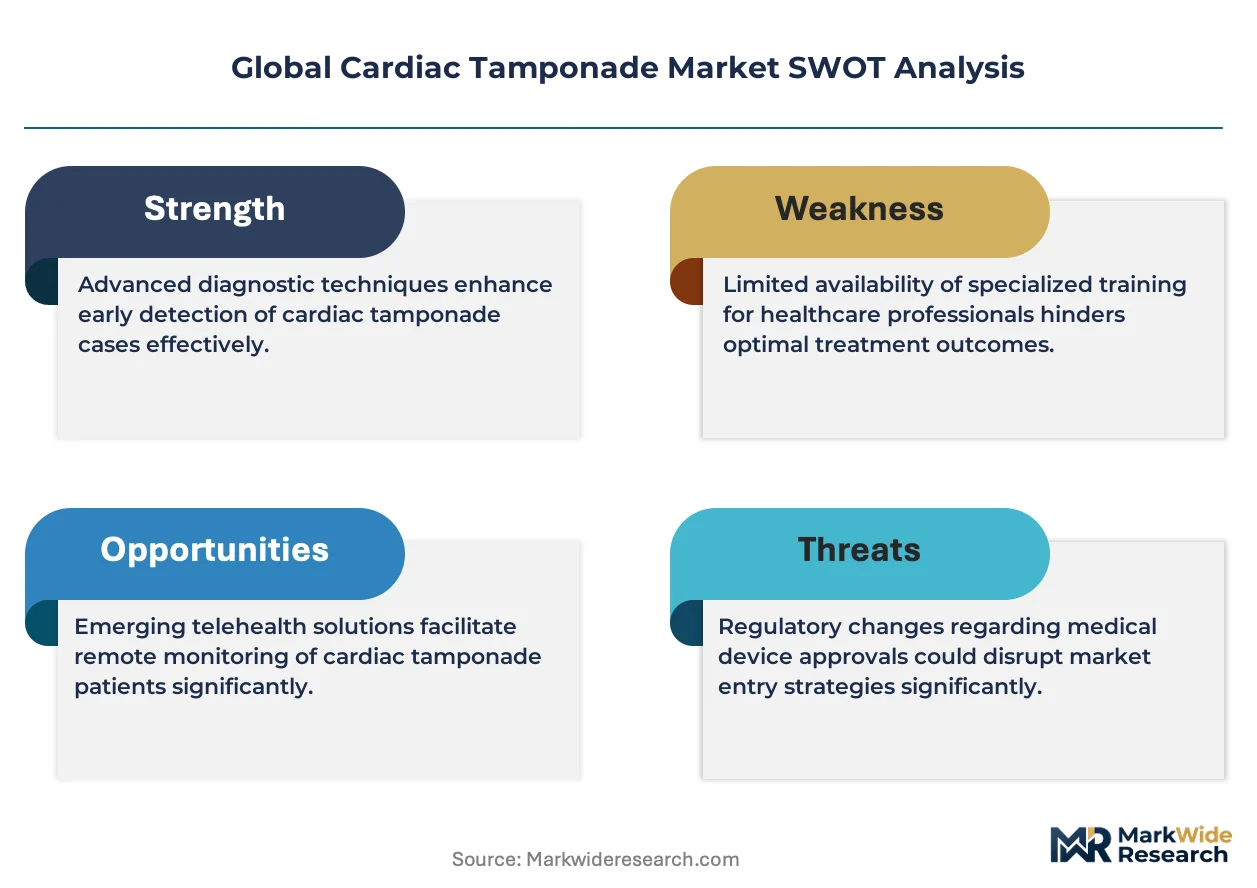
This market sits at a platform-economics inflection where interoperability with electronic health record architectures determines contract viability. The convergence of drainage hardware with remote hemodynamic telemetry is reshaping competitive positioning around data integration rather than device performance alone.
For Market Incumbents: Entrench position through backward integration into catheter-grade silicone polymer supply and capacity expansion near Frankfurt's medical technology corridor. The threat of mid-cap device firms acquiring monitoring technology capabilities demands preemptive certification investment in EU MDR cybersecurity documentation. Channel control through exclusive hospital system partnerships in Bavaria and North Rhine-Westphalia anchors procurement committee specifications.
For New Entrants and Emerging Players: Pursue white-space opportunity in ambulatory pericardiocentesis reimbursement frameworks maturing across United States cardiology clinics. The most penetrable segment sits with outpatient-focused sites performing urgent procedures under local anesthesia. A go-to-market angle emphasizing training support bundled with drainage kits addresses echocardiography skill scarcity in Brazil and India.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap device firms holding CE-marked drainage portfolios but lacking integrated monitoring capabilities. Long-term viability over a 5-10 year window hinges on telemetry convergence and software companion development. The acquisition target archetype is regional catheter manufacturers with established hospital system relationships in Central and Eastern Europe. The signal to watch is Japanese PMDA breakthrough device designation awards for integrated drainage-monitoring platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Cybersecurity Documentation | German notified bodies extend review timelines for networked drainage systems with hardware-based encryption. |
| Hospital System Partnership | Exclusive supply agreements with United States integrated delivery networks in Texas consolidate procurement under cardiovascular bundles. |
| Software Companion Development | Remote hemodynamic tracking integration enables early discharge protocols in Japanese intensive care units. |
| Reimbursement Strategy | Outpatient pericardiocentesis coding alignment with CMS Medicare frameworks shifts volume from inpatient surgical suites. |
| CE Marking Pathway | Streamlined technical documentation reviews for established drainage materials accelerate market access across Western European cardiac centers. |
Research Methodology
A spread of perspectives from hospital purchasing committee members, biomedical engineers, regulatory affairs specialists, and GPO contracts managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and WHO emergency surgical care guidelines. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application setting, end-user facility, and deployment location alongside regional regulatory cluster variations. CAGRs derived from procedure volume trajectories and device replacement cycles. Industry-specific forecast inputs incorporated echocardiography training pipeline scaling and silicone polymer feedstock allocation constraints.
Sensitivities concentrate around FDA premarket notification timeline extensions, EU MDR recertification delays for legacy portfolios, and echocardiography skill scarcity limiting procedural volume in emerging markets. Forecasts reflect documented assumptions on reimbursement reform velocity and ambulatory deployment model maturation. Quarterly review of hospital purchasing cooperative contract awards and PMDA breakthrough device designation grants is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Europe Acute Coronary Syndrome Market
Cardiovascular
Carotid Artery Stenosis Market
Cardiovascular
Endocarditis Therapeutics Market
Cardiovascular
Atrial Fibrillation Stroke Treatment Market
Cardiovascular
Global Advanced Cardiovascular Life Support Market
Cardiovascular
Vasculitis Market
Cardiovascular
Angina Pectoris Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Dilated Cardiomyopathy Market
Cardiovascular
Cardiac Arrhythmia Therapeutics Market
Cardiovascular
Ventricular Tachycardia Market
Cardiovascular
Ischemia Market
Cardiovascular
Carotid Artery Disease Market
Cardiovascular
Chronic Pulmonary Hypertension Treatment Market
Cardiovascular
Ischemia Reperfusion Injury Treatment Market
Cardiovascular
Global Cardiac Rehabilitation Market