
 Atorvastatin Diepoxide Calcium Salt Market | 2026-2036
Atorvastatin Diepoxide Calcium Salt Market Size, Share, and Industry Trends Forecast 2026-2036
Atorvastatin Diepoxide Calcium Salt Market Insights
ICH Q3A(R2) impurity qualification thresholds for specified organic impurities is redrawing competitive boundaries for atorvastatin diepoxide calcium salt suppliers. Pfizer leverages its legacy process knowledge from Lipitor development to sustain analytical method superiority. Dr. Reddy's Laboratories anchors large-volume API production from its Indian manufacturing base. DSM Sinochem Pharmaceuticals differentiates through integrated fermentation-to-synthesis capabilities across European and Asian facilities.
Atorvastatin diepoxide calcium salt is a related substance and synthetic intermediate in atorvastatin calcium production, characterized by an epoxide bridge at the dihydroxy acid moiety and existing as a calcium salt complex with defined crystallinity and particle size distribution critical for downstream coupling reactions. The compound serves primarily as a reference standard for impurity profiling and as a process intermediate in commercial statin synthesis routes. Tablet formulations dominate current offtake as generic atorvastatin volume concentrates in oral solid dosage manufacturing, while cardiovascular applications anchor demand through sustained prescribing of statin therapy for LDL cholesterol management. Hospital procurement channels represent the most concentrated margin pool due to tender-based volume commitments and direct contracting relationships with API suppliers.
US FDA enforces ICH Q3B(R2) reporting thresholds for degradation products in finished drug products, directly elevating analytical reference standard purchases by generic manufacturers seeking ANDA approvals. EMA's revised impurity guideline (ICH M7(R2)) for DNA reactive substances imposes additional testing burdens on atorvastatin API batches, expanding demand for qualified diepoxide reference materials. India's CDSCO mandates BIS-compliant impurity profiling for domestic generic filings, reinforcing local reference standard sourcing requirements. Stakeholders must monitor evolving pharmacopeial monograph revisions for atorvastatin calcium in USP-NF and EP, as tightened related substance limits will cascade into expanded reference standard procurement volumes and qualification documentation demands.
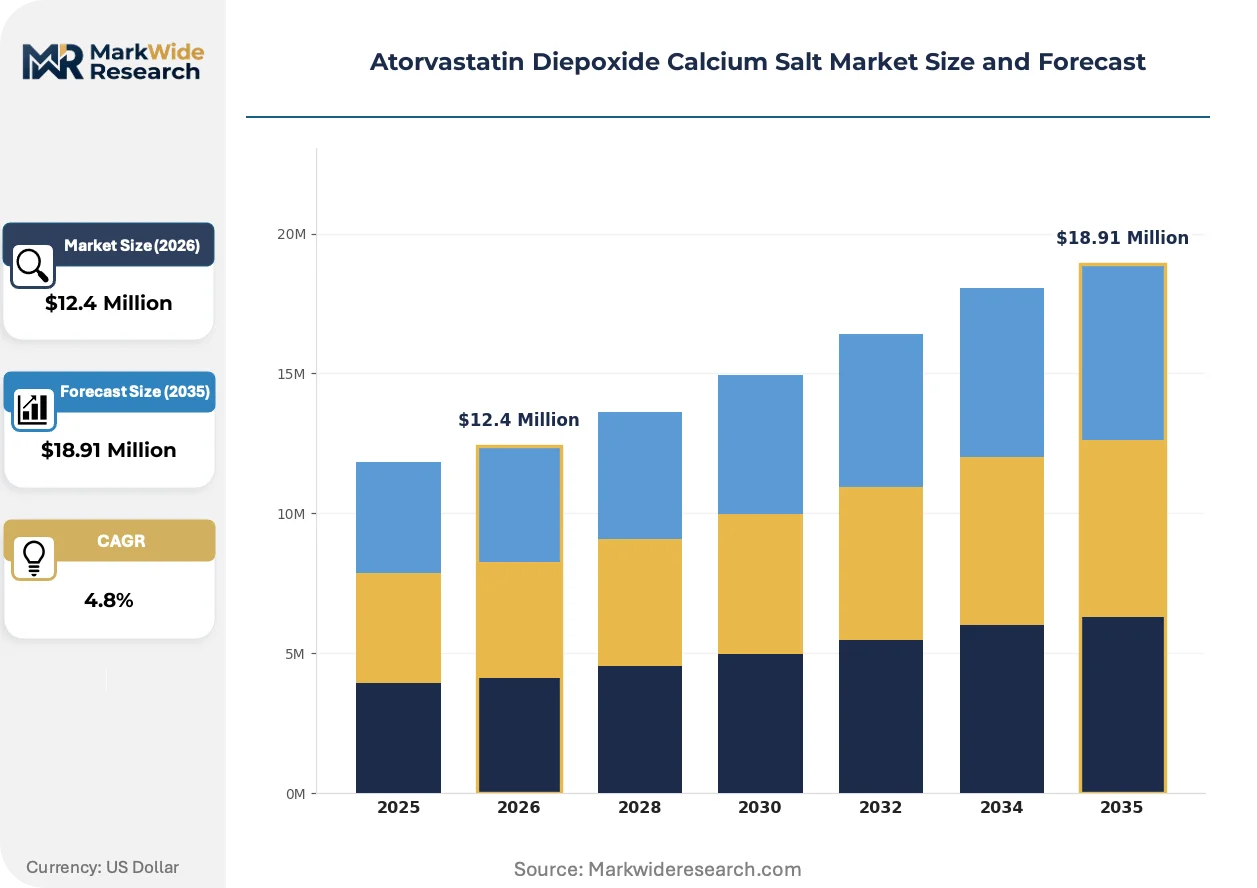
Market Dynamics
ICH Q3A(R2) impurity qualification thresholds are compressing supplier margins as pharmaceutical manufacturers face expanded documentation burdens for ANDA filings and pharmacopeial compliance.
Growth Catalysts
- ANDA filing acceleration:Generic drug manufacturers in India and China are expanding active pharmaceutical ingredient output for statin intermediates to serve North American and European filers.
- EMA impurity guideline revisions:Tightened specifications for related substances in generic atorvastatin are elevating analytical reference standard purchases across European manufacturing networks.
- Cardiovascular therapy persistence:Sustained prescribing of statin therapy for LDL cholesterol management anchors volume demand through hospital procurement channels.
Market Restraints
- Calcium salt input volatility:Fluctuations in pharmaceutical-grade calcium carbonate and acetate sourcing create margin pressure for intermediate manufacturers.
- Indian supplier concentration:Contract manufacturing organizations serving North American and European markets face single-source risk from concentrated API production bases.
- ICH M7(R2) testing burdens:Additional DNA reactive substance testing requirements impose qualification documentation costs that smaller reference standard suppliers cannot absorb.
Strategic Opportunities
- Integrated fermentation-to-synthesis capabilities:European and Asian facilities can capture margin through backward integration into starting material production.
- BIS-compliant impurity profiling mandate:India's CDSCO requirements for domestic generic filings reinforce local reference standard sourcing opportunities.
- Direct hospital contracting:Tender-based volume commitments in cardiovascular therapy procurement create concentrated margin pools bypassing distributor layers.
Industry Challenges
- Analytical method qualification timelines:US FDA enforcement of ICH Q3B(R2) reporting thresholds extends validation cycles for degradation product reference standards.
- Pharmacopeial monograph synchronization:Divergent revision schedules between USP-NF and EP create batch-to-batch specification mismatches for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atorvastatin Diepoxide Calcium Salt Market |
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $18.91 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injection, Oral Suspension, Capsule End User: Hospitals, Pharmacies, Clinics, Homecare Application: Cardiovascular, Diabetes, Obesity, Hypertension Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Cadila Pharmaceuticals, Dr. Reddy's Laboratories, Pfizer, Apotex, Sandoz, DSM Sinochem Pharmaceuticals, Sun Pharmaceutical Industries, Mylan Pharmaceuticals, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atorvastatin Diepoxide Calcium Salt Market Trends and Innovations
Continuous processing technologies and tightened impurity profiling standards are reconfiguring how atorvastatin diepoxide calcium salt is manufactured, tested, and procured across pharmaceutical value chains.
Continuous flow chemistry for epoxide bridge formation is displacing traditional batch reactor approaches in commercial statin synthesis routes. Contract manufacturing organizations serving European generic filers are adopting these systems to reduce solvent volumes and improve particle size distribution control. The technology is displacing legacy batch assets that cannot meet tightened ICH Q3A(R2) specification consistency requirements.
REACH registration requirements for epoxide-containing intermediates are expanding toxicological documentation obligations for suppliers accessing European markets. ECHA substance evaluation protocols now demand enhanced impurity fate-and-transport data for calcium salt complexes used in pharmaceutical manufacturing. API producers are responding by consolidating supplier relationships to reduce qualification audit burdens.
Buyers are unbundling reference standard procurement from bundled API supply agreements to secure dedicated qualification documentation. Hospital procurement channels and generic manufacturers are establishing direct analytical material contracts with certified reference standard producers. This pattern is most visible in North American markets where ANDA reviewers demand supplier-specific chromatographic traceability.
Atorvastatin Diepoxide Calcium Salt Market Segmentation
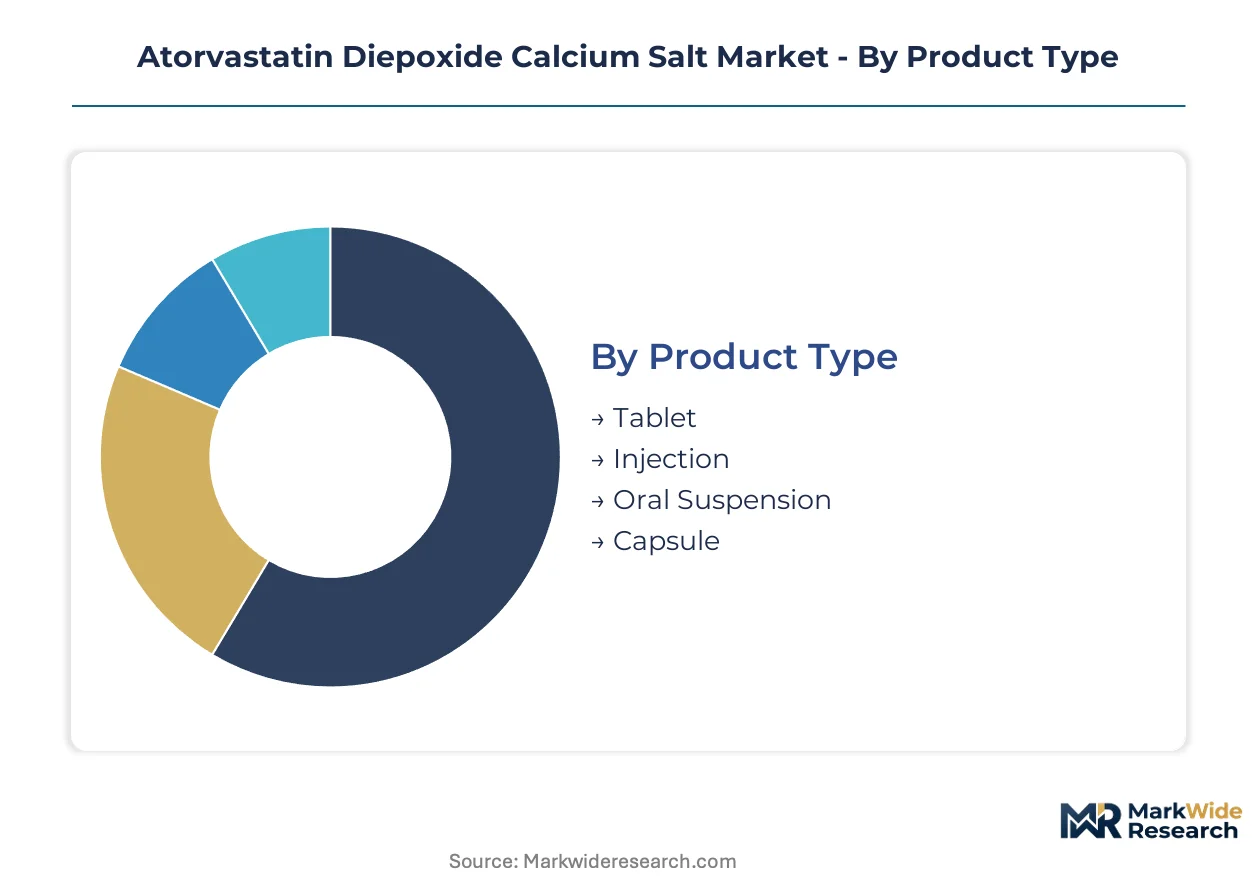
Atorvastatin diepoxide calcium salt demand fragments across formulation types, patient settings, and procurement channels, each governed by distinct impurity thresholds and documentation requirements. Regulatory stringency varies sharply by segment, dictating reference standard qualification depth and supplier selection criteria.
Product Type:
FDA enforces divergent ICH Q3B(R2) reporting thresholds across solid and liquid dosage forms, elevating analytical burden for certain formulations.
- Tablet:Oral solid dosage dominates commercial offtake through direct compression and wet granulation processes. Hospital procurement channels in the United States and Germany concentrate volume for immediate-release and extended-release variants, driven by tender-based cardiovascular therapy contracts and pharmacopeial monograph compliance mandates.
- Injection:Sterile liquid formulations impose stringent endotoxin and particulate specifications beyond standard related substance testing. Parenteral statin applications remain limited to acute coronary syndrome protocols in tertiary care facilities, constrained by stability challenges with epoxide-containing intermediates in aqueous media.
- Oral Suspension:Pediatric and geriatric liquid formulations require particle size distribution control for uniform dosing.
- Capsule:Hard gelatin and HPMC encapsulation serves niche compliance-sensitive patient populations.
Established volume favors Tablet; emerging adoption favors Injection.
End User:
Procurement authority and margin capture concentrate in institutional settings with direct API supplier relationships.
- Hospitals:Centralized pharmacy operations and formulary committees drive bulk purchasing of reference standards for in-house QC laboratories. Tender-based contracting in the United States, Germany, and India creates concentrated demand pools with documented chromatographic traceability requirements.
- Pharmacies:Retail dispensing channels generate fragmented demand for compounding-grade materials and verification standards.
- Clinics:Outpatient cardiovascular practices source limited quantities for point-of-care testing validation.
- Homecare:Patient-directed statin therapy monitoring represents nascent demand for consumer-accessible reference materials.
Procurement scale peaks with Hospitals; patient reach broadens fastest through Pharmacies.
Application:
Therapeutic area penetration correlates with statin prescribing intensity and comorbidity prevalence in aging populations.
- Cardiovascular:LDL cholesterol management anchors absolute demand through sustained primary and secondary prevention protocols. United States and Japanese prescribing guidelines drive reference standard consumption for atorvastatin API batch release testing.
- Diabetes:Dyslipidemia co-management in type 2 diabetes populations expands statin utilization beyond cardiology specialties.
- Obesity:Metabolic syndrome recognition elevates statin therapy in bariatric and endocrine practice settings.
- Hypertension:Combined cardiovascular risk assessment integrates lipid lowering with antihypertensive regimens.
Cardiovascular commands current volume; Diabetes gains share fastest on comorbidity targeting.
Distribution Channel:
Channel selection determines documentation depth, with direct relationships commanding premium positioning.
- Retail:Brick-and-mortar pharmacy supply chains handle finished dosage distribution with limited intermediate material flow.
- Wholesale:Distributor networks consolidate generic manufacturer procurement across North American and European territories.
- Online:Digital procurement platforms emerge for catalog reference standard ordering with electronic qualification documentation.
- Direct Sales:API producers and contract manufacturing organizations bypass intermediaries for high-volume diepoxide calcium salt contracts, securing batch-specific CoA packages and audit trail continuity required by FDA and EMA reviewers.
Wholesale retains volume leadership; Direct Sales climbs fastest on documentation demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturing incentives and impurity testing mandates are redrawing geographic demand patterns for atorvastatin diepoxide calcium salt. National regulators in major API-producing economies enforce divergent qualification standards that shape procurement flows.
United States
FDA's ICH Q3B(R2) enforcement elevates reference standard purchases for ANDA filers. Hospital procurement channels in the Northeast and Midwest concentrate tender-based volume for cardiovascular therapy protocols. New Jersey and Pennsylvania host analytical laboratories serving generic manufacturers with documented chromatographic traceability requirements.
India
CDSCO mandates BIS-compliant impurity profiling for domestic generic filings, reinforcing local reference standard sourcing. Andhra Pradesh and Telangana anchor large-volume API production from contract manufacturing organizations. Hyderabad-based suppliers expand fermentation-to-synthesis capabilities to serve North American and European filers.
Germany
EMA's revised ICH M7(R2) guideline for DNA reactive substances imposes additional testing burdens on API batches. REACH registration requirements for epoxide-containing intermediates expand toxicological documentation obligations. Bavaria and North Rhine-Westphalia concentrate pharmaceutical analytical services for European manufacturing networks.
China
NMPA alignment with ICH quality guidelines accelerates reference standard qualification for export-oriented API producers. Zhejiang and Jiangsu provinces dominate statin intermediate output through integrated chemical synthesis clusters. Shanghai-based contract research organizations support multinational pharmacopeial compliance programs.
Switzerland
Swissmedic enforces stringent pharmacopeial monograph synchronization between USP-NF and EP standards. Basel and Zurich host analytical reference material producers serving premium-tier certification demands. The country's precision chemical sector supplies qualified diepoxide materials for multinational quality control laboratories.
Atorvastatin Diepoxide Calcium Salt Market Competitive Landscape
Listed leaders compete with private specialists across documentation depth and qualification speed. The supplier base organizes into three tiers: integrated pharmaceutical conglomerates with legacy statin process knowledge, mid-scale API specialists with regional certification focus, and dedicated reference standard producers with analytical method superiority. Consolidation pressures favor players with captive fermentation assets and multi-territory regulatory filing experience. Competitive moves center on backward integration into starting material production and direct hospital contracting relationships that bypass distributor markups.
Within the integrated pharmaceutical tier, Pfizer anchors analytical method superiority derived from Lipitor development heritage. Dr. Reddy's Laboratories exemplifies large-volume API production scale from Indian manufacturing bases. DSM Sinochem Pharmaceuticals occupies a position bridging European and Asian facilities through fermentation-to-synthesis integration. These three entities represent distinct competitive archetypes: legacy innovator knowledge, emerging market cost leadership, and geographic arbitrage through multi-continental asset deployment.
| Leading Market Players |
|---|
| Cadila Pharmaceuticals |
| Dr. Reddy's Laboratories |
| Pfizer |
| Apotex |
| Sandoz |
| DSM Sinochem Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Mylan Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for ICH Q3A(R2)-compliant reference standards concentrate purchasing power among hospital procurement channels and large generic filers, compressing margins for smaller analytical suppliers while amplifying price leverage for volume buyers with documented chromatographic traceability requirements.
Pricing Analysis
Certification level (ICH/FDA-grade, EP-compliant, BIS-certified) creates the primary spread across supplier tiers, with qualified reference standards commanding premiums over research-grade materials. Three-tier pricing structure separates pharmacopeial-grade from analytical-grade from compounding-grade offerings, with volume scale and documentation depth as secondary differentiators. Cost compression in the mid-tier intensifies because Indian and Chinese API producers are internalizing reference standard production for captive ANDA filings. Hospital procurement committees demonstrate lowest price sensitivity due to tender-based volume commitments, while independent analytical laboratories face acute margin pressure.
Supply Chain Analysis
Port of Rotterdam customs clearance for epoxide-containing intermediates underwrites European distribution timelines, with delays cascading into batch release testing schedules for generic manufacturers. Supply concentrates in India, China, and Switzerland, with Hyderabad, Zhejiang, and Basel anchoring production clusters for fermentation-derived and synthetic routes. Pharmaceutical-grade calcium carbonate and acetate inputs draw from specialty chemical suppliers in Germany and Japan. Single-source vulnerability persists for ICH M7(R2)-qualified reference standards with complete toxicological documentation. Distribution runs through direct sales channels for high-volume contracts, with wholesale networks handling fragmented laboratory procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atorvastatin diepoxide calcium salt market sits in early-cycle expansion as EMA impurity guideline revisions and FDA ANDA filing acceleration create sustained demand for qualified reference materials with documented chromatographic traceability.
For Market Incumbents: Fortify analytical method superiority through investment in ICH M7(R2) genotoxic impurity testing capabilities, addressing the regulatory shift that threatens legacy reference standard portfolios. Secure backward integration into fermentation-derived starting materials to reduce dependence on Indian calcium salt suppliers facing CDSCO compliance audits. Prioritize direct hospital contracting relationships in Germany and the United States to capture tender-based volume commitments bypassing distributor markups. For New Entrants and Emerging Players: Rapid qualification documentation turnaround—where incumbents average 45-60 days—opens service-layer gaps for agile reference standard producers with dedicated regulatory affairs teams. Target BIS-compliant impurity profiling mandates in India's domestic generic filing segment, the most penetrable geography given CDSCO's enforcement expansion. Pursue digital procurement platform partnerships with catalog ordering and electronic CoA delivery as the primary go-to-market angle against established distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with underutilized analytical services divisions and captive statin process knowledge. The market supports long-term viability framing through sustained cardiovascular therapy prescribing and recurring regulatory compliance cycles. Monitor EMA and FDA pharmacopeial monograph revision schedules as the critical inflection signal for reference standard procurement volume spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | ICH Q3A(R2) qualification accelerates ANDA review timelines for generic filers. |
| Backward Integration | Fermentation-to-synthesis capabilities reduce calcium salt input cost volatility. |
| Manufacturing Scale-Up | Continuous flow chemistry adoption improves particle size distribution control. |
| Long-term Supply Agreement | Direct hospital contracting secures tender-based volume commitments. |
| Strategic Partnership | Digital procurement platform integration enables electronic qualification documentation. |
Research Methodology
Desk research of FDA ANDA filings, EMA impurity guideline revisions, USP-NF and EP pharmacopeial monographs, and Indian CDSCO compliance notifications preceded structured interviews with regulatory affairs leads at generic manufacturers, analytical laboratory directors, hospital procurement managers, and reference standard supplier quality heads. Primary fieldwork combined with secondary validation through trade data and industry association reports. Bottom-up demand modeling and top-down regulatory impact assessment provided cross-verification.
Variance decomposition across formulation type, end-user procurement channel, application area, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions included tablet versus injection dosage forms, hospital versus pharmacy procurement authority, cardiovascular versus diabetes therapeutic application, and direct sales versus wholesale distribution. CAGRs were derived from regression analysis of historical ANDA filing volumes and impurity testing requirement expansions, with inputs from REACH registration timelines and pharmacopeial monograph revision schedules.
Underlying assumptions cover sustained FDA ICH Q3B(R2) enforcement, EMA ICH M7(R2) guideline stability, and Indian CDSCO BIS compliance mandate continuity, with deviation risk concentrated in regulatory harmonization delays or calcium salt supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Tunisia Pharmaceutical Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Global Loperamide Hcl Market