
 Gamma-Hydroxybutyric Acid Market | 2026-2036
Gamma-Hydroxybutyric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Gamma-Hydroxybutyric Acid Market Analytics
Market Context
EMA orphan drug designation protocols is realigning the cost-of-entry calculus for European GHB manufacturers, forcing dedicated facility investments and batch-level traceability systems. BASF SE leverages its Ludwigshafen chemical complex to sustain multi-ton GHB intermediate output for pharmaceutical licensees. Mitsubishi Chemical Corporation anchors Asia-Pacific supply through captive butanediol feedstock integration at its Yokkaichi operations. LyondellBasell Industries competes on propylene oxide route economics, positioning its Rotterdam site as a strategic hub for European GHB precursor distribution.
Technical Definition and Segment Structure
Gamma-hydroxybutyric acid is a four-carbon fatty acid derivative with molecular formula C4H8O3, synthesized industrially via catalytic reduction of gamma-butyrolactone using sodium borohydride or catalytic hydrogenation at 50-80 bar pressure, primarily serving as a Schedule III controlled substance API for narcolepsy therapeutics and alcohol withdrawal protocols. The liquid formulation segment dominates hospital pharmacy procurement due to dose-titration requirements in sodium oxybate therapy, while powder and capsule formats are gaining traction in compounding pharmacy channels where DEA-registered facilities customize patient-specific dosages. Hospital end users command the largest value share through centralized purchasing agreements, though home care delivery models are expanding as risk evaluation and mitigation strategy programs mature and direct-to-patient distribution channels achieve regulatory acceptance.
Regulatory Framework and Outlook
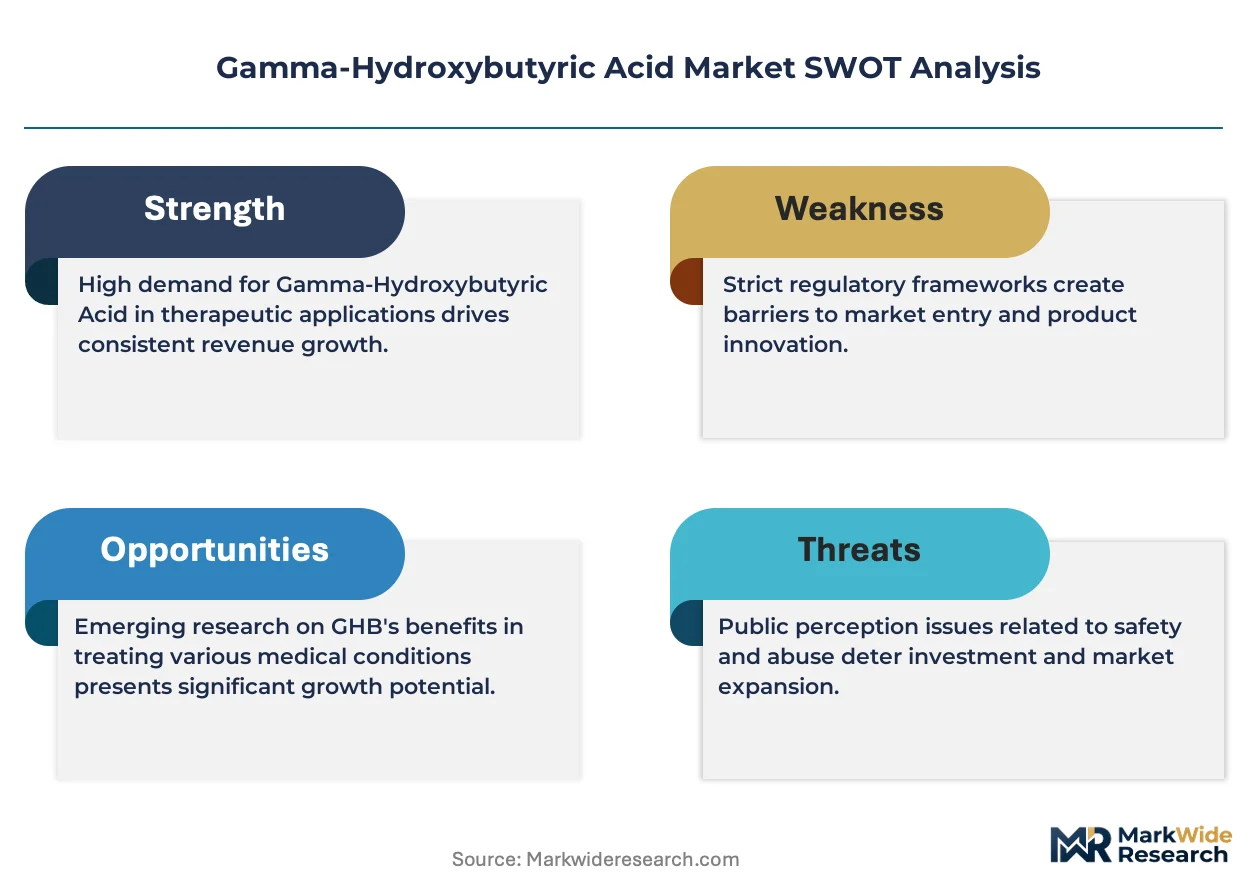
FDA REMS requirements, DEA Schedule III quotas, and EMA Good Manufacturing Practice Annex 1 revisions collectively shape GHB market access, with batch release testing and closed-loop distribution mandates adding compliance costs that favor scaled manufacturers over niche entrants. Health Canada and the UK's MHRA maintain aligned scheduling frameworks that restrict import pathways and require in-country pharmacovigilance reporting. Stakeholders must monitor evolving REMS modification petitions and precursor chemical tracking mandates that will determine which production configurations achieve sustainable operating margins.
Market Dynamics
FDA REMS modifications and EMA Annex 1 revisions are compressing manufacturing economics for GHB producers, forcing dedicated facility investments that favor scaled pharmaceutical contractors over multi-product chemical houses.
Growth Catalysts
- Narcolepsy diagnosis expansion:Sleep medicine specialists in the United States and Germany are broadening screening protocols, pulling more patients into sodium oxybate therapy programs and expanding hospital pharmacy procurement volumes.
- EMA orphan drug incentives:Protocol fee reductions and protocol assistance are lowering regulatory entry costs for European manufacturers seeking to serve specialist sleep clinic networks.
- Catalytic hydrogenation advances:Continuous flow reactor designs are improving gamma-butyrolactone reduction yields, reducing batch failure rates for pharmaceutical-grade GHB synthesis.
Market Restraints
- Butanediol feedstock volatility:Petrochemical derivative pricing swings directly compress margin predictability for GHB intermediate producers dependent on spot market sourcing.
- DEA Schedule III quota allocation:Annual production limits create hard capacity ceilings that prevent demand-responsive scaling regardless of clinical prescription growth.
- Gamma-butyrolactone diversion controls:Precursor chemical tracking mandates in multiple jurisdictions add documentation burden and shipment delay risk to legitimate pharmaceutical supply chains.
Strategic Opportunities
- Home care delivery expansion:Risk evaluation and mitigation strategy program maturation is enabling direct-to-patient distribution models that bypass hospital pharmacy intermediaries.
- Alcohol withdrawal protocol adoption:Addiction medicine specialists are expanding GHB therapeutic use beyond narcolepsy into managed withdrawal settings, creating new prescriber segments.
- Closed-loop distribution technology:Blockchain-enabled batch tracking systems are opening pathways for regulatory acceptance of compounding pharmacy customization at scale.
Industry Challenges
- Pharmacovigilance specialist scarcity:Qualified professionals capable of managing REMS reporting requirements and adverse event documentation are concentrated among a handful of contract research organizations.
- Multi-jurisdiction serialization:Harmonizing track-and-trace data formats across FDA, EMA, and Health Canada requirements demands redundant IT infrastructure investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gamma-Hydroxybutyric Acid Market |
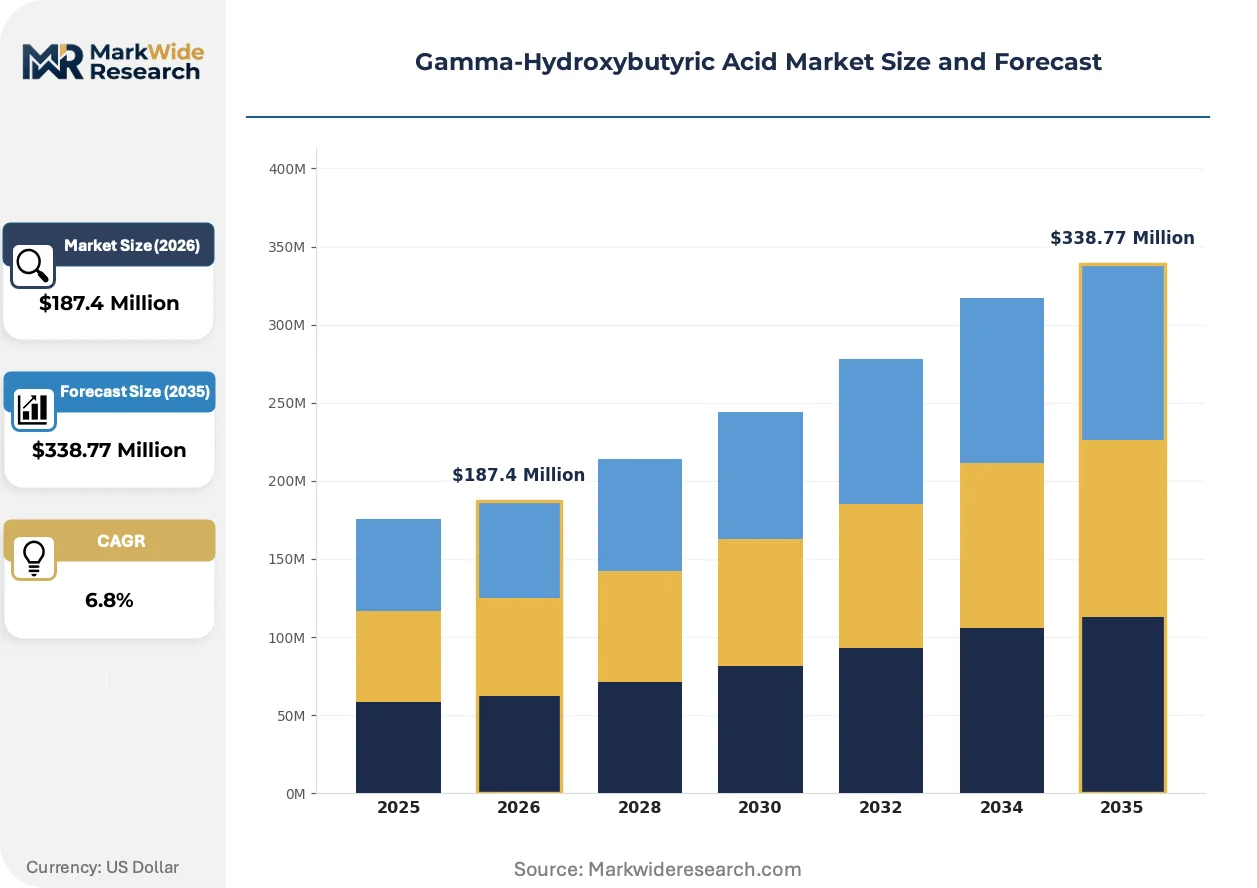
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Capsule Application: Anesthesia, Sleep Disorders, Muscle Relaxant, Alcohol Withdrawal End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Distribution Channel: Online Pharmacy, Retail Pharmacy, Hospital Pharmacy, Direct Sales |
| Companies Covered | BASF SE, LyondellBasell Industries, Mitsubishi Chemical Corporation, Ashland Inc., NNB, Shanghai Kangxin, Anhui Integrity Biopharm, Dairen Chemical Corporation, Sipchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gamma-Hydroxybutyric Acid Market Evolving Landscape
Process analytical technology and closed-system manufacturing are converging to reshape GHB production economics, while distribution models adapt to stricter chain-of-custody requirements.
Continuous manufacturing platforms are integrating real-time mass spectrometry monitoring into gamma-butyrolactone hydrogenation workflows. Pharmaceutical licensees in the United States and Germany are retrofitting batch facilities to hybrid continuous-batch configurations. This technology compression is enabling smaller production footprints with equivalent output, reducing facility capital intensity for entrants.
EMA Annex 1 revisions on sterile product manufacturing are mandating isolator-based filling lines for liquid GHB formulations. European contract manufacturers are absorbing seven-figure retrofit costs to maintain batch release eligibility. Specialist sleep clinic procurement in France and Italy is consolidating toward suppliers with certified isolator capacity, squeezing regional compounders.
Hospital pharmacy buyers are consolidating sodium oxybate purchasing through centralized agreements with integrated distribution networks. Direct-to-patient delivery is displacing traditional wholesale channels in markets with mature REMS infrastructure. This channel compression is most visible in the United States, where specialty pharmacy networks now handle the majority of dispensed volume.
Gamma-Hydroxybutyric Acid Market Segmentation
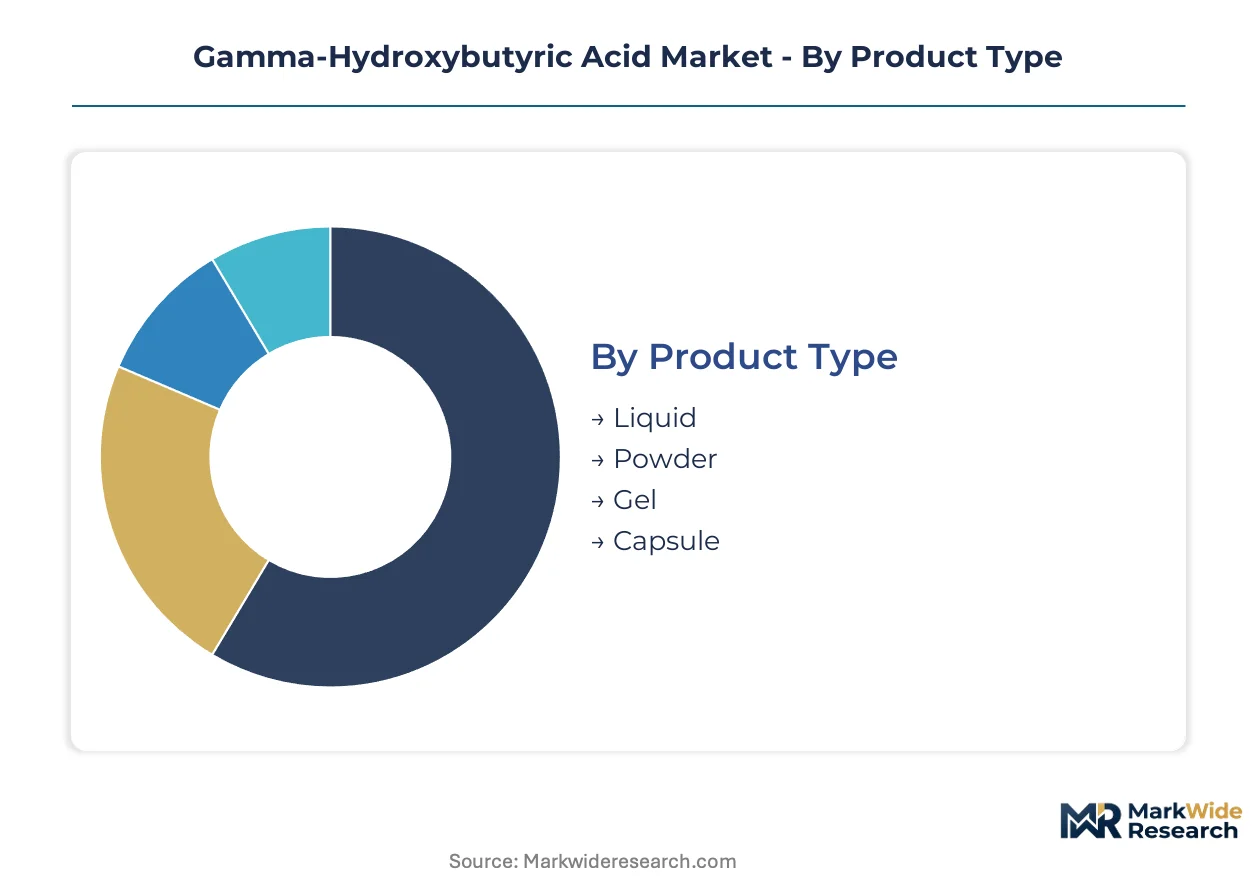
GHB market segmentation reflects divergent compliance burdens across pharmaceutical formats and distribution pathways. FDA REMS and EMA Annex 1 requirements create tiered certification costs that reshape competitive positioning within each category.
Product Type:
Liquid formulations carry the heaviest GMP certification load, requiring isolator-based filling lines and batch-level sterility assurance. Powder and gel formats face reduced documentation intensity but divergent precursor chemical tracking mandates.
- Liquid:Sodium oxybate oral solutions demand closed-system manufacturing with real-time mass spectrometry monitoring. Hospital pharmacy procurement in the United States concentrates here due to dose-titration protocols in narcolepsy therapy. FDA REMS requirements add seven-figure compliance costs that filter out small-scale compounders.
- Powder:Bulk API for compounding pharmacy channels requires DEA-registered facility status and gamma-butyrolactone diversion controls. European specialist sleep clinics in Germany and France source powder for patient-specific dosage preparation. EMA orphan drug batch traceability mandates favor suppliers with integrated serialization infrastructure.
- Gel:Transdermal delivery formats absorb lower regulatory scrutiny in cosmetic-adjacent applications but face emerging pharmacovigilance reporting requirements in therapeutic contexts.
- Capsule:Solid oral dosage forms enable home care distribution models with simplified cold-chain logistics. Direct-to-patient channels in markets with mature REMS infrastructure favor capsule formats for alcohol withdrawal protocols.
Liquid sits at the top of the volume ranking, with capsule climbing the fastest.
Application:
Clinical indication determines prescriber specialization depth and reimbursement pathway complexity. Sleep disorder protocols command premium pricing through orphan drug designation, while anesthesia applications compete on procurement contract scale.
- Sleep Disorders:Narcolepsy with cataplexy represents the anchor indication for sodium oxybate therapy. Sleep medicine specialists in the United States and Germany drive prescription volume through broadened screening protocols. FDA REMS risk evaluation programs restrict dispensing to certified pharmacies.
- Alcohol Withdrawal:Addiction medicine specialists are expanding GHB therapeutic use beyond traditional narcolepsy boundaries. Managed withdrawal settings in European rehabilitation networks create new prescriber segments with distinct procurement patterns. EMA protocol assistance lowers regulatory entry costs for indication expansion filings.
- Anesthesia:Perioperative applications compete on hospital formulary inclusion and group purchasing organization contract terms. Volume concentrates in tertiary surgical centers with centralized pharmacy operations.
- Muscle Relaxant:Off-label utilization in spasticity management faces reimbursement friction and pharmacovigilance scrutiny that limit commercial scale.
Sleep disorders anchor current revenue concentration, with alcohol withdrawal gaining share fastest.
End User:
Customer type shapes distribution infrastructure requirements and chain-of-custody documentation intensity. Hospital systems demand redundant supplier qualification, while home care channels prioritize patient compliance monitoring technology.
- Hospitals:Centralized purchasing agreements dominate sodium oxybate procurement in the United States. Pharmacy and therapeutics committees enforce dual-source requirements that fragment volume across qualified suppliers. DEA Schedule III quota allocation creates hard capacity ceilings regardless of prescription growth.
- Home Care:Direct-to-patient delivery models bypass traditional wholesale channels where REMS infrastructure matures. Specialty pharmacy networks handle dispensed volume with integrated compliance monitoring. Patient-specific dosing regimens favor liquid formulations with titration flexibility.
- Clinics:Specialist sleep clinic networks in France and Italy consolidate procurement toward suppliers with certified isolator capacity. Outpatient settings require streamlined adverse event reporting workflows.
- Rehabilitation Centers:Addiction treatment facilities face distinct diversion control requirements and staff training mandates for controlled substance handling.
Hospitals retain volume leadership, with home care expanding most quickly.
Distribution Channel:
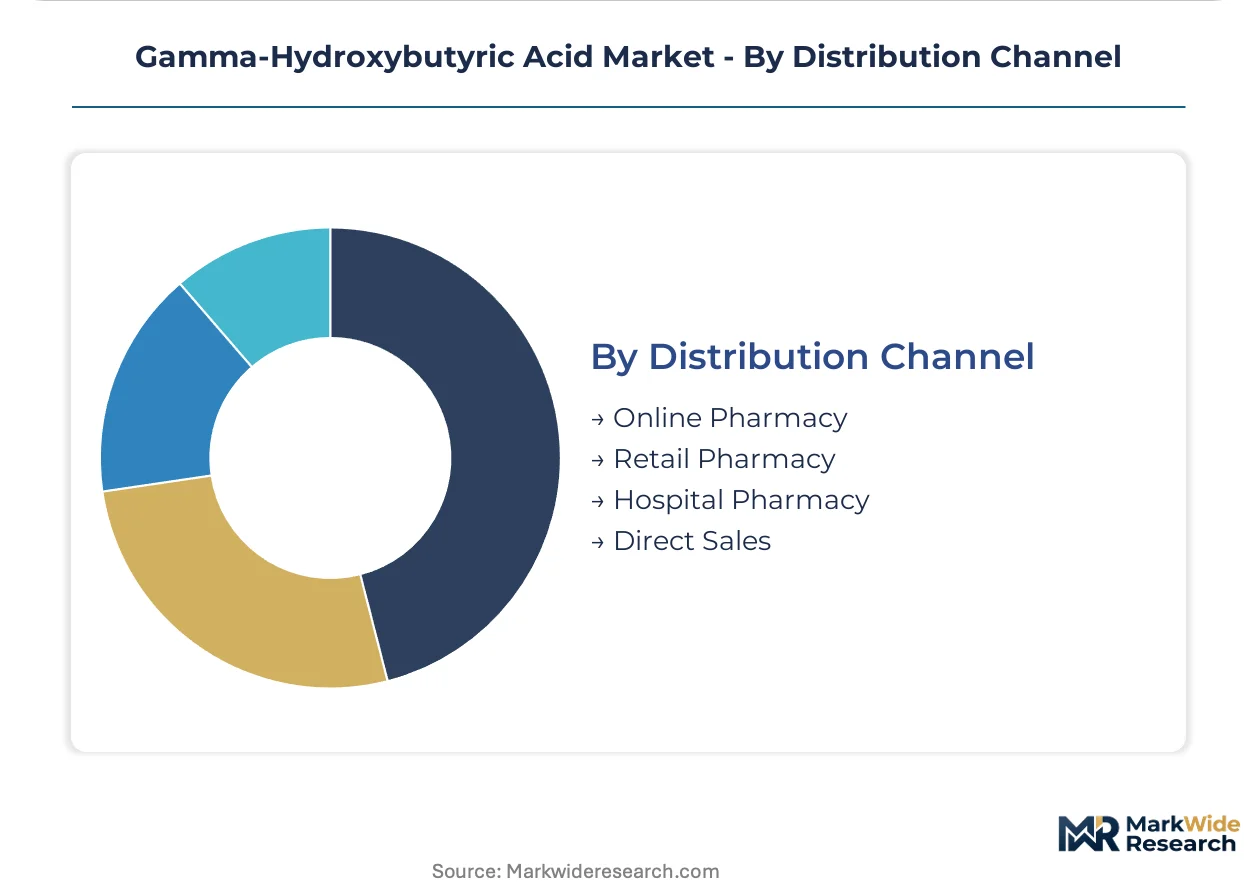
Channel selection determines serialization infrastructure investment and cross-border shipment complexity. Hospital pharmacy intermediaries absorb regulatory compliance costs that direct sales models transfer to manufacturers.
- Hospital Pharmacy:Integrated distribution networks consolidate sodium oxybate purchasing through centralized agreements. Closed-loop distribution mandates favor established logistics providers with track-and-trace capability. Batch release testing requirements add per-shipment documentation burden.
- Direct Sales:Manufacturer-to-patient models eliminate wholesale markups but require in-house REMS program administration. United States specialty pharmacy networks now handle majority dispensed volume through this channel. Blockchain-enabled batch tracking systems open pathways for regulatory acceptance at scale.
- Retail Pharmacy:Community pharmacy participation remains limited by DEA registration requirements and staff training costs for Schedule III controlled substances.
- Online Pharmacy:Digital channels face heightened diversion risk scrutiny and prescription verification complexity that restrict legitimate pharmaceutical utilization.
Hospital pharmacy dominates current throughput, with direct sales capturing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sleep medicine specialists and DEA-registered pharmacologists concentrate in the United States and Germany, anchoring the clinical infrastructure that drives GHB procurement decisions. Regulatory expertise clusters around FDA REMS program administrators in Boston and EMA orphan drug protocol specialists in Amsterdam. Manufacturing competence pools near petrochemical feedstock hubs in Ludwigshafen, Rotterdam, and Yokkaichi.
United States
Sodium oxybate therapy expansion through broadened narcolepsy screening protocols drives hospital pharmacy procurement volumes. FDA REMS risk evaluation and mitigation strategy programs restrict dispensing to certified specialty pharmacy networks. The Greater Boston corridor hosts concentrated sleep medicine research institutions that shape prescriber education and therapeutic guidelines.
Germany
Specialist sleep clinic networks in Munich and Hamburg consolidate procurement toward suppliers with certified isolator capacity. EMA orphan drug designation protocols reduce regulatory entry costs for domestic manufacturers serving European markets. The Ludwigshafen chemical complex sustains multi-ton GHB intermediate output through captive butanediol feedstock integration.
Japan
PMDA scheduling frameworks align with international controlled substance protocols while maintaining distinct pharmacovigilance reporting requirements. Mitsubishi Chemical Corporation anchors regional supply through Yokkaichi operations with backward integration into butanediol production. Tokyo-based sleep disorder research centers drive clinical trial recruitment for indication expansion studies.
Netherlands
Rotterdam petrochemical infrastructure positions the port region as a strategic hub for European GHB precursor distribution. REACH chemical registration requirements and EMA Annex 1 sterile manufacturing standards filter supplier qualification. The Amsterdam-Utrecht corridor concentrates pharmaceutical logistics providers with track-and-trace serialization capability.
China
NMPA controlled substance scheduling creates parallel regulatory pathways for domestic and export-oriented GHB production. Shanghai Kangxin and Anhui Integrity Biopharm exemplify regional manufacturers navigating precursor chemical tracking mandates. The Yangtze River Delta chemical cluster supplies gamma-butyrolactone reduction capacity to pharmaceutical licensees worldwide.
Gamma-Hydroxybutyric Acid Market Competitive Landscape
The competitive structure tilts toward petrochemical conglomerates with captive feedstock positions. BASF SE, LyondellBasell Industries, and Mitsubishi Chemical Corporation dominate intermediate supply through multi-ton chemical complex operations. Three archetypes populate the landscape: integrated petrochemical majors controlling butanediol-to-GHB conversion, pharmaceutical-grade specialists serving DEA-registered facilities, and regional compounders targeting compounding pharmacy channels. Capacity expansion and strategic licensing agreements represent the dominant competitive moves, with manufacturers retrofitting batch facilities to hybrid continuous configurations.
Among German-based chemical conglomerates, BASF SE exemplifies the integrated petrochemical archetype through its Ludwigshafen operations. LyondellBasell Industries represents the transatlantic feedstock optimizer, positioning Rotterdam as a European distribution hub. Mitsubishi Chemical Corporation anchors the Asia-Pacific supply vector through Yokkaichi butanediol integration. These three entities collectively shape intermediate pricing and batch availability for pharmaceutical licensees navigating DEA Schedule III quota constraints.
| Leading Market Players |
|---|
| BASF SE |
| LyondellBasell Industries |
| Mitsubishi Chemical Corporation |
| Ashland Inc. |
| NNB |
| Shanghai Kangxin |
| Anhui Integrity Biopharm |
| Dairen Chemical Corporation |
| Sipchem |
| Others |
Value Network & Pricing Analysis
EMA Annex 1 sterile manufacturing revisions gate qualified supply for liquid GHB formulations while simultaneously filtering premium-tier pricing access to isolator-certified European contractors. Hospital pharmacy buyers in Germany and France absorb seven-figure facility retrofit costs through long-term offtake premiums, creating bifurcated procurement economics between certified and uncertified supply tiers.
Pricing Analysis
Bundled isolator-based filling services command 40-60% premiums over unbundled powder API supply due to batch-level sterility assurance and EMA release documentation. Price differentiation hinges on FDA REMS program participation and DEA Schedule III quota holding status. Cost compression in standard-grade powder supply is intensifying because of gamma-butyrolactone feedstock volatility. Compounding pharmacy channels exhibit highest price sensitivity; hospital systems with centralized purchasing agreements demonstrate lowest sensitivity due to risk-mitigation prioritization.
Supply Chain Analysis
Dual-sourcing requirements from hospital pharmacy and therapeutics committees fragment volume across qualified suppliers regardless of unit economics. Manufacturing concentrates in Germany, the United States, and Japan through Ludwigshafen, Boston-corridor, and Yokkaichi chemical complexes. The supply chain draws from captive butanediol feedstock, sodium borohydride reduction agents, and hydrogenation catalysts. Single-source vulnerability persists around DEA quota allocation ceilings. Distribution runs through integrated specialty pharmacy networks with closed-loop tracking infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States REMS infrastructure maturity and European EMA orphan drug fee reductions, with regulatory compliance cost differentials exceeding manufacturing margin spreads.
For Market Incumbents: Hedge DEA Schedule III quota constraints through backward integration into butanediol feedstock production at Rotterdam or Ludwigshafen. Diversify revenue concentration beyond sodium oxybate narcolepsy monotherapy into alcohol withdrawal protocols to offset prescription volume ceilings. Certification investment in continuous flow reactor technology preserves margin position against batch facility competitors.
For New Entrants and Emerging Players: Continuous manufacturing technology-first wedge opens compounding pharmacy channels where DEA registration barriers filter legacy competitors. Target European specialist sleep clinic networks in France and Italy with isolator-certified powder supply. Pursue white-label manufacturing partnerships with established REMS program administrators as the fastest go-to-market pathway.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders lacking EMA Annex 1 certification but possessing DEA-registered facility infrastructure. Long-term viability over a five-to-ten year horizon rests on REMS program administration capabilities rather than chemical synthesis scale. Monitor FDA modification petitions to REMS protocols as the primary inflection signal for distribution model profitability shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Filling Line Retrofit | EMA Annex 1 compliance enables European hospital pharmacy procurement from certified facilities. |
| Continuous Flow Reactor Deployment | Real-time mass spectrometry integration reduces batch failure rates for pharmaceutical-grade synthesis. |
| REMS Program Administration Partnership | FDA risk evaluation infrastructure unlocks direct-to-patient distribution channel access. |
| Backward Integration into Butanediol | Captive feedstock supply insulates margin predictability from petrochemical derivative spot volatility. |
| Alcohol Withdrawal Indication Expansion | EMA protocol assistance lowers regulatory entry costs for addiction medicine prescriber segments. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with sleep medicine specialists, hospital pharmacy procurement managers, DEA-registered facility operators, and regulatory affairs directors informed demand-side dynamics. Secondary sources include FDA REMS program filings, EMA orphan drug designation records, ClinicalTrials.gov protocol databases, and customs trade data on gamma-butyrolactone shipments. Bottom-up prescription volume modeling and top-down chemical intermediate production estimates were triangulated.
Granularity-level modeling addressed product type, application indication, end-user category, and distribution channel across the projection horizon. Sleep disorder versus alcohol withdrawal therapeutic use, liquid versus powder formulation demand, and hospital pharmacy versus direct-to-patient channel splits were explicitly parameterized. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion constraints. Forecast inputs incorporated DEA quota allocation trajectories and EMA Annex 1 implementation timelines.
The model holds under stable regulatory scheduling frameworks; deviation in FDA REMS modification timing or DEA production quota expansion would shift volume and value outlooks materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Global Immuno Oncology Drugs Market
Pharmaceuticals
Varicella Attenuated Live Vaccination Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Attenuated Vaccines Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Diuretic Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Fertility Drug and Surgery Market