
 Acute Repetitive Seizures Market | 2026-2036
Acute Repetitive Seizures Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Repetitive Seizures Market Analysis
Asset-light licensing partnerships between specialty pharmaceutical firms and contract development organizations is reconfiguring competitive entry barriers for rescue therapy developers. Neurelis leverages intranasal delivery expertise to differentiate its commercial approach in acute seizure management. UCB S.A. anchors European market presence through deep neurology franchise integration. Pfizer sustains manufacturing scale advantages that support reliable supply of parenteral rescue formulations.
Acute repetitive seizures constitute a neurological emergency defined by two or more seizures occurring within 24 hours without full recovery of consciousness between events, requiring immediate pharmacological intervention to prevent status epilepticus and neuronal injury. Rescue therapies dominate clinical preference for outpatient and emergency settings where rapid termination of seizure activity is critical. Injectable medications, particularly intramuscular and intravenous formulations, command the largest revenue share due to hospital-centric purchasing patterns and established reimbursement codes. Oral rescue medications represent the fastest-expanding segment as home healthcare protocols expand patient self-administration capabilities outside institutional settings.
FDA breakthrough therapy and fast track designations shape product development timelines and prescriber awareness for novel rescue formulations. The EMA's centralized marketing authorization procedure governs commercial access across European Union member states, while the EU AI Act introduces compliance considerations for algorithmic diagnostic tools that may guide seizure detection and treatment selection. Stakeholders must monitor evolving home healthcare reimbursement policies and emergency medical services formulary decisions that will determine whether community-based administration models achieve parity with hospital-based rescue protocols.
Market Dynamics
Hospital emergency departments are consolidating seizure rescue protocols around intranasal and intramuscular alternatives to intravenous administration, compressing the window for therapeutic intervention and reshaping procurement priorities across acute care networks.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Expedited review timelines accelerate commercialization for novel rescue formulations targeting status epilepticus prevention.
- Home Healthcare Infrastructure:Community-based administration models expand patient self-management capabilities outside institutional settings.
- Epilepsy Center Networks:Specialized referral systems concentrate diagnostic expertise and standardize rescue medication protocols across United States metropolitan clusters.
Market Restraints
- Parenteral Manufacturing Concentration:Reliable supply of injectable rescue formulations depends on a limited base of FDA-inspected sterile facilities.
- Reimbursement Code Fragmentation:Emergency medical services formularies maintain divergent coverage policies for prehospital seizure rescue.
- Specialized Neurology Training Gaps:Community hospitals face shortages of epileptologists capable of protocol design for acute repetitive seizure management.
Strategic Opportunities
- Pediatric Formulation Gaps:Weight-based dosing innovations for rescue medications address an underserved population segment.
- Prehospital Administration Expansion:Emergency medical services represent a channel innovation opportunity for intranasal delivery systems.
- Algorithmic Seizure Detection:Wearable device integration with rescue therapy protocols creates technology convergence potential.
Industry Challenges
- Pharmacovigilance Infrastructure:Post-market surveillance for rescue medications requires specialized adverse event reporting systems.
- Cold Chain Integrity:Temperature-sensitive biologic formulations demand capital-intensive distribution network upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Repetitive Seizures Market |
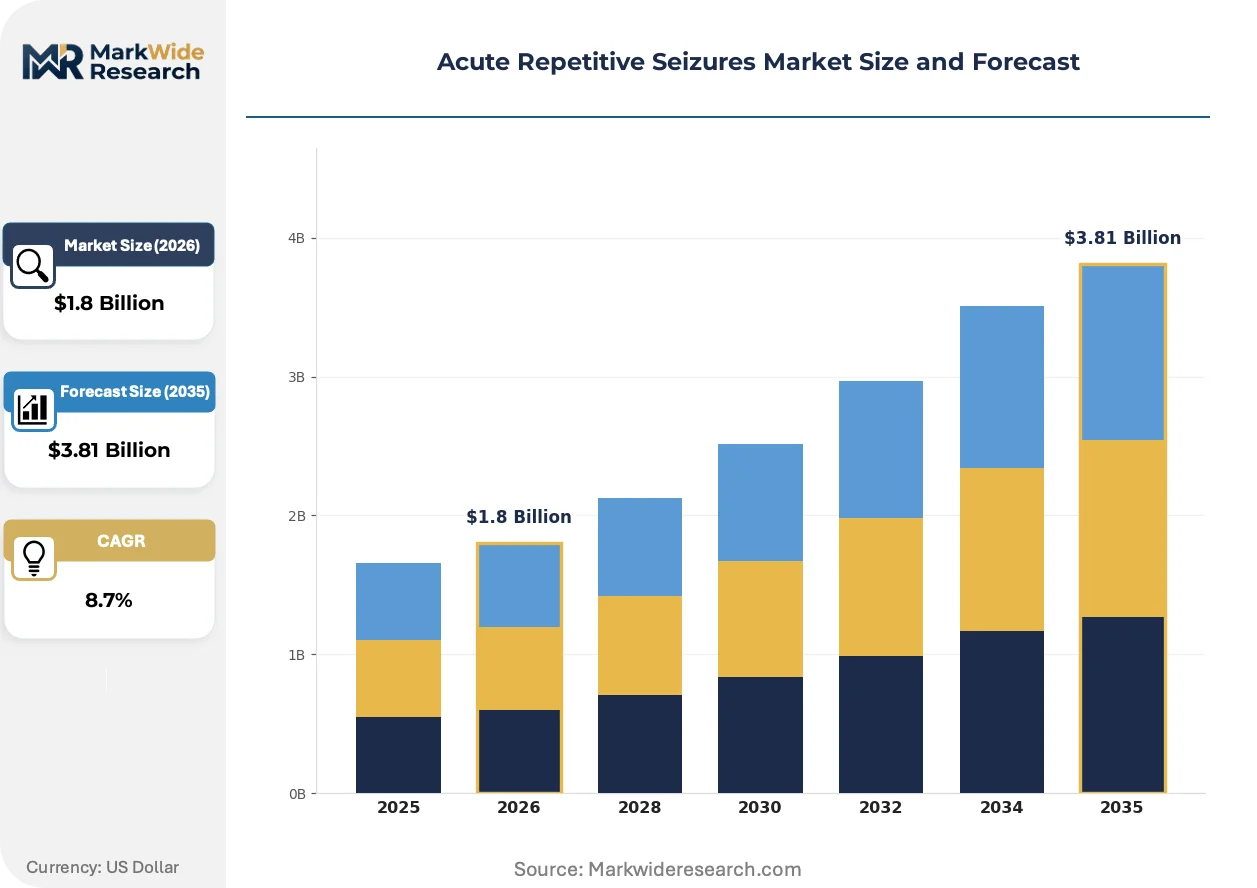
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiepileptic Drugs, Injectable Medications, Oral Medications, Rescue Therapies Therapy Area: Neurology, Epilepsy Management, Emergency Care, Patient Support Delivery Mode: Intravenous, Intramuscular, Oral, Subcutaneous End User: Hospitals, Clinics, Home Healthcare, Emergency Services |
| Companies Covered | Neurelis, UCB S.A., Bausch Health Companies, Pfizer, Sanofi, Aquestive Therapeutics, Veriton Pharma, Eisai Co. Ltd., Alexza Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Repetitive Seizures Market Emerging Trajectories
Intranasal delivery platforms are compressing the therapeutic response window for seizure rescue, while regulatory pathways and reimbursement structures scramble to accommodate administration outside traditional clinical settings.
Benzodiazepine intranasal formulations deliver rapid CNS penetration without vascular access requirements. Emergency departments and epilepsy centers are adopting these systems for outpatient seizure clusters. This modality is rendering obsolete the primacy of intravenous lorazepam in first-line rescue protocols.
The FDA's breakthrough therapy designation creates truncated development timelines for novel rescue mechanisms. Drug developers gain accelerated approval pathways and enhanced prescriber engagement. Neurology franchises are restructuring clinical trial investments around this regulatory channel.
Patient and caregiver self-administration protocols are displacing hospital-centric rescue models. Home healthcare agencies and epilepsy foundations are training non-clinical caregivers in seizure recognition and medication delivery. This behavioral shift concentrates in United States markets with established specialty pharmacy networks.
Acute Repetitive Seizures Market Segmentation
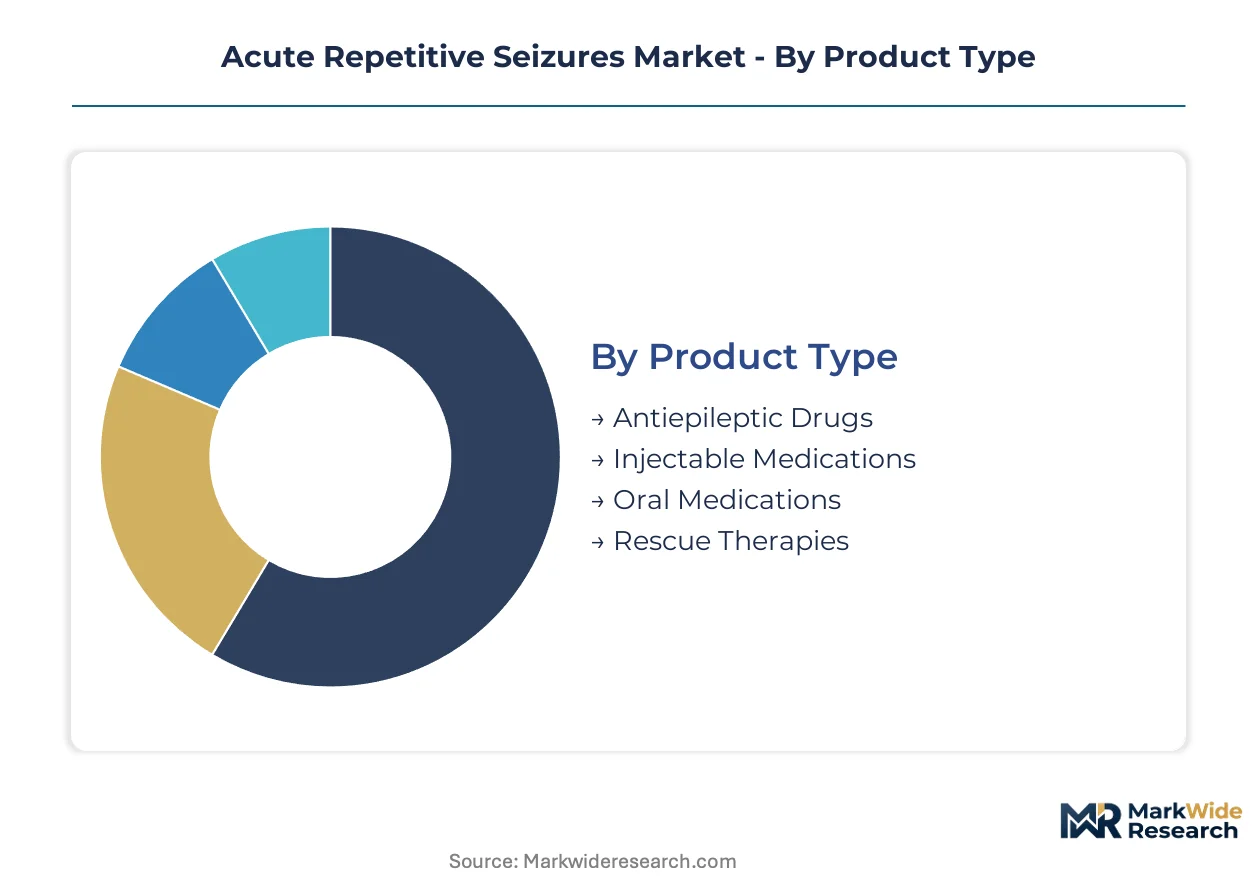
Segmentation in acute repetitive seizures treatment reveals how clinical settings, administration constraints, and patient acuity reshape procurement patterns across rescue therapy categories. Understanding these divisions exposes where formulation innovation and distribution investment will yield competitive advantage.
Product Type:
Rescue formulations span the emergency intervention spectrum from hospital-controlled injectables to patient-administered alternatives.
- Injectable Medications:Intramuscular and intravenous benzodiazepine formulations deliver rapid CNS penetration for status epilepticus prevention. Hospital emergency departments in the United States concentrate procurement volume here due to established reimbursement codes and protocol familiarity.
- Rescue Therapies:Intranasal and buccal formulations enable non-clinical administration outside institutional settings. Home healthcare networks in metropolitan clusters are expanding patient self-management capabilities through caregiver training programs.
- Antiepileptic Drugs:Maintenance medications prevent seizure recurrence but require therapeutic drug monitoring.
- Oral Medications:Tablet and liquid formulations serve stable patients with predictable absorption profiles.
The dominant share belongs to Injectable Medications, while Rescue Therapies are gaining share fastest as community-based protocols mature.
Therapy Area:
Clinical specialization tiers separate acute intervention from longitudinal disease management.
- Emergency Care:Protocol-driven rescue interventions in acute settings prioritize seizure termination speed and airway protection. United States epilepsy center networks standardize these workflows across affiliated hospital systems.
- Epilepsy Management:Comprehensive care coordination spans diagnostic workup, medication optimization, and surgical evaluation. Academic medical centers anchor referral volume for complex case triage.
- Neurology:Broad diagnostic and therapeutic services address seizure mimics and comorbid conditions.
- Patient Support:Education and adherence programs reduce breakthrough seizure frequency.
Emergency Care commands institutional spending priority, though Epilepsy Management captures the steepest expansion trajectory through integrated care models.
Delivery Mode:
Route selection hinges on vascular access availability, caregiver training, and therapeutic onset requirements.
- Intravenous:Direct vascular administration achieves the most rapid CNS drug levels for refractory cases. Hospital-based purchasing dominates despite vascular access complications.
- Intramuscular:Depot absorption through skeletal muscle provides reliable bioavailability without IV placement. Prehospital emergency medical services in the United States are expanding formulary inclusion.
- Oral:Gastrointestinal absorption suits stable patients with intact protective reflexes.
- Subcutaneous:Interstitial administration offers alternative non-vascular delivery for select formulations.
Intravenous retains protocol primacy in hospitals, yet Intramuscular is climbing fastest as emergency medical services broaden access.
End User:
Care setting fragmentation drives divergent packaging, training, and reimbursement requirements.
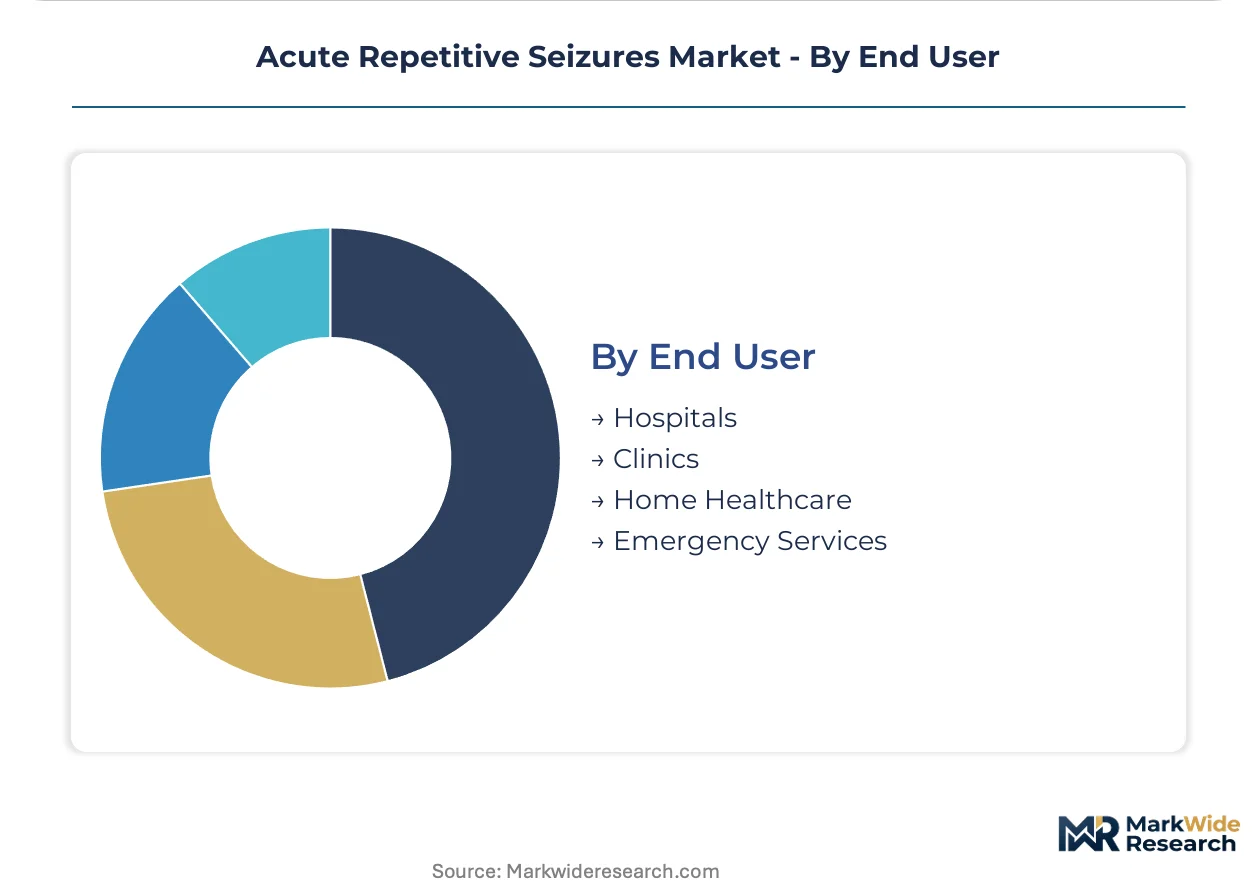
- Hospitals:Inpatient and emergency department settings concentrate high-acuity rescue volume with 24-hour pharmacy coverage. Sterile compounding capabilities and code team infrastructure support complex protocols.
- Home Healthcare:Community-based administration shifts seizure management outside institutional walls. Specialty pharmacy networks in the United States are building caregiver certification programs for intranasal delivery.
- Clinics:Outpatient neurology practices manage medication adjustments and rescue prescription refills.
- Emergency Services:Ambulance and first-responder deployment extends intervention windows before hospital arrival.
Hospitals anchor revenue concentration, while Home Healthcare shows the most rapid share expansion as self-administration protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmacy reimbursement policies and epilepsy center accreditation standards are redistributing acute repetitive seizures treatment capacity across national healthcare systems. FDA breakthrough therapy designations in the United States accelerate commercialization timelines that competitors elsewhere must match through parallel regulatory pathways.
United States
Epilepsy center networks in metropolitan clusters concentrate diagnostic expertise and standardize rescue medication protocols. The FDA's breakthrough therapy pathway truncates development timelines for intranasal benzodiazepine formulations. Home healthcare agencies in Boston and San Francisco are building caregiver certification programs for community-based seizure rescue.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor referral volume for complex case triage. The EMA's centralized marketing authorization procedure governs commercial access across EU member states. Berlin-based neurology franchises are integrating rescue protocols with wearable seizure detection systems.
Japan
PMDA regulatory frameworks accommodate novel delivery mechanisms for rescue therapies through conditional early approval pathways. METI industrial policy supports pharmaceutical manufacturing infrastructure for temperature-sensitive biologic formulations. Osaka pharmaceutical clusters are developing pediatric weight-based dosing innovations.
United Kingdom
NHS specialized commissioning frameworks concentrate acute seizure management within designated epilepsy centers. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for breakthrough rescue medications. London teaching hospitals are piloting prehospital emergency medical services formulary integration for intranasal delivery.
France
ANSM pharmacovigilance infrastructure requires specialized adverse event reporting systems for rescue medications. The country's national pharmaceutical regulator maintains stringent cold chain integrity standards for temperature-sensitive formulations. Paris-region academic hospitals are restructuring clinical trial investments around expedited approval channels.
Acute Repetitive Seizures Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Hospital emergency departments and home healthcare networks maintain divergent formulary preferences that prevent single-dominant positioning. Three archetypes populate this structure: neurology-integrated pharmaceutical conglomerates, intranasal delivery technology specialists, and contract manufacturing-dependent licensing firms. Strategic partnerships and portfolio diversification constitute the dominant competitive moves as developers seek manufacturing scale and regulatory expertise.
Within the intranasal delivery specialist tier, Neurelis exemplifies product-differentiation positioning through formulation expertise. UCB S.A. and Pfizer occupy positions reflecting deep neurology franchise integration and manufacturing scale advantages respectively. These three anchors represent contrasting pathways to market presence: technology-led differentiation, therapeutic area concentration, and supply chain reliability.
| Leading Market Players |
|---|
| Neurelis |
| UCB S.A. |
| Bausch Health Companies |
| Pfizer |
| Sanofi |
| Aquestive Therapeutics |
| Veriton Pharma |
| Eisai Co. Ltd. |
| Alexza Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
New Jersey's concentration of FDA-inspected sterile manufacturing facilities anchors injectable rescue therapy production, with capacity utilization rates directly transmitting into hospital procurement leverage and parenteral formulation premiums.
Pricing Analysis
Certification level creates the primary spread across rescue therapy tiers, with FDA-breakthrough-designated intranasal formulations commanding premium positioning against standard generic injectables. Three-tier pricing structure across premium, standard, and economy levels reflects GMP compliance grade, cold chain infrastructure investment, and prescriber training bundling. Cost compression in standard injectables is intensifying because hospital GPOs are consolidating formulary decisions around limited supplier panels. Community hospitals exhibit highest price sensitivity due to constrained pharmacy budgets, while academic epilepsy centers prioritize clinical outcome metrics over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for contract manufacturing organizations serving rescue therapy developers, with supply-chain finance facilities bridging working capital gaps for mid-tier formulation specialists. Manufacturing capacity concentrates in the United States, Ireland, and Switzerland for sterile parenteral production, while active pharmaceutical ingredient synthesis draws from India and China. Supply chain risk centers on single-source vulnerability for temperature-sensitive biologic formulations requiring validated cold chain distribution. Distribution runs through specialty pharmacy networks with direct-to-patient shipping capabilities for home healthcare administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caregiver certification programs and remote patient monitoring subscriptions represent the fastest-expanding recurring-revenue layer, outpacing hardware growth as epilepsy foundations and home healthcare agencies build training infrastructure for community-based seizure rescue.
For Market Incumbents: Harden formulary control through exclusive epilepsy center network partnerships that embed rescue protocols into electronic health record order sets. Deepen backward integration into intranasal device manufacturing to offset API cost volatility from Indian and Chinese suppliers. Defensive positioning must address emerging intranasal delivery specialists threatening hospital channel primacy. For New Entrants and Emerging Players: Build out pediatric weight-based dosing formulations as the most penetrable white space, with prehospital emergency medical services representing the adjacent expansion corridor. Target metropolitan clusters with established specialty pharmacy infrastructure for pilot caregiver training programs. A go-to-market angle anchored to wearable seizure detection integration bypasses incumbent hospital formulary gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because rescue therapy adoption is tethered to home healthcare network density rather than episodic hospital purchasing. Acquisition targets should display intranasal formulation expertise paired with FDA breakthrough therapy designation navigation capabilities. The signal to watch is CMS reimbursement code expansion for community-based administration, which would validate the shift from institutional to patient-centric models.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Navigation | Truncated approval timelines compress competitive entry windows for intranasal rescue formulations. |
| Specialty Pharmacy Network Partnership | Direct-to-patient distribution bypasses hospital formulary committees for home healthcare expansion. |
| Pediatric Formulation Development | Weight-based dosing innovations address underserved population segments with limited competition. |
| Wearable Device Integration | Algorithmic seizure detection creates technology convergence potential for automated rescue triggers. |
| Caregiver Certification Program Buildout | Epilepsy foundation partnerships establish non-clinical administration training infrastructure. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists converged on the working assumptions driving this analysis. Primary interviews across these stakeholder categories were cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimates across the analysis window.
Demand-supply balance dynamics shaped the forecast framework, with segmentation across administration route, care setting, patient population, and regional regulatory cluster informing growth trajectory projections. CAGRs were derived from historical adoption pattern analysis and forward-looking protocol standardization timelines. Forecast inputs incorporated epilepsy center network expansion rates and home healthcare reimbursement policy evolution.
Stress conditions across FDA inspection frequency, sterile manufacturing capacity constraints, and CMS coding decisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and caregiver training program scalability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Movement Disorder Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Optic Neuritis Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
CNS Treatment and Therapy Market
Neurology
Hydrocephalus Market
Neurology
Neurocutaneous Disorders Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Transcranial Doppler Market
Neurology
CNS Therapeutics Market
Neurology
South Korea Neurology Devices Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
North America Neurology Monitoring Market