
 Netherlands Neurology Devices Market | 2026-2036
Netherlands Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Neurology Devices Market Foresight
Aftermarket service revenue is narrowing toward preventive maintenance contracts and remote software calibration for implanted neurostimulation systems. Medtronic PLC anchors its Dutch position through deep relationships with Amsterdam UMC and Leiden University Medical Center. Abbott Laboratories differentiates via specialized programming support for its deep brain stimulation platforms. Stryker Corporation competes on instrument refurbishment cycles that extend device lifecycles in cost-conscious procurement environments.
Neurology devices encompass instruments, implantable systems, and diagnostic technologies engineered for neural signal modulation, lesion localization, or cerebrospinal fluid management, typically operating at precision tolerances below 0.1 millimeters for intracranial applications. Their primary purpose spans therapeutic intervention, disease monitoring, and surgical navigation within the central and peripheral nervous systems. Neurostimulation devices command the dominant margin pool as rechargeable pulse generators and directional leads capture premium pricing. Diagnostic equipment sustains volume leadership through EEG and EMG installations across the Netherlands' forty-plus neurology departments. Implantable systems within the technology dimension represent the fastest-growing category as closed-loop adaptive stimulation gains regulatory traction.
The EU Medical Device Regulation and Dutch Health and Youth Care Inspectorate shape market access through intensified post-market surveillance and unique device identification mandates for implantable neurology products. CE marking under the MDR now requires clinical evaluation reports with Dutch patient registry data, extending approval timelines for novel neurostimulation therapies. Stakeholders must monitor reimbursement negotiations between the National Health Care Institute and device manufacturers as value-based frameworks replace fee-for-service neurology device procurement.
Market Dynamics
The EU Medical Device Regulation is compressing approval timelines for novel neurostimulation therapies while Dutch academic medical centers accelerate adoption of closed-loop adaptive systems for movement disorders.
Growth Catalysts
- EU MDR Clinical Evidence Requirements:The tightened post-market surveillance mandates under the Medical Device Regulation are elevating standards for implantable neurology systems, creating competitive moats for manufacturers with robust Dutch patient registry data.
- Randstad Hospital Cluster Concentration:University medical centers in Amsterdam, Utrecht, and Leiden generate concentrated demand for advanced neurostimulation platforms, enabling economies of scale in specialist training and device utilization.
- Closed-Loop Adaptive Stimulation:Next-generation implantable systems with real-time neural feedback are expanding treatable patient populations beyond conventional open-loop therapies for Parkinson's disease and essential tremor.
Market Restraints
- Premium Input Cost Volatility:Directional leads with multiple independent current control channels rely on specialized platinum-iridium alloys and biocompatible polymers subject to supply concentration in German and Swiss raw material processors.
- CE Marking Timeline Friction:The Dutch Health and Youth Care Inspectorate's intensified scrutiny of clinical evaluation reports extends regulatory approval cycles for novel neurostimulation indications, delaying commercialization.
- Surgical Robot Substitution Threat:Non-invasive focused ultrasound systems for tremor ablation are capturing select patient segments previously requiring implanted deep brain stimulation hardware.
Strategic Opportunities
- Remote Programming Infrastructure:Telemedicine-enabled neurostimulator parameter adjustment is reducing in-person clinic visits, with Amsterdam UMC and Leiden University Medical Center piloting decentralized care models for rural Limburg and Groningen patients.
- Preventive Maintenance Contract Expansion:Aftermarket service revenue is migrating from reactive repair toward subscription-based remote software calibration and battery status monitoring for implanted pulse generators.
- EEG-DBS Convergence:Integration of intraoperative electrophysiological mapping with implantable recording capabilities is enabling personalized stimulation protocols tailored to individual neural signatures.
Industry Challenges
- Specialized Surgical Workforce Scarcity:Functional neurosurgery fellowship programs in the Netherlands produce limited annual graduates capable of complex deep brain stimulation lead placement with sub-millimeter precision.
- Legacy System Integration Complexity:Hospital information systems at established Dutch neurology departments require costly middleware development to accommodate proprietary data formats from next-generation implantable recording devices.
- Rechargeable Battery Certification Delays:Novel lithium-ion cell chemistries for implantable pulse generators face extended safety testing protocols under updated EU battery regulations, compressing product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Neurology Devices Market |
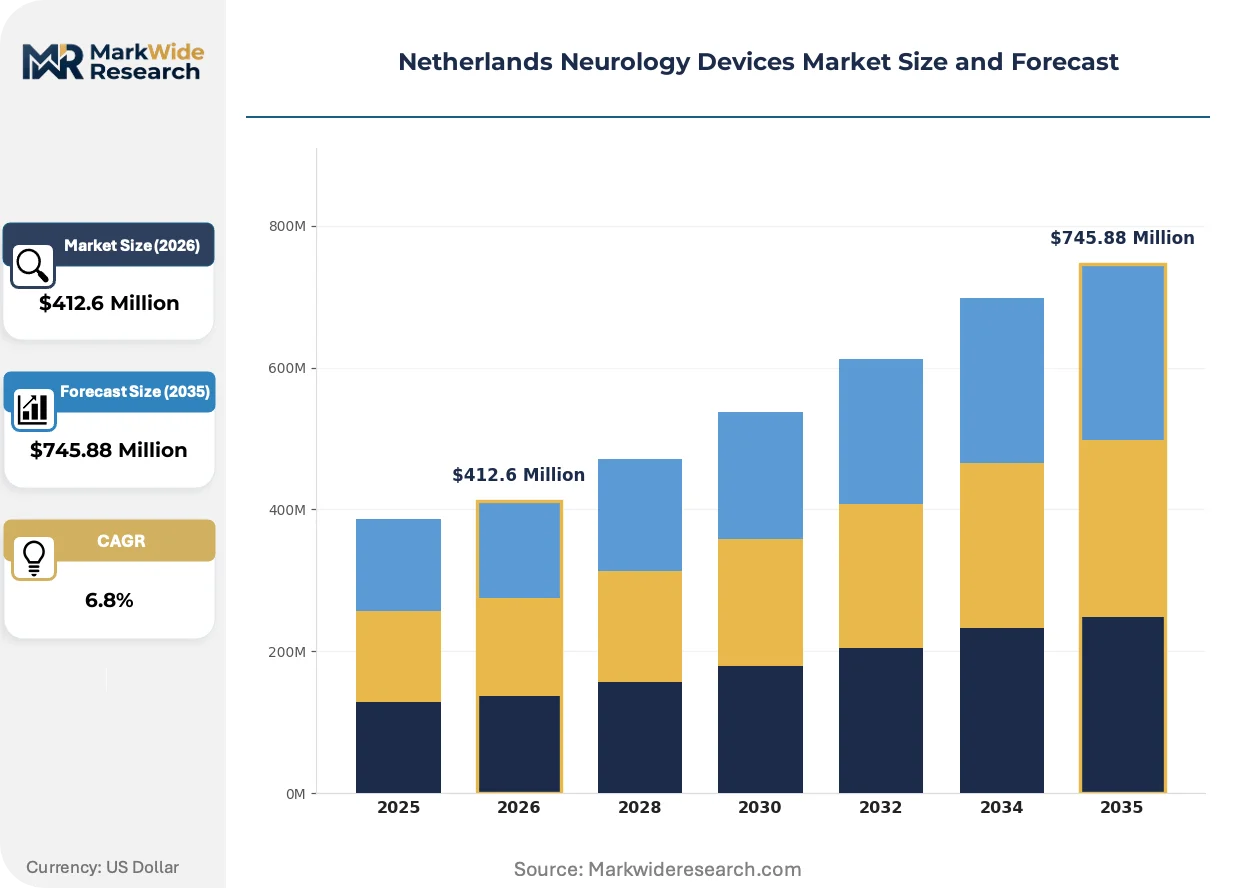
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, Diagnostic Equipment, Surgery Instruments, Monitoring Systems Application: Parkinson's Disease, Epilepsy Management, Pain Relief, Cognitive Disorders End User: Hospitals, Research Institutions, Rehabilitation Centers, Home Care Technology: Wearable Devices, Imaging Techniques, Implantable Systems, Software Solutions |
| Companies Covered | Abbott Laboratories, Johnson & Johnson, Medtronic PLC, Elekta AB, Integra LifeSciences Corporation, Stryker Corporation, B Braun Melsungen AG, Nihon Kohden Corporation, Boston Scientific Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Neurology Devices Market Shifts & Advancements
Neurostimulation technology is converging with digital health infrastructure, while regulatory frameworks and procurement models undergo parallel transformation across Dutch healthcare networks.
Directional leads with segmented electrode arrays are collapsing the therapeutic window between efficacy and side effects in deep brain stimulation. Academic medical centers in Amsterdam and Utrecht are adopting these platforms at accelerating pace for dystonia and obsessive-compulsive disorder indications. The technology is collapsing historical trade-offs between symptom control and cognitive adverse effects, enabling expansion into psychiatric applications previously considered outside neurology device scope.
The EU Medical Device Regulation's unique device identification mandate is restructuring post-market surveillance obligations for implantable neurology products. Manufacturers must now maintain traceability databases linking individual devices to Dutch patient outcomes across multi-year follow-up periods. High-risk implantable systems face the most stringent documentation requirements, with notified bodies demanding expanded clinical evidence for novel adaptive stimulation algorithms.
Hospital procurement departments are unbundling device acquisition from long-term service agreements, separating capital expenditure approvals from recurring maintenance commitments. University medical centers in the Randstad corridor are negotiating standalone preventive maintenance contracts with performance guarantees for device uptime. This restructuring is most visible at Leiden University Medical Center, where neurology device procurement now routes through centralized value-analysis committees rather than individual department budgets.
Netherlands Neurology Devices Market Segmentation
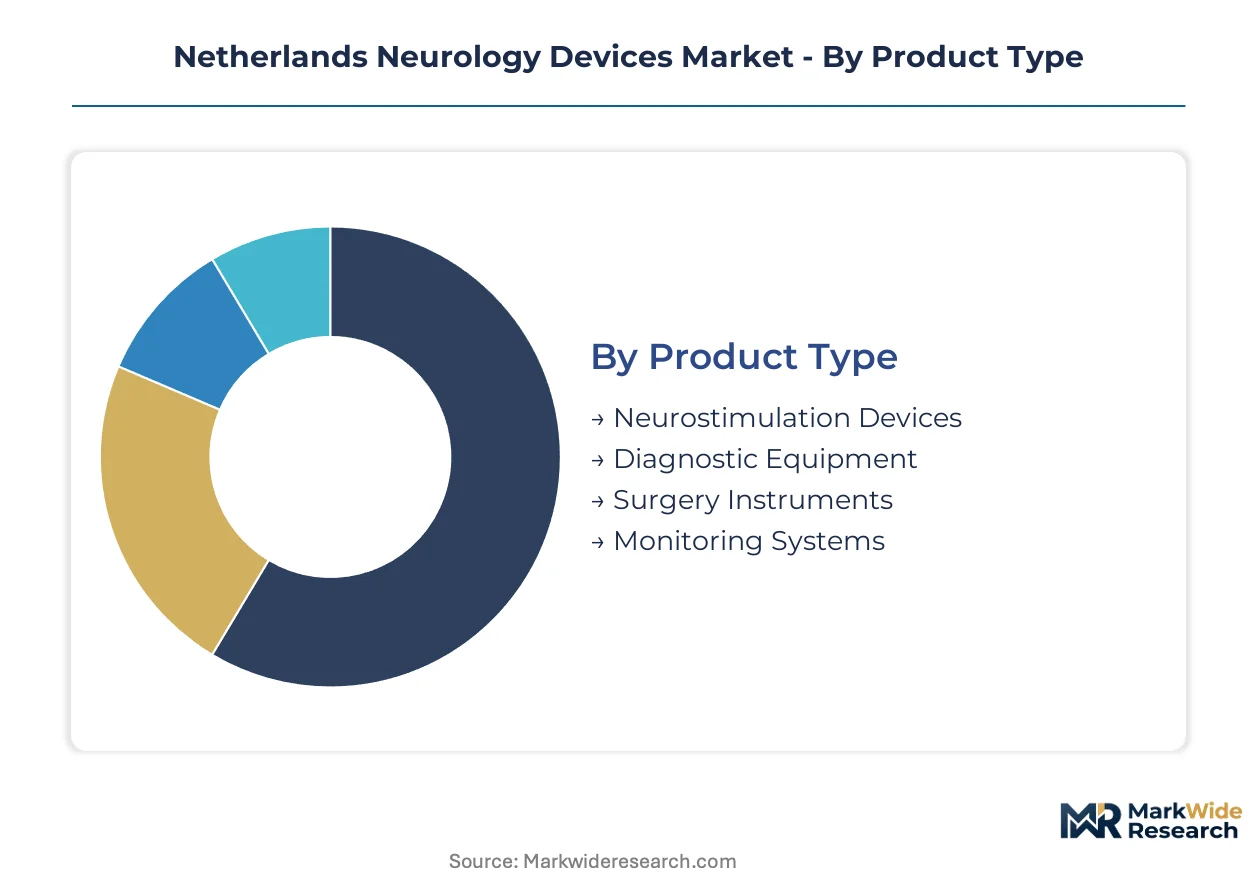
Device turnover velocity varies sharply across neurology segments, with rechargeable implantable systems cycling every 5-7 years while diagnostic platforms operate for 12-15 year lifespans. Procurement patterns in Amsterdam UMC and Leiden University Medical Center reflect this heterogeneity through differentiated capital planning cycles.
Product Type:
Replacement cycles stretch from 18-month instrument refresh rates to decade-long neurostimulator lifespans, creating distinct aftermarket revenue architectures.
- Neurostimulation Devices:Rechargeable pulse generators with directional leads command premium positioning through sub-millimeter precision tolerances. Demand clusters at Amsterdam UMC and Utrecht University Medical Center where functional neurosurgery programs drive implant volumes for movement disorders.
- Diagnostic Equipment:EEG and EMG platforms sustain volume leadership across the Netherlands' forty-plus neurology departments with extended depreciation schedules. Leiden University Medical Center and Maastricht UMC+ are consolidating procurement through centralized value-analysis committees seeking interoperability guarantees.
- Surgery Instruments:Microdissection tools and stereotactic frames require frequent refurbishment cycles in cost-conscious Dutch procurement environments.
- Monitoring Systems:Intracranial pressure and continuous EEG platforms serve intensive care units at academic medical centers with moderate replacement frequencies.
Diagnostic equipment dominates installed base. Neurostimulation devices are where expansion concentrates.
Application:
Reimbursement intensity and patient eligibility criteria create divergent market penetration depths across therapeutic indications.
- Parkinson's Disease:Deep brain stimulation for motor symptoms represents the most mature implantable therapy with established Dutch patient registries tracking long-term outcomes. Randstad corridor hospitals are piloting closed-loop adaptive systems that expand treatable populations beyond conventional open-loop candidates.
- Epilepsy Management:Responsive neurostimulation and vagus nerve stimulation platforms are gaining traction at Utrecht University Medical Center through specialized epilepsy surgery programs. The National Health Care Institute is evaluating value-based reimbursement frameworks for these therapies.
- Pain Relief:Spinal cord stimulation systems address chronic neuropathic conditions with moderate penetration in Dutch pain clinics.
- Cognitive Disorders:Experimental deep brain stimulation for Alzheimer's disease remains confined to academic research protocols at Amsterdam UMC.
Parkinson's disease anchors current implant volumes. Epilepsy management is climbing the fastest.
End User:
Capital availability and technical sophistication stratify procurement authority across care settings.
- Hospitals:University medical centers in Amsterdam, Utrecht, and Leiden concentrate demand for advanced neurostimulation platforms with integrated surgical navigation. These institutions negotiate standalone preventive maintenance contracts with performance guarantees for device uptime.
- Research Institutions:Academic centers drive early adoption of adaptive stimulation algorithms through investigator-initiated studies requiring Dutch Health and Youth Care Inspectorate oversight.
- Rehabilitation Centers:Post-implant programming facilities in peripheral Limburg and Groningen regions are integrating remote telemedicine capabilities.
- Home Care:Limited penetration of wearable diagnostic devices for ambulatory EEG monitoring in rural Dutch provinces.
Hospitals control capital procurement. Research institutions are gaining share fastest.
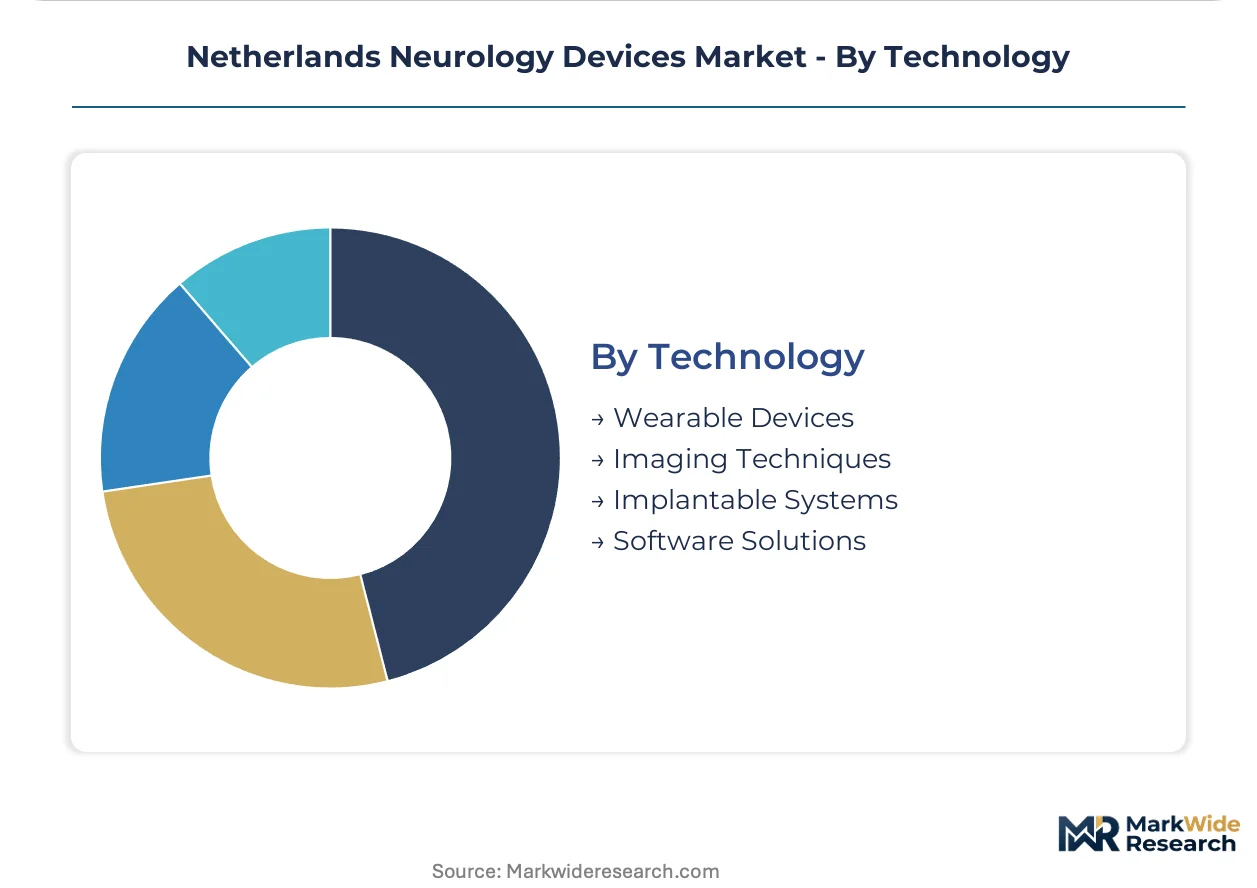
Technology:
Hardware-software integration depth determines margin architecture and regulatory pathway complexity.
- Implantable Systems:Closed-loop adaptive stimulation with real-time neural feedback represents the steepest expansion trajectory as CE marking under MDR enables novel indications. Directional leads with segmented electrode arrays are collapsing therapeutic windows between efficacy and side effects.
- Software Solutions:Remote programming infrastructure for neurostimulator parameter adjustment is reducing in-person clinic visits at pilot sites including Amsterdam UMC.
- Wearable Devices:Ambulatory EEG and tremor monitoring platforms serve diagnostic workflows with moderate reimbursement levels.
- Imaging Techniques:Intraoperative MRI and electrophysiological mapping systems support precision lead placement in functional neurosurgery.
Implantable systems dominate high-value procurement. Software solutions are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across Dutch sub-regions, with Randstad corridor hospitals absorbing premium neurostimulation pricing while peripheral provinces prioritize cost-extended diagnostic equipment lifecycles.
Randstad Corridor
Amsterdam UMC and Leiden University Medical Center drive concentrated demand for closed-loop adaptive neurostimulation systems with directional lead platforms. The Dutch Health and Youth Care Inspectorate intensifies post-market surveillance obligations for these high-risk implantable devices. Functional neurosurgery programs at Utrecht University Medical Center anchor specialist training pipelines that feed implant volumes across movement disorder indications.
Brabant Region
Tilburg and Eindhoven hospital networks concentrate spinal cord stimulation procurement for chronic pain management with moderate reimbursement sensitivity. Value-based care pilots under National Health Care Institute frameworks are reshaping device acquisition timelines. The Eindhoven Brainport ecosystem supports emerging neurotechnology startups developing wearable diagnostic platforms for ambulatory monitoring.
Northern Netherlands
Groningen and Friesland provinces exhibit pronounced price elasticity in EEG and EMG platform procurement, extending depreciation schedules beyond national averages. Remote programming infrastructure pilots at Amsterdam UMC aim to reduce travel burdens for implanted device patients in these peripheral regions. University Medical Center Groningen maintains research protocols for experimental deep brain stimulation in cognitive disorders.
Netherlands Neurology Devices Market Competitive Landscape
Integrated neuromodulation specialists and diversified surgical technology conglomerates split the market along therapy depth versus portfolio breadth lines. The vendor base concentrates around three strategic archetypes: full-stack implantable system developers with proprietary lead and generator portfolios; diagnostic equipment manufacturers with established service networks; and surgical instrument suppliers competing on refurbishment economics. Dominant competitive moves include backward integration into biocompatible material supply chains and technology licensing partnerships for adaptive stimulation algorithms.
Within the full-stack implantable tier, Medtronic PLC and Abbott Laboratories exemplify divergent approaches to Dutch market penetration, with the former anchoring relationships through academic medical center research collaborations and the latter emphasizing specialized programming support infrastructure. Stryker Corporation occupies a distinct position at the instrument-refurbishment end of the value chain, competing on lifecycle extension economics that resonate with centralized hospital procurement committees. These three entities collectively represent the competitive spectrum from premium neurostimulation platforms to cost-optimized surgical tool refresh cycles.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson & Johnson |
| Medtronic PLC |
| Elekta AB |
| Integra LifeSciences Corporation |
| Stryker Corporation |
| B Braun Melsungen AG |
| Nihon Kohden Corporation |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Brainport Eindhoven's neurotechnology manufacturing cluster shapes downstream pricing power through concentrated biocompatible polymer processing capacity and specialized platinum-iridium alloy finishing. Dutch hospital procurement committees leverage this geographic concentration to negotiate preventive maintenance bundling while absorbing premium pricing for closed-loop adaptive systems.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture, with subscription-based remote software calibration and battery status monitoring replacing transactional repair revenue. Three-tier pricing structure across premium adaptive systems, standard open-loop platforms, and economy diagnostic equipment stratifies procurement at Amsterdam UMC and Leiden University Medical Center. Cost compression in diagnostic equipment tiers intensifies as centralized value-analysis committees extend depreciation schedules. Peripheral Limburg and Groningen rehabilitation centers exhibit highest price sensitivity, while Randstad corridor academic medical centers prioritize performance guarantees over acquisition cost.
Supply Chain Analysis
Tariff exposure between Switzerland and Germany dominates supply risk for directional lead electrodes and implantable pulse generator housings. German and Swiss raw material processors anchor platinum-iridium alloy supply, while Dutch biocompatible polymer compounders feed secondary component finishing. Specialized lithium-ion cell chemistries for rechargeable generators draw from South Korean and Japanese suppliers facing extended EU battery regulation certification. Single-source vulnerability concentrates in segmented electrode array manufacturing. Distribution runs through authorized distributor networks serving hospital value-analysis committees with consolidated procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as EEG-DBS convergence and remote programming infrastructure create interoperability-dependent revenue pools. The National Health Care Institute's value-based reimbursement pilots accelerate this shift toward outcome-contingent contracting.
For Market Incumbents: Entrench proprietary data formats through middleware partnerships with hospital information system vendors at established Dutch neurology departments. Deepen backward integration into biocompatible material supply chains to offset platinum-iridium alloy cost volatility. Functional neurosurgery fellowship scarcity threatens implant volume growth; anchor specialist training pipelines at Utrecht University Medical Center to defend procedural throughput.
For New Entrants and Emerging Players: Build out wearable diagnostic platforms for ambulatory EEG monitoring in rural Northern Netherlands provinces where hospital procurement exhibits pronounced price elasticity. Target rehabilitation center programming facilities in Limburg and Groningen with telemedicine-enabled parameter adjustment tools. Partner with Eindhoven Brainport ecosystem startups to accelerate regulatory pathway navigation under Dutch Health and Youth Care Inspectorate oversight.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified surgical technology conglomerates seeking to divest non-core neurology instrument portfolios. Long-term viability hinges on adaptive stimulation algorithm IP and Dutch patient registry data assets. Watch for CE marking acceleration under MDR as inflection signal for novel indication commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance with Dutch patient registry data accelerates novel neurostimulation indication approvals. |
| Hospital System Partnership | Amsterdam UMC and Leiden University Medical Center anchor premium system adoption through research collaborations. |
| Software Companion Development | Remote programming infrastructure reduces in-person clinic visits for rural implanted device patients. |
| Reimbursement Strategy | National Health Care Institute value-based frameworks reshape procurement from fee-for-service to outcome-contingent models. |
| Backward Integration | Captive supply of biocompatible polymers and platinum-iridium alloys mitigates raw material processor concentration risk. |
Research Methodology
Initial hypotheses were tested against primary input from functional neurosurgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation against Dutch Health and Youth Care Inspectorate regulatory filings, National Health Care Institute reimbursement databases, CE marking notifications, and hospital procurement records. Bottom-up demand modeling across product type, application, end user, and technology dimensions was triangulated with top-down market sizing.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include neurostimulation versus diagnostic versus surgical instrument categories, movement disorder versus epilepsy versus pain applications, academic medical center versus rehabilitation center end users, and implantable versus wearable versus software technology tiers. CAGRs were derived from installed base turnover velocity and replacement cycle analysis, with directional lead adoption curves and closed-loop adaptive system penetration serving as neurology-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by focused ultrasound tremor ablation developers or non-invasive neurotechnology entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Acute Repetitive Seizures Market
Neurology
Benign Positional Vertigo Treatment Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Australia Neurology Devices Market
Neurology
Nerve Repair Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Argentina Neurology Devices Market
Neurology
United States Neurology Devices Market
Neurology
Sweden Neurology Devices Market
Neurology
Brain Tumor Diagnosis and Treatments Market
Neurology
North America Traumatic Brain Injuries Assessment Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Neurocognitive Assessment and Rehabilitation Market
Neurology
White Matter Injury Treatment Market