
 Cervical Dystonia Treatment Market | 2026-2036
Cervical Dystonia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Dystonia Treatment Market Analytics
Market Context with Strategic Players
Single-source reliance on incumbent botulinum toxin suppliers is repositioning toward multi-source procurement as biosimilar entrants gain manufacturing traction. AbbVie leverages its established neurology infrastructure to sustain dominance in North American specialty distribution. Merz Pharma anchors European market presence through differentiated formulation portfolios and direct hospital contracting. Ipsen Pharma competes on extended dosing intervals that reduce patient visit burden and improve adherence metrics.
Technical Definition and Structural Segments
Cervical dystonia treatment encompasses pharmacologic and interventional modalities targeting sustained involuntary contraction of neck musculature, with botulinum toxin serotype A representing the principal first-line intervention through chemodenervation of overactive muscles. The primary purpose centers on restoring functional head position, reducing pain, and preventing secondary musculoskeletal complications in affected patients. Botulinum toxin commands the dominant margin pool across treatment type segments due to recurring injection cycles and limited curative alternatives. Hospital end users capture the highest procedure volume, though outpatient facilities represent the fastest-growing site of care as same-day injection protocols standardize. Adult age groups constitute the mature core demographic, while adolescent indications emerge as a concentrated growth frontier with expanding pediatric neurology specialization.
Regulatory Framework and Forward Outlook
FDA orphan drug designations and EMA centralized marketing authorizations govern market access for novel cervical dystonia therapeutics, with each regulator imposing distinct efficacy endpoint requirements and post-marketing surveillance obligations. The EU MDR and FDA Good Manufacturing Practice standards shape product quality benchmarks, particularly for biologic toxin manufacturing where lot-to-lot consistency determines clinical utility. Stakeholders must monitor evolving interchangeability standards for biosimilar neurotoxins and their impact on formulary positioning and physician prescribing behavior.
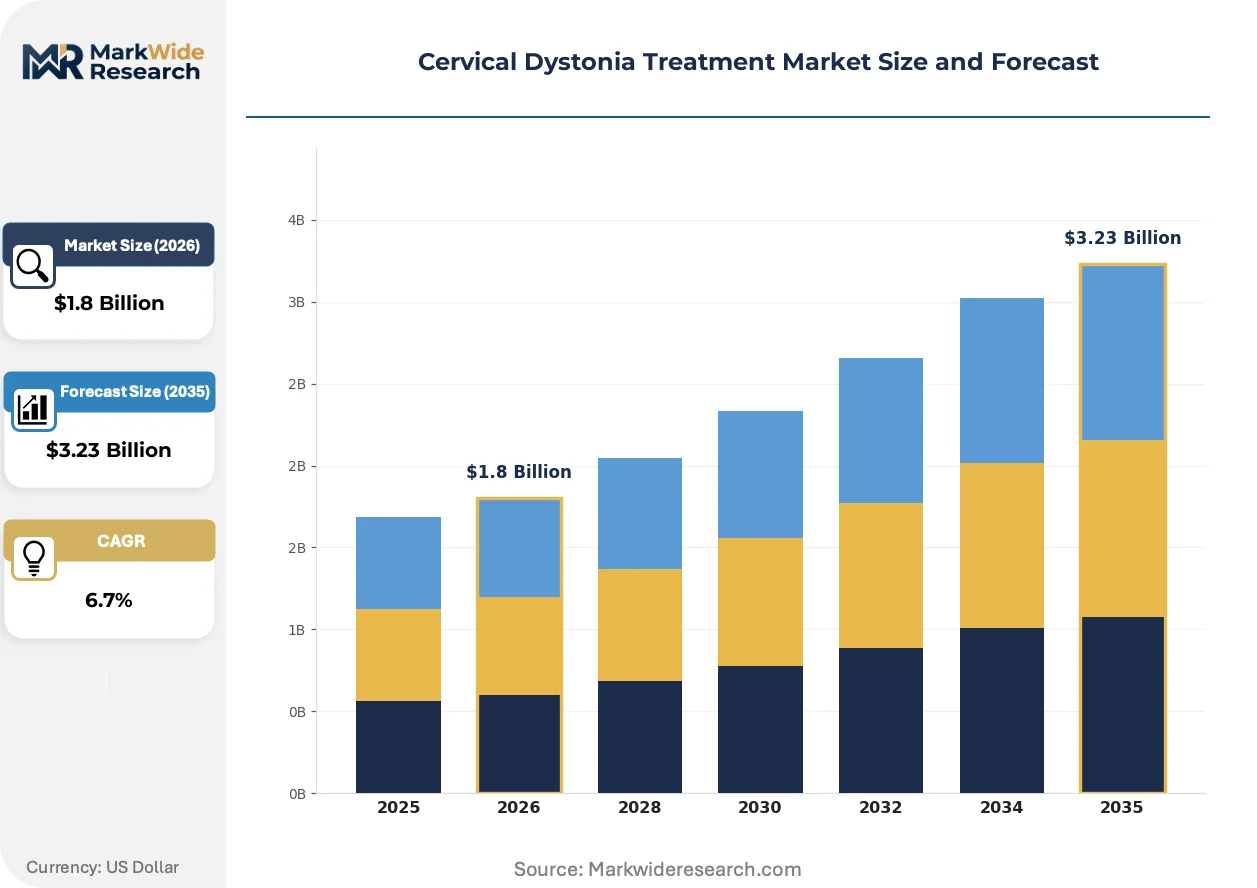
Market Dynamics
Botulinum toxin manufacturing concentration among three dominant suppliers creates supply vulnerability as demand for extended-interval formulations accelerates, forcing procurement officers to diversify sourcing strategies and qualify secondary manufacturers.
Growth Catalysts
- EMA centralized marketing authorizations:Streamlined approval pathways for biosimilar neurotoxins accelerate competitive entry across Germany, France, and Italy, expanding patient access to lower-cost alternatives.
- Neurology clinic networks:Specialized outpatient facilities in the United States deploy same-day injection protocols, reducing hospital dependency and capturing procedure volume migration.
- Pediatric neurology specialization:Adolescent indication expansion creates concentrated demand growth as academic medical centers build dedicated movement disorder programs for younger patients.
Market Restraints
- Clostridium botulinum fermentation capacity:Limited bioreactor infrastructure at established manufacturing sites constrains lot expansion and creates multi-year qualification timelines for new entrants.
- FDA lot-release testing backlogs:Extended pharmacovigilance review periods for serotype A products delay commercial shipment schedules and compress revenue recognition windows.
- Deep brain stimulation systems:Medtronic and Boston Scientific implantable devices capture refractory cases, eroding addressable market for repeat injection-dependent patients.
Strategic Opportunities
- Japan's aging demographic:PMDA priority review vouchers for orphan neurological indications incentivize sponsor investment in localized clinical trials and post-market surveillance infrastructure.
- Telemedicine-guided injection training:Remote physician supervision protocols enable community hospital staff to administer complex multi-site injections, expanding addressable geography beyond academic centers.
- EU MDR Article 117:Device-drug combination product reclassification creates regulatory arbitrage for needle-free delivery systems seeking faster market access than standalone biologics.
Industry Challenges
- Electromyography-guided injection certification:Shortage of neurologists trained in needle placement verification limits optimal dosing precision and drives variability in therapeutic outcomes across treatment sites.
- Cold chain integrity maintenance:Temperature excursion events during last-mile distribution to outpatient clinics compromise toxin potency and trigger costly product replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Dystonia Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Botulinum Toxin, Physical Therapy, Medications, Surgical Procedures Age Group: Adults, Adolescents, Elderly, Children Route of Administration: Intramuscular, Oral, Intravenous, Topical End User: Hospitals, Clinics, Homecare, Outpatient Facilities |
| Companies Covered | AbbVie, Merz Pharma, Ipsen Pharma, Revance Therapeutics, Supernus Pharmaceuticals, Allergan, Daewoong Pharmaceutical, Medytox, Lundbeck, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Dystonia Treatment Market Evolving Landscape
Novel formulation technologies are compressing injection frequency requirements while biosimilar entry reshapes procurement negotiations. These forces are redistributing margin pools across the value chain.
Extended-duration botulinum toxin formulations incorporating albumin-free stabilization buffers are integrating into standard-of-care protocols at United States academic medical centers. Movement disorder specialists at Mayo Clinic and Cleveland Clinic adopt these products to reduce patient visit burden. This integration is compressing the competitive moat of established high-frequency injection brands and forcing pricing recalibration across the therapeutic class.
EMA's updated biosimilar interchangeability guidelines for complex biologics establish distinct efficacy endpoint thresholds for cervical dystonia indications compared to cosmetic applications. German and French health technology assessment bodies incorporate these standards into hospital formulary decisions. Hospital pharmacy committees in Berlin and Paris now require head-to-head non-inferiority data before granting therapeutic substitution privileges.
Direct-to-specialist distribution models are displacing traditional wholesale channels for high-value neurotoxin shipments. Hospital systems in Japan and Germany negotiate consignment arrangements with manufacturers, transferring inventory risk from provider to supplier. This shift concentrates procurement leverage within integrated delivery networks and marginalizes independent distributor margins.
Cervical Dystonia Treatment Market Segmentation
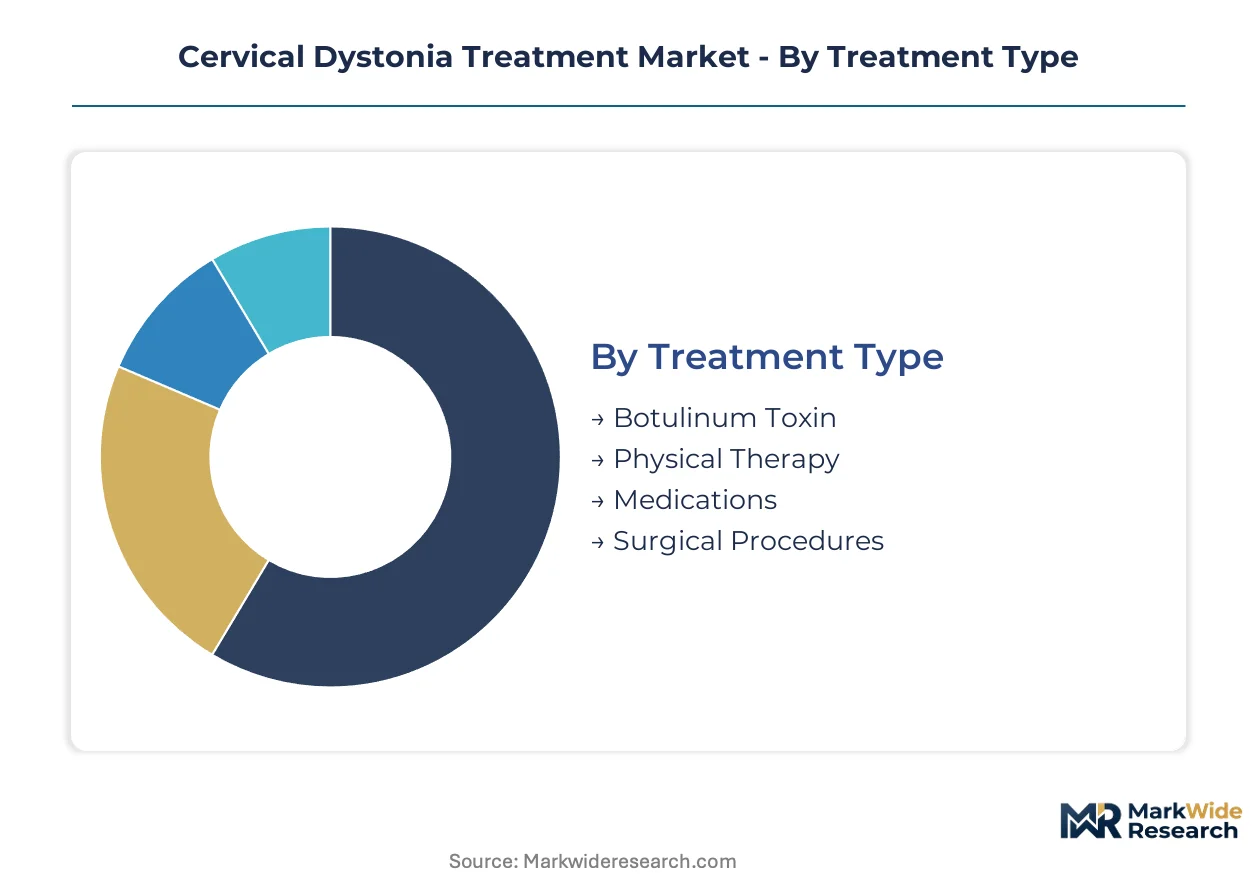
Segmentation in the cervical dystonia treatment market reveals how capital deployment, patient demographics, and care delivery sites allocate therapeutic investment. Treatment type determines manufacturing infrastructure requirements, while age group and end user shape distribution complexity and reimbursement pathways.
Treatment Type:
Capital intensity varies sharply across modalities, with biologic manufacturing demanding dedicated fermentation facilities and surgical suites requiring specialized neurosurgical equipment.
- Botulinum Toxin:Chemodenervation agents require Clostridium botulinum fermentation in GMP-certified bioreactors with lot-to-lot potency validation. Demand concentrates in United States academic medical centers where movement disorder specialists administer electromyography-guided injections. Cold chain infrastructure and FDA lot-release testing create multi-year barriers to manufacturing scale-up.
- Surgical Procedures:Deep brain stimulation implantation and selective peripheral denervation demand operating room capacity, stereotactic navigation systems, and specialized neurosurgical training. German university hospitals capture the highest procedure volumes for refractory cases, driven by statutory health insurance coverage for implantable devices.
- Physical Therapy:Cervical mobilization protocols and neuromuscular retraining require therapist certification but minimal equipment investment beyond standard rehabilitation facilities.
- Medications:Oral muscle relaxants and anticholinergic agents represent the lowest capital threshold, with generic manufacturing widely distributed across contract pharmaceutical suppliers.
Botulinum toxin absorbs the bulk of installed manufacturing capacity; surgical procedures are expanding most quickly as deep brain stimulation gains traction for treatment-resistant patients.
Age Group:
Clinical trial investment and dosing protocol development concentrate where regulatory pathways offer expedited review and where specialist physician density supports complex case management.
- Adults:The mature core demographic with established dosing algorithms and broad reimbursement coverage across commercial and public payers in the United States and Germany.
- Adolescents:Pediatric neurology specialization at Cleveland Clinic and Boston Children's Hospital drives concentrated demand growth. PMDA priority review vouchers in Japan incentivize sponsor investment in localized juvenile trials.
- Elderly:Comorbidity burden and polypharmacy constraints shape prescribing patterns, with Medicare Advantage plans in Florida and Arizona capturing high prescription volumes.
- Children:Rare early-onset cases require multidisciplinary management at dedicated pediatric movement disorder centers, with limited commercial infrastructure outside academic settings.
Adults command the majority of current therapeutic volume; adolescents represent the steepest expansion trajectory as pediatric neurology networks mature.
Route of Administration:
Delivery complexity determines training requirements, site-of-care restrictions, and patient compliance patterns across the treatment continuum.
- Intramuscular:Direct injection into dystonic neck muscles demands electromyography verification or ultrasound guidance, limiting administration to neurologists and physiatrists at Mayo Clinic and Johns Hopkins.
- Oral:Systemic muscle relaxants and anticholinergics permit primary care prescribing, with pharmacy benefit managers at UnitedHealth and CVS Caremark driving formulary placement decisions.
- Intravenous:Diazepam and other agents for acute dystonic crisis management require infusion center capacity, concentrated in hospital emergency departments.
- Topical:Limited evidence base constrains adoption, with compounding pharmacies serving niche demand for patients with needle aversion.
Intramuscular delivery dominates procedure-based revenue; oral routes are gaining share fastest as telemedicine expands primary care prescribing reach.
End User:
Site-of-care economics and reimbursement differentials redistribute patient volume across institutional settings and ambulatory environments.
- Hospitals:Academic medical centers capture complex cases requiring electromyography-guided injection and surgical evaluation, with Cleveland Clinic and Massachusetts General maintaining dedicated movement disorder programs.
- Clinics:Neurology specialty practices in Germany deploy same-day injection protocols, reducing hospital dependency and capturing procedure volume migration from inpatient settings.
- Outpatient Facilities:Ambulatory surgery centers in Texas and Florida build dedicated injection suites for high-frequency botulinum toxin administration, optimizing reimbursement under site-neutral payment rules.
- Homecare:Limited to oral medication management and physical therapy compliance monitoring, with visiting nurse associations in rural United States markets filling geographic access gaps.
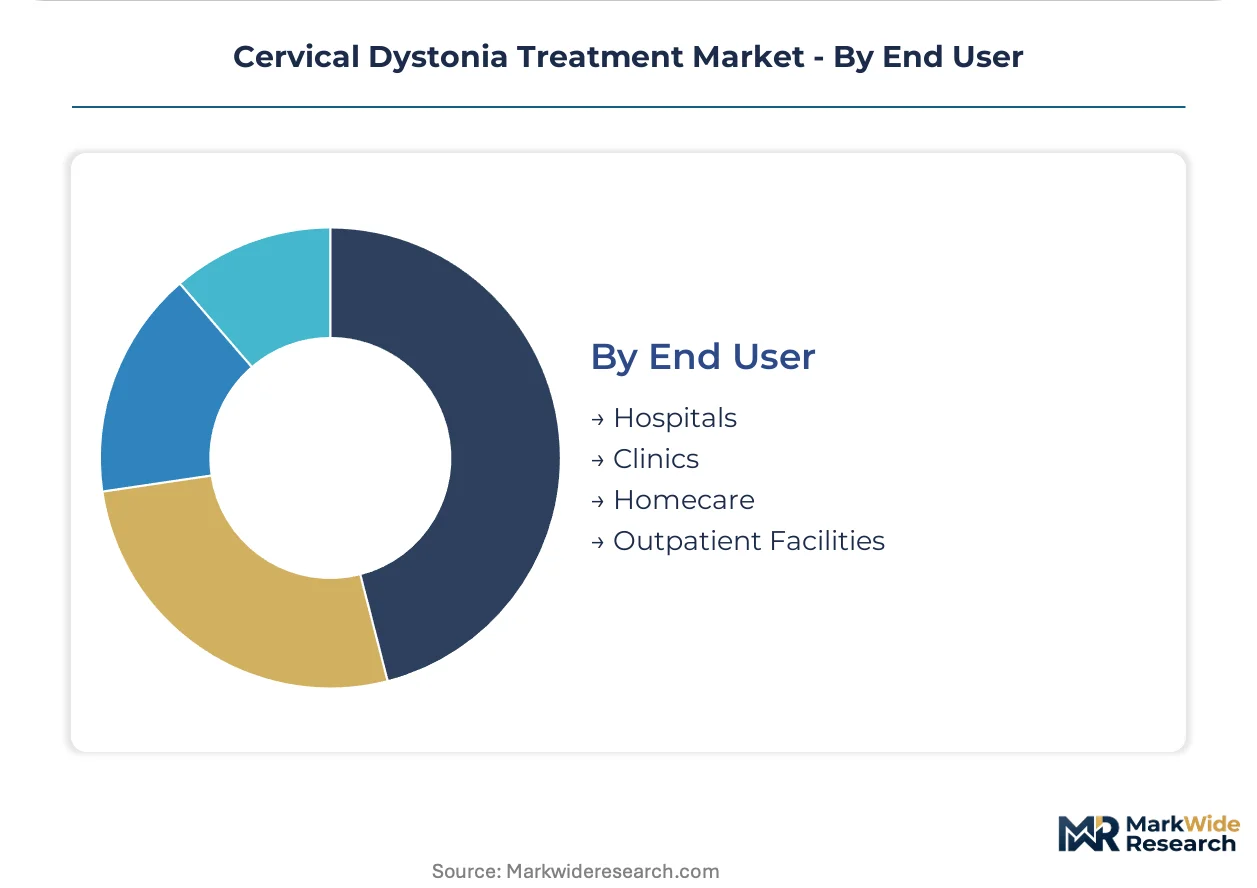
Hospitals retain the largest share of high-complexity cases; outpatient facilities are climbing the fastest as same-day protocols standardize and site-neutral payment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clostridium botulinum fermentation capacity anchors geographic market development, with specialist neurologist density and orphan drug incentive frameworks determining regional uptake trajectories.
United States
Academic medical centers at Mayo Clinic and Cleveland Clinic drive botulinum toxin procedure volume through dedicated movement disorder programs. FDA orphan drug designations and priority review vouchers accelerate novel therapeutic entry. Medicare Advantage penetration in Florida and Arizona shapes prescribing patterns for elderly patients with comorbidity burdens.
Germany
Statutory health insurance coverage for implantable devices sustains deep brain stimulation procedure growth at university hospitals in Berlin and Munich. EMA centralized marketing authorizations streamline biosimilar neurotoxin entry. Hospital pharmacy committees in Berlin and Paris now require head-to-head non-inferiority data before granting therapeutic substitution privileges.
Japan
PMDA priority review vouchers for orphan neurological indications incentivize sponsor investment in localized juvenile trials. Aging demographic concentration in Kanto and Kansai regions expands addressable patient pools. Movement disorder specialists at Tokyo University Hospital pioneer extended-interval formulation adoption.
United Kingdom
NHS England specialized commissioning frameworks concentrate cervical dystonia care at designated tertiary neurology centers in London and Manchester. NICE technology appraisals govern botulinum toxin formulary placement. Academic partnerships at University College London drive electromyography-guided injection training protocol development.
South Korea
MFDS accelerated approval pathways for biologics with established international safety profiles compress market entry timelines. Domestic fermentation infrastructure at Pangyo biotech clusters supports regional toxin manufacturing. Seoul National University Hospital anchors pediatric neurology specialization for adolescent indication expansion.
Cervical Dystonia Treatment Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and specialist distribution reach, creating a tiered structure where fermentation capacity and neurologist network depth determine competitive position. The vendor base clusters around three strategic archetypes: integrated biologic manufacturers with captive toxin supply, specialty pharmaceutical firms with neurology-focused sales infrastructure, and emerging biosimilar entrants leveraging abbreviated regulatory pathways. Dominant competitive moves include backward integration into fermentation capacity and strategic partnerships with academic medical centers for clinical trial site designation.
Within the integrated biologic tier, AbbVie and Merz Pharma exemplify divergent geographic anchoring strategies. AbbVie occupies a position reflecting North American specialty distribution dominance through established neurology infrastructure. Merz Pharma sits within the European hospital contracting archetype, leveraging differentiated formulation portfolios and direct institutional relationships. Ipsen Pharma represents the extended-interval innovation vector, with dosing protocol advantages that reduce patient visit burden and improve adherence metrics. Revance Therapeutics anchors the novel formulation development segment, exemplifying how albumin-free stabilization technologies compress competitive moats of established high-frequency injection brands.
| Leading Market Players |
|---|
| AbbVie |
| Merz Pharma |
| Ipsen Pharma |
| Revance Therapeutics |
| Supernus Pharmaceuticals |
| Allergan |
| Daewoong Pharmaceutical |
| Medytox |
| Lundbeck |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialty neurology practices in Florida and Texas concentrate procurement leverage within integrated delivery networks, compressing distributor margins while enforcing price discipline on botulinum toxin suppliers through multi-year consignment arrangements.
Pricing Analysis
Warranty and service bundling separates premium toxin brands with electromyography training support from unbundled economy alternatives requiring independent physician certification. Three-tier pricing structure across premium, standard, and economy levels tracks formulation complexity and dosing interval duration. Pricing pressure stems from EMA biosimilar interchangeability guidelines forcing originator brands to absorb certification cost burdens. Hospital pharmacy committees exhibit highest price sensitivity; academic medical centers with captive movement disorder programs demonstrate lowest sensitivity due to adherence-driven outcomes contracts.
Supply Chain Analysis
Workforce availability constraints in Clostridium botulinum fermentation constrain lot expansion at facilities in the United States, Ireland, and South Korea, where specialized bioreactor technicians command premium compensation. Manufacturing draws from pharmaceutical-grade yeast extract, anaerobic culture media, and GMP-certified vial filling capacity. Single-source vulnerability pervades the serotype A toxin supply base, with FDA lot-release testing backlogs amplifying shipment delays. Distribution runs through direct-to-specialist channels that displace traditional wholesale intermediaries for high-value neurotoxin shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where biosimilar manufacturing qualification timelines and FDA fermentation facility inspections force subscale entrants into distressed asset sales.
For Market Incumbents: Extend formulation patent estates through albumin-free stabilization innovations that compress competitor dosing intervals. Secure backward integration into captive Clostridium botulinum fermentation capacity in South Korea to insulate against FDA lot-release bottlenecks. Deepen academic medical center partnerships at Cleveland Clinic and Mayo Clinic to lock in movement disorder specialist prescribing loyalty. For New Entrants and Emerging Players: The premium-to-economy price-point gap in outpatient injection suites creates white-space opportunity for mid-tier biosimilar entrants with abbreviated EMA approval pathways. Target ambulatory surgery centers in Texas and Florida with same-day protocol certification bundled into product offerings. Penetrate adolescent indication segments where pediatric neurology specialization concentrates demand at academic medical centers with limited current supplier relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap biosimilar developers with qualified GMP fermentation infrastructure in Pangyo biotech clusters. Long-term viability hinges on regulatory arbitrage capacity across FDA, EMA, and PMDA submission pathways. Watch for PMDA priority review voucher awards as inflection signals for Japan market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Interval Formulation Development | Albumin-free stabilization at Revance Therapeutics compresses competitor moats through reduced patient visit burden. |
| Biosimilar Manufacturing Scale-Up | Clostridium botulinum bioreactor qualification at Daewoong Pharmaceutical diversifies supply beyond incumbent triopoly. |
| Telemedicine-Guided Injection Training | Remote physician supervision protocols at community hospitals expand addressable geography beyond academic centers. |
| Pediatric Indication Expansion | Adolescent clinical trials at Boston Children's Hospital unlock concentrated growth in pediatric neurology networks. |
| Direct Hospital Consignment Arrangements | Inventory risk transfer to suppliers at Berlin university hospitals concentrates procurement leverage within integrated networks. |
Research Methodology
FDA filings, EMA centralized marketing authorization databases, and ClinicalTrials.gov registry entries formed the secondary backbone, cross-referenced against primary interviews with movement disorder specialists, hospital pharmacy directors, and biologic manufacturing executives. Bottom-up and top-down triangulation validated volume estimates across treatment type, age group, and end-user segments. Payer access specialists at UnitedHealth and CVS Caremark provided formulary placement intelligence, while GPO contracts managers supplied procurement pattern data.
Bottom-up modeling anchored volume projections in qualified fermentation capacity and specialist neurologist density across the analysis window. Top-down validation referenced statutory health insurance coverage frameworks and orphan drug incentive structures. Segmentation dimensions included treatment modality, route of administration, patient demographic, and site-of-care economics. CAGRs derived from procedure volume growth curves and pricing trajectory assumptions, with inputs from cold chain logistics providers and electromyography equipment distributors.
Inputs from FDA lot-release databases and EMA biosimilar interchangeability guidelines were available through the study window; gaps in real-world adherence data for extended-interval formulations introduce uncertainty bands around patient visit reduction estimates. Forecasts reflect documented assumptions regarding pediatric neurology specialization rates and PMDA priority review voucher award velocity. Material deviation in FDA fermentation facility inspection timelines or EMA Article 117 device-drug reclassification rulings warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Ulnar Nerve Treatment Market
Neurology
Neurocutaneous Disorders Market
Neurology
Middle-East and Africa Neurology Monitoring Market
Neurology
Ischemic Cerebral Stroke Market
Neurology
Pediatric Neurology Device Market
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Mild Traumatic Brain Injury Treatment Market
Neurology
Global MRI Guided Neurosurgical Ablation Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Neuroendocrine Carcinoma Market
Neurology
Amnestic Disorders Therapeutics Market
Neurology
Canada Neurology Devices Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
Brazil Neurology Devices Market
Neurology
Benign Positional Vertigo Treatment Market