
 Tourette Syndrome Market | 2026-2036
Tourette Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Tourette Syndrome Market Outlook
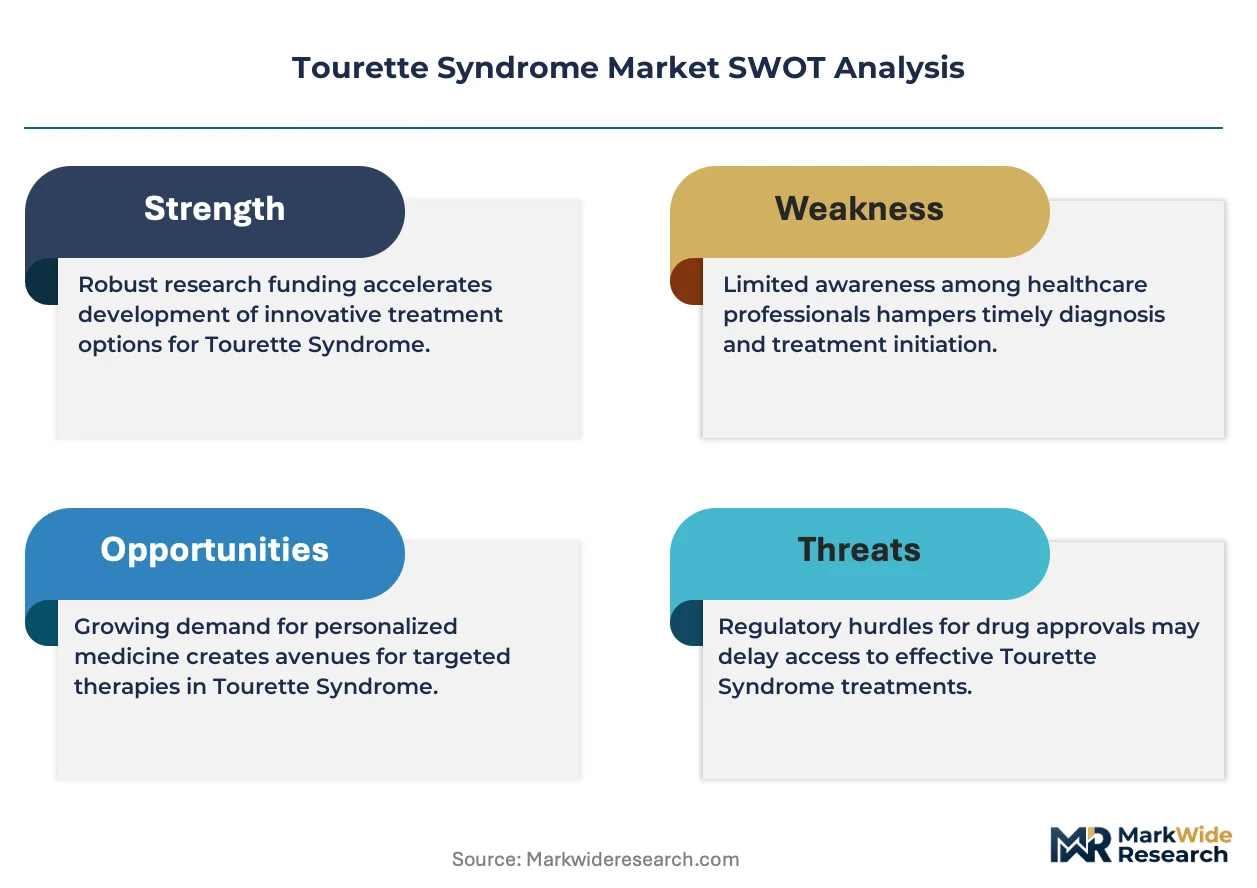
Project finance for late-stage neurological drug development is tilting competitive dynamics toward firms with balance-sheet depth. Neurocrine Biosciences leverages its commercial infrastructure in movement disorders to sustain pricing power across neurology indications. Eli Lilly anchors its position through R&D intensity in psychiatric and neurological pipelines. Teva Pharmaceutical Industries competes via manufacturing scale and established distribution through behavioral health channels.
Tourette syndrome constitutes a neurodevelopmental disorder characterized by persistent motor and vocal tics with onset typically in childhood, diagnosed under DSM-5 criteria requiring multiple motor tics and at least one vocal tic present for over one year. The condition serves commercial purpose by creating sustained demand for chronic management therapies and specialized behavioral interventions across neurology and psychiatry practices. Medications command the largest revenue share within product type segments, while behavioral therapy represents the fastest-growing category as payer coverage for comprehensive behavioral intervention for tics expands. Pediatric care dominates therapy area allocation due to early-age diagnosis patterns, though adult patient segments gain attention as recognition of persistent tic disorders in mature populations improves.
FDA orphan drug designations and accelerated approval pathways shape development incentives for novel tic disorder therapeutics, while HIPAA compliance requirements govern teletherapy delivery models expanding access to remote behavioral intervention. The Drug Enforcement Administration monitors controlled substance scheduling for certain tic-suppressing medications, influencing prescriber behavior and pharmacy distribution. Stakeholders must monitor how evolving FDA guidance on digital therapeutics could reclassify software-based behavioral interventions and alter reimbursement structures for technology-enabled care delivery.
Market Dynamics
FDA orphan drug incentives and pediatric neurology referral network expansion are restructuring competitive entry economics, concentrating development resources toward rare movement disorder indications with expedited review pathways.
Growth Catalysts
- Orphan Drug Act incentives:The FDA's seven-year market exclusivity and tax credits for clinical trial expenditures attract capital toward tic disorder therapeutics previously deemed commercially marginal.
- Telehealth infrastructure:HIPAA-compliant remote delivery platforms extend behavioral intervention access to rural pediatric populations lacking specialized tic disorder centers.
- Pediatric neurology networks:Academic medical centers in the United States are formalizing referral protocols that channel diagnosed patients toward protocol-driven care pathways.
Market Restraints
- Specialized prescriber scarcity:Board-certified child neurologists and movement disorder specialists concentrate in major metropolitan clusters, constraining patient throughput.
- Controlled substance scheduling:DEA monitoring of certain tic-suppressing medications creates pharmacy distribution friction and prescriber documentation burdens.
- Behavioral therapy reimbursement gaps:Payer coverage for comprehensive behavioral intervention for tics remains inconsistent across state Medicaid programs.
Strategic Opportunities
- Adult persistent tic recognition:Improved diagnostic awareness among general psychiatrists in the United States opens chronic management revenue streams beyond pediatric transitions.
- Digital therapeutic classification:Evolving FDA guidance on software-based behavioral interventions may establish distinct reimbursement codes for technology-enabled care delivery.
- Integrated care models:Co-location of neurology and psychiatry services within academic medical centers enables bundled payment structures for complex tic disorder management.
Industry Challenges
- Cross-disciplinary care coordination:Pediatric neurologists, child psychiatrists, and behavioral therapists operate under disparate electronic health record systems, fragmenting longitudinal patient tracking.
- Behavioral intervention scale constraints:Training and certifying sufficient therapists in habit reversal training and exposure-response prevention requires eighteen-to-twenty-four-month pipeline development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tourette Syndrome Market |
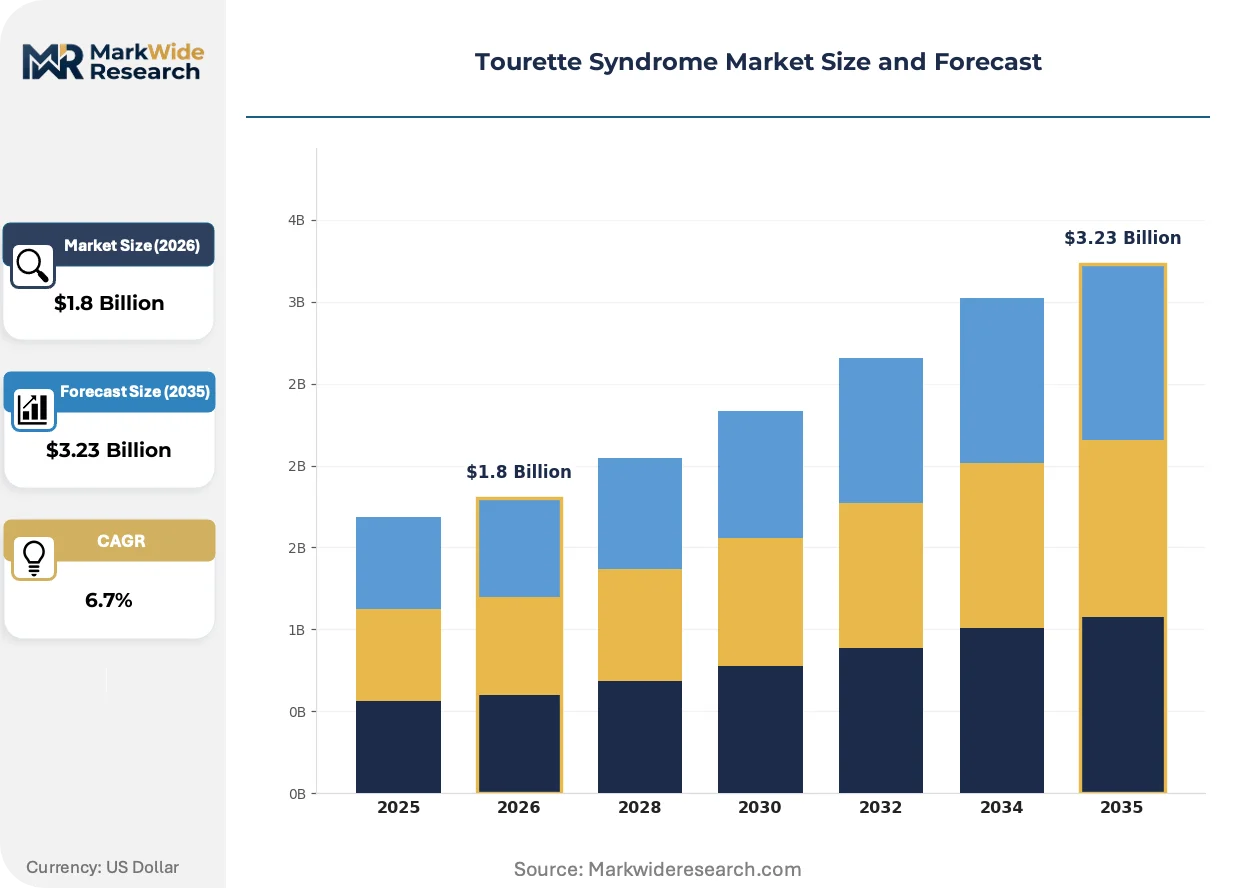
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Behavioral Therapy, Support Devices, Educational Programs Therapy Area: Neurology, Psychiatry, Behavioral Health, Pediatric Care Delivery Mode: Oral, Injectable, Transdermal, Teletherapy End User: Children, Adolescents, Adults, Caregivers |
| Companies Covered | Emalex Biosciences Inc., Neurocrine Biosciences Inc., AstraZeneca Plc, Otsuka Pharmaceutical Co. Ltd., Teva Pharmaceutical Industries Ltd., H. Lundbeck A/S, Eli Lilly and Company, Bausch Health Companies Inc., Reviva Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tourette Syndrome Market Strategic Shifts
Digital biomarker capture and asynchronous therapeutic delivery are compressing the traditional clinic-based care model for tic disorders, shifting value capture toward platform-enabled service architectures.
Smartphone-based tic detection algorithms using accelerometer and microphone pattern recognition are rendering obsolete paper-based tic frequency diaries and subjective parent reporting. Pediatric neurology clinics in the United States are piloting these systems for remote symptom monitoring between visits. The technology is rendering obsolete the episodic, recall-dependent clinical assessment model that has dominated tic disorder management for decades.
The FDA's evolving guidance framework for digital therapeutics is creating precedent for prescription software interventions in neurology and psychiatry indications. Manufacturers of behavioral intervention platforms are pursuing De Novo classification pathways to establish predicate devices for subsequent tic disorder applications. European regulators through the MDR are developing parallel software-as-medical-device standards that may create transatlantic harmonization pressure.
Specialized tic disorder centers are consolidating referral authority through outcome data publication and protocol standardization, compressing the role of general community neurologists in initial diagnosis. Academic medical centers in the United States are establishing branded comprehensive programs that capture patients from expanded catchment areas. This concentration is most visible in the Northeast and Midwest corridor, where institutional reputation drives family travel patterns for second-opinion consultations.
Tourette Syndrome Market Segmentation
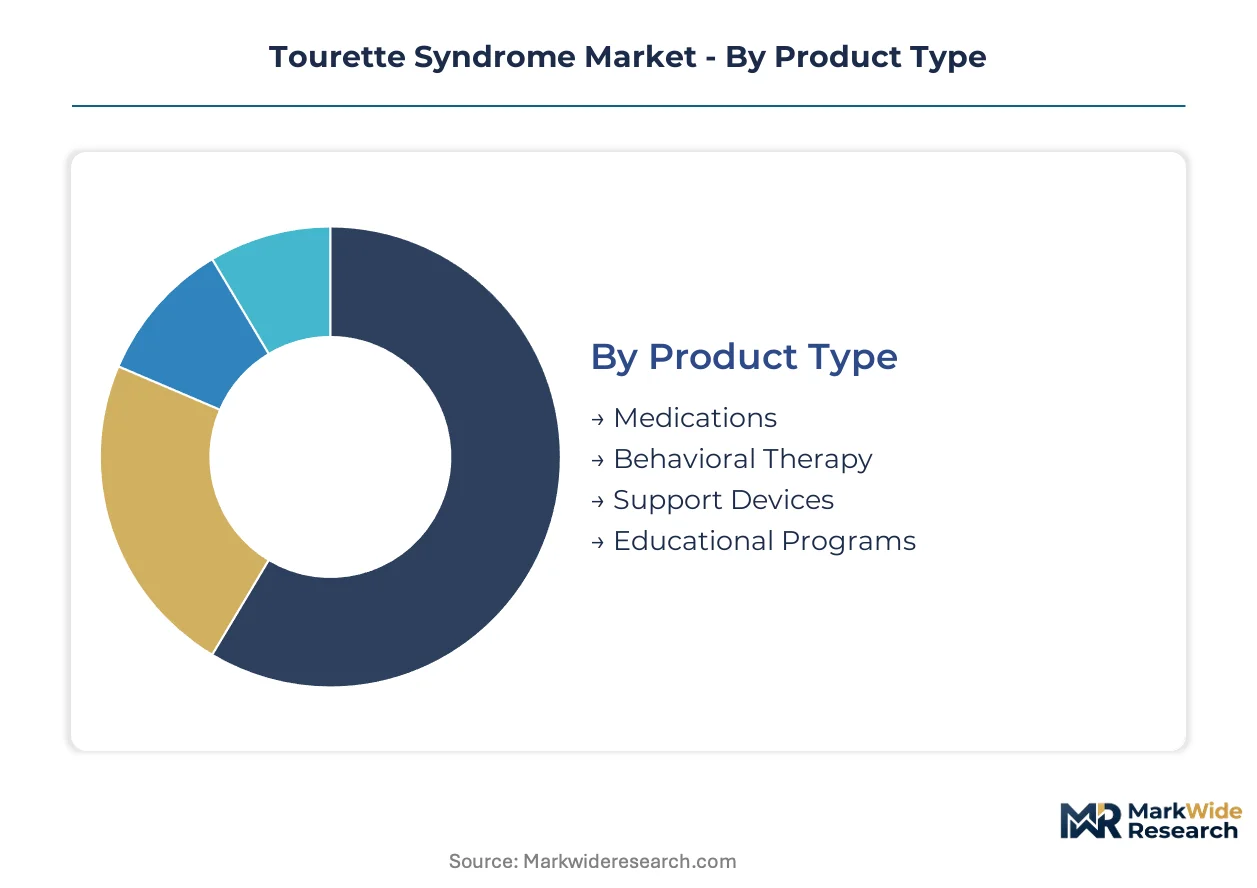
Segmentation in the Tourette syndrome market reveals how treatment complexity fragments across clinical disciplines and patient life stages. Each dimension exposes distinct reimbursement pathways, prescriber behaviors, and technology adoption patterns that shape commercial strategy.
Product Type:
After-sales service intensity varies sharply across product categories, with behavioral therapy platforms requiring ongoing therapist certification updates and medication regimens demanding pharmacovigilance reporting.
- Medications:Pharmacological interventions span alpha-2 adrenergic agonists, antipsychotics, and dopamine depletors formulated for chronic tic suppression. Demand concentrates in pediatric neurology clinics across the United States where FDA-approved formulations anchor protocol-driven prescribing. DEA scheduling requirements for certain agents create pharmacy distribution friction that favors established wholesale relationships.
- Behavioral Therapy:Comprehensive behavioral intervention for tics (CBIT) and habit reversal training delivered through certified practitioners. Pediatric academic medical centers in the Northeast and Midwest corridor drive demand as families travel for specialized second-opinion consultations. Payer coverage expansion under state Medicaid programs accelerates adoption fastest.
- Support Devices:Wearable tic detection monitors and biofeedback equipment for symptom tracking.
- Educational Programs:School-based accommodations and individualized education plan coordination services.
Medications hold the largest share; momentum sits with behavioral therapy.
Therapy Area:
Cost tier stratification separates high-complexity academic center care from community-based management, with reimbursement rates scaling to specialist credentialing intensity.
- Pediatric Care:Early-age diagnosis and chronic management of tics through child neurologists and developmental pediatricians. United States metropolitan clusters with board-certified specialists constrain patient throughput and sustain pricing premiums. Referral network formalization at academic medical centers channels volume toward protocol-driven pathways.
- Neurology:Movement disorder specialists managing severe or atypical tic presentations requiring differential diagnosis from other hyperkinetic disorders. Adult recognition of persistent tics among general psychiatrists opens revenue streams beyond pediatric transitions.
- Psychiatry:Co-occurring conditions including OCD and ADHD drive integrated treatment approaches.
- Behavioral Health:Psychologists and licensed therapists delivering evidence-based behavioral interventions.
Pediatric care commands dominant volume; psychiatry is expanding most quickly as comorbidity awareness spreads.
Delivery Mode:
Application context dictates technology selection, with acute settings favoring rapid-onset formulations and maintenance phases enabling remote delivery platforms.
- Oral:Tablet and liquid formulations of alpha-2 agonists and antipsychotics for daily chronic administration. United States retail pharmacy networks handle fulfillment with prior authorization requirements varying by payer. Generic availability for older agents compresses margins while driving volume.
- Teletherapy:HIPAA-compliant remote delivery of behavioral intervention through synchronous video and asynchronous practice platforms. Rural pediatric populations lacking specialized tic disorder centers represent the steepest expansion trajectory as state licensure compacts enable cross-border practitioner access.
- Injectable:Long-acting formulations for patients with adherence challenges or severe symptomatology.
- Transdermal:Patch-based delivery systems for continuous medication release with reduced peak-trough variability.
Oral delivery maintains dominant share; teletherapy gains share fastest among delivery modalities.
End User:
Customer type segmentation aligns prescriber training, caregiver involvement intensity, and reimbursement pathway complexity to developmental stage.
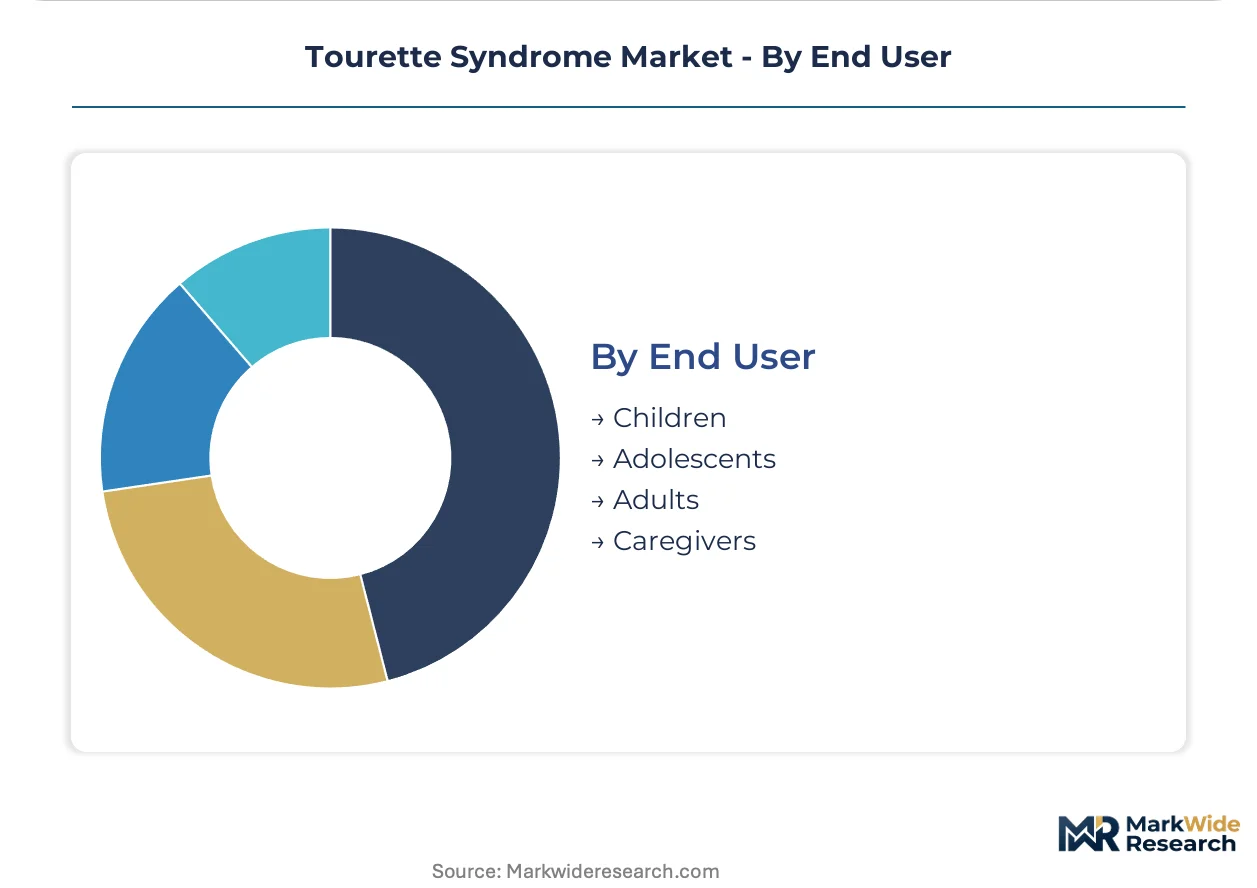
- Children:Patients aged 4-12 years presenting with initial tic onset and requiring school accommodation coordination. United States pediatric neurology clinics represent the fastest-expanding buyer segment as referral networks widen. Educational program integration drives family selection of comprehensive centers.
- Adolescents:Patients navigating transition to adult services with elevated social stigma concerns and peer relationship impacts.
- Adults:Persistent tic disorder patients previously undiagnosed or re-entering care after pediatric service graduation.
- Caregivers:Parents and guardians managing appointment logistics, medication administration, and behavioral coaching reinforcement.
Children account for the largest patient volume; adults represent the emerging segment with recognition improving among general psychiatrists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and pediatric neurology referral network expansion in the United States concentrate development resources toward rare movement disorder indications with expedited review pathways. Academic medical centers in the Northeast and Midwest corridor formalize protocols that channel diagnosed patients toward standardized care pathways. Specialized tic disorder centers in metropolitan clusters sustain pricing premiums through outcome data publication and institutional reputation.
United States
Pediatric neurology clinics represent the fastest-expanding buyer segment as referral networks widen across metropolitan clusters. The FDA's expanded orphan drug incentives reshape development economics for rare movement disorders through seven-year market exclusivity and tax credits. The Northeast and Midwest corridor hosts academic medical centers establishing branded comprehensive programs that capture patients from expanded catchment areas.
Germany
Movement disorder specialists concentrate in university hospital networks serving severe or atypical tic presentations requiring differential diagnosis. The EMA's centralized marketing authorization procedures enable streamlined access to novel neurological therapeutics across member states. Baden-Württemberg and Bavaria host specialized pediatric neurology departments integrating behavioral intervention with pharmacological management.
United Kingdom
NHS England's specialized commissioning frameworks channel complex tic disorder cases toward designated tertiary centers with multidisciplinary teams. The MHRA operates post-Brexit recognition procedures for FDA-approved neurological therapeutics that accelerate patient access timelines. London and the Southeast corridor concentrate board-certified child neurologists and tic disorder specialists within academic medical center networks.
Japan
PMDA Sakigake designation pathways attract development investment for pediatric neurological indications with unmet medical need. The Ministry of Health, Labour and Welfare's reimbursement pricing negotiations for orphan drugs sustain commercial viability for low-prevalence conditions. The Kanto region around Tokyo hosts the highest density of pediatric neurology specialists and movement disorder academic departments.
Canada
Provincial health authority funding for rare disease therapeutics varies across Ontario, Quebec, and British Columbia, creating access fragmentation. Health Canada's priority review pathways for drugs treating serious or life-threatening conditions compress regulatory timelines for novel tic disorder therapeutics. Ontario and Quebec concentrate pediatric neurology subspecialists within academic hospital networks serving referred populations from Atlantic and Prairie provinces.
Tourette Syndrome Market Competitive Environment
Channel-controlling players compete with product-specialist players across the Tourette syndrome therapeutic landscape. The vendor base fragments across multinational pharmaceutical conglomerates with established neurology franchises, mid-cap biotech firms with movement disorder specialization, and emerging developers pursuing orphan indications. Three strategic archetypes dominate: balance-sheet-heavy incumbents leveraging commercial infrastructure, R&D-intensive innovators targeting unmet need, and manufacturing-scale generics competitors. Consolidation through acquisition of late-stage neurological assets and strategic partnerships for digital therapeutic co-development represent the dominant competitive moves.
Within the commercial infrastructure archetype, Neurocrine Biosciences and Teva Pharmaceutical Industries exemplify established positioning. Neurocrine Biosciences occupies a position representing balance-sheet depth applied to movement disorder commercialization. Teva Pharmaceutical Industries sits within the manufacturing-scale tier, anchoring competitive presence through established distribution channels. Eli Lilly and Company represents the R&D-intensive archetype among Indianapolis-based pharmaceutical developers. These three named entities illustrate how competitive dynamics tilt toward firms with specialized neurology expertise, manufacturing scale, or pipeline intensity rather than undifferentiated market participation.
| Leading Market Players |
|---|
| Emalex Biosciences Inc. |
| Neurocrine Biosciences Inc. |
| AstraZeneca Plc |
| Otsuka Pharmaceutical Co. Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| H. Lundbeck A/S |
| Eli Lilly and Company |
| Bausch Health Companies Inc. |
| Reviva Pharmaceuticals Inc. |
| Others |
Value Chain & Pricing Dynamics
The Northeast and Midwest corridor of the United States anchors specialized tic disorder center capacity, and this geographic concentration of board-certified child neurologists and movement disorder specialists sustains pricing premiums through outcome data publication and institutional reputation capture.
Pricing Analysis
Certification level of behavioral intervention practitioners creates the primary spread between premium and standard service tiers, with CBIT-certified therapists commanding reimbursement rates substantially above generalist providers. The dominant pricing structure operates as a tiered premium-standard-economy model across medication, behavioral therapy, and digital therapeutic categories. Price differentiation stems from FDA approval status of pharmacological agents and geographic delivery costs for rural teletherapy access. Pricing pressure intensifies in the medication segment as generic alpha-2 agonist formulations expand, while behavioral therapy maintains resilience through certified practitioner scarcity. State Medicaid programs demonstrate highest price sensitivity, whereas academic medical center networks show lowest sensitivity due to bundled payment structures and research funding offsets.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from wholesale pharmaceutical distributors sustain inventory carrying costs for DEA-scheduled tic-suppressing medications through retail pharmacy networks. Manufacturing concentration rests in the United States, India, and Ireland for active pharmaceutical ingredients and finished dosage forms. Raw material dependencies center on specialized dopamine modulator precursors, alpha-2 agonist intermediates, and biofeedback sensor components. Single-source vulnerability pervades the digital therapeutic platform segment, where FDA De Novo classification pathways create predicate device dependencies. Distribution runs through three-tier wholesale arrangements for medications, direct-to-provider licensing for behavioral therapy platforms, and academic medical center procurement for comprehensive care programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tourette syndrome market sits at a platform-economics inflection where digital therapeutic interoperability with electronic health record systems will determine which care delivery models capture longitudinal patient relationships and associated revenue streams.
For Market Incumbents: Insulate commercial infrastructure by deepening captive supply relationships for DEA-scheduled medications and securing exclusive CBIT therapist certification partnerships at academic medical centers. The emerging threat of software-based behavioral interventions with distinct reimbursement codes demands defensive investment in digital therapeutic co-development capabilities. Vertical integration into teletherapy platform ownership represents the critical lever for preserving patient relationship control. For New Entrants and Emerging Players: Adult persistent tic disorder recognition among general psychiatrists in the United States represents the most penetrable entry point, with diagnostic awareness gaps creating addressable white space beyond saturated pediatric neurology networks. Rural teletherapy delivery through HIPAA-compliant asynchronous platforms offers second-mover advantage where state licensure compacts enable cross-border practitioner deployment. The optimal go-to-market angle centers on employer-sponsored behavioral health benefits targeting undiagnosed adult populations in professional services industries. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management platform play because tic disorder patient lifetime value extends across decades of medication adherence, behavioral intervention refresh cycles, and comorbidity treatment expansion. Acquisition targets should display movement disorder specialization with established FDA interaction history and pediatric neurology referral network relationships. The signal to watch is evolving FDA guidance on prescription digital therapeutics that would reclassify software-based interventions and unlock distinct reimbursement code creation.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Therapeutic De Novo Classification | FDA precedent for prescription software interventions establishes predicate pathways for tic disorder applications. |
| CBIT Therapist Certification Pipeline Expansion | Eighteen-to-twenty-four-month training cycles constrain supply and sustain premium pricing for certified practitioners. |
| Academic Medical Center Partnership Structuring | Branded comprehensive programs capture expanded catchment area patients through outcome data publication. |
| Orphan Drug Designation Pursuit | Seven-year market exclusivity and tax credits reshape development economics for rare movement disorder indications. |
| Telehealth Licensure Compact Navigation | State-level regulatory harmonization enables rural pediatric population access and platform-enabled service scaling. |
Study Parameters
Initial hypotheses were tested against primary input from pediatric neurologists, child psychiatrists, behavioral health payers, and digital therapeutic developers and refined through secondary validation against FDA orphan drug designation databases, ClinicalTrials.gov enrollment data, state Medicaid formulary filings, and CMS Medicare reimbursement schedules. Bottom-up patient volume estimates from academic medical center referral networks were triangulated against top-down pharmaceutical shipment data and behavioral therapy platform utilization metrics.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling across product type, therapy area, delivery mode, and end user dimensions. CAGRs were derived from patent expiration timelines, generic entry assumptions, and digital therapeutic adoption curves. Forecast inputs incorporated FDA review pathway timelines, DEA scheduling modifications, and state-level telehealth reimbursement policy evolution.
Practitioners should monitor regulatory guidance revision on digital therapeutics classification, DEA scheduling adjustments for tic-suppressing medications, and state Medicaid behavioral therapy coverage expansion for early signals of structural shift. Forecasts reflect assumptions anchored in current orphan drug incentive structures and HIPAA telehealth enforcement postures; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Neurodegenerative Disease Treatment Market
Neurology
Traumatic Brain Injuries Assessment Market
Neurology
Occipital Nerve Block Treatment Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Global Neurology Clinical Trials Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Global Lambert-Eaton Myasthenic Syndrome Treatment Market
Neurology
Hepatic Encephalopathy Market
Neurology
Arachnoiditis Market
Neurology
Europe Pediatric Neurology Device Market
Neurology
Vertebrobasilar Insufficiency Treatment Market
Neurology
Transverse Myelitis Treatment Market
Neurology
Cerebral Spinal Fluid (CSF) Management Market
Neurology
Brain Aneurysm Treatment Market
Neurology
South Korea Neurology Devices Market
Neurology
Netherlands Neurology Devices Market