
 Oak Chips White Extract Market | 2026-2036
Oak Chips White Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Oak Chips White Extract Market Analytics
REACH is repositioning the cost-of-entry calculus for European suppliers of oak-derived extracts. White Oak leverages captive forestry assets in Appalachian zones to sustain raw material security. The Vintner Vault anchors its position through specialized distribution to craft beverage producers. Oak Solutions Group differentiates via technical service capabilities around extract dosing protocols.
Oak chips white extract comprises phenolic compounds, ellagitannins, and volatile aldehydes extracted from Quercus alba through controlled toasting and solvent or steam distillation processes; manufacturers target specific vanillin and eugenol concentrations to achieve consistent flavor profiles in finished goods. The natural product type dominates volume as beverage manufacturers resist synthetic labeling, while concentrated formats capture disproportionate margin pools from cosmetic companies seeking standardized active dosages. Food industry applications are maturing amid established bakery and confectionery usage, whereas fragrances represent the fastest-expanding segment as perfumers seek woody base notes with provenance credentials.
FDA oversight of food-contact substances and EPA guidance on extraction solvent residues jointly shape product specifications for US-bound shipments. EMA botanical drug guidelines and ISO 17025 testing protocols further condition market access across European pharmaceutical and cosmetic channels. Stakeholders must monitor evolving purity standards and solvent disclosure requirements to preserve cross-border commercial eligibility.
Market Dynamics
REACH compliance thresholds are compressing supplier margins while simultaneously advantaging extractors with captive oak forestry and in-house solvent recovery systems.
Growth Catalysts
- Natural labeling mandates:Beverage manufacturers across France and the United States are reformulating to eliminate synthetic flavor declarations, pulling demand toward certified botanical extracts.
- REACH Article 57 substance restrictions:Tightened purity protocols for botanical imports into the European Union are disqualifying informal suppliers and consolidating volume with compliant processors.
- Cooperage cluster proximity:Extraction facilities sited near Cognac and Kentucky stave mills secure preferential access to fresh white oak biomass before oxidative degradation.
Market Restraints
- Input cost volatility:White oak timber prices fluctuate with Appalachian logging permit cycles and hardwood flooring sector competition.
- Supply concentration risk:Premium Quercus alba feedstock concentrates in eastern North American forests, exposing processors to regional climate disruption and export logistics bottlenecks.
- Substitution threat:Laboratory-synthesized vanillin and guaiacol from petrochemical precursors undercut natural extract pricing in cost-sensitive fragrance applications.
Strategic Opportunities
- Underpenetrated cosmetics channel:South Korean formulators are integrating oak-derived polyphenols into anti-aging serums, creating pull for standardized ellagitannin concentrations.
- Emerging pharmaceutical application:EMA botanical drug guidelines are opening pathways for oak extract submissions in topical anti-inflammatory indications.
- Supercritical CO2 convergence:Combination with inline spectroscopic monitoring enables real-time extraction endpoint detection, reducing solvent waste and batch-to-batch variation.
Industry Challenges
- Analytical talent scarcity:ISO 17025-compliant laboratories struggle to recruit chromatography specialists capable of validating complex phenolic profiles for regulatory submissions.
- Legacy equipment integration:Steam distillation vessels require retrofitting with closed-loop condensation to meet EPA air emission standards for volatile organic compound capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oak Chips White Extract Market |
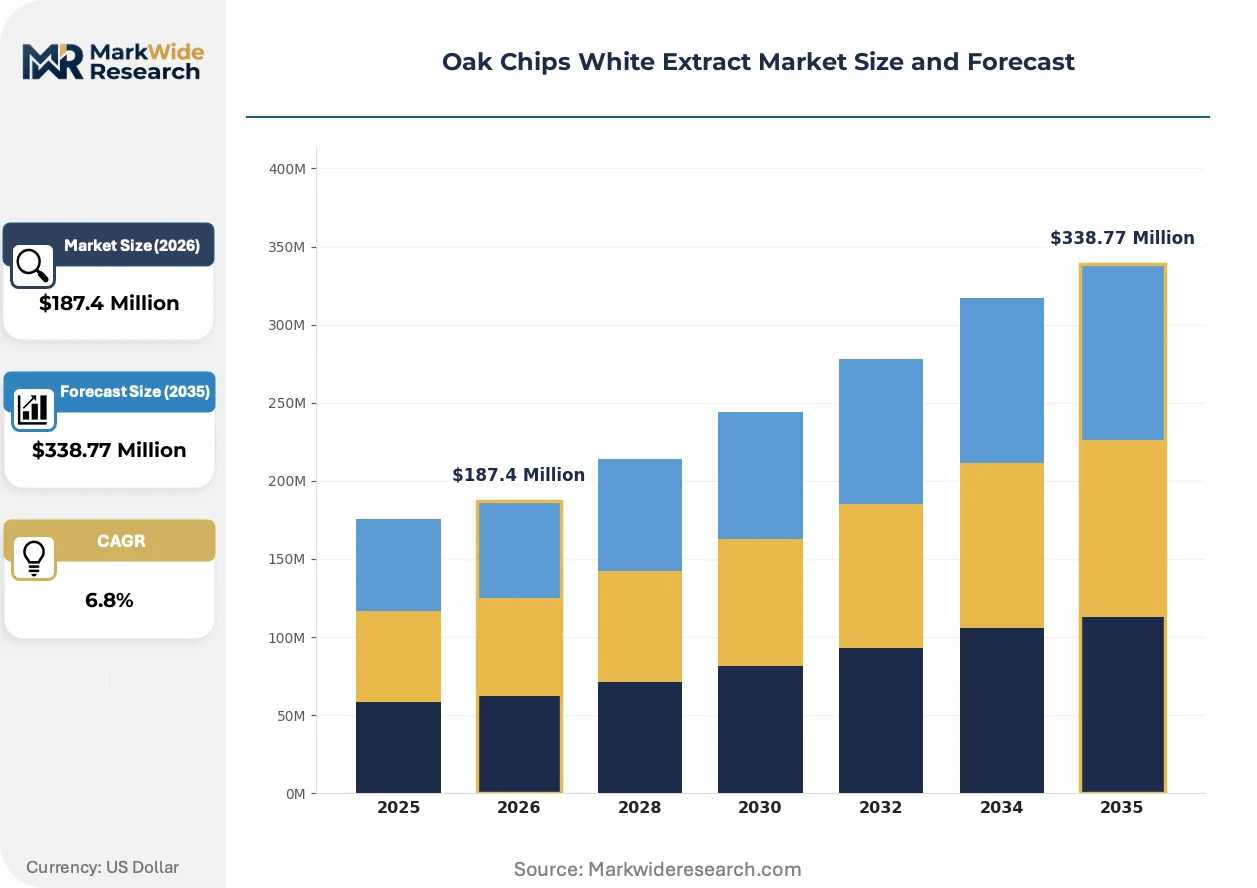
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Organic, Blended, Concentrated Application: Flavors, Fragrances, Cosmetics, Food Industry End User: Beverage Manufacturers, Personal Care Brands, Food Producers, Cosmetic Companies Distribution Channel: Online Retail, Wholesale, Supermarkets, Specialty Stores |
| Companies Covered | White Oak, The Vintner Vault, Rich Xiberta USA, The Barrel Mill, Canadell, Oak Solutions Group, Swiss Woodcraft, Oak Chips Inc, Seguin Moreau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oak Chips White Extract Market Evolving Landscape
Extraction technology and regulatory disclosure requirements are converging to reward processors with transparent supply chains and precision process control.
Supercritical CO2 extraction systems paired with inline near-infrared spectroscopy are rewriting quality assurance economics for mid-scale processors. Cosmetic compounders in Germany and Switzerland are adopting these platforms to guarantee batch-to-batch phenolic consistency. The technology is compressing the competitive gap between artisan extractors and industrial suppliers by democratizing analytical rigor.
EMA botanical drug guidelines are conditioning market access for pharmaceutical-grade oak extracts. Compliance demands comprehensive phytochemical characterization and stability documentation that exceeds cosmetic or food-grade requirements. European contract manufacturers are responding by segregating production lines and dedicating validation protocols to therapeutic-grade output.
Fragrance houses are consolidating supplier relationships around extractors with documented provenance and chain-of-custody certification. This behavior is displacing spot-market purchasing for woody base notes. The shift is most visible in Grasse and Paris, where perfumers now require GPS-tracked forestry documentation and carbon footprint disclosure for oak-derived materials.
Oak Chips White Extract Market Segmentation
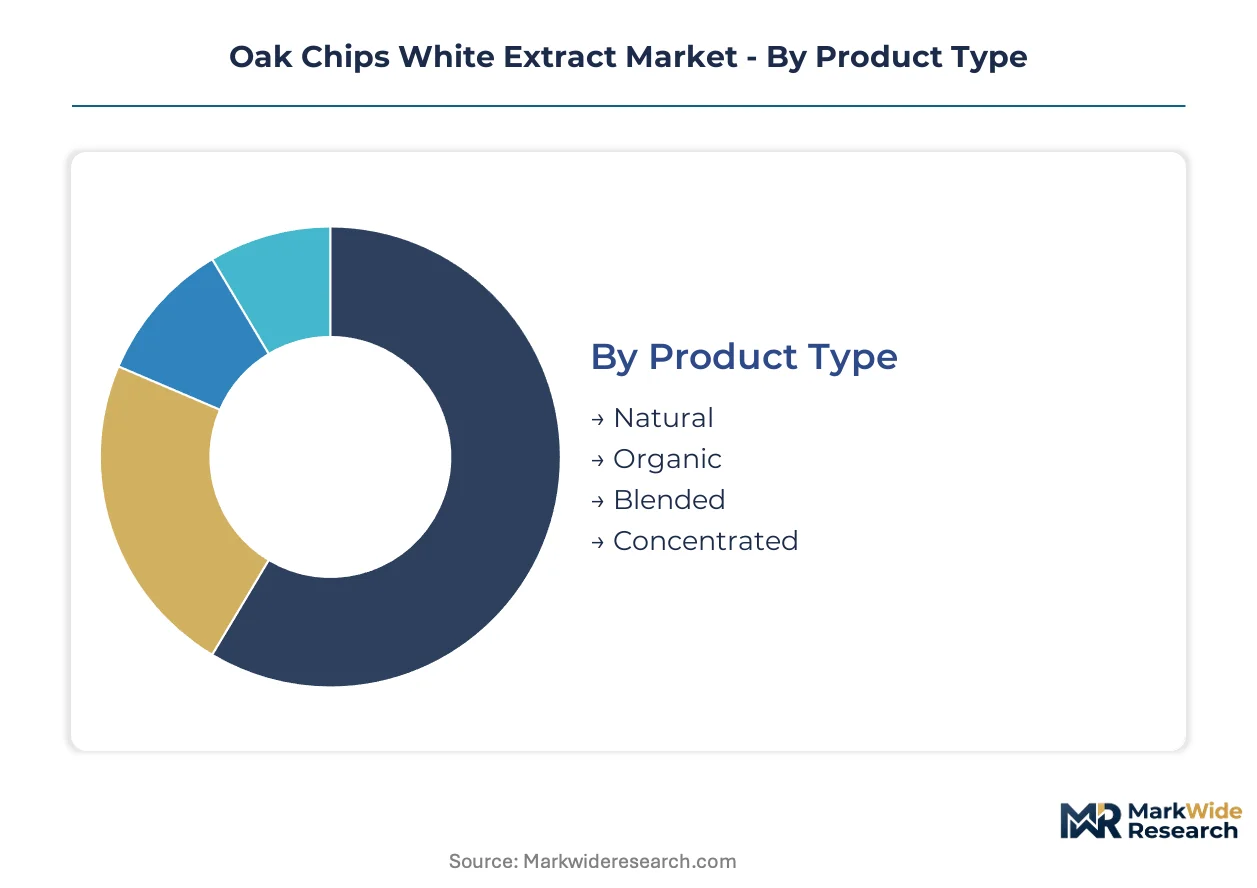
Oak chips white extract demand fragments across purity grades, regulatory jurisdictions, and end-use specifications. Each segment imposes distinct extraction protocols and documentation requirements that reshape supplier economics.
Product Type:
Supply concentration around Appalachian Quercus alba forests advantages processors with captive forestry and in-house toasting capabilities.
- Natural:Unadulterated extracts derived from steam distillation or ethanol extraction without synthetic additives. Beverage manufacturers in France's Cognac region specify natural grades to meet EU labeling requirements for spirit production.
- Concentrated:Standardized phenolic content through reduced solvent volume or vacuum concentration techniques. Cosmetic compounders in Germany and Switzerland purchase concentrated formats to achieve precise ellagitannin dosing in anti-aging formulations.
- Organic:Certified feedstock from USDA Organic or EU Organic managed forests with full chain-of-custody documentation.
- Blended:Custom ratios of toasted and untoasted oak extracts engineered for specific vanillin-to-eugenol balance.
Natural grades absorb the bulk of installed capacity; concentrated formats are expanding most quickly.
Application:
Margin structures diverge sharply between mature food channels and emerging cosmetic applications with stringent purity premiums.
- Flavors:Oak-derived vanillin, guaiacol, and whisky lactones for beverage and bakery applications. Kentucky bourbon distillers and French cognac houses specify toasted chip extracts to accelerate barrel-equivalent maturation profiles.
- Cosmetics:Polyphenol-rich fractions targeting antioxidant and anti-inflammatory claims. South Korean formulators are integrating oak ellagitannins into premium serum lines, pulling demand for pharmaceutical-grade extraction documentation.
- Fragrances:Woody base notes with provenance credentials for luxury perfumery. Grasse and Paris fragrance houses now require GPS-tracked forestry documentation.
- Food Industry:Established bakery and confectionery usage for vanilla enhancement and smoke flavoring.
Flavor applications command the largest volume commitments; cosmetics is climbing the fastest.
End User:
Procurement sophistication varies from spot-market purchasing by commodity food producers to multi-year contracts with integrated beverage groups.
- Beverage Manufacturers:Distillers and wineries seeking barrel-alternative maturation. Kentucky and Tennessee whiskey producers dominate North American procurement with specifications for fresh Quercus alba biomass.
- Cosmetic Companies:Formulators requiring ISO 17025-validated phenolic profiles and REACH-compliant solvent disclosure. German and Swiss contract manufacturers segregate production lines for pharmaceutical-grade output.
- Personal Care Brands:Mid-tier skincare and haircare marketers sourcing standardized extracts for natural positioning.
- Food Producers:Bakery and confectionery operations with established extract specifications and price-sensitive procurement.
Beverage manufacturers anchor contract volumes; cosmetic companies are gaining share fastest.
Distribution Channel:
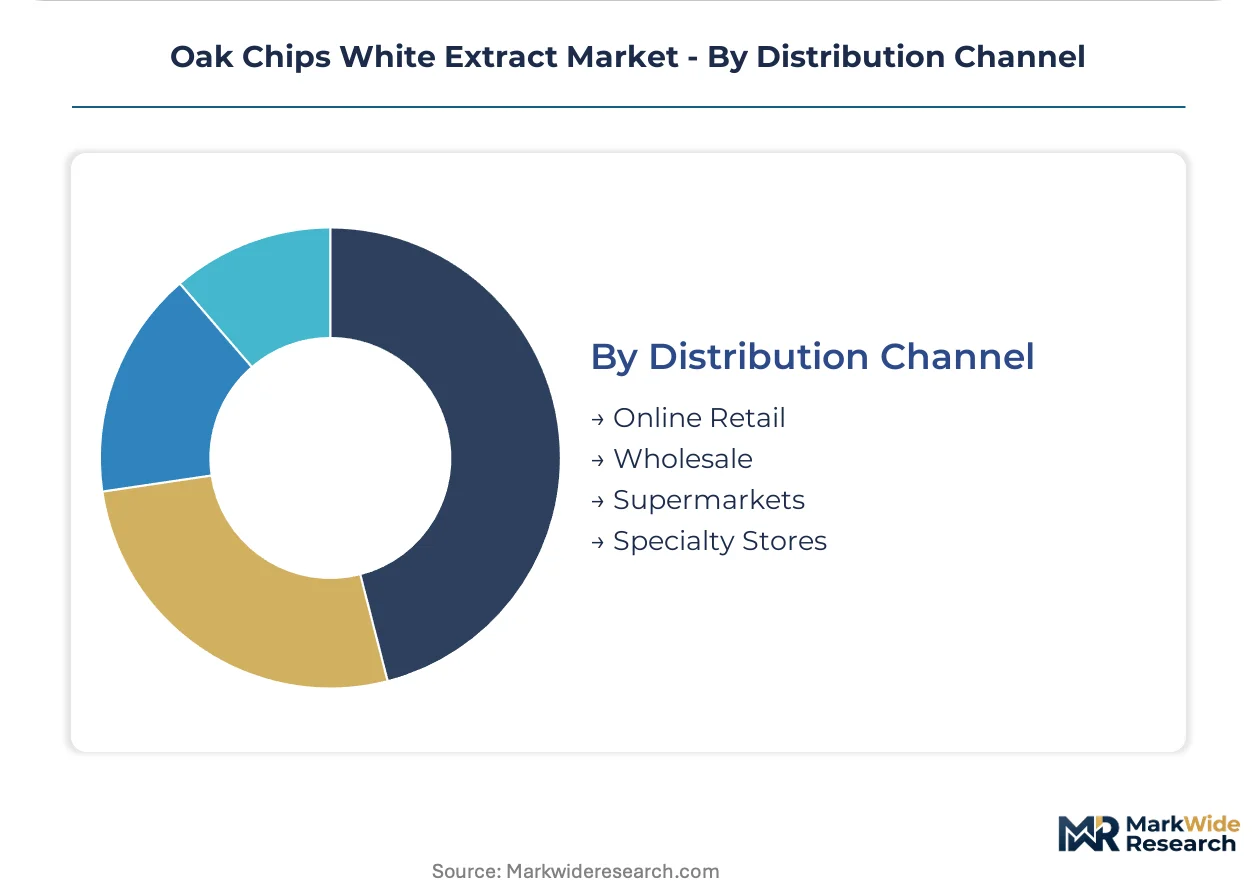
Channel selection reflects end-user scale, technical service requirements, and regulatory documentation needs.
- Wholesale:Bulk shipments to integrated processors and contract manufacturers with dedicated account management. The Vintner Vault and similar specialized distributors serve craft beverage producers with technical dosing support.
- Specialty Stores:Small-format retail for artisan distillers and experimental cosmetic formulators seeking trial quantities with batch-specific certificates of analysis.
- Online Retail:Direct-to-producer platforms with automated documentation downloads for REACH and FDA compliance.
- Supermarkets:Limited penetration given technical specification requirements and low consumer familiarity.
Wholesale channels handle the majority of tonnage; specialty stores are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian Opportunity Zones in Kentucky and Tennessee concentrate white oak processing through tax-advantaged forestry operations. Cognac's cooperage cluster anchors European extraction demand. South Korean cosmetic formulators are emerging as high-value import destinations.
United States
Kentucky bourbon distillers and Tennessee whiskey producers specify fresh Quercus alba biomass for barrel-alternative maturation. EPA air emission standards for volatile organic compound capture are forcing steam distillation retrofits with closed-loop condensation. The Appalachian hardwood belt around Knoxville and Louisville houses captive forestry assets and in-house toasting capabilities.
France
Cognac houses and Bordeaux wineries purchase natural-grade extracts to meet EU spirit labeling requirements. REACH Article 57 substance restrictions disqualify informal suppliers and consolidate volume with ECHA-registered processors. The Charente cooperage cluster surrounding Segonzac secures preferential access to fresh oak biomass before oxidative degradation.
Germany
Cosmetic compounders in Hamburg and Frankfurt seek standardized ellagitannin concentrations for anti-aging serum formulations. EMA botanical drug guidelines are opening pathways for oak extract submissions in topical anti-inflammatory indications. The Baden-Württemberg chemical processing corridor is segregating production lines for pharmaceutical-grade output.
South Korea
Seoul-based formulators are integrating oak-derived polyphenols into premium skincare lines, pulling demand for ISO 17025-validated phenolic profiles. MFDS cosmetic safety regulations require comprehensive phytochemical characterization for botanical active claims. The Songdo biocluster is attracting contract manufacturers with dedicated validation protocols for therapeutic-grade extraction.
Switzerland
Geneva and Basel fragrance houses require GPS-tracked forestry documentation and carbon footprint disclosure for woody base notes. Swissmedic guidelines for botanical drug intermediates exceed cosmetic-grade purity thresholds. The Givaudan-Firmenich supplier network around Geneva is consolidating relationships around extractors with documented provenance certification.
Oak Chips White Extract Market Competitive Landscape
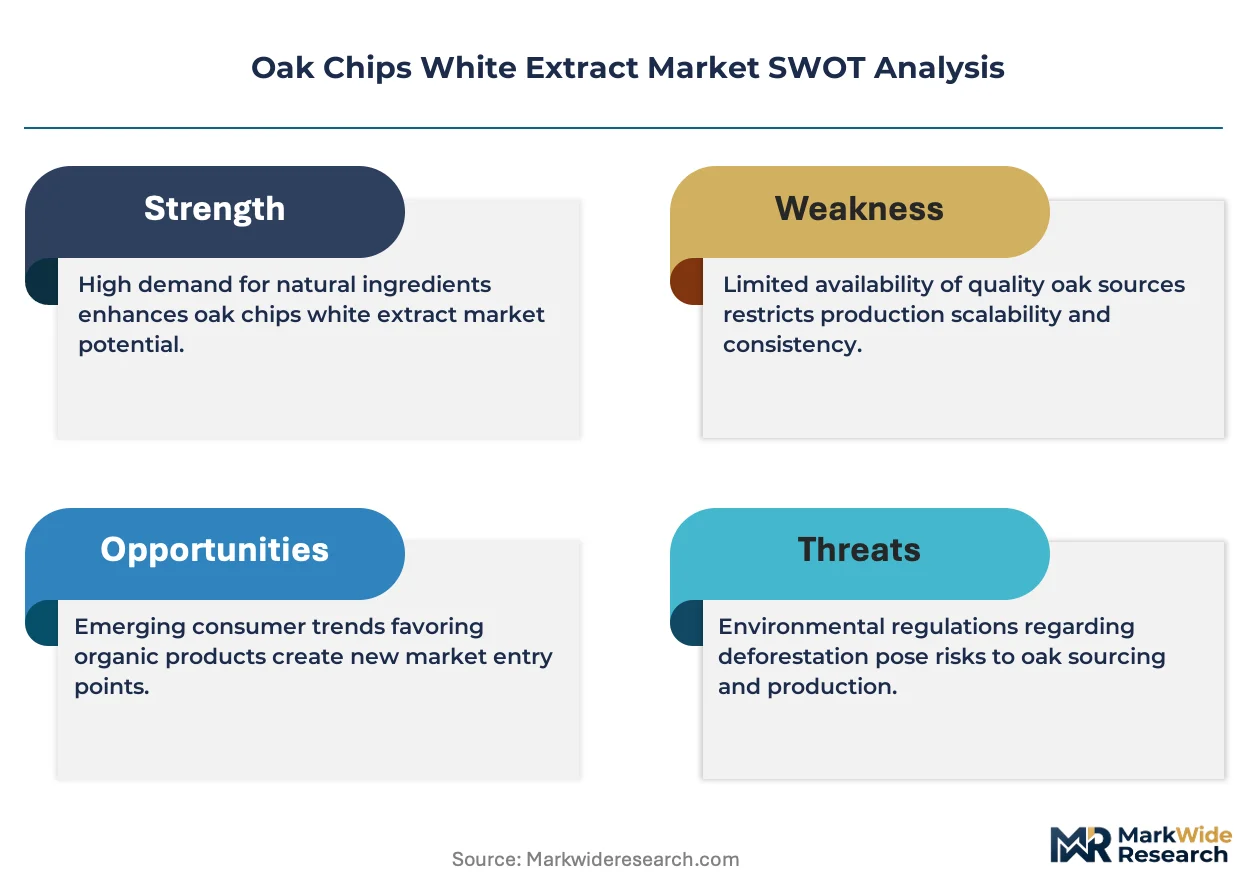
Appalachian producers anchor one tier; European cooperage-linked specialists hold another. The vendor base splits between captive forestry operators and toll extraction services. Three archetypes dominate: integrated forest-to-extract processors, regional cooperage affiliates, and cosmetic-grade purification specialists. Competitive moves center on backward integration into managed timberlands and technology licensing for supercritical CO2 systems.
Among integrated processors, White Oak exemplifies the captive forestry archetype through Appalachian asset control. The Vintner Vault occupies a position within specialized distribution to craft beverage producers, while Oak Solutions Group sits within technical service capabilities around extract dosing protocols. These three represent distinct competitive vectors—raw material security, channel specialization, and formulation support—rather than overlapping positioning.
| Leading Market Players |
|---|
| White Oak |
| The Vintner Vault |
| Rich Xiberta USA |
| The Barrel Mill |
| Canadell |
| Oak Solutions Group |
| Swiss Woodcraft |
| Oak Chips Inc |
| Seguin Moreau |
| Others |
Value Network & Pricing Analysis
Appalachian logging permit cycles transmit directly into three-tier pricing structure across premium, standard, and economy levels, with fresh Quercus alba biomass commanding premiums before oxidative degradation sets in. Beverage manufacturers in Kentucky and Cognac absorb these upstream cost movements through long-term offtake contracts that lock in preferential access to cooperage-linked feedstock.
Pricing Analysis
Short lead-time premiums separate emergency spot purchases from contracted annual volumes, with Kentucky bourbon distillers paying substantial markups for fresh biomass outside normal harvest windows. Price differentiation rests on REACH registration status and ISO 17025 certification tier, with ECHA-registered processors capturing margin premiums over informal competitors. Pricing pressure stems from laboratory-synthesized vanillin undercutting natural extracts in fragrance applications. Commodity food producers exhibit highest price sensitivity, while Swiss and South Korean cosmetic compounders prioritize phenolic consistency over unit cost.
Supply Chain Analysis
Transatlantic freight costs from eastern North American ports to European cooperage clusters impose working capital burdens that favor processors with bonded warehouse arrangements in Rotterdam and Hamburg. Geographic supply concentration centers on the United States, France, and Germany, with raw material dependencies spanning Appalachian Quercus alba forests, French cooperage trimmings, and German solvent recovery systems. Single-source vulnerability concentrates around eastern North American hardwood belts exposed to climate disruption. Distribution runs through wholesale channels with dedicated account management for integrated beverage groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Article 57 substance restrictions have erected a cost-of-compliance moat that consolidates volume with ECHA-registered processors and disqualifies informal suppliers from European market access.
For Market Incumbents: Anchor competitive position through captive forestry asset control in Appalachian Opportunity Zones and in-house supercritical CO2 extraction capabilities that reduce solvent waste. Synthetic vanillin substitution in fragrance applications threatens natural extract pricing; defend through backward integration into managed timberlands and exclusive cooperage partnerships around Segonzac and Louisville. For New Entrants and Emerging Players: Supercritical CO2 convergence with inline spectroscopic monitoring offers a technology-first wedge into mid-scale cosmetic processing where analytical rigor gaps persist. Target South Korean pharmaceutical-grade extraction demand and German contract manufacturing segregation for therapeutic-grade output. Lead with ISO 17025 validation capabilities and GPS-tracked forestry documentation to satisfy Grasse fragrance house procurement requirements. For Investors and Strategic Acquirers: EMA botanical drug guideline submissions for topical anti-inflammatory indications are the leading indicator that pharmaceutical-grade oak extracts will command sustained margin premiums. Five-to-ten year viability favors processors with segregated production lines and REACH-registered status. Acquisition targets should display captive Appalachian forestry assets paired with technical service capabilities around extract dosing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Managed Timberlands | Captive Quercus alba supply in Kentucky and Tennessee secures feedstock before oxidative degradation. |
| Supercritical CO2 Technology Licensing | German and Swiss cosmetic compounders adopt inline spectroscopy for real-time phenolic consistency. |
| REACH Registration and ECHA Compliance | Article 57 substance restrictions disqualify informal suppliers and consolidate European volume. |
| Pharmaceutical-Grade Production Line Segregation | EMA botanical drug guidelines open pathways for oak extract submissions in topical indications. |
| GPS-Tracked Forestry Documentation Programs | Grasse and Paris fragrance houses now require provenance certification and carbon footprint disclosure. |
Research Methodology
Multi-period observation of Appalachian logging permit cycles, REACH registration filings, and supercritical CO2 installation trends anchored the trend analysis, supplemented by interviews with extraction plant managers, cooperage procurement leads, cosmetic compounder R&D directors, and fragrance house raw material buyers. Secondary validation drew from ECHA substance registration databases, FDA food-contact substance filings, EMA botanical drug guidance documents, and ISO 17025 laboratory accreditation records. Bottom-up capacity modeling across Kentucky, Tennessee, and Charente processing facilities triangulated against top-down demand estimates from beverage, cosmetic, and fragrance end-use channels.
Segment-weighting approaches distributed value projections across natural, concentrated, organic, and blended product grades, with application-level modeling spanning flavors, cosmetics, fragrances, and food industry channels. End-user segmentation captured procurement sophistication differentials between Kentucky bourbon distillers, German contract manufacturers, and South Korean serum formulators. CAGRs were derived from installed capacity trajectories, regulatory compliance cost curves, and substitution elasticity estimates for synthetic versus natural vanillin across the analysis window.
Several conditions sit outside the modeled scope, including potential EPA revisions to volatile organic compound capture standards, MFDS cosmetic safety regulation amendments, and breakthrough advances in laboratory-synthesized woody base notes. Forecasts reflect assumptions about sustained REACH enforcement intensity and continued Appalachian hardwood availability. Stakeholders should weight assumptions against their own operating context and monitor EMA botanical drug submission outcomes as inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
China Soy Protein Market
Ingredients
Global Edible Oil Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Hops Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Glucuronolactone Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Vegetable Powder Market
Ingredients
North America Agar Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Feed Ingredients Market
Ingredients
Cacao Extracts Market
Ingredients
Bakery Ingredients Market
Ingredients
Citrus Based Dietary Fibers Market