
 Cacao Extracts Market | 2026-2036
Cacao Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Cacao Extracts Market Analytics
Functional beverage formulators are bifurcating demand away from conventional confectionery buyers as polyphenol-rich cacao extracts gain traction in sports nutrition and wellness positioning. Barry Callebaut leverages its integrated bean-to-extract infrastructure to supply standardized theobromine grades. Naturex (Givaudan) anchors European demand through its botanical extraction platform in France. Olam competes on origination scale, sustaining supply from Ghana and Ecuador into industrial extraction channels.
Cacao extracts comprise concentrated bioactive fractions—primarily flavanols, methylxanthines, and polyphenols—derived through solvent extraction, supercritical CO2 processing, or cold-pressing of fermented cacao beans, serving as functional ingredients for cardiovascular health claims and clean-label flavor modulation. Powder formats dominate pharmaceutical and supplement tableting due to shelf stability and dosing precision, while liquid concentrates lead in beverage applications where solubility and rapid dispersion matter. The dietary supplements application captures expanding margin pools as brands seek EFSA-backed health claim substantiation for flavanol content.
FDA GRAS self-determination governs U.S. cacao extract inclusion in foods, while EFSA Novel Food catalog listings and health claim opinions shape European market access and label permissibility. Organic and fair-trade certification requirements from USDA and EU organic frameworks increasingly filter supplier eligibility for premium channels. Stakeholders must monitor evolving methylxanthine threshold regulations and adapt extraction processes to preserve flavanol integrity under tightening purity standards.
Market Dynamics
The cacao extracts sector pivots on regulatory health claim substantiation, where EFSA Novel Food approvals and FDA GRAS determinations compress formulation timelines and determine which polyphenol concentrations command premium positioning.
Growth Catalysts
- EFSA Novel Food catalog expansion:The EU regulatory pathway now permits specific flavanol content claims, triggering dietary supplement brands to reformulate with standardized cacao polyphenol concentrates.
- Sports nutrition category pull:Functional beverage formulators in Switzerland and Germany are substituting synthetic caffeine with theobromine-rich cacao extracts for clean-label energy positioning.
- Supercritical CO2 extraction scale-up:Processing technology advances in France and Italy preserve heat-sensitive flavanol integrity, unlocking pharmaceutical-grade supply contracts.
Market Restraints
- Cocoa bean price volatility:Input costs fluctuate with West African supply disruptions and currency instability in Ghana and Côte d'Ivoire, squeezing extraction margin pools.
- EFSA health claim substantiation burden:The regulatory requirement for human intervention studies on cardiovascular endpoints extends product development cycles by 18-36 months.
- Green tea extract substitution:EGCG concentrates compete directly with cacao flavanols in antioxidant positioning, often at lower cost-per-active-unit.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland show minimal cacao extract adoption in functional foods despite high supplement consumption rates, creating first-mover positioning potential.
- Cosmeceutical topical applications:Polyphenol-rich cacao fractions are penetrating anti-aging skincare formulations, with French and Korean beauty brands piloting inclusion rates.
- EU organic certification alignment:The EU Green Deal's farm-to-fork sustainability mandates favor organic-certified extraction supply chains, rewarding early compliance investments.
Industry Challenges
- Analytical chemistry talent scarcity:Flavanol standardization and batch-to-batch consistency verification require specialized phytochemical expertise that extraction facilities struggle to recruit.
- Multi-jurisdictional compliance synchronization:Parallel FDA GRAS self-determination, EFSA Novel Food dossiers, and organic certification audits drain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cacao Extracts Market |
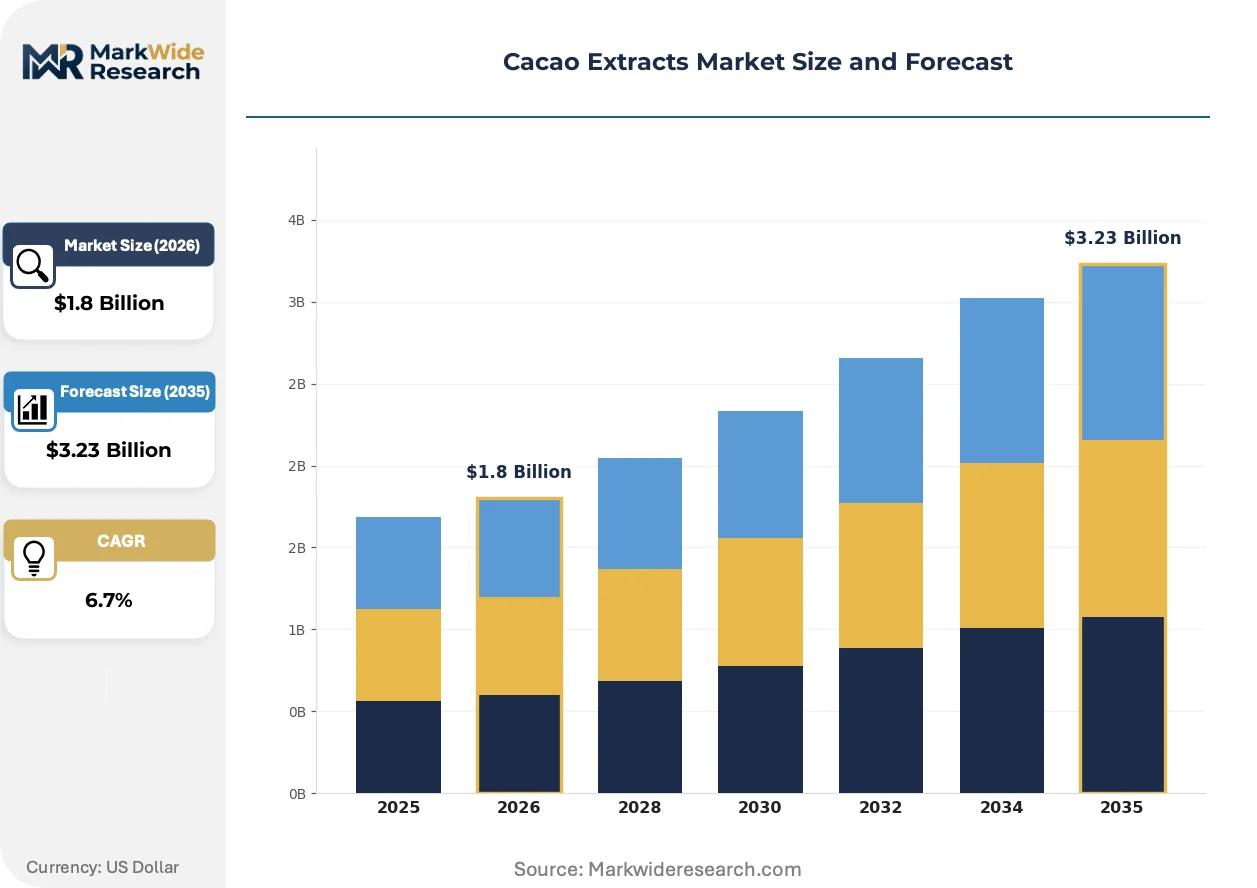
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Raw Material, Concentrate Application: Food & Beverage, Cosmetics, Pharmaceuticals, Dietary Supplements End User: Manufacturers, Retailers, Restaurants, Health Stores Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Naturex (Givaudan), Barry Callebaut, Olam, Cargill, ADM, Nexira, Indena, Sabinsa, Blommer Chocolate Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cacao Extracts Market Evolving Landscape
Extraction technology and regulatory science are converging to redefine which bioactive fractions achieve commercial scale, with process innovation outpacing health claim approval velocity.
Supercritical CO2 extraction is miniaturizing from industrial batch systems to modular skid-mounted units, enabling mid-sized botanical processors in Switzerland and Austria to enter pharmaceutical-grade supply without capital-intensive infrastructure. Regional supplement manufacturers are adopting these systems to secure captive flavanol supply chains. The technology is miniaturizing capital barriers that previously locked extraction capacity among integrated cocoa processors.
REACH registration requirements for novel solvent systems are tightening purity documentation standards for European extraction facilities, forcing processors to retire legacy hexane-based methods ahead of compliance deadlines. The regulation compresses operational flexibility but creates competitive separation for early adopters of green chemistry alternatives. German and Dutch extraction houses are accelerating supercritical and aqueous ethanol transitions to maintain EU market access.
Direct-procurement relationships between supplement brands and origin-country extraction facilities are displacing traditional trader-mediated supply chains, compressing margin capture at each intermediary layer. Swiss and German formulators now contract directly with Ecuadorian and Peruvian processors for single-origin flavanol certificates. This channel restructuring concentrates most visibly in premium positioning segments where traceability commands price premiums.
Cacao Extracts Market Segmentation
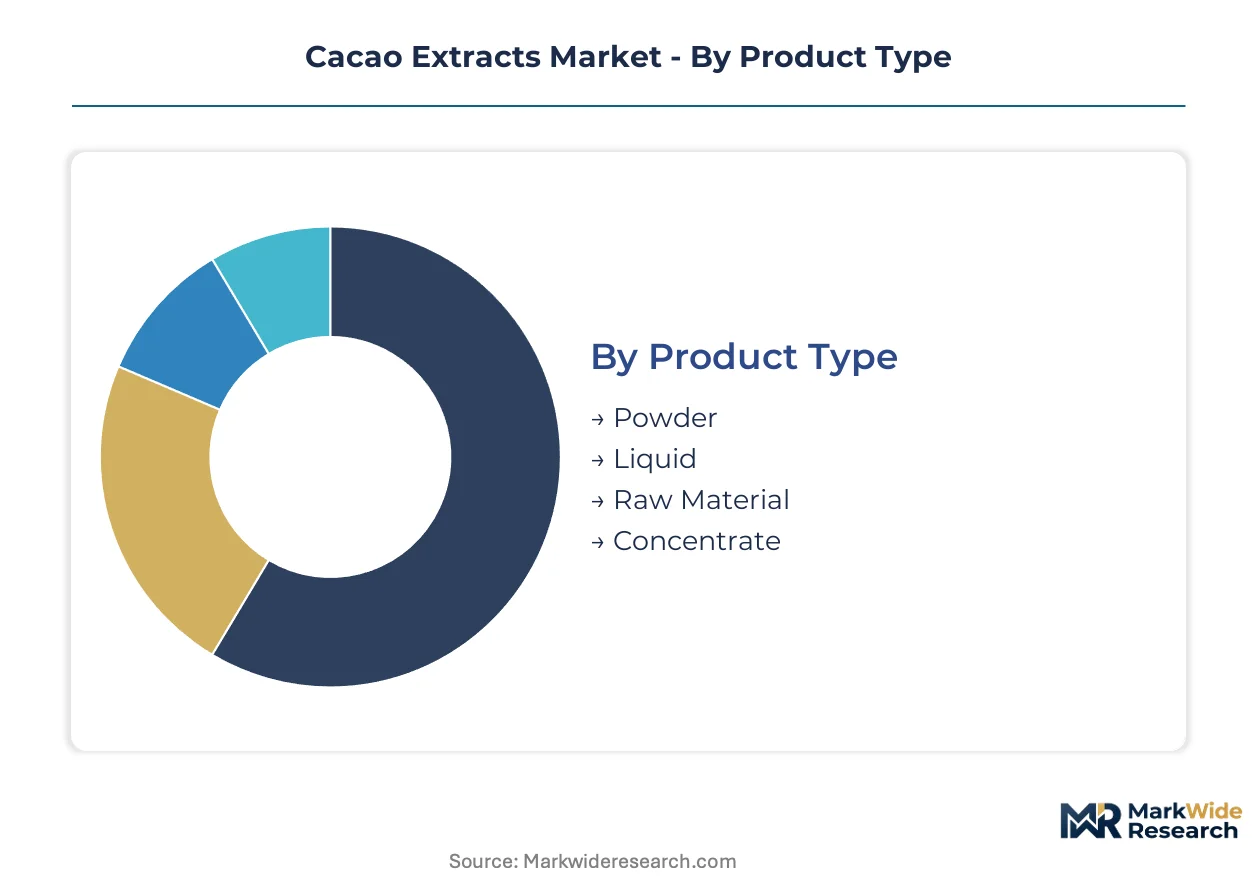
Cacao extract procurement patterns diverge sharply across product formats and end-use specifications. Pharmaceutical and nutraceutical buyers impose exacting flavanol standardization requirements that reshape supplier qualification criteria. Understanding segment-level margin distribution enables targeted positioning against EFSA Novel Food substantiation timelines and sports nutrition formulation trends.
Product Type:
Premium margin pools concentrate in standardized concentrates and pharmaceutical-grade powders where batch-to-batch consistency commands price premiums.
- Powder:Shelf-stable formats with precise dosing characteristics dominate supplement tableting and encapsulation workflows. Swiss and German pharmaceutical contract manufacturers specify minimum 10% flavanol content for cardiovascular health claim eligibility.
- Liquid:Rapid-dispersion concentrates serve functional beverage formulators seeking clean-label theobromine positioning. French and Italian processors leverage supercritical CO2 extraction to preserve heat-sensitive methylxanthine profiles for sports nutrition brands.
- Raw Material:Unprocessed cacao mass supplies industrial extraction facilities in Ghana and Ecuador.
- Concentrate:High-polyphenol fractions target cosmeceutical and premium supplement channels.
Powder holds installed capacity. Concentrate is rotating up the share rankings.
Application:
Volume concentration tilts toward food and beverage integration, though margin extraction favors segments with regulatory claim substantiation requirements.
- Dietary Supplements:EFSA-backed flavanol health claims trigger reformulation demand from brands seeking cardiovascular positioning. Swiss supplement houses commission single-origin certificates with specified theobromine-to-caffeine ratios.
- Food & Beverage:Clean-label energy applications in Germany and Austria substitute synthetic caffeine with cacao-derived methylxanthines. Barry Callebaut supplies standardized grades to functional beverage co-packers.
- Cosmetics:Polyphenol-rich fractions penetrate anti-aging skincare from French and Korean beauty formulators.
- Pharmaceuticals:Clinical-grade extracts require REACH-compliant solvent documentation and GMP certification.
Dietary Supplements captures the steepest expansion trajectory as EFSA opinions clarify label permissibility.
End User:
Procurement sophistication stratifies sharply between integrated manufacturers and fragmented retail channels.
- Manufacturers:Direct-contracting supplement brands and beverage co-packers specify origin certificates and flavanol standardization protocols. German formulators now bypass trader intermediaries for Ecuadorian single-origin supply.
- Retailers:Premium health food chains in Switzerland and Austria stock organic-certified SKUs with traceability documentation.
- Restaurants:Specialty chocolate artisans and functional food cafes source small-batch liquid concentrates.
- Health Stores:Independent supplement retailers emphasize USDA and EU organic certification badges.
Manufacturers dominate volume call-offs. Health Stores is climbing fastest on organic certification alignment.
Distribution Channel:
Channel restructuring compresses margin capture at intermediary layers as direct procurement displaces traditional trader mediation.
- Direct Sales:Swiss and German formulators contract origin-country processors for single-origin flavanol certificates, eliminating 2-3 intermediary markups. This channel concentrates in premium positioning segments.
- Wholesale:Industrial extraction facilities in France and Italy supply mid-sized botanical processors through volume-tiered contracts.
- Online:Supplement brands and specialty ingredient marketplaces serve small-batch formulators with minimum order quantities below wholesale thresholds.
- Offline:Traditional trader-mediated channels persist for commodity-grade raw material sourcing.
Direct Sales anchors premium tier volume. Online is gaining share fastest among emerging supplement brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana and Ecuador ship fermented cacao beans to Swiss and German extraction facilities, creating a trade corridor that concentrates premium flavanol processing in Alpine Europe while West African and Andean origins supply raw material streams.
Switzerland
Barry Callebaut and Givaudan operate integrated bean-to-extract facilities serving pharmaceutical and supplement manufacturers. Swissmedic oversees novel ingredient notifications for cosmeceutical applications. Zurich-Geneva corridor houses supercritical CO2 processing clusters supplying standardized theobromine grades to German beverage formulators.
Germany
Sports nutrition brands in Bavaria and North Rhine-Westphalia substitute synthetic caffeine with cacao-derived methylxanthines. REACH registration requirements for extraction solvents are tightening purity documentation standards. Hamburg extraction houses accelerate aqueous ethanol transitions to maintain EU market access ahead of compliance deadlines.
France
Botanical processors in Provence and the Rhône-Alpes region leverage supercritical CO2 technology to preserve heat-sensitive flavanol integrity. EFSA Novel Food catalog listings determine which polyphenol concentrations achieve premium positioning. Lyon-based extraction facilities supply pharmaceutical-grade certificates to Swiss contract manufacturers.
United States
Dietary supplement brands in California and New York commission GRAS self-determinations for cardiovascular health claim positioning. FDA enforcement discretion on methylxanthine thresholds shapes formulation ceilings. Chicago-area industrial processors supply commodity-grade extracts to Midwest beverage co-packers seeking clean-label energy positioning.
Ecuador
Single-origin cacao processors in Guayaquil and Quito bypass traditional trader intermediaries to contract directly with Swiss and German formulators. The country's national agricultural regulator certifies organic compliance for EU Green Deal alignment. Coastal extraction facilities are upgrading solvent systems to meet REACH-registered standards for European pharmaceutical contracts.
Cacao Extracts Market Competitive Landscape
Player mix skews toward integrated cocoa processors with captive extraction infrastructure. Tier concentration is pronounced at the premium end, where bean-to-extract capabilities command price premiums for standardized flavanol grades. Two strategic archetypes dominate: vertically integrated chocolate manufacturers backward-integrating into bioactive extraction, and specialized botanical extractors leveraging supercritical technology for pharmaceutical-grade supply. Dominant competitive moves include direct-procurement relationship formation with origin-country processors and supercritical CO2 capacity expansion to preserve heat-sensitive compound integrity.
Within the integrated-processor tier, Barry Callebaut and Naturex (Givaudan) exemplify the bean-to-extract archetype that anchors European supply. Olam occupies a position representing origination-scale players competing through Ghana and Ecuador supply chain control. These three companies collectively illustrate how market position depends on upstream raw material access married to downstream extraction technology deployment.
| Leading Market Players |
|---|
| Naturex (Givaudan) |
| Barry Callebaut |
| Olam |
| Cargill |
| ADM |
| Nexira |
| Indena |
| Sabinsa |
| Blommer Chocolate Company |
| Others |
Value Network & Pricing Analysis
EU organic certification requirements gate both supplier qualification and price differentiation simultaneously, filtering extraction facilities into premium channels while compressing margin capture for non-compliant processors. Swiss and German formulators pay premiums for single-origin certificates that satisfy farm-to-fork traceability mandates.
Pricing Analysis
Supercritical CO2 extraction commands price premiums over legacy solvent methods, while aqueous ethanol systems occupy mid-tier positioning and hexane-based processing faces cost compression from REACH compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade flavanol concentrates from beverage-grade methylxanthine fractions and commodity raw material supply. Price differentiation rests on certification tier and volume scale, with organic-certified batches capturing margins above conventional grades. Pricing pressure stems from cocoa bean cost volatility in Ghana and Côte d'Ivoire, squeezing extraction margin pools. Dietary supplement brands show least price sensitivity for EFSA-backed health claim substantiation, while industrial beverage co-packers drive hardest bargaining on commodity-grade inputs.
Supply Chain Analysis
Strategic stockpile preferences dominate Swiss and German pharmaceutical contract manufacturers, who secure multi-quarter flavanol concentrate contracts to buffer West African supply disruptions. Raw material flows concentrate in Ghana, Ecuador, and Côte d'Ivoire, feeding extraction facilities in Switzerland, Germany, and France. Processing infrastructure draws from fermented cacao beans, supercritical CO2 equipment, and REACH-compliant solvent systems. Single-source vulnerability runs through West African bean supply exposed to currency instability and climate disruption. Distribution runs through direct-procurement relationships that displace traditional trader mediation in premium positioning segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cacao extracts occupy early-cycle expansion as EFSA Novel Food catalog clarity triggers reformulation demand from dietary supplement brands seeking cardiovascular health claim positioning.
For Market Incumbents: Secure captive supply chains through backward integration into Ecuadorian and Peruvian origin processing, insulating margin pools from cocoa bean price volatility. Expand supercritical CO2 capacity in Swiss and Alpine European clusters to preserve heat-sensitive flavanol integrity for pharmaceutical-grade contracts. Certification investment in EU organic compliance creates competitive separation as Green Deal farm-to-fork mandates tighten. For New Entrants and Emerging Players: Differentiate on single-origin traceability certificates targeting Nordic markets where Sweden and Finland show minimal cacao extract adoption despite high supplement consumption rates. White-space concentration sits in cosmeceutical topical applications, where French and Korean beauty brands pilot polyphenol-rich cacao fractions. Go-to-market execution should leverage online channels serving small-batch formulators with minimum order quantities below wholesale thresholds. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated chocolate manufacturers seeking to monetize captive extraction infrastructure as standalone bioactive ingredient divisions. Long-term viability over the projection horizon rests on regulatory health claim substantiation velocity and supercritical technology scale-up economics. Watch EFSA Novel Food opinion issuance frequency as inflection indicator for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Alpine European processors preserve flavanol integrity for Swiss pharmaceutical contracts. |
| Direct-Procurement Relationship Formation | German formulators bypass trader intermediaries for Ecuadorian single-origin supply. |
| EU Organic Certification Alignment | Early compliance investments reward extraction facilities under Green Deal mandates. |
| Backward Integration into Origin Processing | Swiss incumbents secure captive supply from Ghana and Ecuador bean streams. |
| EFSA Health Claim Dossier Investment | Supplement brands unlock cardiovascular positioning through human intervention studies. |
Research Methodology
A standing panel of extraction facility technical directors, dietary supplement brand formulators, EFSA regulatory affairs consultants, and cocoa procurement managers provided ongoing calibration across primary fieldwork. Secondary validation drew from EFSA Novel Food catalog listings, REACH registration databases, EU organic certification registries, and customs trade flows for cacao-derived products. Bottom-up volume modeling triangulated against top-down market sizing from integrated processor disclosures.
Consistency checks validated outputs against external benchmarks including EFSA health claim opinion timelines and supercritical equipment installation records across European extraction houses. The analytical framework modeled product format, application segment, end-user sophistication, and distribution channel across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and regulatory approval velocity. Forecast inputs incorporated cocoa bean price volatility indices and methylxanthine threshold regulation evolution.
The analysis sits within stated boundaries; outcomes outside EFSA opinion issuance schedules or West African supply stability would require recalibration. Forecasts reflect assumptions on health claim substantiation timelines and extraction technology adoption curves. Revision becomes warranted when cocoa bean price volatility crosses thresholds that compress extraction margin pools below operational sustainability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Egg White Peptide Market
Ingredients
Global Dry Yeast Market
Ingredients
Meat Starter Culture Market
Ingredients
Yeast Peptide Market
Ingredients
Notoginseng Root Extract Market
Ingredients
Vegetable Glycerin Market
Ingredients
Corn Gluten Meal Market
Ingredients
Tapioca Market
Ingredients
China Soy Protein Market
Ingredients
Fermented Rennet Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Diastatic Malt Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Middle East and Africa Fermented Ingredients Market
Ingredients
Hops Market
Ingredients
Feed Ingredients Market