
 North America Agar Market | 2026-2036
North America Agar Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agar Market Analytics
The U.S. FDA's updated guidance on plant-derived excipients in pharmaceutical formulations is realigning procurement patterns across the region. Thermo Fisher Scientific Inc. leverages its distribution network to supply certified agar grades to research institutions throughout the Northeast. BD Biosciences dominates the clinical diagnostics segment with agar-based culture media manufactured under stringent quality protocols. Gelita AG anchors the food-grade segment with specialized stabilizer formulations for North American processed food manufacturers.
Agar is a hydrocolloid extracted primarily from red algae (Rhodophyta) of the Gelidium and Gracilaria genera, composed of agarose and agaropectin polysaccharides that gel at 32-45°C and melt at 85°C, functioning as an inert matrix for microbial culture, food stabilization, and pharmaceutical encapsulation. The microbiology application leads in value terms due to sustained R&D spending by pharmaceutical and academic end users, while the powder form occupies the largest volume share because of its handling efficiency in industrial-scale food processing. Research labs represent the fastest-growing end user category as federal funding for life sciences expands and cell-based assay protocols proliferate across the region.
The U.S. FDA and Health Canada/PMRA jointly shape market access through divergent but increasingly harmonized standards for food-grade hydrocolloids and pharmaceutical excipients, with FDA's GRAS self-affirmation pathway offering faster entry than Canada's pre-market notification system. The U.S. EPA's water quality monitoring mandates indirectly sustain demand for agar-based environmental testing media. Stakeholders must monitor how FDA's ongoing plant-derived material qualification initiatives reshape supplier certification requirements and whether Health Canada accelerates alignment with U.S. standards to streamline cross-border trade.
Market Dynamics
FDA's plant-derived excipient qualification initiatives are compressing certification timelines for pharmaceutical-grade agar while simultaneously disqualifying legacy animal-based alternatives across U.S. formulation facilities.
Growth Catalysts
- Biologics manufacturing scale-up:Cell culture media consumption is accelerating as U.S. pharmaceutical producers expand monoclonal antibody and vaccine production capacity. Agar's inert matrix properties satisfy serum-free and chemically defined media specifications.
- EPA water quality mandates:Environmental monitoring protocols require standardized agar-based culture media for coliform and pathogen detection across municipal water systems. Testing volume scales with infrastructure investment cycles.
- Health Canada-PMRA harmonization pressure:Cross-border regulatory alignment is streamlining excipient documentation for suppliers serving both U.S. and Canadian pharmaceutical markets. Dual-market certification costs are declining.
Market Restraints
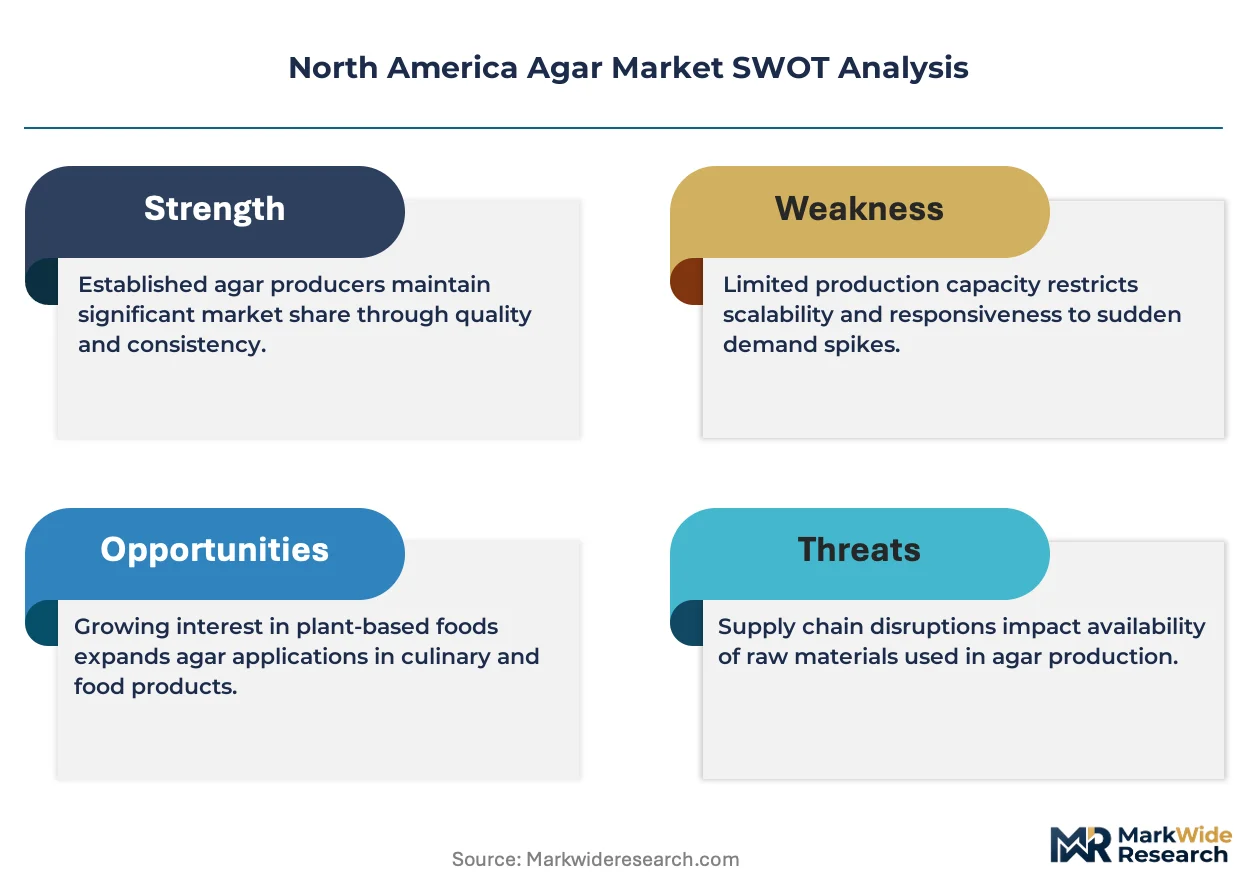
- Red algae supply concentration:Raw material sourcing clusters in specific coastal zones of Chile, Morocco, and Indonesia. Climate variability and harvest licensing restrictions create input volatility for North American processors.
- Carrageenan substitution in food applications:Lower-cost hydrocolloids compete for stabilizer and gelling functions in processed foods. Price-sensitive manufacturers in mass-market segments switch where formulation flexibility permits.
- FDA's evolving documentation burdens:Plant-derived material qualification requires extensive supply chain traceability and contaminant testing. Smaller suppliers face disproportionate compliance costs relative to revenue base.
Strategic Opportunities
- Cell-based assay proliferation:Three-dimensional cell culture and organoid research is opening high-margin specialty agar formulations. Research institutions in California's biotechnology corridor represent concentrated early demand.
- Clean-label food positioning:Consumer packaged goods brands are reformulating around recognizable, plant-derived ingredients. Agar's algae origin supports natural positioning claims in premium frozen desserts and plant-based alternatives.
- Direct-to-laboratory distribution platforms:E-procurement channels are disintermediating traditional chemical distributors for research-grade materials. Specialized agar grades with batch-specific certificates of analysis command price premiums through digital channels.
Industry Challenges
- Phycocolloid extraction expertise scarcity:Skilled technicians capable of optimizing agarose yield and gel strength from variable raw material inputs are concentrated among legacy processors. Workforce development lags capacity expansion plans.
- Multi-jurisdictional certification synchronization:Pharmaceutical excipient suppliers must maintain concurrent FDA Drug Master Files, Health Canada establishment licenses, and NSF food-grade registrations. Audit scheduling and documentation versioning create operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agar Market |
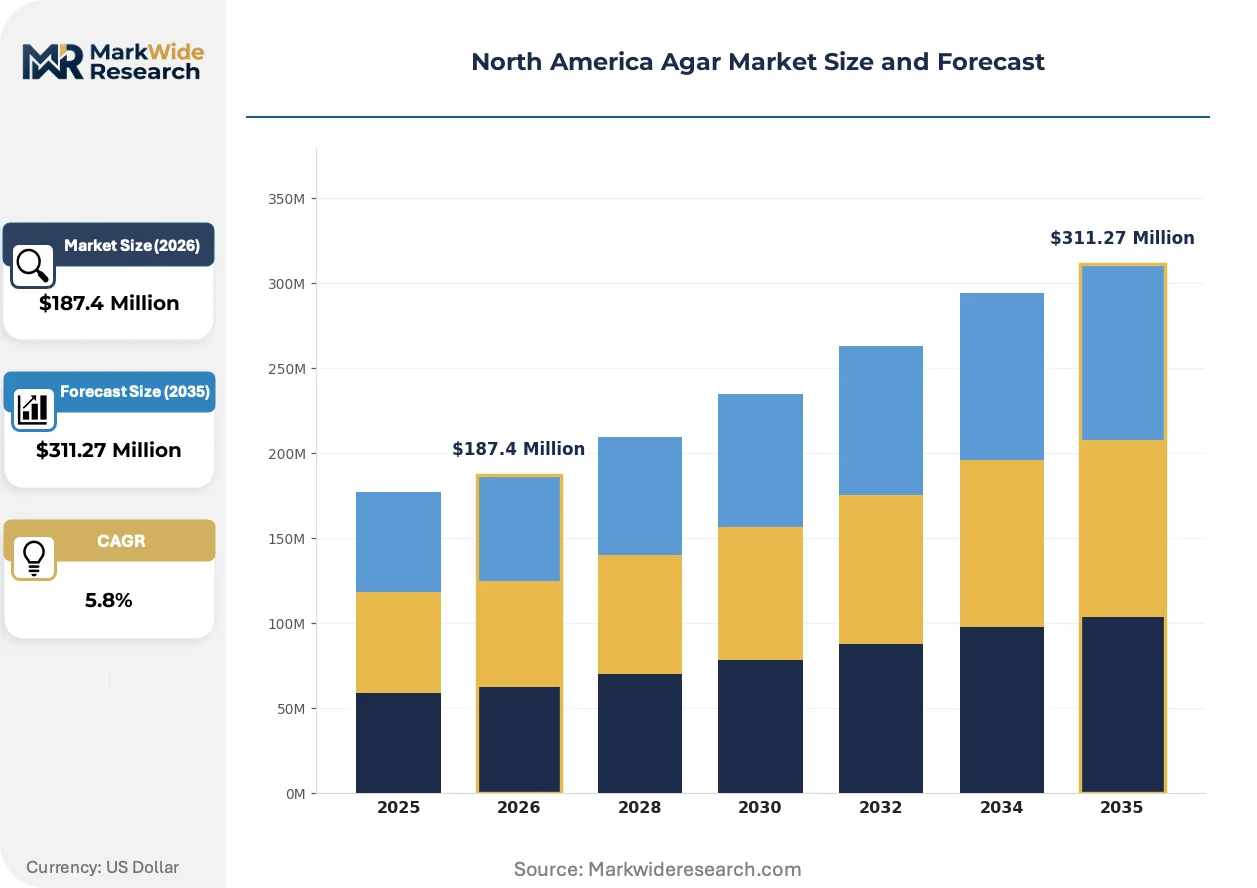
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Industry, Pharmaceuticals, Cosmetics, Microbiology Form: Powder, Sheets, Granules, Capsules Product Type: Vegetarian, Gelatinous, Stabilizers, Thickening Agents End User: Food Manufacturers, Research Labs, Cosmetic Companies, Academic Institutions |
| Companies Covered | Hispanagar USA LLC, Sobigel North America, Agarmex USA Corp., Green Fresh Group, Merck KGaA, Thermo Fisher Scientific Inc., BD Biosciences, ROKO, Gelita AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agar Market Evolving Landscape
Process intensification in red algae processing and precision fermentation alternatives are compressing traditional extraction economics while regulatory data requirements for plant-derived materials expand.
Low-temperature agar extraction protocols using enzyme-assisted cell wall disruption are rewriting yield-efficiency benchmarks for Gracilaria processing. California-based biotechnology firms are piloting these methods to secure higher gel-strength product from lower-grade feedstock. The technology is compressing the cost gap between food-grade and pharmaceutical-grade production lines.
Health Canada-PMRA's pre-market notification system for novel food ingredients is tightening relative to FDA's GRAS self-affirmation pathway. Canadian suppliers face extended review timelines for agar-based functional ingredients in fortified foods. Reformulation decisions increasingly bifurcate by destination market rather than pursuing unified North American product specifications.
Research institutions are consolidating purchasing through group procurement organizations to secure volume-tier pricing on cell culture media components. The Northeast pharmaceutical belt's university consortia negotiate master service agreements directly with certified agar producers. This channel compression is squeezing traditional laboratory supply distributors' margin capture on high-purity grades.
North America Agar Market Segmentation
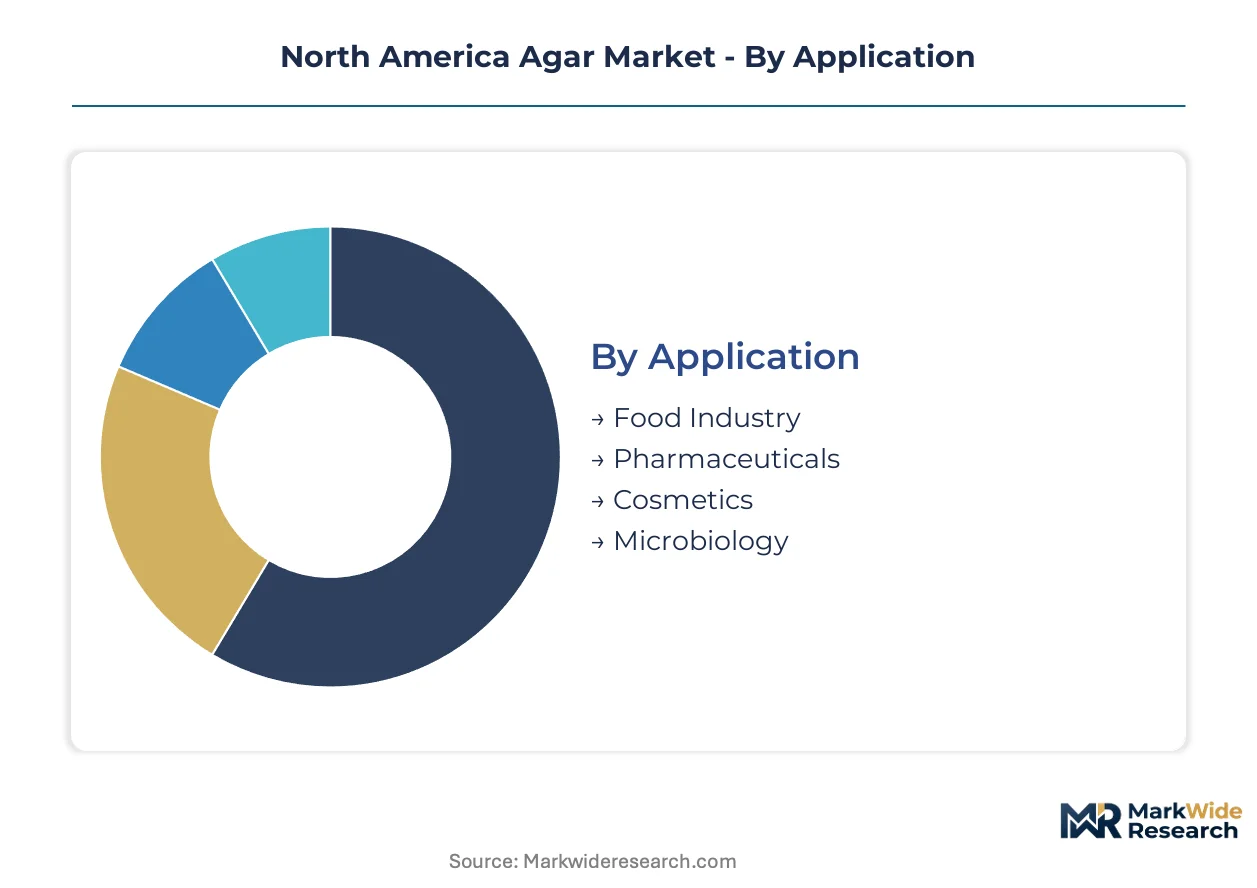
Segmentation in the North America Agar Market reveals how procurement decisions bifurcate between pharmaceutical-grade certification requirements and food-grade cost optimization. Buyers prioritize gel strength specifications in cell culture applications while emphasizing clean-label positioning in consumer packaged goods.
Application:
Formulation performance requirements determine grade selection and supplier qualification intensity across end-use categories.
- Microbiology:Cell culture media demand concentrates on serum-free and chemically defined specifications. Research institutions in California's biotechnology corridor and the Northeast pharmaceutical belt drive procurement volume for high-purity agarose fractions.
- Pharmaceuticals:FDA's plant-derived excipient qualification initiatives are compressing certification timelines. U.S. formulation facilities are disqualifying legacy animal-based alternatives, redirecting procurement toward certified agar grades with extensive supply chain traceability documentation.
- Food Industry:Clean-label positioning supports premium frozen desserts and plant-based alternatives. Consumer packaged goods brands leverage agar's algae origin for natural ingredient claims in reformulated products.
- Cosmetics:Stabilizer applications in premium skincare formulations require low-impurity grades with batch-specific certificates of analysis.
Microbiology leads on scale; Pharmaceuticals leads on momentum.
Form:
Handling efficiency and dissolution characteristics shape manufacturing integration decisions across processing scales.
- Powder:Industrial-scale food processing facilities prioritize powder for metering accuracy and storage density. California-based processed food manufacturers specify powder grades for automated stabilizer dosing systems in frozen dessert production lines.
- Granules:Dust-reduced handling properties suit pharmaceutical cleanroom environments. Northeast contract manufacturing organizations specify granule forms for excipient blending operations with controlled particle size distribution.
- Sheets:Traditional format persists in artisanal food preparation and educational laboratory settings requiring visual quality assessment.
- Capsules:Pre-measured units serve small-batch cosmetic formulators and research laboratories with intermittent agar consumption patterns.
Powder dominates volume throughput; Granules command the steepest expansion trajectory in pharmaceutical channels.
Product Type:
Functional claims and dietary positioning determine premium capture potential in ingredient specification.
- Vegetarian:Algae-derived origin satisfies kosher, halal, and vegan certification requirements simultaneously. Plant-based meat alternative manufacturers in the U.S. specify vegetarian agar for texture modulation in reformulated products.
- Stabilizers:Gel strength consistency supports freeze-thaw stability in premium ice cream formulations. Food-grade processors prioritize stabilizer grades with standardized viscosity profiles across production batches.
- Thickening Agents:Lower gel strength variants serve sauce and beverage applications requiring pourable consistency at refrigerated temperatures.
- Gelatinous:High-gel strength fractions command specialty pricing in confectionery and pharmaceutical encapsulation segments.
Vegetarian claims capture the widest addressable market; Stabilizers generate the highest margin per kilogram in food applications.
End User:
Procurement sophistication and volume scale separate institutional buyers from commercial manufacturing accounts.
- Research Labs:Federal funding expansion for life sciences is proliferating cell-based assay protocols. University consortia in the Northeast pharmaceutical belt negotiate master service agreements directly with certified agar producers, compressing distributor margins.
- Food Manufacturers:Mass-market processors balance carrageenan substitution pressure against clean-label premium positioning. Reformulation decisions increasingly bifurcate by destination market rather than pursuing unified North American product specifications.
- Academic Institutions:Group procurement organizations consolidate purchasing to secure volume-tier pricing on teaching-grade materials.
- Cosmetic Companies:Small-batch formulators prioritize direct-to-laboratory distribution platforms with batch-specific documentation.
Food Manufacturers anchor absolute volume; Research Labs are gaining share fastest through federal R&D investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled phycocolloid extraction technicians cluster along coastal processing zones and pharmaceutical manufacturing belts, anchoring regional capacity expansion across North America.
United States
Biologics manufacturing scale-up and EPA water quality monitoring mandates drive pharmaceutical-grade and environmental testing agar consumption. FDA's plant-derived excipient qualification initiatives compress certification timelines while disqualifying animal-based alternatives. California's biotechnology corridor and the Northeast pharmaceutical belt concentrate research institution procurement through direct manufacturer agreements.
Canada
Health Canada-PMRA harmonization pressure with U.S. standards streamlines cross-border excipient documentation for dual-market suppliers. The pre-market notification system for novel food ingredients extends review timelines for agar-based functional ingredients relative to FDA's GRAS pathway. Ontario and Quebec pharmaceutical manufacturing clusters prioritize certified grades with concurrent FDA Drug Master Files and Health Canada establishment licenses.
Mexico
Processed food manufacturing expansion in northern border states generates stabilizer demand for clean-label reformulations targeting U.S. export markets. COFEPRIS alignment with FDA food additive standards accelerates ingredient approval synchronization. Jalisco and Nuevo León food processing corridors adopt agar for premium frozen dessert and plant-based alternative production lines.
North America Agar Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across certification-intensive pharmaceutical channels and price-sensitive food applications. The vendor base separates into three tiers: multinational life sciences conglomerates with integrated excipient portfolios, specialized hydrocolloid processors with red algae sourcing control, and regional distributors serving research laboratories. Consolidation pressures concentrate among mid-scale processors lacking vertical integration into raw material supply. Dominant competitive moves include strategic partnerships for certified grade distribution and portfolio diversification into specialty cell culture formulations.
Among U.S.-based distributors, Thermo Fisher Scientific Inc. anchors research-grade supply networks through direct institutional agreements. BD Biosciences exemplifies the clinical diagnostics archetype with stringent quality protocol manufacturing. German-origin Merck KGaA and Gelita AG occupy positions spanning pharmaceutical excipient and food-grade stabilizer segments, representing the multinational integrated portfolio archetype.
| Leading Market Players |
|---|
| Hispanagar USA LLC |
| Sobigel North America |
| Agarmex USA Corp. |
| Green Fresh Group |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| BD Biosciences |
| ROKO |
| Gelita AG |
| Others |
Value Network & Pricing Analysis
EPA water quality monitoring mandates gate access to both qualified agar supply and premium-tier pricing for environmental testing grades. Pharmaceutical-grade certification requirements compress margins for uncertified suppliers while concentrating pricing power among FDA Drug Master File holders serving biologics manufacturers.
Pricing Analysis
The bundled-vs-unbundled service split separates pharmaceutical-grade agar with traceability documentation from commodity food-grade powder. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with FDA-qualified grades commanding substantial premiums over food stabilizer tiers. Cost compression in standard food-grade segments is intensifying because carrageenan substitution erodes volume leverage. Mass-market food processors exhibit highest price sensitivity; cell culture media buyers prioritize batch consistency over unit cost.
Supply Chain Analysis
Skilled phycocolloid extraction technicians concentrate in Chile, Morocco, and Indonesia's coastal processing zones, anchoring raw material supply for North American processors. Red algae harvests from Gelidium and Gracilaria species feed into agarose and agaropectin separation lines, with yield variability hinging on seasonal climate patterns. Single-source vulnerability runs through Indonesian licensing restrictions that periodically constrain Gracilaria export volumes. Distribution runs through multinational life sciences distributors for pharmaceutical channels and regional food ingredient brokers for industrial stabilizer accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in North American agar hinges on enzyme-assisted extraction cost-down curves and the premium-tier shift toward serum-free cell culture specifications. The structural transition from animal-derived to plant-derived excipients creates pricing power for qualified suppliers.
For Market Incumbents: Anticipate carrageenan displacement in mass-market food stabilizers by accelerating clean-label positioning investments and securing multi-year supply agreements with California biotechnology corridor research institutions. Backward integration into Chilean red algae harvesting operations mitigates input volatility from climate-driven yield fluctuations. FDA qualification documentation serves as the priority defensive moat against emerging specialty grade competitors. For New Entrants and Emerging Players: Direct-to-laboratory e-procurement platforms offer the most penetrable route into research-grade agar segments underserved by traditional distributor markups. Target small-batch cosmetic formulators and regional academic consortia with batch-specific certificates of analysis and rapid fulfillment guarantees. A digital-first go-to-market angle compresses customer acquisition costs relative to field sales-dependent incumbents. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hydrocolloid processors because multi-jurisdictional certification synchronization creates operational overhead that favors consolidated documentation management. The viable acquisition window spans five to ten years as biologics manufacturing scale-up sustains pharmaceutical-grade demand growth. Watch for FDA acceleration of plant-derived material qualification timelines as the inflection signal for premium-tier pricing power expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Assisted Extraction Scale-Up | California biotechnology firms piloting low-temperature protocols rewrite yield-efficiency benchmarks for Gracilaria processing. |
| FDA Drug Master File Investment | Concurrent Health Canada establishment licensing streamlines cross-border excipient documentation for dual-market suppliers. |
| Direct Institutional Distribution Agreements | Northeast university consortia negotiating master service agreements compress traditional laboratory supply distributor margins. |
| Clean-Label Stabilizer Reformulation | Premium frozen dessert manufacturers leverage agar's algae origin for natural ingredient positioning claims. |
| Red Algae Harvest Licensing Control | Chilean and Moroccan coastal zone permits secure captive supply of Gelidium species for high-gel-strength pharmaceutical grades. |
Research Methodology
Direct dialogue with pharmaceutical formulation scientists, food industry procurement directors, red algae processing plant managers, and research laboratory supply coordinators grounded the qualitative foundation. Secondary validation drew from FDA GRAS notifications, Health Canada pre-market submissions, EPA water quality monitoring protocols, and U.S. customs import records for phycocolloid trade flows. Bottom-up and top-down triangulation cross-checked segment-level consumption patterns against macroeconomic indicators for biologics manufacturing investment cycles.
Bottom-up modeling aggregated end-use consumption across microbiology, pharmaceutical, food, and cosmetic applications, while top-down verification tracked raw material import volumes and processor capacity utilization rates. Segmentation dimensions included application type, form factor, product grade certification, and end-user procurement sophistication. CAGRs were derived from regression analysis of historical consumption trends and forward projections of federal R&D funding cycles and biologics manufacturing capacity expansion announcements.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation-derived hydrocolloids would alter the outlook for traditional red algae extraction economics. Forecasts reflect assumptions regarding sustained EPA monitoring mandates and FDA plant-derived excipient qualification trajectory. Material deviation in biologics manufacturing investment cycles or red algae harvest licensing restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pea Hull Fiber Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Potato Fiber Market
Ingredients
Global Pulse Flours Market
Ingredients
Almond Ingredients Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Sodium Caseinate Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Wheat Starch Derivative Market
Ingredients
Fish Gelatin Market
Ingredients
Food Grade Linseed Oil Market
Ingredients
Gymnema Extract Market
Ingredients
Boysenberry Extract Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Confectionery Ingredients Market