
 Global Virtual Private Server Market | 2026-2036
Global Virtual Private Server Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Private Server Market Foresight
Fragmentation among digital agencies and indie game studios is repositioning procurement patterns across the VPS landscape. Amazon Web Services leverages its hyperscale infrastructure to dominate enterprise-grade managed hosting. DigitalOcean anchors developer-centric workflows with streamlined deployment tools. OVHcloud competes through European data sovereignty and competitive pricing on bare-metal alternatives.
A virtual private server partitions a physical server into isolated environments with dedicated CPU cores, RAM allocations, and root access for each tenant. This architecture delivers predictable performance for workloads requiring customization beyond shared hosting without the cost of full dedicated servers. Managed VPS solutions command premium positioning as IT enterprises outsource infrastructure maintenance, while cloud VPS offerings capture fastest expansion among startups needing elastic scaling. Application development and e-commerce deployments concentrate margin pools where low-latency requirements justify higher compute tiers.
FDA guidelines on healthcare data integrity, GDPR data residency rules, and China's GB standards on cross-border data flows collectively shape compliance-driven purchasing decisions across the VPS sector. ISO 27001 certification has become a baseline qualifier for vendor shortlists in financial services and government procurement. Stakeholders must weigh regional regulatory divergence against the operational complexity of multi-jurisdiction infrastructure footprints.
Market Dynamics
Data localization mandates across Germany, India, and Brazil are fragmenting infrastructure deployment patterns, forcing providers to establish sovereign compute clusters rather than centralized hyperscale regions.
Growth Catalysts
- EU AI Act compliance:Enterprises processing sensitive AI workloads are migrating from public cloud to managed private VPS environments to satisfy algorithmic transparency and data governance requirements.
- Container orchestration:Kubernetes-native VPS platforms are capturing developer workflows previously locked into proprietary serverless ecosystems.
- Brazil's data residency enforcement:ANPD penalties for cross-border data transfers are accelerating local VPS procurement among fintech and healthtech startups.
Market Restraints
- Energy cost volatility:European VPS providers face margin compression from natural gas-driven electricity price spikes affecting Frankfurt and Amsterdam data centers.
- Hardware supply concentration:Taiwan-based semiconductor foundries create single-point-of-failure risk for high-core-count VPS node provisioning.
- IPv4 address exhaustion:Regional internet registries are rationing remaining blocks, inflating provisioning costs for multi-tenant environments.
Strategic Opportunities
- India's PLI scheme for data centers:Government incentives for domestic cloud infrastructure are opening greenfield VPS deployment zones in Mumbai and Hyderabad.
- Edge-AI convergence:GPU-enabled VPS instances at 5G network edges are enabling real-time inference for autonomous systems and industrial IoT.
- Subscription billing platforms:Usage-based pricing APIs are displacing traditional monthly VPS contracts among SaaS-native buyers.
Industry Challenges
- Certification timeline compression:ISO 27001 and SOC 2 Type II audit cycles are extending 40% as assessor capacity fails to match enterprise demand.
- Legacy workload migration:Mainframe-dependent financial institutions face integration friction when containerizing COBOL-based applications onto Linux VPS environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Private Server Market |
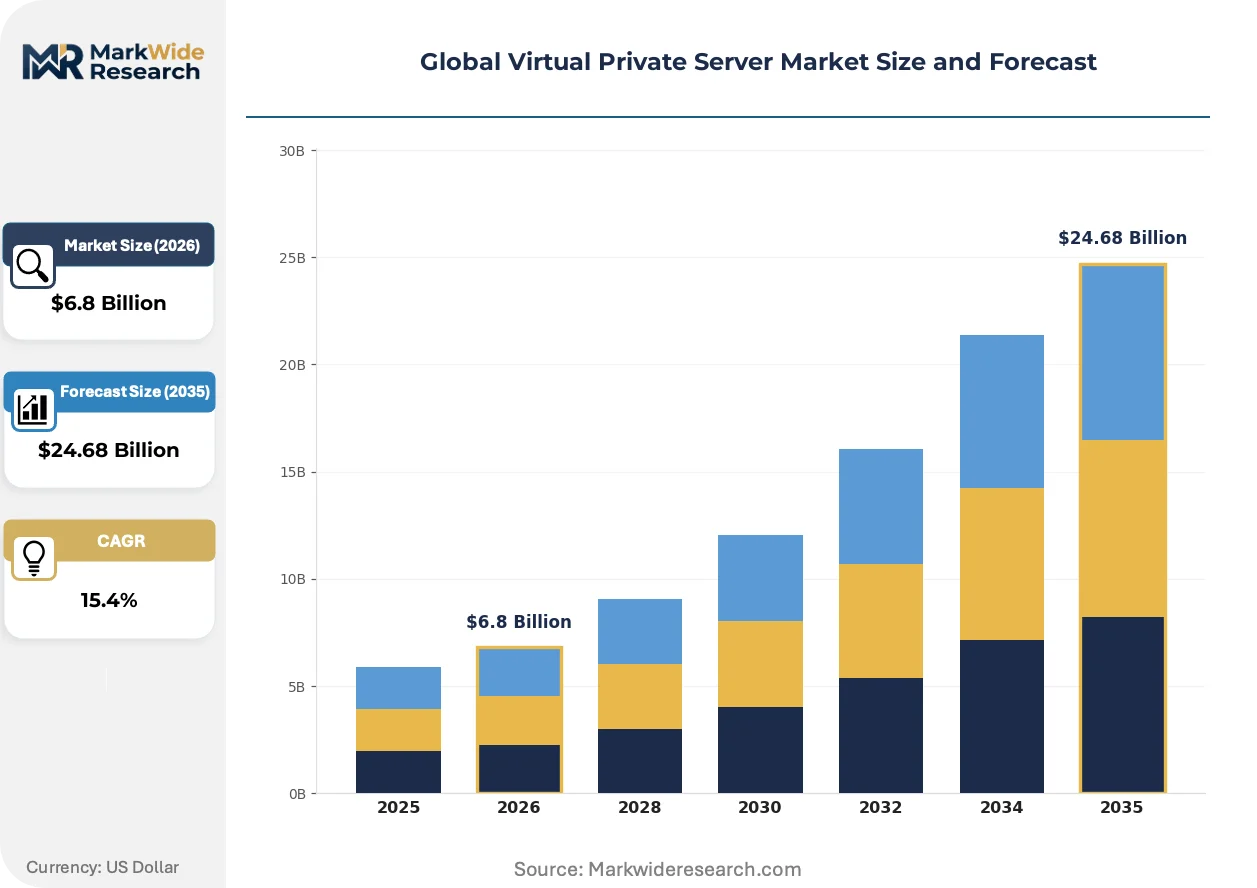
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $24.68 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Managed Hosting Solution: Managed VPS, Unmanaged VPS, Cloud VPS, Dedicated VPS Application: Web Hosting, E-commerce, Game Hosting, Application Development, Database Management End User: Startups, SMEs, IT Enterprises, Digital Agencies, Government Organizations |
| Companies Covered | Amazon Web Services, DigitalOcean, OVHcloud, GoDaddy, A2 Hosting, Liquid Web, Rackspace Technology, InMotion Hosting, DreamHost, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Private Server Market Shifts & Advancements
Lightweight virtualization technologies are compressing provisioning overhead while sovereign data requirements are reshaping where compute physically resides.
ARM-based server architectures are overtaking x86 dominance in power-constrained European facilities. Hyperscale operators and boutique hosters alike are deploying Ampere Altra and AWS Graviton processors to reduce per-workload energy consumption. This shift is overtaking traditional Intel and AMD procurement patterns in sustainability-sensitive segments.
China's GB standards on cross-border data flows are forcing multinational enterprises to architect separate VPS instances for domestic versus international user bases. The MIIT enforcement mechanism requires localized data storage for personal information collected within mainland borders. Financial services and automotive OEMs are responding by establishing captive VPS deployments in Shanghai and Beijing zones.
Developer purchasing committees are displacing centralized IT procurement for infrastructure decisions. Engineering-led organizations now evaluate VPS providers through API ergonomics and CI/CD integration depth rather than enterprise sales relationships. This pattern concentrates in venture-backed startups across Berlin, Bangalore, and São Paulo.
Global Virtual Private Server Market Segmentation
VPS procurement patterns diverge sharply across deployment architectures and buyer sophistication levels. Segmentation reveals where infrastructure investments concentrate and which customer profiles drive margin expansion.
Deployment:
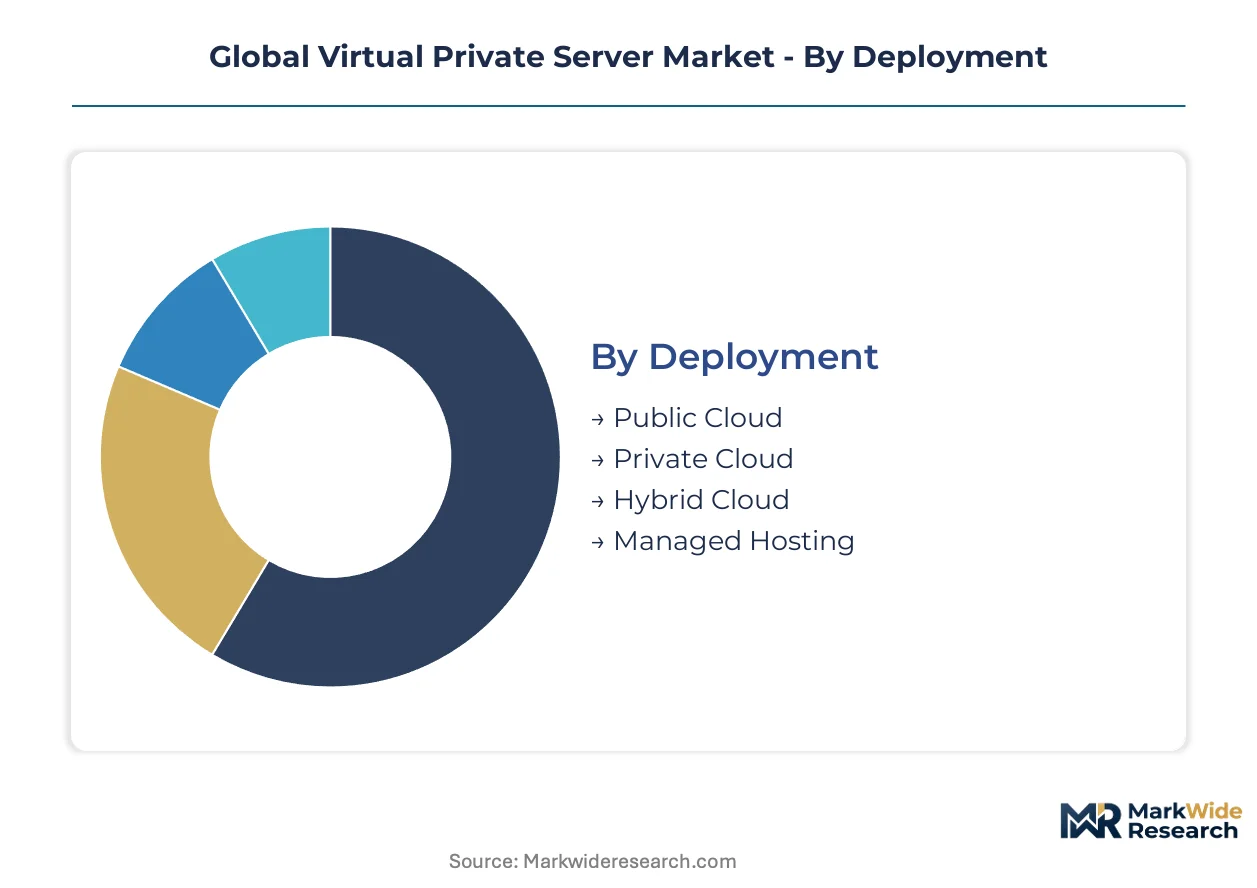
Capital intensity peaks with private cloud buildouts requiring dedicated hardware and sovereign data center footprints.
- Public Cloud:Multi-tenant environments provisioned over shared hyperscale infrastructure deliver instant scalability without upfront hardware commitment. SaaS startups in Bangalore and São Paulo favor this model for elastic burst capacity during funding rounds.
- Private Cloud:Single-tenant deployments on dedicated physical nodes command premium positioning for GDPR and EU AI Act compliance. German automotive suppliers and French healthcare networks are consolidating workloads here to satisfy algorithmic transparency mandates.
- Hybrid Cloud:Orchestrated workloads span public burst capacity and private baseline infrastructure. Indian fintechs use this architecture to keep transaction data domestic while offloading analytics overseas.
- Managed Hosting:Providers assume full infrastructure maintenance burden, capturing IT enterprises with limited DevOps bench strength. Brazilian healthtech startups facing ANPD enforcement are migrating here for bundled compliance support.
Private cloud absorbs the bulk of installed capacity; public cloud is expanding most quickly among venture-backed scaleups.
Solution:
Operational complexity separates buyer profiles more than raw compute specifications.
- Managed VPS:Providers handle patching, monitoring, and security updates through bundled service tiers. IT enterprises in Frankfurt and Singapore outsource infrastructure maintenance here to redirect engineering talent toward product development.
- Unmanaged VPS:Root access with zero provider intervention appeals to cost-conscious developers with in-house sysadmin capability. Indie game studios across Poland and Argentina cluster in this segment.
- Cloud VPS:API-driven provisioning with hourly billing and instant vertical scaling. Container-native startups in Berlin and Hyderabad favor this for Kubernetes cluster expansion.
- Dedicated VPS:Physically isolated nodes with guaranteed resource reservation for latency-sensitive workloads. High-frequency trading firms in London and Chicago require this for deterministic execution.
Managed VPS commands the largest revenue pool; cloud VPS shows the steepest expansion trajectory among developer-led procurement committees.
Application:
Latency tolerance and data gravity determine infrastructure tier selection.
- Web Hosting:Standard LAMP stack deployments dominate volume but compress margins through commoditization. Regional hosting providers in Indonesia and Vietnam compete aggressively here.
- E-commerce:PCI-DSS compliance requirements and checkout latency sensitivity push merchants toward higher-tier managed solutions. Brazilian and Indian marketplaces are upgrading from shared hosting during peak season preparation.
- Game Hosting:Low-latency UDP requirements and DDoS resilience needs favor bare-metal-adjacent VPS tiers. Multiplayer studios in Sweden and South Korea cluster compute near player populations.
- Application Development:CI/CD integration and ephemeral staging environments drive API-first provider selection. DevOps teams in Amsterdam and Austin prioritize Terraform provider quality over raw compute pricing.
- Database Management:IOPS guarantees and backup SLA stringency separate enterprise-grade from commodity offerings. Financial services in Zurich and Sydney require synchronous replication across availability zones.
Web hosting carries the highest server count; application development is gaining share fastest as engineering-led procurement expands.
End User:
Budget authority and technical sophistication create distinct buying motions.
- Startups:Burn-rate sensitivity and technical debt tolerance favor cloud VPS with usage-based billing. Pre-seed and seed-stage companies across Tel Aviv and Lagos optimize for minimal committed spend.
- SMEs:Limited IT headcount drives managed VPS preference despite 40-60% cost premium over unmanaged alternatives. Professional services firms in Madrid and Milan value uptime guarantees over customization depth.
- IT Enterprises:Procurement committees evaluate security certifications and contract flexibility at scale. Fortune 500 technology and pharmaceutical companies in Boston and Basel run multi-year RFP processes.
- Digital Agencies:Client-diverse workloads require rapid environment provisioning and white-label management portals. Boutique shops in Copenhagen and Mexico City consolidate multiple client sites per VPS node.
- Government Organizations:Sovereign data requirements and ISO 27001 mandates restrict vendor shortlists to domestic or regional providers. Federal and municipal buyers in Ottawa and Canberra face strict data residency enforcement.
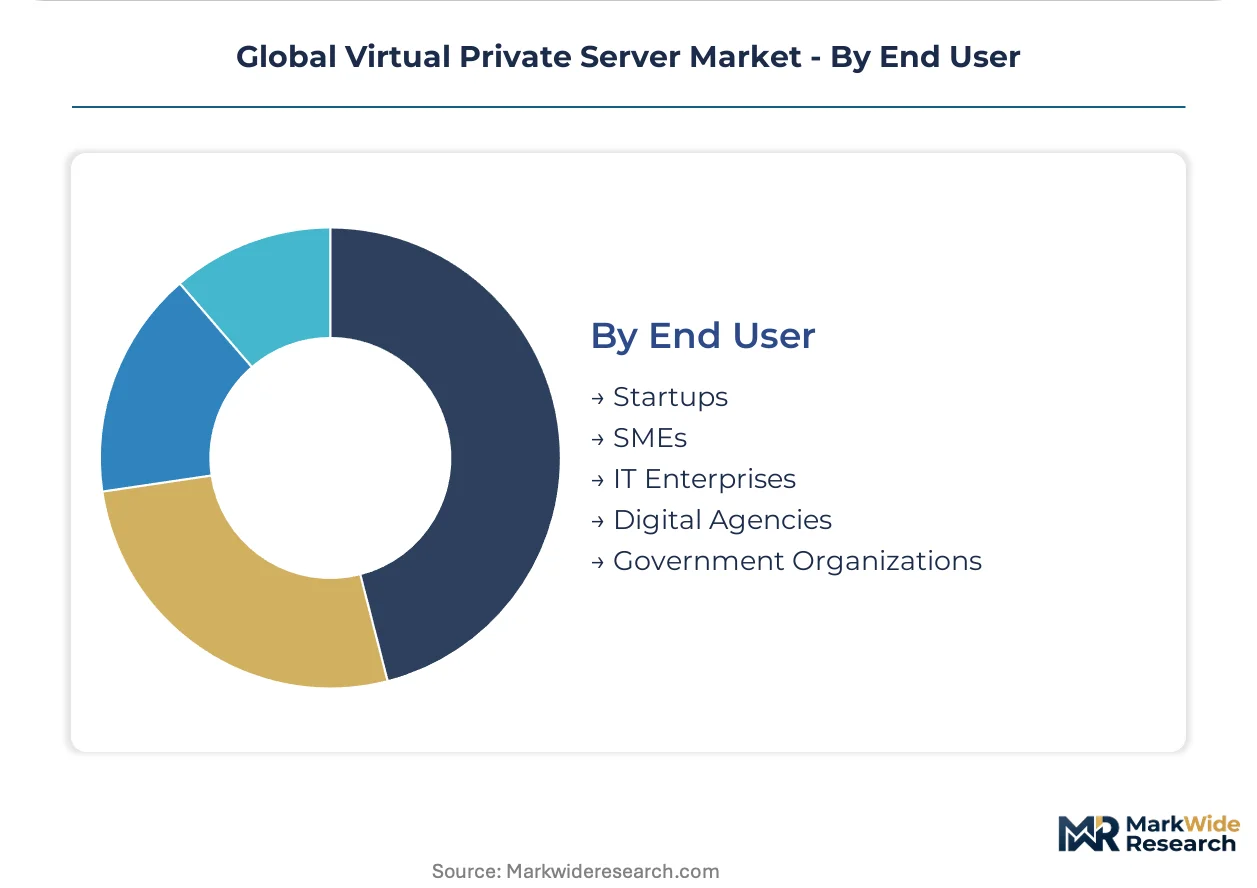
IT enterprises deploy the most aggregate compute capacity; startups are climbing the fastest as venture funding democratizes infrastructure access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for virtual private server infrastructure concentrates in jurisdictions with stringent data governance frameworks. Germany, India, Brazil, the United States, and Japan collectively anchor procurement volume as localization mandates reshape deployment patterns.
Germany
Automotive suppliers and healthcare networks drive managed private cloud adoption for algorithmic transparency compliance. The EU AI Act and GDPR enforcement through CNIL-equivalent state regulators mandate sovereign data processing. Frankfurt and Munich host the densest concentration of certified Tier III facilities serving cross-border enterprise workloads.
India
Fintech transaction volumes and healthtech digitization propel cloud VPS procurement among venture-backed startups. The PLI scheme for data centers incentivizes domestic infrastructure buildouts through the Ministry of Electronics and Information Technology. Mumbai and Hyderabad clusters absorb the majority of greenfield capacity as ANPD-style cross-border restrictions tighten.
Brazil
Fintech compliance costs and e-commerce peak-season scaling push merchants toward managed hosting with bundled regulatory support. ANPD penalties for unauthorized data transfers have hardened local procurement preferences since 2023. São Paulo's metro zone concentrates both hyperscale availability zones and boutique sovereign providers.
United States
Healthcare data integrity requirements and FDA guidelines on electronic records drive HIPAA-compliant private deployments. Financial services procurement committees evaluate SOC 2 Type II certification depth during multi-year vendor assessments. Northern Virginia and Dallas-Fort Worth maintain the highest density of GPU-enabled instances for AI training workloads.
Japan
Gaming studios and industrial IoT manufacturers require low-latency edge compute with deterministic performance guarantees. METI guidelines on critical infrastructure cybersecurity shape vendor qualification criteria for financial and energy sector buyers. Tokyo and Osaka metropolitan areas anchor domestic cloud zones with sub-10ms latency to manufacturing hubs.
Global Virtual Private Server Market Competitive Landscape
Established hyperscale operators occupy the standard tier; emerging regional specialists pursue sovereign compliance differentiation. The vendor base organizes around three archetypes: infrastructure-anchored platforms with global fiber networks, developer-centric providers optimizing API ergonomics, and compliance-focused hosters bundling certification management. Geographic expansion through local data center buildouts and strategic partnerships with systems integrators represent the dominant competitive vectors.
Among hyperscale infrastructure operators, Amazon Web Services exemplifies the capacity-driven archetype through its global region footprint. DigitalOcean and OVHcloud occupy adjacent positions within the developer-sovereignty spectrum—DigitalOcean representing streamlined deployment workflows, OVHcloud anchoring European data residency positioning. These three entities collectively illustrate how scale, usability, and compliance specialization segment procurement committee evaluations across enterprise, startup, and government buyer profiles.
| Leading Market Players |
|---|
| Amazon Web Services |
| DigitalOcean |
| OVHcloud |
| GoDaddy |
| A2 Hosting |
| Liquid Web |
| Rackspace Technology |
| InMotion Hosting |
| DreamHost |
| Others |
Supply & Pricing Matrix
DevOps engineering talent concentration in Bangalore and Hyderabad creates labor-cost differentials that widen pricing-tier spreads between managed and unmanaged VPS offerings. European operators absorb 25-40% higher personnel expenses, forcing premium positioning on sovereign compliance bundles.
Pricing Analysis
Volume concentrates in commoditized web hosting tiers while margin pools in private cloud and managed segments with ISO 27001 certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates dedicated GPU instances from shared vCPU nodes. Cost compression in entry-level tiers intensifies because hyperscale operators subsidize customer acquisition through cross-sell to storage and networking services. Pre-seed startups exhibit highest price sensitivity, while Fortune 500 procurement committees prioritize SLA stringency over unit economics.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certification gating restricts qualified hardware suppliers to Taiwan, South Korea, and USA-based semiconductor foundries. Server assembly draws from Chinese ODMs, Dutch cooling system specialists, and Japanese power management component manufacturers. Single-source vulnerability in high-core-count CPU provisioning creates delivery risk when geopolitical friction disrupts TSMC allocation priorities. Distribution runs through direct enterprise sales teams, hyperscale self-service portals, and regional systems integrators with compliance advisory capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IPv4 address exhaustion and semiconductor foundry allocation constraints prop pricing power for qualified providers, creating a supply-constrained market structure favoring incumbent defenders with established certification pipelines.
For Market Incumbents: Anticipate margin compression from ARM-based server architecture transitions by securing early allocation commitments with Ampere and AWS Graviton supply chains. Defensive consolidation through ISO 27001 assessor capacity investments addresses the 40% audit timeline extension threatening customer retention. Vertical integration into sovereign data center real estate in Frankfurt, Mumbai, and São Paulo locks in localization-compliant capacity before PLI scheme saturation. For New Entrants and Emerging Players: Indie game studios in Poland and Argentina represent an underserved buyer archetype seeking bare-metal-adjacent VPS with DDoS resilience at unmanaged price points. White-space capture opportunities concentrate in GPU-enabled edge instances for 5G network zones serving autonomous systems and industrial IoT. Go-to-market execution through Terraform provider certification and GitHub Actions integration depth bypasses enterprise sales cycle friction. For Investors and Strategic Acquirers: Re-rating potential sits with regional compliance specialists given EU AI Act enforcement acceleration and ANPD penalty escalation in Brazil. Long-term viability over a multi-year horizon favors acquisition targets with captive data center footprints in Germany, India, and Brazil paired with managed services bundling capabilities. The signal to watch is hyperscaler capex allocation shifts toward sovereign cloud infrastructure indicating demand validation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Buildout | ANPD and EU AI Act enforcement create captive demand for localized compute in São Paulo and Frankfurt zones. |
| ARM Architecture Transition | Ampere Altra and Graviton deployments reduce European energy costs while satisfying sustainability procurement criteria. |
| Certification Pipeline Investment | ISO 27001 assessor capacity scarcity threatens customer onboarding velocity for compliance-dependent buyers. |
| Kubernetes-Native Platform Launch | Container orchestration capture displaces proprietary serverless lock-in among developer-led procurement committees. |
| Edge-AI GPU Instance Deployment | 5G network edge positioning enables real-time inference for autonomous systems and industrial IoT workloads. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, data center permitting filings, and certification audit queue lengths anchored the trend analysis, supplemented by interviews with cloud infrastructure executives, DevOps team leads, data center operations directors, and enterprise procurement officers. Secondary validation drew from SEC 10-K infrastructure segments, TRAI and MEITY policy circulars, and ISO registrar publication logs. Bottom-up triangulation across deployment architecture segments converged with top-down demand modeling from SaaS funding round velocities and e-commerce transaction growth proxies.
Segment-weighting approaches distributed value estimates across public cloud, private cloud, hybrid, and managed hosting deployment models, further subdivided by managed versus unmanaged operational complexity tiers. Growth trajectories across the analysis window derived from elasticity coefficients linking venture funding volumes to cloud VPS procurement intensity, adjusted for data localization mandate implementation timelines. GPU instance penetration rates and ARM architecture adoption curves served as technology-specific forecast inputs.
Revisions become necessary when semiconductor foundry allocation priorities shift, energy price volatility exceeds historical bands, or regulatory enforcement intensity departs from announced timelines. Forecasts reflect documented assumptions regarding PLI scheme continuation and IPv4 market liquidity. A model refresh is warranted upon material change in hyperscaler sovereign cloud investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Software Defined Video Networking Market
Data Center and Networking
Converged Data Platform Market
Data Center and Networking
Ireland Data Center Networking Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
United States Data Center Networking Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Europe Subscriber Data Management Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Enterprise Network Infrastructure Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
United Kingdom Data Center Networking Market
Data Center and Networking
New Zealand Data Center Networking Market