
 Asia-Pacific Hazardous Waste Handling Automation Market | 2026-2036
Asia-Pacific Hazardous Waste Handling Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hazardous Waste Handling Automation Market Outlook
Aftermarket service revenue for legacy crane and material handling systems is narrowing as automation-as-a-service contracts replace traditional maintenance models. Konecranes PLC leverages its installed base across Southeast Asian port facilities to extend recurring software licensing income. Veolia Environnement anchors its regional position through captive engineering teams in Shanghai and Singapore that specialize in hazardous waste retrofit automation. SUEZ India Private Limited competes by integrating IoT-enabled remote monitoring into municipal waste treatment contracts across Maharashtra and Gujarat.
Asia-Pacific hazardous waste handling automation encompasses robotic arms, automated sorting conveyors, sensor networks, and AI-driven contamination detection systems engineered to manipulate, transport, and process toxic, flammable, corrosive, or reactive waste streams without direct human exposure. These systems typically operate within temperature-controlled enclosures rated for chemical resistance and incorporate real-time gas monitoring with emergency containment protocols to prevent occupational exposure and environmental release. Robotics and AI Integration currently occupy the highest-margin solution tier as end users demand autonomous decision-making for waste classification and routing. Automated Sorting sustains volume leadership across industrial waste management applications where high-throughput separation of mixed hazardous streams remains the dominant operational challenge.
China's Ministry of Ecology and Environment enforces GB standards that mandate automated handling for Category I hazardous waste, while India's Central Pollution Control Board implements the Hazardous Waste Management Rules requiring real-time tracking of cradle-to-grave disposal. Japan's METI circular economy guidelines further shape procurement specifications by prioritizing closed-loop automation systems that recover valuable materials from industrial byproducts. Stakeholders must evaluate regulatory divergence across national hazardous waste classifications when configuring cross-border automation platforms for multinational chemical and electronics manufacturers.
Market Dynamics
China's GB standards on solid waste pollution control are eliminating manual handling exemptions for Category I hazardous waste, forcing chemical manufacturers across Jiangsu and Zhejiang provinces to accelerate capital deployment into robotic containment systems and AI-driven sorting infrastructure.
Growth Catalysts
- India's Hazardous Waste Management Rules:The Central Pollution Control Board mandates real-time tracking of cradle-to-grave disposal, compelling pharmaceutical and petrochemical facilities in Maharashtra to install automated conveyor and sensor networks.
- Robotic Sorting Arms:Chemical manufacturing plants in eastern China's industrial corridor are standardizing six-axis robotic arms with chemical-resistant coatings to handle corrosive waste streams without human exposure.
- AI-Integrated Containment Systems:Electronics manufacturers in South Korea's Gyeonggi-do cluster deploy machine vision for autonomous waste classification, reducing misrouting incidents in semiconductor fabrication byproducts.
Market Restraints
- Specialized Component Supply Concentration:Pneumatic actuators and corrosion-resistant bearings for hazardous environments concentrate among Japanese and German suppliers, exposing automation integrators to 14-18 week lead times.
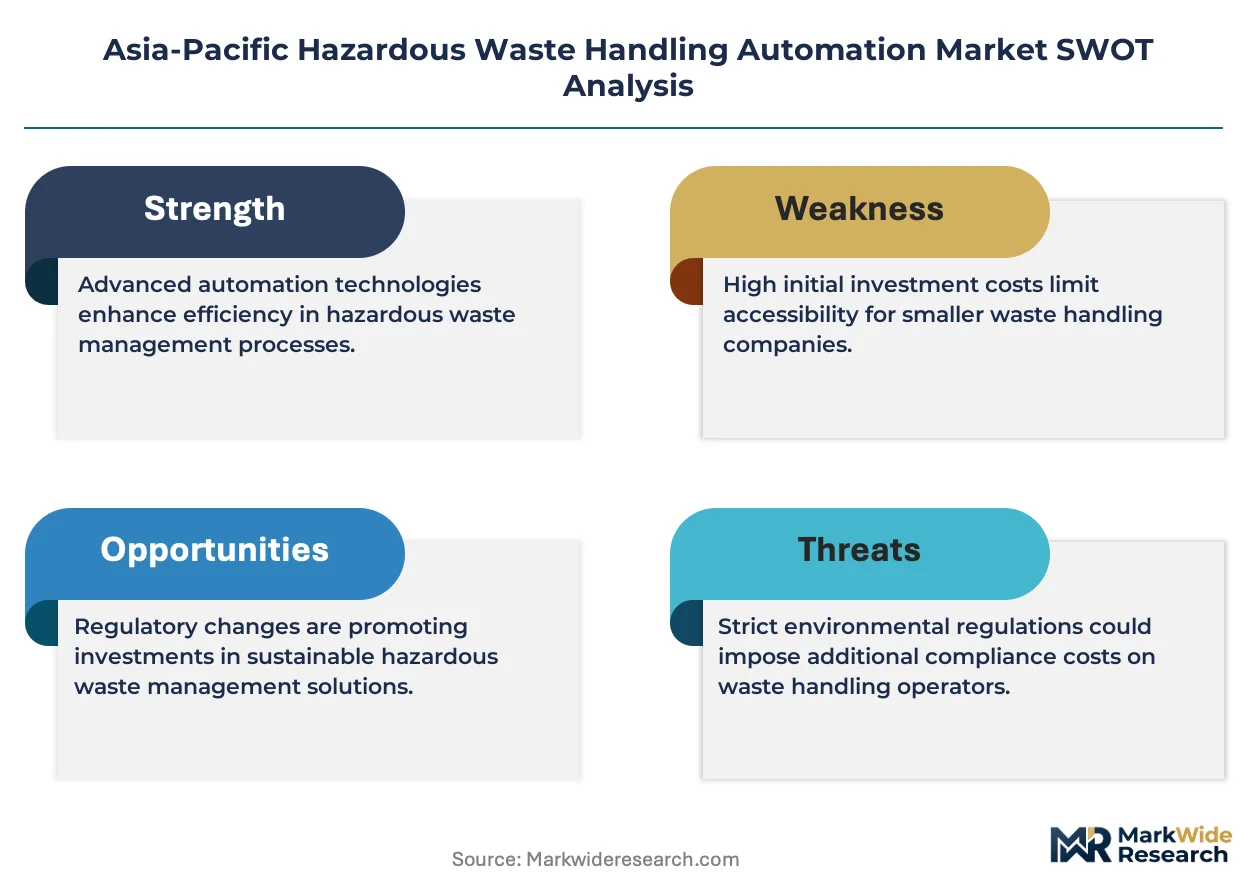
- Capital Intensity Barriers:Full-line automation retrofits for existing chemical plants require eight-figure RMB investments that mid-size processors in Shandong province cannot access without state-backed financing.
- Technical Limitation in Mixed Waste Streams:Current spectroscopic sensors struggle to differentiate polymer-coated hazardous solids from non-hazardous substrates at conveyor speeds above 2.5 meters per second.
Strategic Opportunities
- Vietnam's Emerging Electronics Corridor:Samsung and Foxconn supplier parks in Bac Ninh and Thai Nguyen provinces lack legacy automation infrastructure, creating greenfield deployment opportunities for turnkey hazardous waste handling systems.
- Japan's METI Circular Economy Guidelines:Closed-loop automation specifications for rare earth recovery from industrial byproducts create premium demand for hydrometallurgical processing integration with robotic material handling.
- Automation-as-a-Service Contracts:Malaysian palm oil processors in Johor are piloting subscription-based robotic maintenance models that shift capex to opex and accelerate technology refresh cycles.
Industry Challenges
- Certification Timeline Compression:China's MEE now requires third-party validation of emergency containment protocols within 90 days of installation, straining local testing laboratory capacity.
- Integration Complexity with Legacy Crane Systems:Southeast Asian port facilities operate 1980s-era Konecranes installations with proprietary control architectures that resist API connectivity to modern AI sorting platforms.
- Cross-Border Regulatory Divergence:Multinational chemical manufacturers must configure automation platforms to simultaneously satisfy India's cradle-to-grave tracking, China's GB emission thresholds, and Japan's material recovery specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hazardous Waste Handling Automation Market |
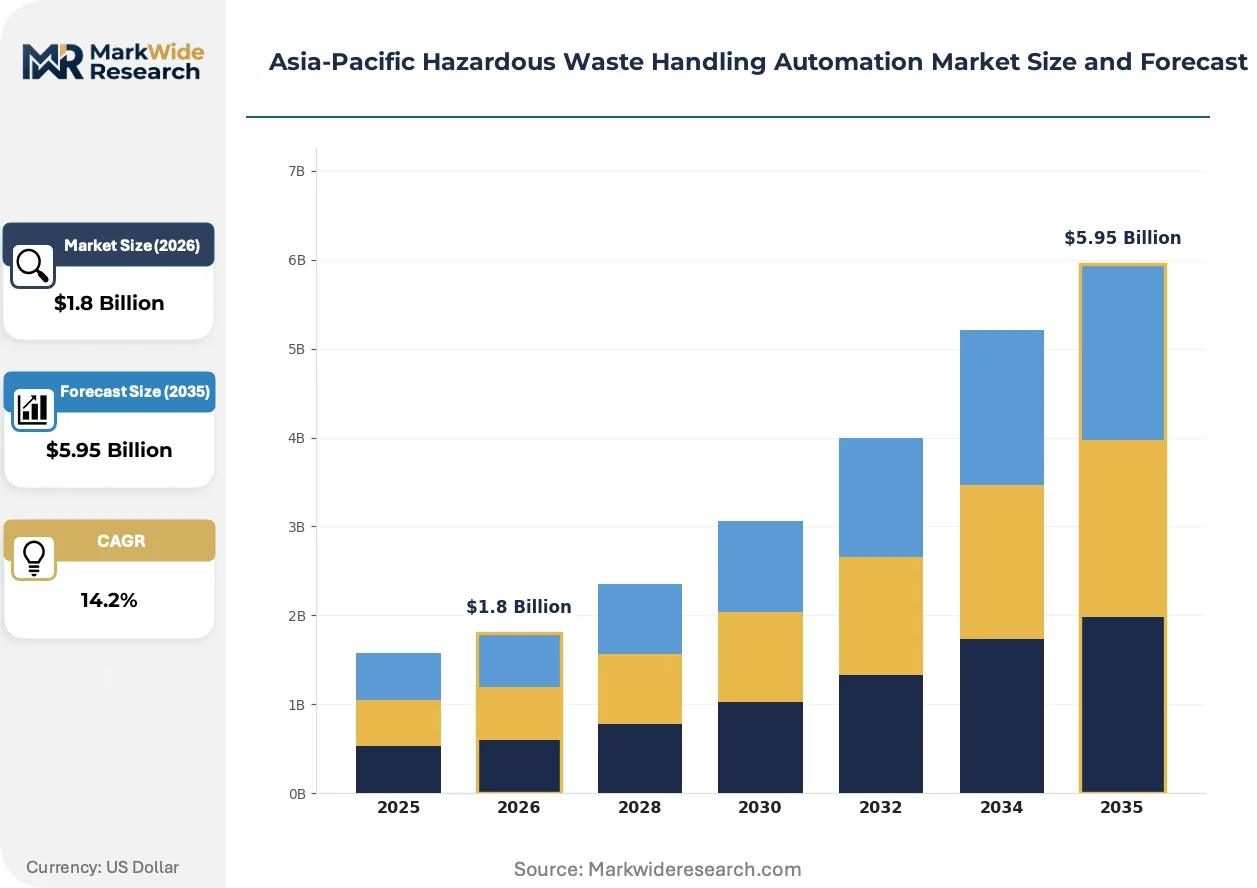
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Sorting, Robotics, IoT Solutions, AI Integration End User: Manufacturing Plants, Waste Treatment Facilities, Government Agencies, Environmental Consultants Application: Industrial Waste Management, Medical Waste Disposal, Chemical Treatment, E-Waste Processing Solution: On-premises Systems, Cloud-based Platforms, Hybrid Solutions, Remote Monitoring |
| Companies Covered | PaR Systems Inc, Konecranes PLC, Terex MHPS GmbH, Hiab, Penz Crane, Pallmann, Hosokawa Micron Powder Systems, Veolia Environnement, SUEZ India Private Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hazardous Waste Handling Automation Market Strategic Shifts
Autonomous decision-making systems are displacing rule-based automation across hazardous waste streams, compressing the gap between sensor detection and mechanical response from seconds to milliseconds while enabling continuous operation in environments previously requiring human oversight.
Hyperspectral imaging paired with deep learning classification algorithms is rendering obsolete manual sampling and laboratory confirmation for waste stream characterization. Petrochemical complexes in Singapore's Jurong Island are deploying these systems at full throughput, eliminating batch processing delays and enabling real-time routing adjustments that compress facility cycle times by eliminating quarantine holds.
China's Ministry of Ecology and Environment enforcement of automated handling mandates for Category I hazardous waste is restructuring procurement specifications across the chemical sector. Domestic integrators in Jiangsu province now pre-certify systems against GB emission thresholds before bidding, while foreign suppliers face extended validation timelines that favor local engineering partnerships for complex retrofits.
Buyers in India's pharmaceutical belt are consolidating vendor relationships around full-lifecycle service agreements that bundle hardware, software licensing, and predictive maintenance. Maharashtra-based active pharmaceutical ingredient manufacturers now prioritize automation providers with captive engineering teams in Pune over equipment-only suppliers, compressing the competitive field to integrators capable of 24-hour response commitments for containment system failures.
Asia-Pacific Hazardous Waste Handling Automation Market Segmentation
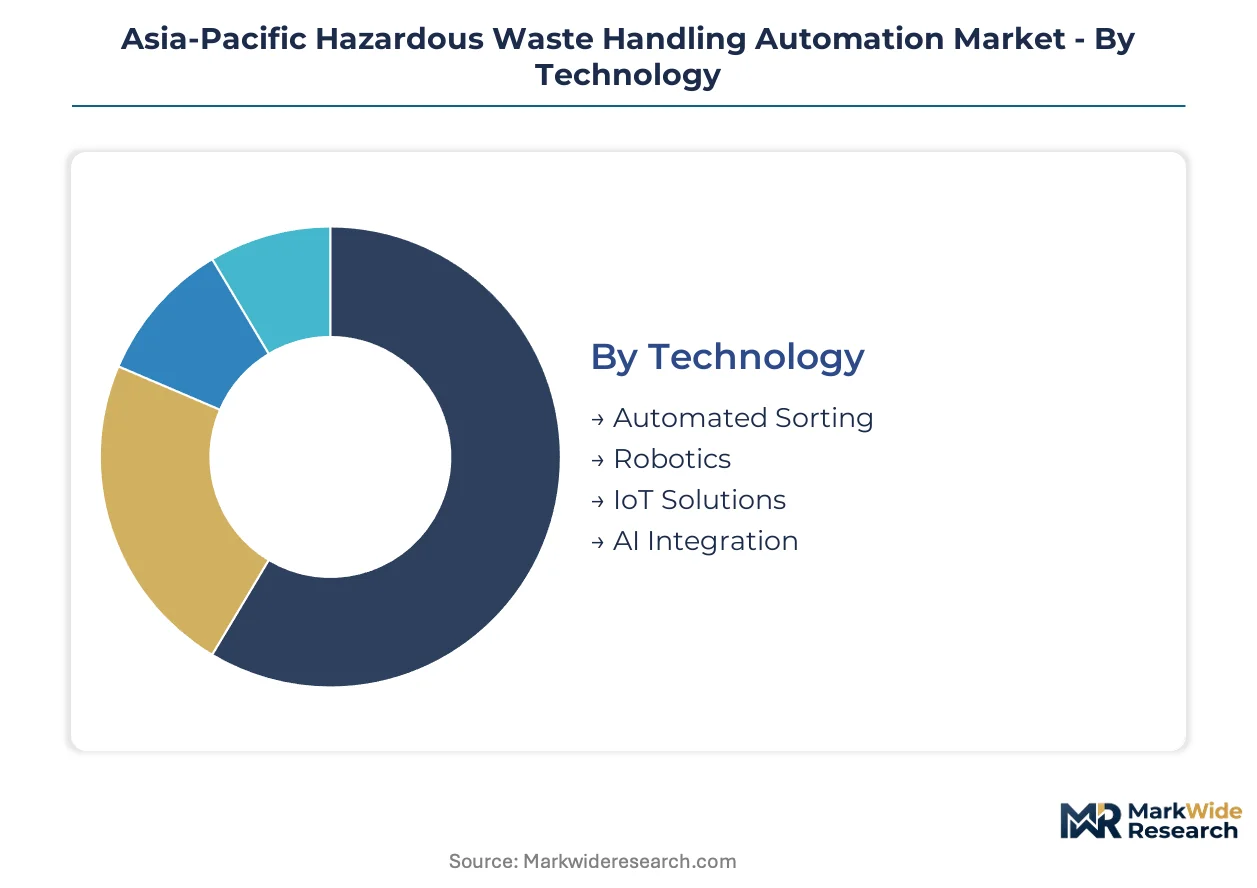
Hazardous waste handling automation segments diverge sharply by technical maturity and deployment complexity. Procurement patterns across Asia-Pacific chemical corridors favor integrated technology stacks over point solutions, compressing vendor selection timelines.
Technology:
Mature sorting infrastructure coexists with emerging AI decision layers, creating a bifurcated procurement landscape where legacy retrofits compete against greenfield autonomous installations.
- Automated Sorting:Mechanical separation systems using conveyor-fed optical sensors and pneumatic diverters for mixed waste streams. Demand concentrates in Jiangsu province chemical clusters where GB standards mandate throughput volumes exceeding manual capacity.
- Robotics:Six-axis articulated arms with chemical-resistant coatings and force-feedback grippers for direct waste manipulation. South Korean semiconductor foundries in Gyeonggi-do deploy these for wafer fabrication byproduct handling where contamination thresholds approach zero tolerance.
- IoT Solutions:Distributed sensor networks for real-time fill-level monitoring and equipment health tracking.
- AI Integration:Machine vision and deep learning classification for autonomous waste stream routing decisions.
Automated Sorting handles the majority of throughput; AI Integration is expanding most quickly on share as end-users eliminate laboratory confirmation delays.
End User:
Customer archetypes span from capital-intensive process industries to fee-for-service operators with divergent financing constraints and technical staffing.
- Manufacturing Plants:Integrated captive systems for continuous production waste streams. Shandong province petrochemical complexes require eight-figure RMB automation investments that strain mid-size processors without state-backed financing.
- Waste Treatment Facilities:Centralized processing hubs serving multiple industrial generators. Maharashtra's municipal contracts now mandate IoT-enabled remote monitoring, favoring vendors with captive engineering teams in Pune over equipment-only suppliers.
- Government Agencies:Regulatory enforcement and public sector procurement for centralized hazardous waste infrastructure.
- Environmental Consultants:Third-party validation and system design services for compliance certification.
Manufacturing Plants anchor capital deployment; Waste Treatment Facilities are gaining share fastest as municipal outsourcing accelerates across India.
Application:
Regulatory stringency varies dramatically across waste categories, segmenting automation requirements by containment protocol and emergency response specifications.
- Industrial Waste Management:High-volume processing of manufacturing byproducts with mixed hazard profiles. Singapore's Jurong Island petrochemical complexes deploy hyperspectral imaging to eliminate batch quarantine holds and compress facility cycle times.
- Medical Waste Disposal:Sterilization-integrated handling systems for infectious and sharps waste with strict chain-of-custody documentation.
- Chemical Treatment:Corrosive and reactive substance processing requiring temperature-controlled enclosures and real-time gas monitoring.
- E-Waste Processing:Rare earth recovery automation with closed-loop material separation for Japan's METI circular economy specifications.
Industrial Waste Management dominates installed base; E-Waste Processing shows steepest expansion trajectory as electronics manufacturing concentrates in Vietnam's Bac Ninh corridor.
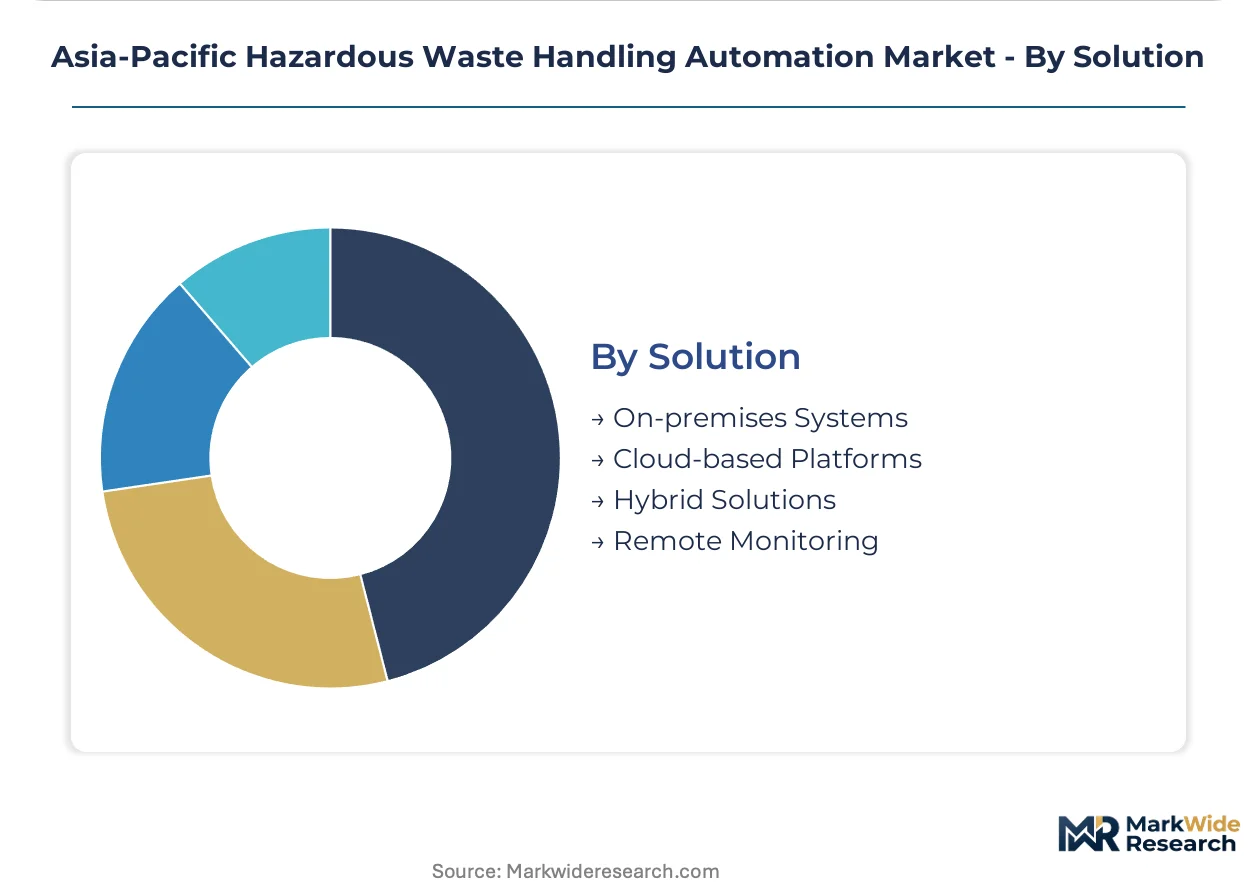
Solution:
Deployment architectures segment by data sovereignty requirements and connectivity infrastructure maturity across national industrial networks.
- On-premises Systems:Air-gapped control architectures for facilities with cybersecurity mandates or unreliable connectivity. China's MEE now requires third-party validation of emergency containment protocols within compressed installation timelines.
- Cloud-based Platforms:Centralized analytics and predictive maintenance with subscription licensing models. Malaysian palm oil processors in Johor pilot these to shift capex to opex and accelerate technology refresh cycles.
- Hybrid Solutions:Edge computing with cloud backup for latency-critical operations and long-term data archiving.
- Remote Monitoring:IoT-enabled oversight of distributed equipment fleets with 24-hour response commitments for containment failures.
On-premises Systems retain dominance in regulated chemical sectors; Cloud-based Platforms are climbing fastest as automation-as-a-service contracts displace traditional maintenance models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia-Pacific hazardous waste handling automation landscape, with Vietnamese electronics manufacturers demanding turnkey solutions at compressed margins while Japanese petrochemical operators prioritize premium closed-loop systems regardless of cost.
China
Jiangsu and Zhejiang province chemical clusters are retrofitting legacy facilities with six-axis robotic arms and AI-integrated containment systems. The Ministry of Ecology and Environment enforces GB standards eliminating manual handling exemptions for Category I hazardous waste. Shandong province mid-size processors face capital intensity barriers without state-backed financing for eight-figure RMB automation investments.
India
Pharmaceutical and petrochemical facilities in Maharashtra are installing automated conveyor and sensor networks under Central Pollution Control Board mandates. The Hazardous Waste Management Rules require real-time cradle-to-grave tracking, compelling municipal waste treatment contracts across Gujarat to integrate IoT-enabled remote monitoring. Pune-based captive engineering teams now command vendor selection priority for 24-hour response commitments.
Japan
Semiconductor fabrication byproduct handling in Gyeonggi-do-adjacent supplier networks demands zero-tolerance contamination thresholds. METI circular economy guidelines prioritize closed-loop automation systems recovering rare earth materials from industrial byproducts. Hydrometallurgical processing integration with robotic material handling creates premium demand in Nagoya-area industrial corridors.
South Korea
Electronics manufacturers in Gyeonggi-do cluster deploy machine vision for autonomous waste classification, reducing misrouting incidents in semiconductor fabrication. The country's national environmental regulator enforces emission thresholds that accelerate AI-driven sorting infrastructure procurement. Busan-Ulsan petrochemical complexes are standardizing hyperspectral imaging to eliminate batch quarantine holds.
Vietnam
Samsung and Foxconn supplier parks in Bac Ninh and Thai Nguyen provinces present greenfield deployment opportunities lacking legacy automation infrastructure. Electronics manufacturing concentration creates demand for turnkey hazardous waste handling systems without retrofit complexity. Subscription-based robotic maintenance models are piloting to shift capex to opex for palm oil processors in adjacent regional markets.
Asia-Pacific Hazardous Waste Handling Automation Market Competitive Environment
Industrial crane specialists and environmental services conglomerates split the Asia-Pacific hazardous waste handling automation market between equipment-centric and full-lifecycle service models. The vendor base concentrates around three strategic archetypes: legacy crane manufacturers extending software licensing income, diversified environmental services providers with captive regional engineering teams, and automation integrators bundling predictive maintenance into municipal contracts. Dominant competitive moves include automation-as-a-service contract structures displacing traditional maintenance models and vertical integration of captive engineering capabilities in high-growth industrial corridors.
Among European-origin environmental services providers, Veolia Environnement and SUEZ India Private Limited exemplify the full-lifecycle service archetype through regional engineering presences in Shanghai, Singapore, Pune and Mumbai. Konecranes PLC represents the installed-base leverage model among Nordic crane and material handling specialists. These three companies anchor the competitive landscape without exhausting its diversity, as Japanese pneumatic actuator suppliers and German corrosion-resistant bearing manufacturers maintain critical component positions despite extended lead times.
| Leading Market Players |
|---|
| PaR Systems Inc |
| Konecranes PLC |
| Terex MHPS GmbH |
| Hiab |
| Penz Crane |
| Pallmann |
| Hosokawa Micron Powder Systems |
| Veolia Environnement |
| SUEZ India Private Limited |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Japanese pneumatic actuators and German corrosion-resistant bearings compresses pricing tier spreads while forcing automation integrators toward extended inventory positions and premium sourcing premiums. This component chokepoint simultaneously widens the gap between certified-system pricing and uncertified alternatives while reshaping regional supply chain footprints toward dual-source qualification programs.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions now drive lifetime value more than initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates full-lifecycle integrators with captive engineering teams from equipment-only suppliers. Pricing pressure stems from automation-as-a-service contracts displacing traditional maintenance models and compressing upfront margins. Municipal waste treatment facilities in Maharashtra exhibit highest price sensitivity due to budget-constrained procurement, while Japanese semiconductor foundries prioritize zero-tolerance contamination systems regardless of cost.
Supply Chain Analysis
Export-control restrictions on advanced machine vision components and AI accelerators limit flows from US and EU sources into Chinese automation integrators. Manufacturing of critical inputs concentrates in Japan for pneumatic actuators, Germany for corrosion-resistant bearings, and South Korea for machine vision sensors. The supply chain draws from specialty steel foundries in Jiangsu province and chemical-resistant coating applicators in Zhejiang. Single-source vulnerability around precision motion components exposes integrators to allocation risk during demand surges. Distribution runs through regional system integrators with captive engineering teams in Shanghai, Singapore, and Pune.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific hazardous waste handling automation sits at early-cycle expansion driven by regulatory mandates eliminating manual handling exemptions across China's chemical corridor. Penetration remains below saturation even in leading industrial clusters, creating runway for sustained capital deployment.
For Market Incumbents: Build switching-cost moats through automation-as-a-service contracts that embed predictive maintenance and software licensing into multi-year agreements. Integrators should deepen backward integration into captive engineering teams in high-growth corridors like Bac Ninh and Thai Nguyen to compress response times below 24 hours. Threat of emerging local Chinese integrators with pre-certified GB compliance capabilities demands pre-emptive certification investments and local partnership structures.
For New Entrants and Emerging Players: Mid-size chemical processors in Shandong province without state-backed financing represent the most penetrable entry point for subscription-based robotic maintenance models that shift capex to opex. Vietnam's Samsung and Foxconn supplier parks lacking legacy automation infrastructure offer greenfield deployment opportunities without retrofit complexity. Go-to-market should anchor on turnkey hazardous waste handling systems bundled with regulatory compliance certification support.
For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors integrators with captive regional engineering capabilities over pure equipment manufacturers. Long-term viability hinges on recurring revenue share from software licensing and service contracts rather than one-time hardware sales. Acquisition target archetype: mid-size automation integrators with established municipal waste treatment relationships in India or pre-certified GB compliance capabilities in China. Signal to watch is consolidation of vendor relationships around full-lifecycle service agreements in Maharashtra's pharmaceutical belt.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Engineering Team Expansion | Establishes 24-hour response capabilities in Bac Ninh and Thai Nguyen supplier parks. |
| GB Standards Pre-Certification | Compresses validation timelines for Category I hazardous waste handling systems in Jiangsu province. |
| Automation-as-a-Service Launch | Shifts capex to opex for Malaysian palm oil processors in Johor and mid-size Shandong chemical plants. |
| Hyperspectral Imaging Integration | Eliminates batch quarantine holds at Singapore's Jurong Island petrochemical complexes. |
| Rare Earth Recovery Automation | Aligns with Japan's METI circular economy guidelines for closed-loop material separation. |
Study Parameters
Operator-level perspectives from plant engineers at chemical manufacturing facilities, procurement leads at waste treatment operators, automation integrators, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, Ministry of Ecology and Environment enforcement notices, Central Pollution Control Board mandate documentation, and SEC filings from listed environmental services providers. Bottom-up equipment deployment estimates triangulated against top-down industrial waste generation projections across the analysis window.
Scenario-bracketing around regulatory enforcement intensity and capital availability for mid-size processors shaped the analytical framework. Segmentation dimensions modeled include technology tier, end-user archetype, waste category application, and deployment architecture. CAGRs were derived from installed base growth rates, replacement cycles for legacy crane systems, and penetration assumptions for AI-integrated containment. Industry-specific forecast inputs incorporated GB standards implementation timelines and Maharashtra municipal contract award patterns.
Practitioners should monitor shifts in China's MEE enforcement posture, India's Hazardous Waste Management Rules amendment schedules, and component lead time volatility for early signals requiring forecast reassessment. Material changes in state-backed financing availability for Shandong province chemical processors or export-control expansion on machine vision components would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Construction Waste Market
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
ASEAN Waste Management Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market