
 Novolac Resins Market | 2026-2036
Novolac Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Novolac Resins Market Analytics
REACH is pivoting the cost-of-entry calculus for European novolac resin suppliers by mandating stricter formaldehyde emission thresholds and enhanced substance registration protocols. Hexion leverages its integrated phenol-to-novolac manufacturing footprint to absorb compliance costs without downstream price escalation. Kukdo Chemical anchors its position through captive epoxy hardener production that locks in raw material security across Asian electronics supply chains. Mitsui Chemicals specializes in ultra-high-purity novolac grades that navigate Japan's stringent semiconductor packaging standards.
Novolac resins are thermosetting phenol-formaldehyde polymers synthesized under acidic conditions with a formaldehyde-to-phenol molar ratio below unity, yielding permanently fusible and soluble prepolymers that require crosslinking with hexamethylenetetramine or epoxy hardeners for final cure. These resins deliver exceptional thermal stability above 150°C, flame retardancy, and chemical resistance, making them indispensable for high-performance coatings, electronics encapsulation, and friction materials. Novolac epoxy formulations dominate margin pools in the product type landscape due to their irreplaceable role in semiconductor molding compounds and PCB laminates where thermal cycling resistance commands premium pricing. The coatings application segment sustains volume leadership through protective industrial formulations for oilfield equipment and marine infrastructure, while composites applications for aerospace structural components represent the fastest-growing demand vector driven by weight reduction mandates.
EPA regulations in the United States restrict formaldehyde emissions from composite wood products under TSCA Title VI, directly shaping novolac resin formulation requirements for North American construction and furniture applications. ECHA's REACH restrictions on phenol derivatives and Germany's KBA automotive material safety standards collectively elevate product certification burdens across European supply chains. China's MEE enforces dual carbon goals that pressure phenolic resin producers toward energy-efficient condensation processes and solvent recovery systems. Stakeholders must monitor evolving cross-border chemical registration reciprocity and pre-position compliant inventory ahead of anticipated tightening in Asian environmental enforcement.
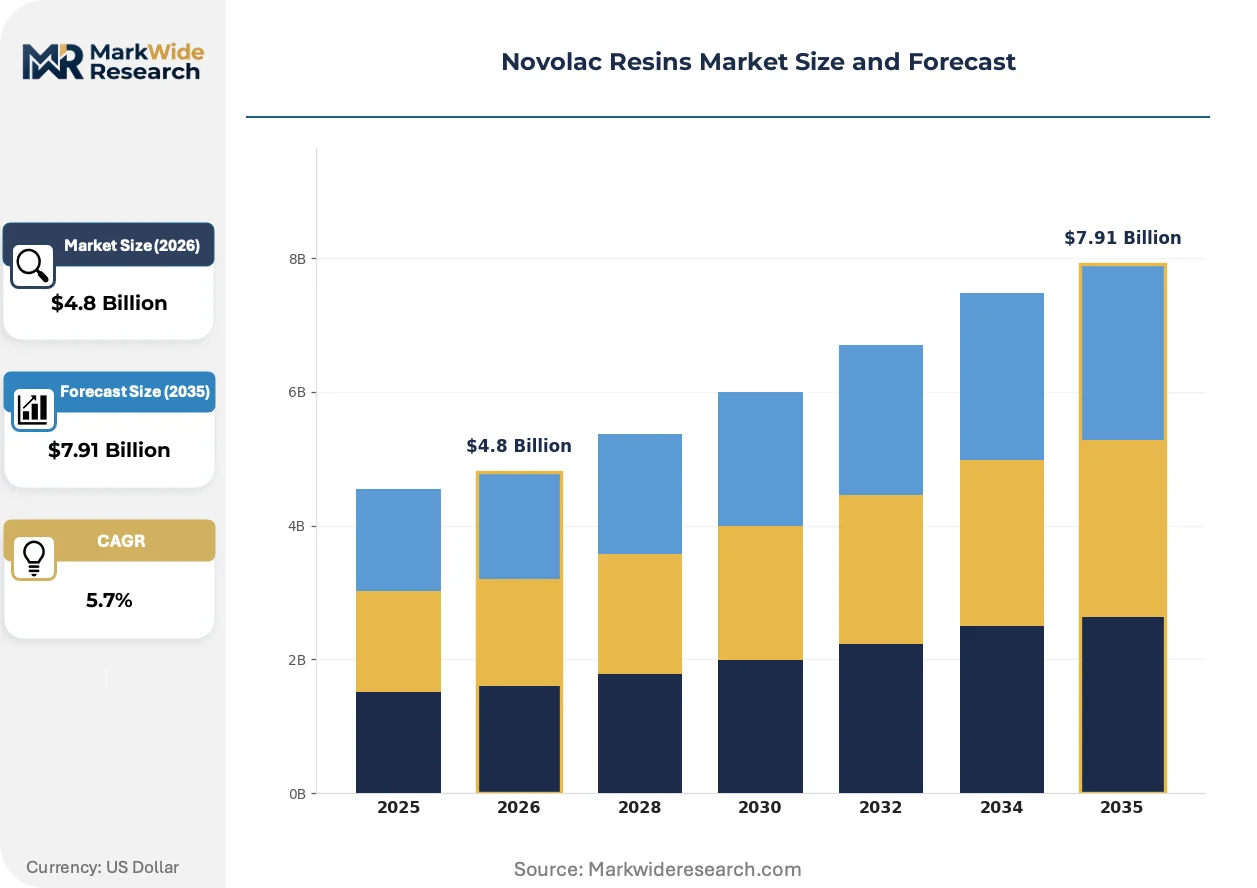
Market Dynamics
REACH formaldehyde emission thresholds are compressing European novolac resin formulation margins while electronics encapsulation demand in East Asia pulls capacity expansion toward phenol-to-novolac integration. The tension between compliance cost absorption and specialty grade premium capture defines current competitive positioning.
Growth Catalysts
- Semiconductor packaging grade demand:Ultra-high-purity novolac specifications for advanced chip molding compounds are pulling capacity toward electronics-dedicated production lines in Japan and South Korea.
- REACH substance registration protocols:ECHA's tightening phenol derivative oversight is accelerating substitution toward pre-registered novolac epoxy systems with established safety dossiers.
- Guangdong PCB cluster concentration:China's printed circuit board fabrication hubs are scaling captive novolac epoxy formulation capacity to secure laminates supply.
Market Restraints
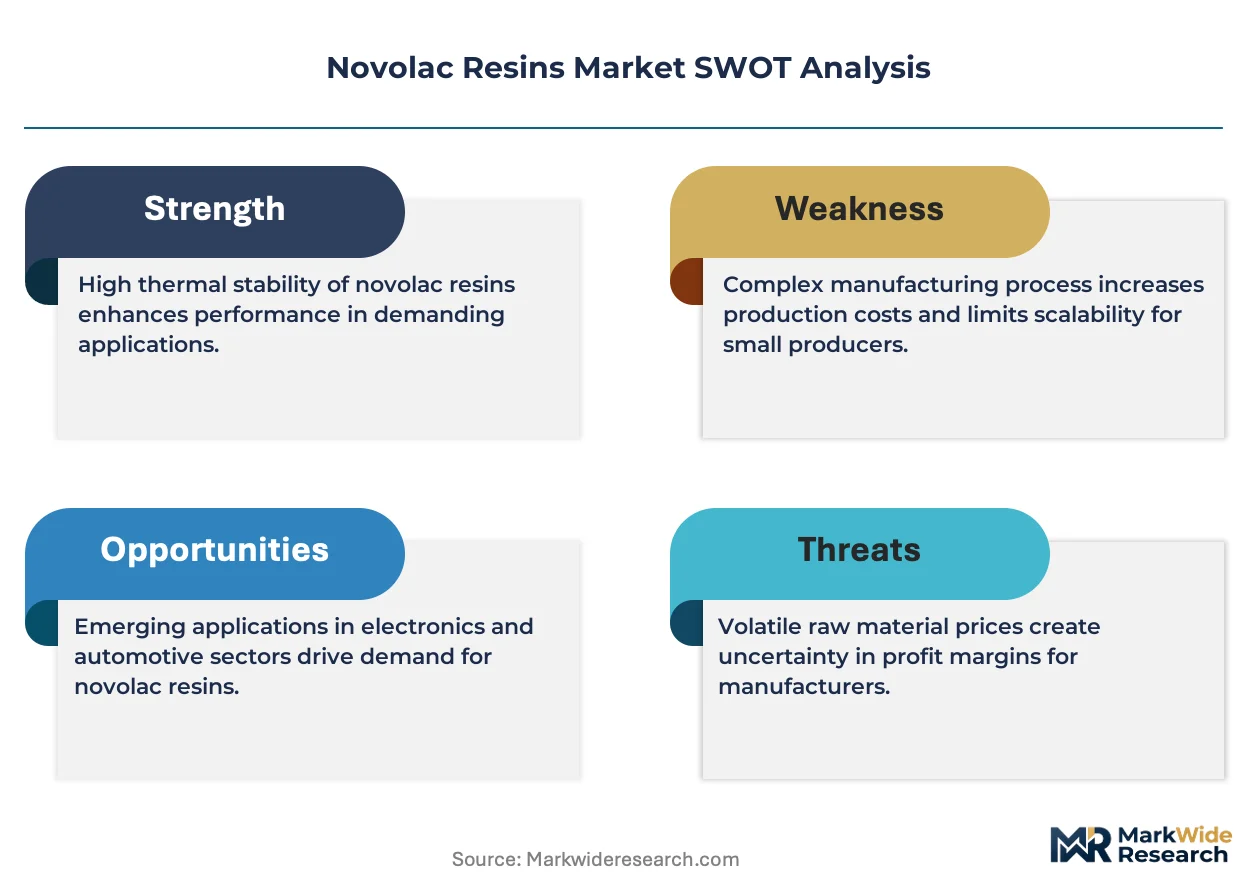
- Phenol feedstock volatility:Benzene-to-phenol cracking economics and refinery output swings transmit directly to novolac resin input cost structures.
- Hexamethylenetetramine crosslinker supply concentration:Production of this cure agent clusters in specific chemical manufacturing corridors, creating single-source vulnerability for novolac hardening systems.
- Formaldehyde substitution pressure:Bio-based phenolic alternatives and non-formaldehyde thermoset chemistries threaten incumbent novolac positions in construction adhesives.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor and PCB production are creating virgin demand territory for novolac epoxy laminates and molding compounds.
- Aerospace composites qualification:Novolac-cyanate ester blends for structural thermosets are penetrating weight-critical airframe applications previously served by epoxy-amine systems.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive phenolic resins will advantage European novolac producers with integrated bio-phenol or carbon capture process configurations.
Industry Challenges
- High-purity synthesis expertise scarcity:Semiconductor-grade novolac production requires rare combination of phenol-formaldehyde condensation chemistry and ionic contamination control capabilities.
- Multi-jurisdiction substance registration synchronization:Divergent chemical inventory requirements across REACH, TSCA, and China's MEE create compliance timeline fragmentation for global novolac suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Novolac Resins Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Novolac Phenolic, Novolac Epoxy, Novolac Urea, Novolac Formaldehyde Application: Coatings, Adhesives, Composites, Laminates End User: Aerospace, Automotive, Electronics, Construction Form: Powder, Liquid, Paste, Granules |
| Companies Covered | Olin Corporation, Kukdo Chemical, Hexion, Georgia-Pacific Chemicals, Westlake Epoxy, DIC Corporation, KOLON Industries, Mitsui Chemicals, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Novolac Resins Market Evolving Landscape
Active materials research is compressing cure cycles and elevating thermal performance thresholds for novolac-based thermosets across electronics and industrial coatings. These developments are reshaping process economics and qualification protocols simultaneously.
Bio-based phenol feedstocks derived from lignin depolymerization are integrating into commercial novolac resin production at pilot scale in European and North American facilities. Coatings formulators in marine and oilfield protective applications are trialing these partially renewable grades to preempt carbon intensity disclosure requirements. The technology is integrating into supply chain decarbonization roadmaps without sacrificing the flame retardancy or chemical resistance specifications that define novolac competitive advantage.
ECHA's SVHC candidate list expansion for phenol and formaldehyde derivatives is forcing reformulation investments across European novolac resin applications. Industrial coatings producers are accelerating migration toward low-free-formaldehyde novolac grades to maintain CE marking eligibility. Electronics encapsulation suppliers with established EU market positions are absorbing registration costs through specialty grade premium structures rather than volume discounting.
Consolidated procurement of novolac epoxy systems by vertically integrated PCB laminate manufacturers is compressing distributor roles in East Asian supply chains. Direct phenol-to-laminate integration among Guangdong and Taiwan-based producers is displacing merchant resin offtake. This pattern is most visible in high-layer-count board segments where formulation consistency and lot traceability override spot price minimization.
Novolac Resins Market Segmentation
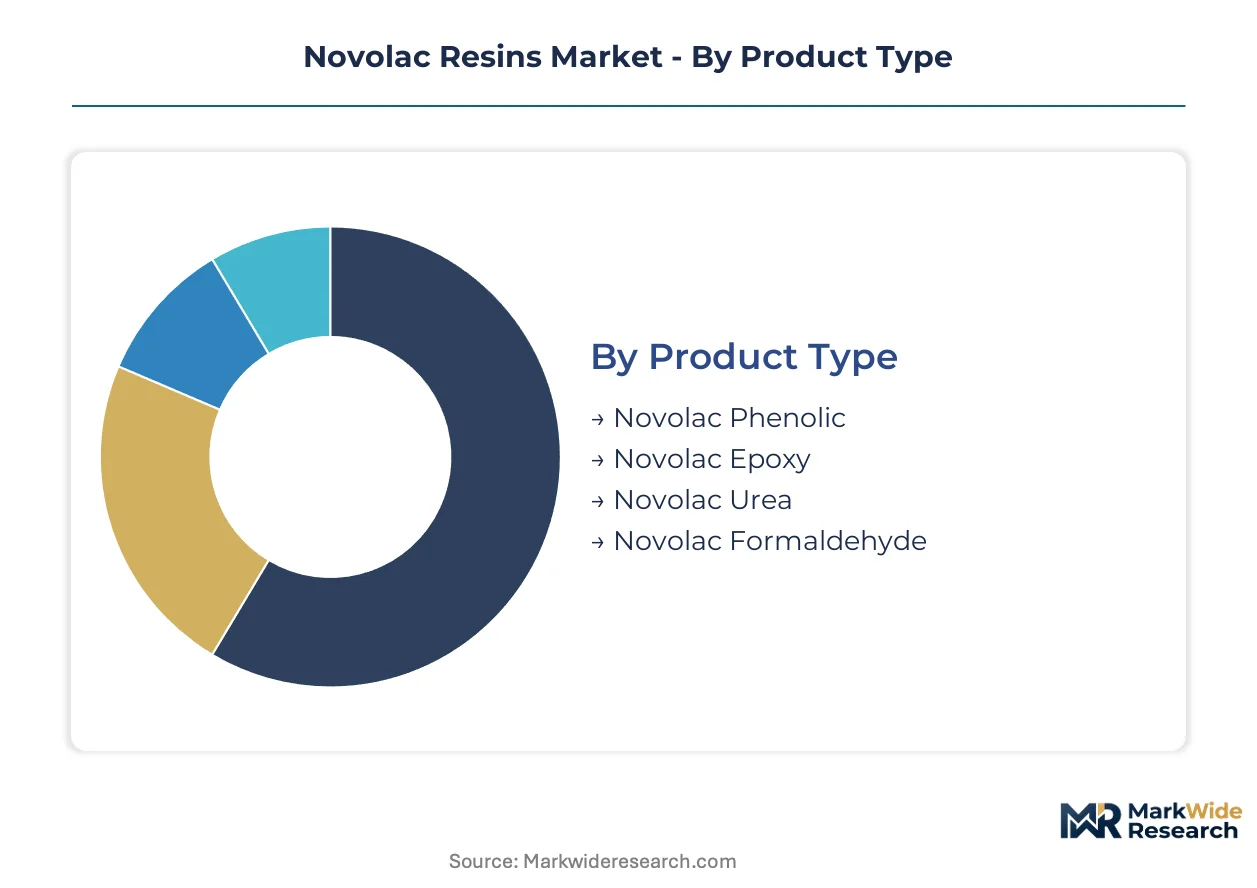
Novolac resin specifications diverge sharply across end-use certifications, with semiconductor-grade purity demanding ionic contamination controls that construction-grade formulations ignore entirely. Segmentation discipline separates margin-accretive specialty grades from commodity volume plays.
Product Type:
REACH substance registration protocols impose divergent compliance burdens across phenolic chemistries, with epoxy-novolac hybrids requiring the most extensive safety dossiers for electronics applications.
- Novolac Epoxy:Hybrid thermosets combining phenolic backbones with epoxide functionality deliver the thermal cycling resistance and ionic purity specifications demanded by advanced semiconductor molding compounds. Demand concentrates in Japan and South Korea where chip packaging facilities enforce sub-ppm contamination thresholds. Premium capture here exceeds standard phenolic grades by substantial margins.
- Novolac Phenolic:Acid-catalyzed condensation products with formaldehyde-to-phenol ratios below unity form the foundational chemistry for high-temperature friction materials and industrial coatings. Automotive brake pad manufacturers in Germany and the United States anchor volume offtake, though formaldehyde emission regulations are compressing formulation flexibility in both jurisdictions.
- Novolac Urea:Cost-optimized variants incorporating urea extenders serve construction adhesives and wood composite binders where thermal performance requirements moderate.
- Novolac Formaldehyde:Straight phenol-formaldehyde condensates retain relevance in legacy electrical insulation and foundry applications despite substitution pressure from epoxy-modified systems.
Leading the category by volume: Novolac Phenolic. Growing fastest: Novolac Epoxy.
Application:
Application selection determines supply chain configuration, with electronics-facing segments demanding lot traceability and coating applications tolerating broader specification bands.
- Coatings:Protective formulations for marine infrastructure and oilfield equipment leverage novolac chemical resistance and flame retardancy. Marine coatings producers in Norway and Singapore specify these systems for subsea pipeline protection where cathodic disbondment resistance commands premium pricing.
- Laminates:PCB substrate manufacturing consumes high-purity novolac epoxy formulations in multilayer board fabrication. Guangdong fabrication clusters drive regional demand concentration, with layer-count specifications rising alongside chip complexity.
- Adhesives:Structural bonding applications in automotive and construction balance cure speed with thermal stability requirements.
- Composites:Aerospace prepregs and industrial fiber-reinforced plastics represent the steepest expansion trajectory as weight reduction mandates penetrate airframe design.
Coatings command volume leadership. Composites climb the fastest.
End User:
End-user segmentation maps directly onto regulatory exposure profiles, with aerospace and electronics facing the most stringent material qualification protocols.
- Electronics:Semiconductor packaging and PCB fabrication impose purity specifications that exclude all but dedicated production lines. Japan's METI standards and South Korea's MFDS requirements create dual compliance burdens for suppliers serving both markets.
- Aerospace:Structural thermoset applications for airframes and engine components demand flame-smoke-toxicity certification under FAA and EASA protocols. Boeing and Airbus qualification timelines stretch 18-36 months, locking in supplier relationships.
- Automotive:Brake friction materials and underhood electrical components sustain phenolic resin consumption despite lightweighting pressures on non-structural applications.
- Construction:Composite wood binders and insulation materials face formaldehyde emission restrictions under EPA TSCA Title VI and comparable state-level regulations in California.
Electronics generates the highest margin pool. Aerospace posts the steepest qualification barriers.
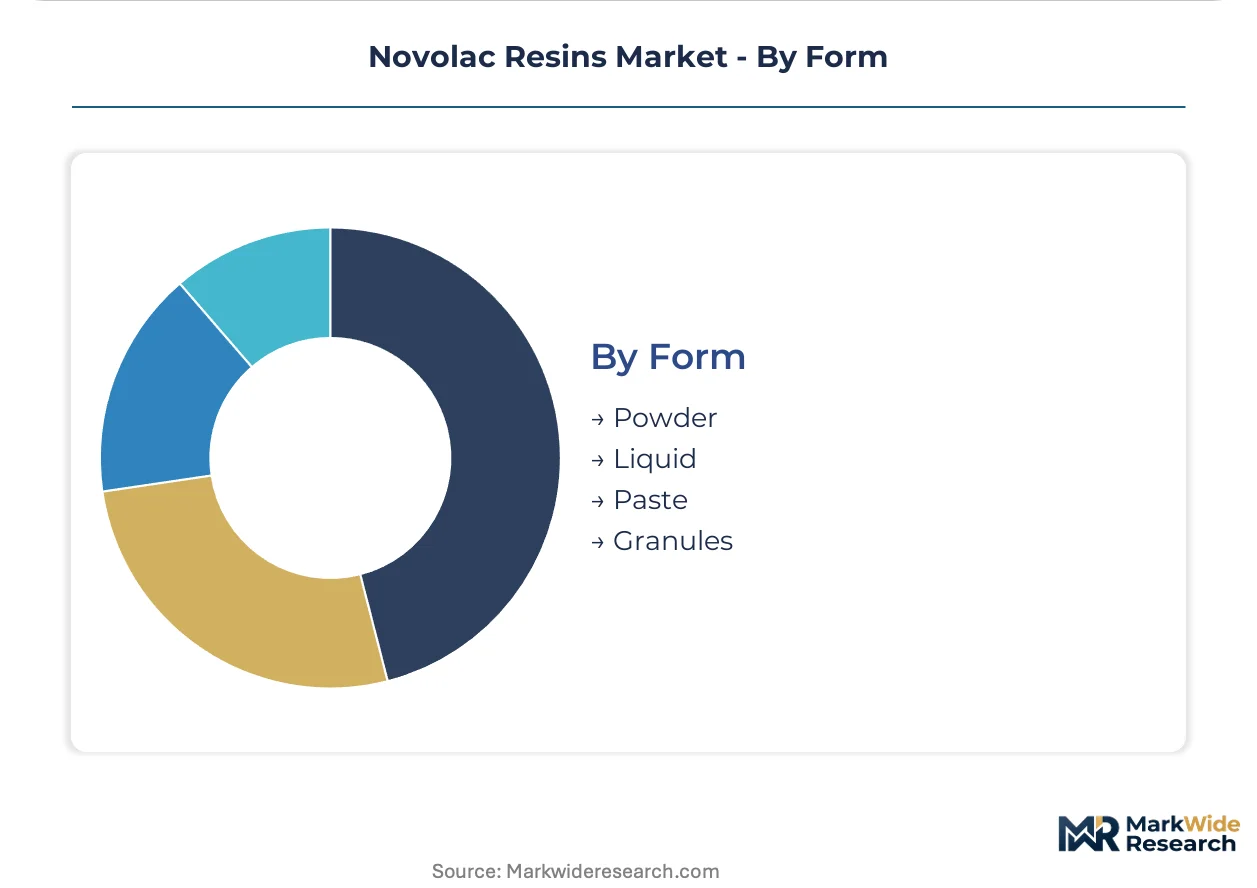
Form:
Physical form selection reflects processing economics and shelf-life requirements, with powder formats dominating high-volume coating applications.
- Powder:Solid novolac grades enable solvent-free coating application and extended storage stability. Industrial powder coating lines in Germany and the United States specify these forms for environmental compliance and handling efficiency.
- Liquid:Solvent-borne and waterborne dispersions serve adhesive and composite wet layup processes where flow characteristics control fiber wetout quality.
- Paste:High-viscosity formulations with mineral fillers target trowel-applied corrosion protection and joint sealing applications.
- Granules:Free-flowing particulate forms facilitate automated metering in friction material batching and foundry sand binding.
Powder leads by tonnage. Liquid forms expand most quickly in electronics encapsulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronics manufacturing clusters in East Asia command the dominant share of high-purity novolac resin consumption, while European regulatory pressure and North American industrial demand define secondary demand poles.
China
Guangdong province hosts the world's densest concentration of PCB fabrication facilities, with Shenzhen and Dongguan clusters scaling captive novolac epoxy formulation capacity. MEE dual carbon goals enforce energy-efficient condensation processes and solvent recovery mandates. Shanghai Yangtze River Delta electronics assemblers are pulling premium-grade novolac supply for advanced packaging applications.
Japan
Semiconductor molding compound producers in Kyushu and Nagoya require sub-ppm ionic contamination thresholds that exclude non-dedicated production lines. METI standards for advanced chip packaging create compliance burdens unmatched elsewhere. Osaka-based specialty chemical houses maintain captive phenol-to-novolac integration to secure raw material security.
South Korea
Memory and logic chip packaging facilities in Gyeonggi-do and Pyeongtaek drive ultra-high-purity novolac specifications. MFDS pharmaceutical-grade chemical oversight extends to electronics material contamination protocols. Busan-Ulsan chemical complexes are expanding phenolic resin capacity to serve domestic electronics supply chains.
Germany
Automotive friction material manufacturers in North Rhine-Westphalia sustain volume offtake for brake pad applications. KBA automotive material safety standards and REACH formaldehyde thresholds compress formulation flexibility. BASF Ludwigshafen operations exemplify integrated phenol-to-novolac manufacturing that absorbs compliance costs.
United States
Industrial coatings producers in Texas and Louisiana leverage novolac chemical resistance for oilfield equipment protection. EPA TSCA Title VI restricts formaldehyde emissions from composite wood products, shaping construction-grade formulation requirements. Gulf Coast petrochemical corridors supply phenol feedstock to regional novolac resin operations.
Novolac Resins Market Competitive Landscape
East Asian producers anchor one tier; European and North American specialists hold differentiated positions in compliance-intensive segments. Market structure tilts toward consolidation at the high-purity electronics grade tier while remaining fragmented in industrial coatings. Three archetypes dominate: integrated phenol-to-novolac operators, captive epoxy hardener producers, and ultra-high-purity specialists. Capacity expansion and backward integration into phenol supply represent the dominant competitive moves.
Among integrated chemical conglomerates, Hexion and Mitsui Chemicals exemplify archetypes that absorb regulatory costs through manufacturing footprint control. Kukdo Chemical occupies a position among Korean producers that anchor electronics supply chain security through captive hardener production. These three entities represent distinct strategic postures without implying specific market share claims.
| Leading Market Players |
|---|
| Olin Corporation |
| Kukdo Chemical |
| Hexion |
| Georgia-Pacific Chemicals |
| Westlake Epoxy |
| DIC Corporation |
| KOLON Industries |
| Mitsui Chemicals |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Semiconductor-grade purity mandates from Japan's METI and South Korea's MFDS are forcing supply reconfiguration toward dedicated production lines, compressing merchant resin availability and elevating premium tier pricing power for qualified suppliers.
Pricing Analysis
Volume leadership sits with standard-grade novolac phenolic resins for coatings and friction materials, while margin concentration flows to ultra-high-purity novolac epoxy grades for semiconductor packaging. Pricing stratifies across premium, standard, and economy tiers based on ionic contamination thresholds and certification grade. Cost compression in standard grades is intensifying because REACH formaldehyde compliance investments cannot be fully passed through to price-sensitive construction adhesives buyers. Electronics manufacturers demonstrate the lowest price sensitivity, absorbing specialty premiums for lot traceability and sub-ppm purity guarantees.
Supply Chain Analysis
Single-source vulnerability sits with hexamethylenetetramine crosslinker production, which clusters in specific chemical manufacturing corridors and creates hardening system fragility. Phenol feedstock draws from benzene cracking operations concentrated in China, South Korea, and the United States Gulf Coast. Tariff exposure on carbon-intensive phenolic imports under EU Green Deal border adjustments threatens European supply security. Distribution runs through direct phenol-to-laminate integration among Guangdong and Taiwan-based PCB manufacturers, displacing traditional merchant resin channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-absorbing integrated producers, with REACH substance registration costs and high-purity synthesis expertise scarcity forcing sub-scale competitors toward exit or acquisition.
For Market Incumbents: Anticipate formaldehyde substitution pressure in construction adhesives by accelerating bio-phenol pilot scale integration and securing captive epoxy hardener supply through backward integration into hexamethylenetetramine production. Defensive positioning requires pre-registering low-free-formaldehyde grades under ECHA protocols ahead of SVHC list expansion. For New Entrants and Emerging Players: The premium-to-economy price-point gap in India electronics manufacturing offers white-space entry under PLI scheme subsidies for semiconductor and PCB production. Target aerospace composites qualification in weight-critical airframe applications previously served by epoxy-amine systems, leveraging novolac-cyanate ester blend performance advantages. Go-to-market through direct mill supply agreements with vertically integrated laminate manufacturers bypasses distributor compression. For Investors and Strategic Acquirers: The window for entry favors integrated phenol-to-novolac operators with established ECHA safety dossiers and electronics-grade certification. Long-term viability hinges on carbon capture or bio-phenol process configurations that neutralize EU Green Deal border adjustment exposure. Monitor ECHA SVHC candidate list expansion velocity as the inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Supply | Hexion's Ludwigshafen operations demonstrate compliance cost absorption through captive feedstock security. |
| Green Manufacturing Transition | Lignin-derived bio-phenol pilots in European facilities preempt carbon intensity disclosure mandates under EU Green Deal. |
| Long-term Supply Agreement | Guangdong PCB clusters are locking in direct phenol-to-laminate integration to secure formulation consistency. |
| Joint Venture | Busan-Ulsan chemical complexes are expanding phenolic resin capacity through domestic electronics supply chain partnerships. |
| Capacity Expansion | Kyushu and Nagoya semiconductor molding compound producers are pulling dedicated high-purity production line investment. |
Research Methodology
Independent corroboration across plant managers at phenol-to-novolac integrated facilities, procurement leads at downstream PCB laminate manufacturers, and distribution channel partners in East Asian electronics supply chains underwrites the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from segmented demand elasticity analysis and input cost trajectory modeling. Forecast inputs include phenol feedstock cracking economics, REACH substance registration timeline assumptions, and electronics packaging technology node migration patterns.
Inputs from ECHA registration databases and MEE environmental compliance disclosures were available through the study window; gaps in real-time hexamethylenetetramine production capacity data introduce uncertainty bands around hardener supply security assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market