
 Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market | 2026-2036
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market Foresight
Modular window-wall systems is pivoting how commercial contractors evaluate UPVC suppliers. VEKA AG leverages its extrusion technology leadership to supply integrated frame-gasket hardware kits. Rehau Group anchors its position through backward integration into polymer compounding. Fenesta Building Systems dominates India's project channel through direct sales to real estate developers.
Unplasticized Polyvinyl Chloride (UPVC) windows are rigid thermoplastic fenestration systems manufactured from PVC resin without plasticizer additives, typically formulated with titanium dioxide for UV resistance and calcium-zinc stabilizers for thermal stability, extruded into multi-chamber hollow profiles that achieve U-values below 1.0 W/m²K when glazed with low-emissivity glass. These systems serve primarily as thermally efficient, low-maintenance building envelopes for residential and commercial structures. Casement configurations occupy the largest share among product types due to superior sealing performance and established installer familiarity. Tilt-and-turn mechanisms represent the fastest-growing product category as European design standards penetrate Asian residential markets. Premium material grades command concentrated margin pools where architects specify color-fast profiles for coastal and high-altitude exposures.
The EU Green Deal and REACH frameworks mandate phased reductions in embodied carbon for construction products, compelling profile extruders to reformulate stabilizer packages and validate recyclability through ECHA-registered testing protocols. India's BIS certification for UPVC window profiles under IS 17917 creates mandatory quality gates for domestic manufacturers and importers alike. Fenestration stakeholders must monitor how national building codes integrate whole-window lifecycle assessments into procurement criteria.
Market Dynamics
Modular window-wall systems are restructuring procurement relationships between commercial contractors and UPVC extruders, compressing traditional distributor margins while rewarding integrated hardware-software suppliers with direct specification access.
Growth Catalysts
- EU Green Deal building renovation targets:Mandatory thermal performance upgrades across Germany, France, and Poland are accelerating replacement cycles for aging aluminum and timber fenestration in residential stock.
- Tilt-and-turn mechanism adoption:German multifamily builders are specifying these configurations as standard, driving fabricator investment in hardware integration capabilities.
- India's urban corridor concentration:High-rise residential tower construction between Mumbai and Delhi is absorbing volume from organized fabricators with BIS-certified profile supply chains.
Market Restraints
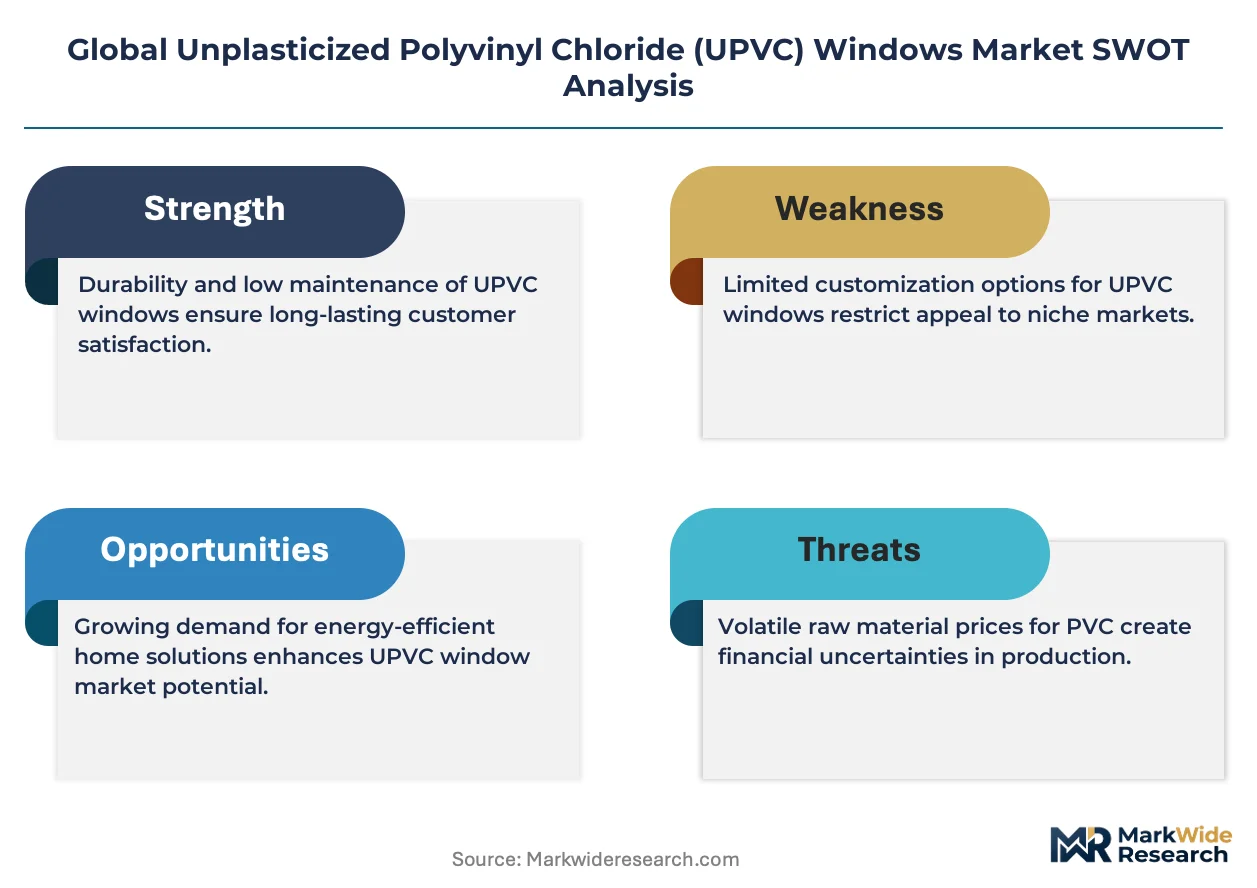
- Polymer resin cost volatility:PVC feedstock prices track ethylene and chlorine derivatives, squeezing extruder margins during upstream petrochemical disruptions.
- REACH compliance burden:ECHA-registered testing protocols for stabilizer reformulation add validation costs and timeline risk for European profile manufacturers.
- Aluminum composite substitution:Thin-profile aluminum systems with thermal breaks compete for premium commercial facade specifications where structural sightlines dominate.
Strategic Opportunities
- Underpenetrated Indian secondary cities:Tier-2 and Tier-3 urban centers lack organized fabrication infrastructure, creating whitespace for system houses with mobile training and logistics capabilities.
- Photovoltaic-integrated glazing convergence:Building-integrated photovoltaics paired with UPVC frames opens new specification channels for net-zero commercial envelopes.
- Direct-to-developer sales channels:Real estate procurement centralization in India and Poland favors fabricators bypassing traditional distributor networks.
Industry Challenges
- Fabricator skill certification gaps:Multi-chamber profile welding and hardware alignment require trained installers, creating bottlenecks in markets with fragmented contractor bases.
- Whole-window lifecycle assessment integration:National building codes are embedding embodied carbon calculations into procurement criteria, forcing rapid EPD documentation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market |
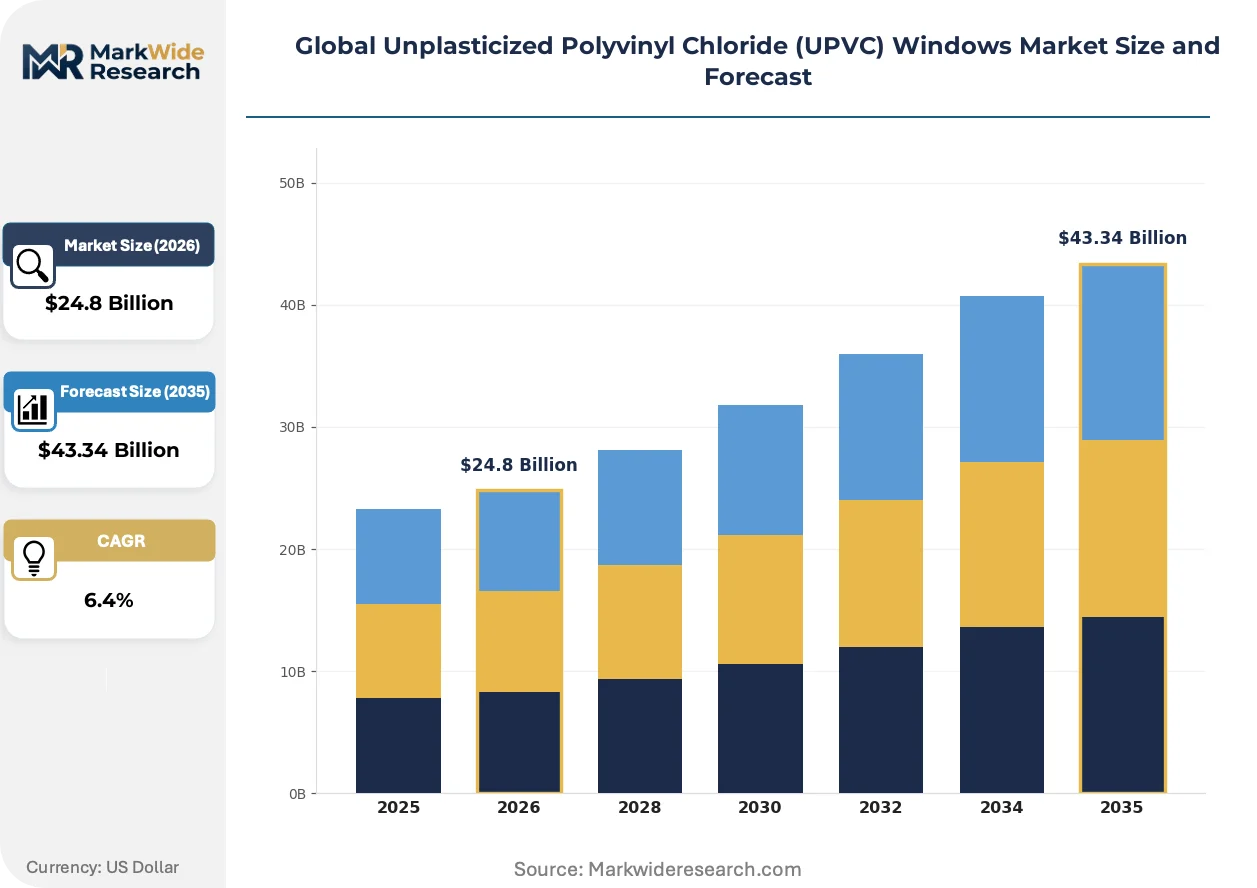
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casement, Sliding, Awning, Fixed, Tilt and Turn Material Grade: Premium, Standard, Fire Resistant, UV Stabilized, Weatherproof End User: Residential Builders, Commercial Contractors, Renovation Specialists, Real Estate Developers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers, Specialty Stores |
| Companies Covered | VEKA AG, Deceuninck NV, Rehau Group, LIXIL Group, Profine GmbH, Andersen Corporation, JELD-WEN Holding, Fenesta Building Systems, YKK AP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market Shifts & Advancements
Extrusion technology and regulatory chemistry are converging to redefine competitive advantage, with thermal performance validation and circular material flows becoming primary differentiation vectors rather than secondary compliance checkboxes.
Co-extruded color-fast surface layers with ASA capstock are consolidating specification preference among architects designing coastal and high-altitude residential projects. German and Austrian facade consultants specify these grades for UV resistance guarantees exceeding fifteen years. The technology is consolidating premium margin pools away from painted or laminated alternatives that carry delamination risk in freeze-thaw cycling.
REACH mandates on lead and cadmium stabilizer phase-outs are forcing reformulation investments across European extrusion plants. ECHA-registered calcium-zinc and organic-based alternatives require revalidation of weathering performance through accelerated aging protocols. Profile manufacturers serving Nordic markets face the tightest compliance timelines as national building codes anticipate 2027 restriction deadlines.
Developer-led procurement centralization is displacing fragmented contractor purchasing in Indian high-rise residential construction. Organized real estate players in Mumbai and Delhi now specify system-integrated hardware directly, compressing traditional distributor roles. Poland exhibits similar concentration as institutional investors standardize fenestration packages across multifamily portfolios.
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market Segmentation
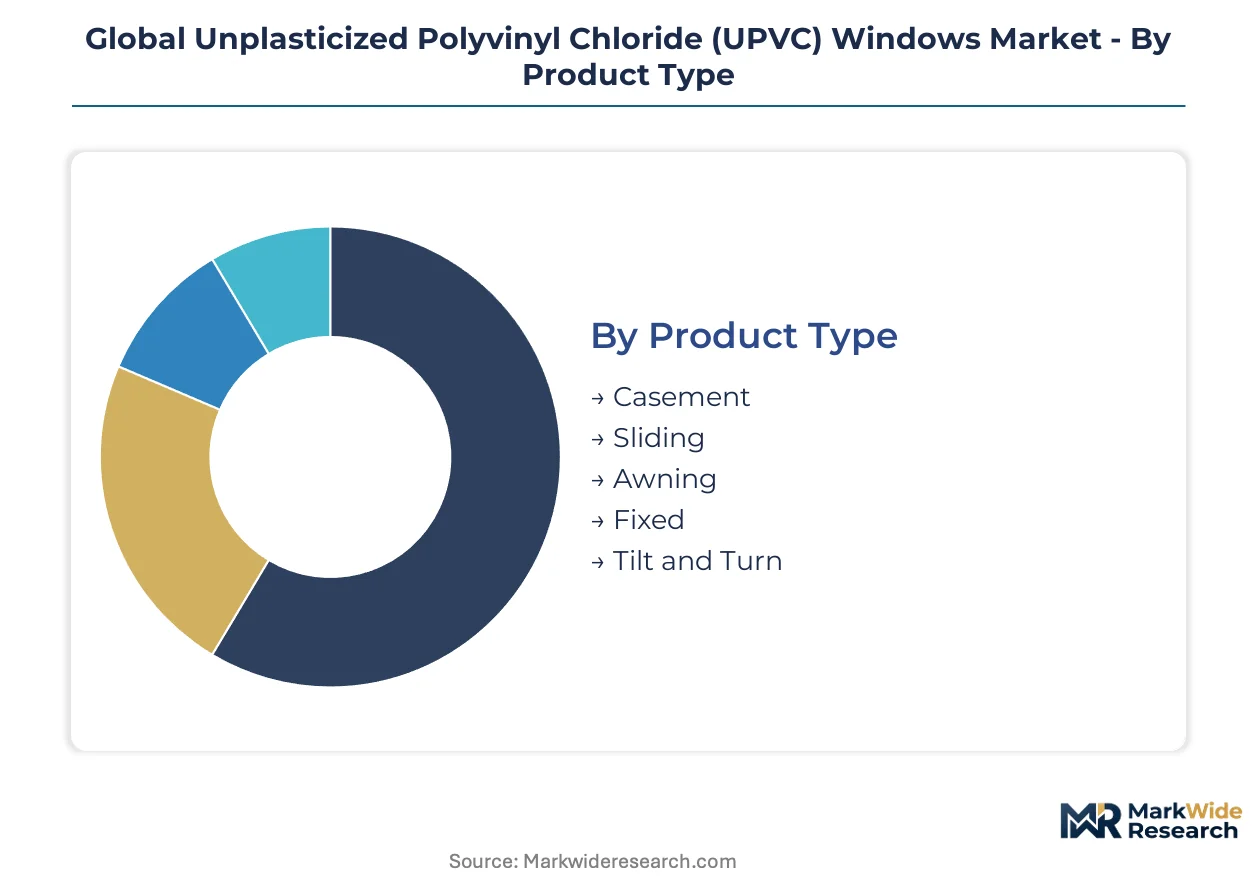
UPVC window procurement patterns diverge sharply across buyer archetypes, with thermal performance thresholds, hardware integration complexity, and project financing structures dictating segment-specific supplier requirements. Understanding these fault lines enables extruders to align extrusion capacity and certification investments with margin-concentrated demand pools.
Product Type:
Architects and builders select configurations based on ventilation control precision, structural sightline constraints, and installer familiarity with hardware alignment protocols.
- Casement:Side-hinged sashes with compression-seal gaskets deliver superior air-tightness ratings, making them the default specification for German and Polish residential retrofits targeting sub-1.0 W/m²K envelope performance. Fabricator training investments concentrate in established European markets where weld-quality certification gates installer eligibility.
- Tilt and Turn:Dual-axis hardware enables both top-ventilation and full inward-swing cleaning positions, penetrating Indian high-rise residential towers where German design standards influence developer specifications. Mumbai and Delhi fabricators report hardware lead times as the binding constraint on project delivery.
- Sliding:Horizontal track systems dominate space-constrained retrofits in Japanese urban apartments where outward-opening sashes violate balcony setback codes.
- Awning:Top-hinged rain-shedding geometry suits coastal Australian residential markets where AS 2047 wind-load ratings mandate reinforced frame chambers.
- Fixed:Non-operable picture windows command premium glazing budgets in commercial atrium specifications where thermal bridge minimization outweighs ventilation requirements.
Casement leads volumes today; tilt and turn is gaining share fastest.
Material Grade:
Cost-to-performance positioning stratifies around climate exposure severity, facade longevity guarantees, and insurance-backed warranty requirements.
- Premium:Co-extruded ASA capstock surface layers with titanium dioxide loadings exceeding 8% by weight deliver color-fast guarantees exceeding fifteen years in coastal and high-altitude UV environments. Austrian facade consultants specify these grades for Alpine residential developments where freeze-thaw cycling accelerates surface degradation.
- Standard:Monolayer profiles with calcium-zinc stabilization satisfy BIS IS 17917 baseline requirements for Indian urban residential towers where first-cost optimization dominates developer procurement criteria.
- Fire Resistant:Intumescent gasket integration and halogen-free flame retardant packages address UK Building Regulations Part B compliance for mid-rise residential escape routes.
- UV Stabilized:Enhanced TiO2 formulations target Australian and Saudi Arabian markets where solar irradiance exceeds 2000 kWh/m² annually.
- Weatherproof:Dual-durometer gasket co-extrusion suits Nordic coastal exposures where salt spray and driving rain test seal integrity across seasonal temperature swings.
Standard grade dominates unit volumes; premium commands the steepest margin expansion trajectory.
End User:
Procurement centralization intensity and technical specification authority vary dramatically across buyer types, reshaping channel economics for profile extruders.
- Residential Builders:German multifamily contractors specify tilt-and-turn hardware integration as standard, driving fabricator consolidation around system houses with captive machining capabilities.
- Commercial Contractors:Modular window-wall procurement for Polish office developments favors direct extruder relationships that compress traditional distributor margins while rewarding integrated frame-gasket-hardware kit suppliers.
- Renovation Specialists:French residential retrofit contractors responding to EU Green Deal thermal performance mandates prioritize fast-install replacement systems with minimal structural modification requirements.
- Real Estate Developers:Organized Indian developers in Mumbai and Delhi now bypass distributor networks entirely, specifying BIS-certified profiles through direct system house partnerships that bundle hardware, glazing, and installation training.
Real estate developers are consolidating procurement fastest; renovation specialists remain the most fragmented buyer type.
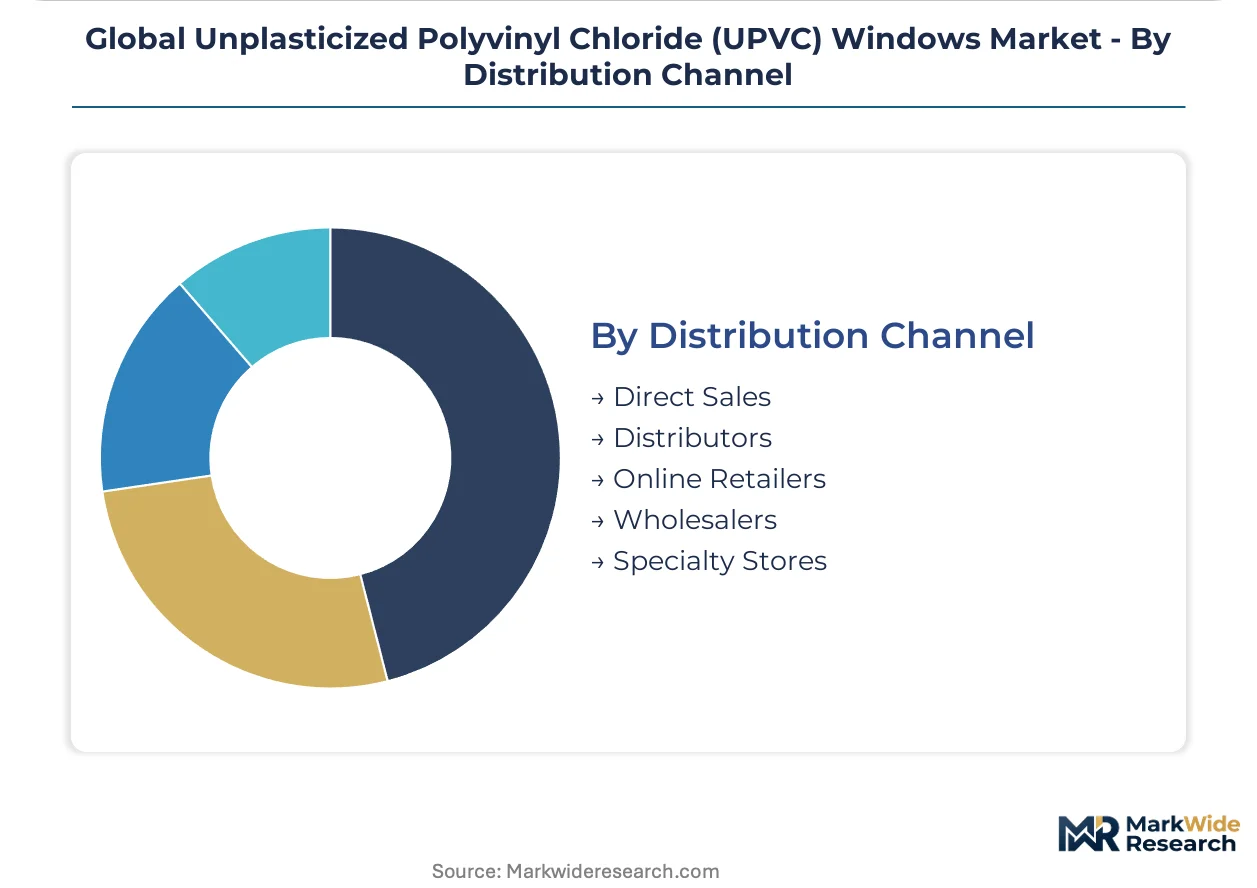
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to fabrication infrastructure.
- Direct Sales:System houses serving Indian and Polish real estate developers maintain captive specification teams that embed thermal performance modeling into early-stage architectural design.
- Distributors:Regional stockists dominate fragmented French and Italian residential retrofit markets where contractor order sizes fall below extruder minimums.
- Online Retailers:Digital platforms capture replacement sash and hardware orders from UK and German DIY homeowners with standardized profile dimension knowledge.
- Wholesalers:Volume aggregators supply Indian Tier-2 and Tier-3 city fabricators lacking direct system house relationships.
- Specialty Stores:Showroom-based consultative selling persists in Japanese and Swiss markets where architect-specified custom color matching commands premium positioning.
Direct sales channels are expanding most quickly; distributors retain dominance in fragmented European retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineers pioneered multi-chamber UPVC extrusion during the 1970s energy crisis, establishing thermal performance benchmarks that now dominate specification standards across temperate climates worldwide.
Germany
Tilt-and-turn hardware integration commands specification preference among multifamily developers in Berlin and Hamburg. REACH mandates on lead stabilizer phase-outs compel extruders to validate calcium-zinc alternatives through ECHA-registered protocols. The Rhine-Ruhr industrial corridor concentrates profile manufacturing capacity serving renovation contractors responding to EU Green Deal thermal upgrade targets.
India
High-rise residential towers between Mumbai and Delhi absorb organized fabrication output as real estate developers centralize procurement. BIS certification under IS 17917 creates mandatory quality gates for domestic manufacturers and importers alike. Fenesta Building Systems anchors direct sales relationships with developers in the Mumbai-Pune corridor, bypassing traditional distributor networks entirely.
Poland
Institutional investors standardize fenestration packages across multifamily portfolios, compressing contractor purchasing discretion. EU Green Deal building renovation targets accelerate replacement cycles for aging aluminum frames in Warsaw and Kraków residential stock. The Silesian manufacturing basin hosts extrusion plants supplying modular window-wall systems to commercial contractors.
United States
New construction in Texas and Florida favors vinyl window systems for cost-efficient thermal compliance with IECC codes. EPA and state-level energy efficiency programs influence residential builder specification patterns. The Southeast manufacturing belt from Georgia to the Carolinas concentrates extrusion capacity serving national distribution networks.
Japan
Space-constrained urban apartments in Tokyo and Osaka specify sliding configurations where outward-opening sashes violate balcony setback codes. METI building energy standards drive replacement demand in aging residential stock. The Kanto industrial region hosts fabrication facilities serving architect-specified custom color matching for premium residential developments.
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material grade and hardware integration capabilities. The vendor base stratifies into three tiers: system houses with captive compounding and machining, regional fabricators dependent on third-party profile supply, and project-specific installers without extrusion assets. Strategic moves concentrate on backward integration into polymer compounding and direct specification relationships with real estate developers.
Among European-headquartered system houses, VEKA AG and Rehau Group exemplify the integrated archetype with upstream control over formulation and downstream hardware kit integration. Fenesta Building Systems represents the direct-to-developer channel model that is displacing traditional distribution in high-growth Asian markets. These three anchors demonstrate how geographic origin and corporate structure correlate with competitive positioning across margin tiers.
| Leading Market Players |
|---|
| VEKA AG |
| Deceuninck NV |
| Rehau Group |
| LIXIL Group |
| Profine GmbH |
| Andersen Corporation |
| JELD-WEN Holding |
| Fenesta Building Systems |
| YKK AP |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon mandates gate qualified supply for premium-tier UPVC window systems, compelling extruders to absorb ECHA-registered testing costs while restricting specification access to calcium-zinc stabilized profiles with validated EPD documentation. This regulatory filter concentrates pricing power among system houses with captive compounding assets, compressing margins for distributors dependent on commodity-grade feedstock.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies UPVC window procurement by certification grade and hardware integration depth. Premium ASA capstock profiles command margin expansion through fifteen-year color-fast guarantees demanded by Alpine and coastal architects, while standard BIS-certified grades face cost compression from resin volatility and first-cost optimization among Indian developers. Price differentiation hinges on REACH compliance status and direct-to-developer channel access. Margins are tightening in the standard tier due to ethylene derivative cost swings, whereas renovation specialists in France exhibit highest price sensitivity and German multifamily contractors show lowest sensitivity to hardware premiums.
Supply Chain Analysis
Dual-sourcing requirements from institutional investors in Poland and India mandate multi-supplier qualification for profile extruders, forcing system houses to maintain redundant fabrication partnerships. Supply concentrates in Germany, India, and Poland, with the Rhine-Ruhr corridor anchoring European extrusion capacity and the Mumbai-Pune corridor serving Indian high-rise demand. Raw material dependencies rest on PVC resin, titanium dioxide UV stabilizers, and calcium-zinc compounding packages. Single-source vulnerability runs through ethylene-chlorine derivative supply chains exposed to petrochemical disruption. Distribution runs through direct sales channels for organized real estate developers, while regional stockists serve fragmented European retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UPVC window market represents a late-cycle quality story where specification authority migrates toward premium-grade, lifecycle-assessed systems as EU Green Deal renovation targets harden thermal performance thresholds across residential stock.
For Market Incumbents: Anticipate aluminum composite substitution pressure in commercial facade specifications by deepening captive compounding capabilities and accelerating EPD documentation for calcium-zinc stabilized profiles. Defensive consolidation around direct-to-developer channel control in India and Poland protects margin pools from distributor disintermediation. Priority investment targets hardware-integrated kit production and REACH-compliant stabilizer reformulation ahead of 2027 Nordic restriction deadlines. For New Entrants and Emerging Players: Renovation specialists in French and Italian residential retrofit markets present the most penetrable buyer archetype, fragmented across regional contractors lacking system house relationships. Whitespace concentrates in Tier-2 and Tier-3 Indian cities where organized fabrication infrastructure remains underdeveloped. A mobile training and logistics platform paired with BIS-certified profile supply chains enables rapid contractor base cultivation without extruder asset intensity. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fabricators with captive machining capabilities because procurement centralization among real estate developers favors scaled system houses with direct specification access. Long-term viability over the next decade hinges on backward integration into polymer compounding and EPD-generation infrastructure. The signal to watch is national building code adoption of whole-window lifecycle assessments as mandatory procurement criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-mandated stabilizer reformulation requires in-house calcium-zinc validation capabilities. |
| Direct-to-Developer Sales Channel Expansion | Real estate procurement centralization in Mumbai and Delhi rewards bypassing distributor networks. |
| EPD Documentation Capability Buildout | EU Green Deal procurement criteria embed embodied carbon calculations into specification gates. |
| Mobile Training Infrastructure Deployment | Fabricator skill gaps in Indian Tier-2 cities create whitespace for system house expansion. |
| Photovoltaic-Integrated Glazing Partnership | Building-integrated photovoltaics convergence opens net-zero commercial envelope specifications. |
Research Methodology
Coverage spans Germany, India, Poland, the United States, and Japan, with primary inputs from each market gathered through structured interviews with profile extrusion plant managers, real estate developer procurement leads, facade consultant specification architects, regional fabrication contractors, and BIS certification auditors. Secondary validation draws from REACH ECHA registration databases, BIS IS 17917 certification records, EU Green Deal building renovation target documentation, and SEC filings from publicly traded building products manufacturers. Bottom-up volume triangulation across product type, material grade, and end-user segments reconciles with top-down market sizing from customs trade data and industry association reports.
Granularity-level modeling operates at the intersection of hardware configuration complexity, thermal performance certification tier, and channel structure intensity. Segmentation dimensions include product type, material grade, end-user archetype, and distribution channel, with additional modeling of regional regulatory cluster effects on procurement timing. CAGRs were derived from trend extrapolation of replacement cycle acceleration and new construction absorption rates, cross-referenced with resin cost elasticity assumptions and fabricator capacity expansion announcements. Industry-specific forecast inputs incorporate EU Green Deal renovation target implementation schedules and Indian urban corridor high-rise permitting velocity.
Underlying measurement precision varies by segment; premium-grade and direct-sales channels carry tighter precision than economy-tier and wholesale-distributed volumes due to consolidated reporting from system houses. Forecasts reflect assumptions about regulatory timeline adherence, resin cost normalization, and contractor training pipeline throughput that could shift materially with petrochemical supply disruptions or building code amendment cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
High Density Polyethylene (HDPE) Market