
 Thermoplastic Ester Elastomer (TPEE) Market | 2026-2036
Thermoplastic Ester Elastomer (TPEE) Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Ester Elastomer (TPEE) Market Analytics
High-performance automotive specification grades is rotating toward broader industrial adoption as compounders broaden thermal resistance thresholds. BASF SE leverages integrated polyol supply chains to sustain cost-advantaged TPEE compound production. DuPont anchors North American demand through specialized electrical insulation formulations. LG Chem competes on scale in Asian automotive supply chains with standardized molding grades.
Thermoplastic ester elastomers are segmented polyester-polyether block copolymers combining rubber-like elasticity with thermoplastic processability, typically exhibiting Shore D hardness of 35-80 and continuous service temperatures up to 150°C. TPEE compounds dominate volume due to their direct injection-molding compatibility for under-the-hood automotive components. TPEE moldings capture expanding margin pools as medical device manufacturers specify biocompatible soft-touch grips with autoclavable performance. Automotive parts remains the leading application dimension, though electrical insulation is accelerating with EV platform voltage upgrades.
EPA tailpipe standards and NHTSA fuel economy mandates in the United States compel automakers to substitute TPEE for heavier vulcanized rubber in sealing systems. REACH substance restrictions and the EU F-Gas Regulation in Europe restrict certain plasticizer chemistries, redirecting formulation R&D toward halogen-free TPEE blends. Stakeholders must monitor evolving automotive OEM material qualification protocols and polymer recycling infrastructure investments to align capacity with next-generation specification requirements.
Market Dynamics
Automotive OEM material qualification protocols are compressing supplier timelines while demanding higher thermal performance thresholds, forcing compounders to accelerate R&D cycles for halogen-free formulations that satisfy simultaneous EPA tailpipe standards and REACH substance restrictions.
Growth Catalysts
- EV platform voltage upgrades:Battery pack architectures above 800V require TPEE electrical insulation with enhanced dielectric strength, pulling specialized grades into high-volume production schedules.
- REACH substance restrictions:ECHA's tightening plasticizer bans redirect formulation investment toward intrinsically flexible polyester-polyether block copolymers that eliminate external plasticizer loadings.
- German automotive compounding cluster:Dense supplier networks around Ludwigshafen and Domat/Ems enable rapid prototype-to-production scaling for under-the-hood sealing specifications.
Market Restraints
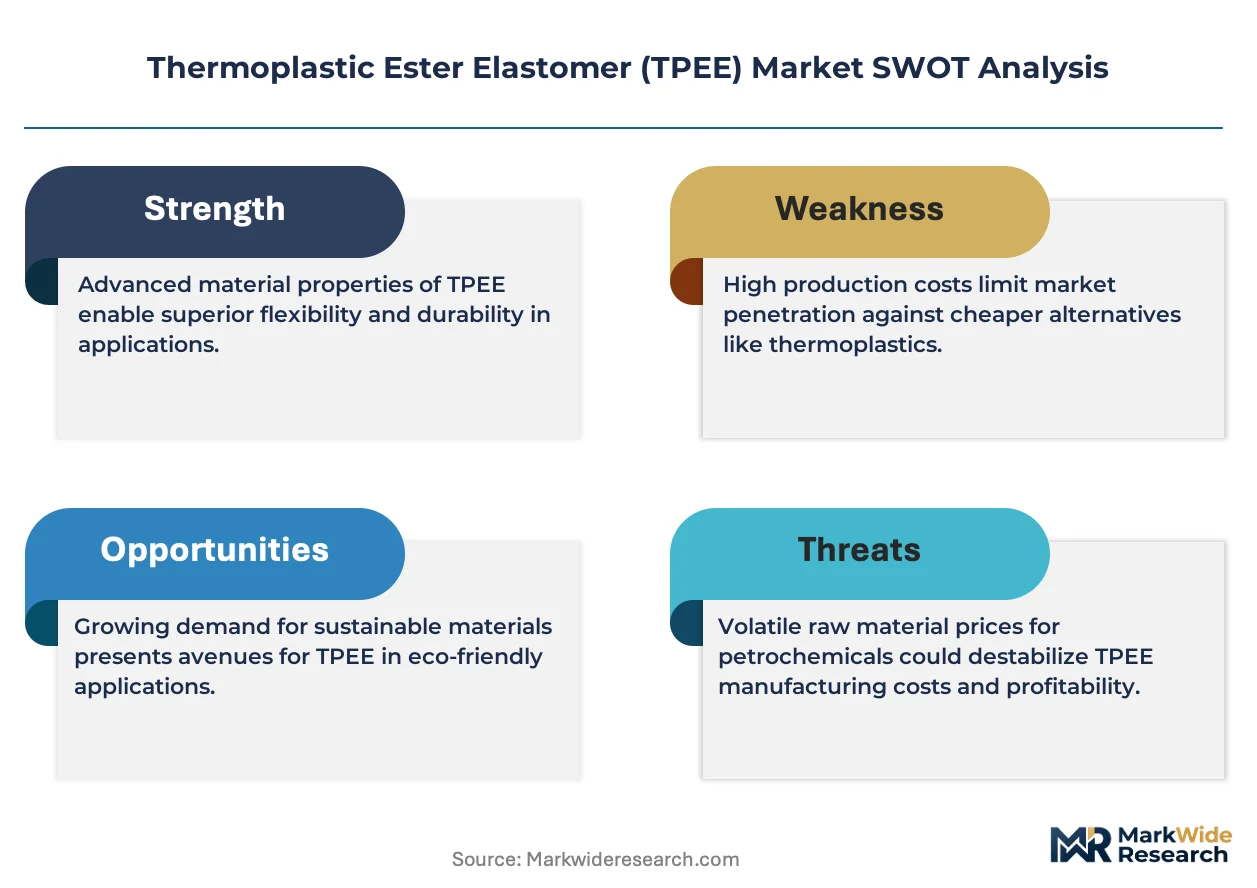
- Butanediol feedstock volatility:TPEE backbone chemistry depends on BDO pricing swings tied to Asian acetylene-based production economics, compressing compounder margins unpredictably.
- Specialized Shore D 35-80 grade concentration:High-specification automotive qualifications concentrate among three integrated polyol producers, creating single-source vulnerability for tier-2 molders.
- Autoclave sterilization ceiling:Medical device manufacturers face 134°C steam cycle limits that restrict TPEE adoption against silicone alternatives in repeated-use surgical instruments.
Strategic Opportunities
- Indian medical device manufacturing:CDSCO's streamlined Class A/B device approvals and PLI scheme incentives attract TPEE grip and tubing producers to Ahmedabad-Pune corridor.
- Soft-touch industrial robotics:Collaborative robot arm coverings requiring 10^6+ flex cycles without fatigue represent unpenetrated demand beyond traditional automotive applications.
- EU F-Gas Regulation:Refrigeration sealing mandates favor low-permeability TPEE over HNBR in commercial HVAC systems, creating specification pull through 2030 phase-down schedules.
Industry Challenges
- Polymer rheology expertise scarcity:Injection molding TPEE at 240-280°C melt temperatures without degradation requires process engineers with specific polyester-polyether copolymer experience that resin suppliers struggle to train at scale.
- OEM qualification timeline compression:Volkswagen Group and Stellantis now demand 18-month material validation cycles versus historical 36-month windows, straining compounder testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Ester Elastomer (TPEE) Market |
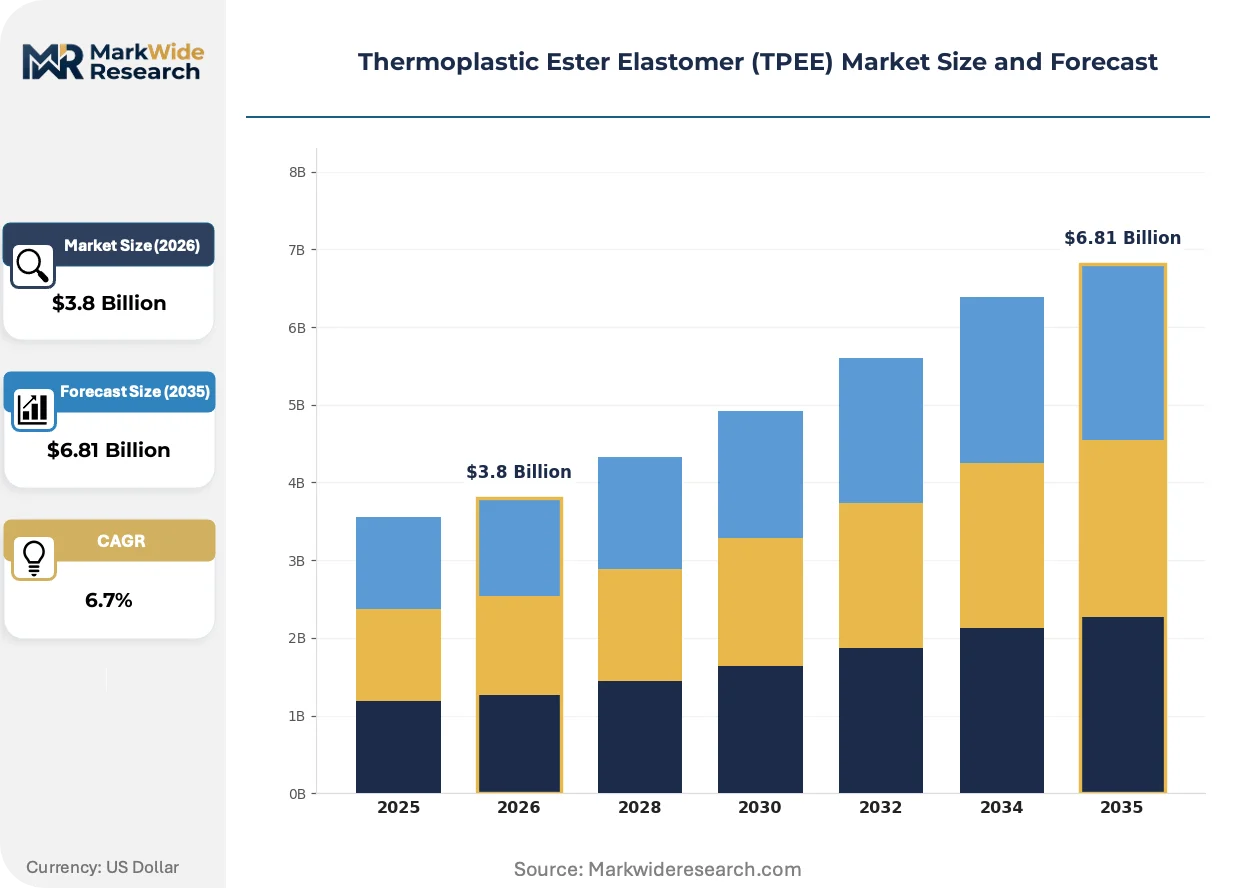
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: TPEE Blends, TPEE Compounds, TPEE Films, TPEE Moldings End User: Automotive OEMs, Consumer Electronics, Medical Devices, Industrial Components Application: Automotive Parts, Electrical Insulation, Sealing Solutions, Soft Touch Grips Distribution Channel: Direct Sales, Distributors, Online Retail, Value-Added Resellers |
| Companies Covered | BASF SE, LG Chem, DuPont, Toray Industries, Eastman Chemical Company, Lubrizol Corporation, EMS-CHEMIE HOLDING AG, Asahi Kasei Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Ester Elastomer (TPEE) Market Evolving Landscape
Formulation chemistry and processing technology are converging to expand TPEE applicability beyond traditional automotive perimeters into medical, electrical, and industrial robotics domains previously served by thermoset alternatives.
Halogen-free flame-retardant TPEE grades incorporating phosphorus-nitrogen synergists are displacing brominated compounds in EV battery module insulation. Tier-1 suppliers to Tesla and BYD have accelerated adoption since 2023. This displacement is compressing legacy FR additive supply chains while rewarding compounders with in-house reactive extrusion capabilities.
REACH Annex XVII substance restrictions on medium-chain chlorinated paraffins and certain phthalate plasticizers are eliminating formulation flexibility for conventional TPE modifiers. Compounders must redesign Shore hardness gradients using intrinsic block copolymer architecture rather than additive blending. German automotive OEMs are responding by consolidating qualified supplier lists to those with full polymerization-to-compounding integration.
Medical device OEMs now specify autoclavable soft-touch materials through direct long-term agreements with compounders, bypassing traditional distributor channels. This disintermediation concentrates volume with BASF SE and EMS-CHEMIE HOLDING AG for surgical instrument grips. Switzerland's medical device cluster around Solothurn exhibits the most advanced procurement model evolution, with OEMs demanding lot-level biocompatibility documentation (ISO 10993) and recycled content traceability simultaneously.
Thermoplastic Ester Elastomer (TPEE) Market Segmentation
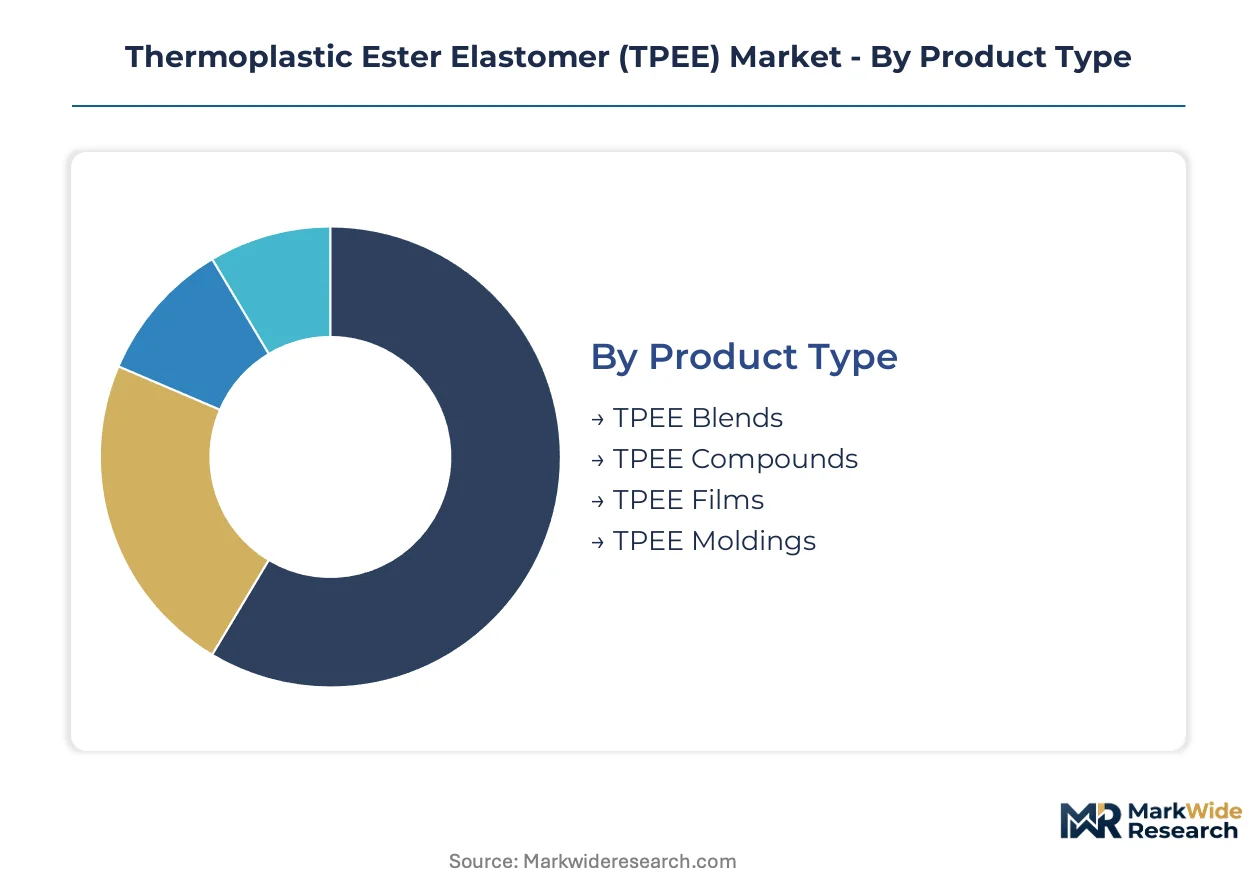
TPEE market segmentation reveals how material specifications diverge across processing methods and end-use performance requirements. Each dimension carries distinct substitution pressures from thermoset elastomers, commodity thermoplastics, and emerging bio-based alternatives.
Product Type:
Substitution pressure concentrates most intensely on commodity-grade blends where TPU and copolyester alternatives compete on Shore hardness overlap and processing temperature compatibility.
- TPEE Compounds:Pre-formulated polyester-polyether block copolymers with Shore D 35-80 hardness ranges and continuous service temperatures to 150°C. Automotive OEMs in Germany specify these for under-the-hood sealing systems where EPA tailpipe standards demand lighter alternatives to vulcanized rubber.
- TPEE Moldings:Injection-molded components produced at 240-280°C melt temperatures requiring specialized rheology expertise. Medical device manufacturers in Switzerland specify these for autoclavable surgical instrument grips with ISO 10993 biocompatibility documentation.
- TPEE Blends:Alloy formulations combining TPEE with engineering thermoplastics for cost-optimized performance tiers.
- TPEE Films:Extruded sheet and membrane products serving packaging and industrial lamination applications.
TPEE Compounds anchor the volume base while TPEE Moldings gain share at the steepest rate.
End User:
Margin concentration follows application complexity, with medical and electrical specifications commanding formulation premiums over standardized automotive grades.
- Automotive OEMs:Primary demand source for high-specification sealing and interior soft-touch components. Volkswagen Group and Stellantis now compress material qualification timelines to 18 months versus historical 36-month windows.
- Medical Devices:Surgical instrument manufacturers specify autoclavable soft-touch materials through direct compounder agreements. CDSCO's streamlined Class A/B approvals and India's PLI scheme attract producers to the Ahmedabad-Pune corridor.
- Consumer Electronics:Smartphone and wearable device housings requiring fatigue-resistant overmolding solutions.
- Industrial Components:Collaborative robot arm coverings demanding 10^6+ flex cycles without material fatigue.
Automotive OEMs dominate current volume while Medical Devices demonstrate the steepest expansion trajectory.
Application:
Voltage architecture evolution in electric vehicles is redirecting formulation R&D toward dielectric performance optimization.
- Electrical Insulation:Halogen-free flame-retardant grades incorporating phosphorus-nitrogen synergists displace brominated compounds in EV battery modules above 800V architectures. Tier-1 suppliers to Tesla and BYD accelerated adoption since 2023.
- Automotive Parts:Under-the-hood sealing and lightweight interior components where NHTSA fuel economy mandates compel substitution for heavier vulcanized rubber systems.
- Sealing Solutions:Low-permeability formulations favored by EU F-Gas Regulation mandates in commercial HVAC refrigeration systems through 2030 phase-down schedules.
- Soft Touch Grips:Biocompatible, autoclavable surfaces for repeated-use medical instruments facing 134°C steam sterilization ceiling constraints against silicone alternatives.
Automotive Parts retains the largest volume position while Electrical Insulation climbs the fastest on EV platform proliferation.
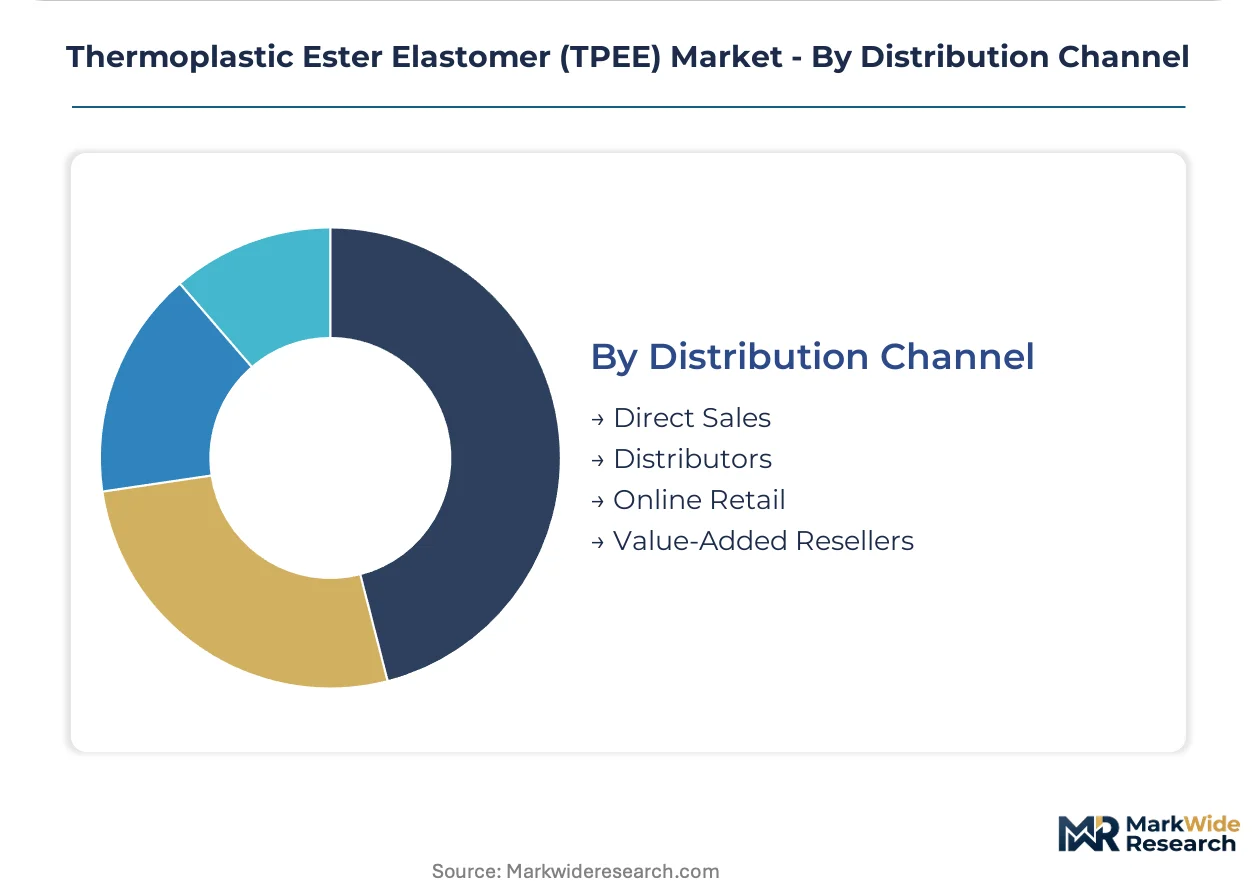
Distribution Channel:
Channel structure reflects technical complexity, with direct relationships displacing intermediaries where formulation customization and lot-level documentation are required.
- Direct Sales:Long-term agreements between compounders and OEMs for qualified automotive and medical specifications. Swiss medical device manufacturers around Solothurn demand simultaneous lot-level biocompatibility documentation and recycled content traceability.
- Distributors:Inventory stocking for standardized molding grades with predictable demand patterns.
- Value-Added Resellers:Technical support and small-batch customization for specialty industrial applications.
- Online Retail:Emerging channel for prototype quantities and research-grade materials.
Direct Sales commands the highest value concentration while Value-Added Resellers expand most quickly in robotics and specialty industrial niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in TPEE track closely to automotive and medical device manufacturing footprints. Germany and the United States remain net importers of specialized compounding grades, while South Korea and China balance domestic consumption with regional supply to Southeast Asian molders.
United States
NHTSA fuel economy mandates and EPA tailpipe standards compel Detroit automakers to substitute TPEE for heavier vulcanized rubber in under-the-hood sealing systems. The Inflation Reduction Act's domestic content incentives accelerate EV platform electrical insulation demand. Michigan and Ohio host dense tier-1 supplier networks serving battery pack architectures above 800V.
Germany
Volkswagen Group and Stellantis compress material qualification timelines to 18 months versus historical 36-month windows, straining compounder testing infrastructure. REACH substance restrictions and the EU F-Gas Regulation redirect formulation R&D toward halogen-free TPEE blends. The Ludwigshafen-Domat/Ems corridor anchors advanced compounding capabilities for high-specification automotive grades.
China
BYD and Tesla Shanghai accelerate adoption of halogen-free flame-retardant grades for battery module insulation since 2023. MIIT dual carbon goals and GB standards for recyclable automotive materials tighten compliance requirements. The Yangtze River Delta concentrates injection molding capacity for standardized automotive supply chains.
Switzerland
Medical device OEMs around Solothurn demand simultaneous lot-level ISO 10993 biocompatibility documentation and recycled content traceability. Swissmedic oversight and MDR alignment create procurement model evolution toward direct compounder agreements. The Basel-Solothurn cluster leads specification pull for autoclavable surgical instrument grips.
India
CDSCO streamlined Class A/B device approvals and PLI scheme incentives attract TPEE grip and tubing producers. Ahmedabad-Pune corridor manufacturers target export markets with cost-optimized molding operations. BIS standards for medical device materials gradually align with ISO 10993 frameworks.
Thermoplastic Ester Elastomer (TPEE) Market Competitive Landscape
Concentration sits with integrated polyol producers controlling polymerization-to-compounding value chains. Three archetypes dominate: petrochemical conglomerates with captive BDO supply, specialized engineering polymer compounders with medical-grade certifications, and Asian scale players serving standardized automotive tiers. Competitive moves center on backward integration into polyol production and reactive extrusion capability expansion for halogen-free formulations.
Within the integrated petrochemical tier, BASF SE and LG Chem exemplify divergent geographic strategies. BASF SE anchors European demand through Ludwigshafen-based polyol supply chains. LG Chem occupies a position in Asian automotive supply chains with standardized molding grades. EMS-CHEMIE HOLDING AG represents the specialized compounder archetype, sitting within the Swiss-German medical device qualification ecosystem.
| Leading Market Players |
|---|
| BASF SE |
| LG Chem |
| DuPont |
| Toray Industries |
| Eastman Chemical Company |
| Lubrizol Corporation |
| EMS-CHEMIE HOLDING AG |
| Asahi Kasei Corporation |
| Arkema |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German automotive OEMs and Ludwigshafen-based compounders lock in polyether polyol supply access while anchoring price visibility against butanediol feedstock swings. These contracts insulate qualified suppliers from spot market volatility while compressing margins for tier-2 molders excluded from direct allocation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across automotive specification grade, medical certification tier, and volume commitment scale. Price differentiation separates ISO 10993-qualified medical grades from standard automotive molding tiers, with the former commanding formulation premiums. Cost compression in commodity-grade blends intensifies as TPU alternatives erode Shore hardness overlap segments. Tier-2 injection molders exhibit highest price sensitivity due to single-source vulnerability for specialized Shore D 35-80 grades, while integrated polyol producers face least sensitivity through captive BDO supply.
Supply Chain Analysis
Strait of Malacca transit underwrites Asian butanediol feedstock flows that feed TPEE polymerization economics across China, South Korea, and Japan. Raw material dependencies center on 1,4-butanediol from acetylene-based production, polyether polyols from propylene oxide routes, and dimethyl terephthalate for polyester block construction. Single-source vulnerability concentrates among three integrated polyol producers controlling automotive qualification pipelines. Distribution runs through direct sales channels for medical and high-specification automotive grades, with distributors handling standardized molding tiers for consumer electronics and industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EV platform voltage upgrades splinter demand into dielectric-specialized niches unreachable by standardized compounders. Medical device procurement disintermediation creates additional white-space for qualified entrants bypassing traditional distribution.
For Market Incumbents: Compound defensive moats by deepening backward integration into BDO production and expanding reactive extrusion capacity for halogen-free formulations. Threat from REACH Annex XVII substance restrictions demands accelerated R&D cycles to maintain qualified supplier status with Volkswagen Group and Stellantis. Certification investment in ISO 10993 medical-grade documentation anchors priority lever against EMS-CHEMIE HOLDING AG concentration. For New Entrants and Emerging Players: Differentiate on collaborative robot arm coverings requiring 10^6+ flex cycle performance, a segment unpenetrated by automotive-specialized incumbents. The Ahmedabad-Pune corridor offers most penetrable geography given CDSCO streamlined approvals and PLI scheme incentives for medical device manufacturing. Direct compounder agreements with Swiss OEMs around Solothurn provide go-to-market angle bypassing distributor intermediaries. For Investors and Strategic Acquirers: The market sits at a specification-intensification phase that favors specialized engineering polymer compounders with medical-grade certifications over commodity scale players. Long-term viability over the next decade hinges on reactive extrusion capabilities and halogen-free formulation portfolios. Acquisition target archetype: mid-cap compounders with ISO 10993 documentation and underutilized capacity in European medical device clusters. Signal to watch: OEM qualification timeline compression beyond 18-month windows forcing consolidation of approved supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into BDO Production | Captive feedstock supply insulates BASF SE and LG Chem from Asian acetylene-based pricing volatility. |
| Halogen-Free Formulation Certification | REACH compliance unlocks Tesla and BYD battery module insulation specifications above 800V architectures. |
| Medical-Grade ISO 10993 Documentation | Lot-level biocompatibility traceability qualifies suppliers for Swiss Solothurn surgical instrument grip contracts. |
| Reactive Extrusion Capacity Expansion | In-house phosphorus-nitrogen synergist compounding displaces legacy brominated flame-retardant supply chains. |
| Direct OEM Agreement Structuring | Long-term offtake contracts with Volkswagen Group compress distributor margins and lock in volume commitments. |
Research Methodology
Desk research of customs trade databases, SEC chemical sector filings, and ECHA REACH restriction notices preceded structured interviews with TPEE compounder technical directors, automotive Tier 1 procurement managers, medical device OEM material scientists, and Swiss distribution channel partners. Bottom-up demand modeling triangulated against top-down polymer consumption estimates from regional chemical industry associations. Primary fieldwork concentrated on Ludwigshafen-Domat/Ems and Basel-Solothurn clusters.
Variance decomposition across product type, end-use industry, Shore hardness tier, and regional regulatory cluster shaped analytical framework development over the projection horizon. CAGRs derived from segment-level volume build-ups incorporating EV platform penetration rates, medical device sterilization cycle requirements, and REACH substance restriction phase-in schedules. Modeled inputs included butanediol price elasticity coefficients and automotive OEM material qualification pipeline data.
The analysis sits within stated boundaries; outcomes outside sustained EV voltage architecture upgrades or ECHA plasticizer ban enforcement timelines would require recalibration. Forecasts reflect assumptions regarding polymer recycling infrastructure investment trajectories and German automotive production stability. Practitioners should keep alternative scenarios live as MIIT dual carbon goal implementation and EPA tailpipe standard stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polyglycerol Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Polyacrylamide Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Global Amino Resin Market